
 RDX and HMX Market | 2026-2036
RDX and HMX Market Size, Share, and Industry Trends Forecast 2026-2036
RDX and HMX Market Analytics
The gap between military-grade purity specifications and industrial demolition grades is repositioning supplier portfolios across the RDX and HMX landscape. Eurenco dominates European defense supply chains through backward integration into nitramine synthesis. Solar Industries India Ltd anchors South Asian demand by leveraging domestic mining and defense contracts. Chemring Group PLC competes in niche ordnance formulations where trace impurity thresholds define contract eligibility.
RDX and HMX are nitramine high explosives synthesized through Bachmann processes and nitrolysis routes, with HMX offering superior detonation velocity and thermal stability for shaped charges and solid rocket propellants. Military end users command the largest value pool due to multi-year procurement frameworks and stringent qualification requirements. Demolition applications represent the fastest-expanding segment as infrastructure decommissioning and controlled blasting operations expand across mining corridors. Granular and pellet forms retain pricing power over powder variants because of safer handling profiles and precise metering in automated loading systems.
EPA regulations in the United States govern wastewater discharge from nitramine manufacturing, while REACH in Europe mandates full chemical safety dossiers for explosive precursors. The Department of Defense maintains Qualified Products Lists that lock out uncertified suppliers for extended qualification cycles. Stakeholders must monitor how emerging energetic material formulations and green chemistry mandates reshape regulatory compliance costs and qualification timelines.
Market Dynamics
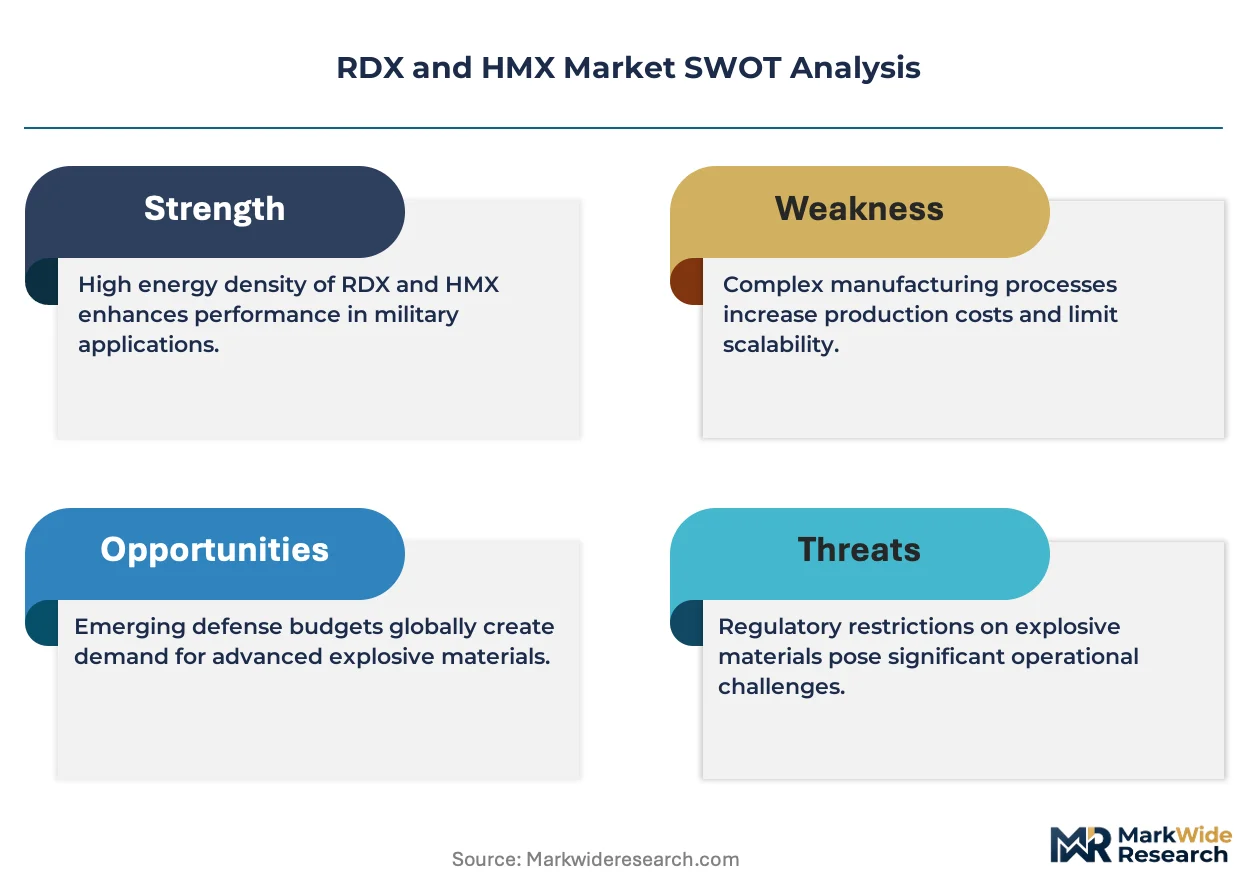
Defense procurement cycles are compressing qualification timelines while REACH and EPA frameworks simultaneously tighten purity thresholds, creating a structural squeeze between speed-to-contract and compliance rigor.
Growth Catalysts
- Ordnance Modernization Programs:Multi-year defense frameworks in the United States are accelerating nitramine consumption for next-generation munitions and warhead upgrades.
- REACH Chemical Safety Mandates:Full dossier requirements for explosive precursors in Europe are filtering out subscale competitors and consolidating contract pools around qualified suppliers.
- Controlled Demolition Expansion:Mining corridor decommissioning and infrastructure removal projects are pulling granular RDX formulations into civilian blasting operations.
Market Restraints
- Hexamine Feedstock Volatility:Petrochemical-derived hexamine pricing swings directly compress nitramine production margins without long-term supply agreements.
- Qualified Supplier Concentration:Defense Qualified Products Lists lock out new entrants for 18-36 month qualification windows, freezing competitive entry.
- Green Chemistry Substitution Pressure:Insensitive munition formulations and CL-20 alternatives threaten HMX demand in next-generation propellant designs.
Strategic Opportunities
- Indian Defense Indigenization:Domestic procurement mandates under the PLI scheme are opening captive demand for locally synthesized nitramines.
- Automated Loading System Integration:Pellet and granular form factors are capturing premium positioning in robotic ammunition handling lines.
- EPA Wastewater Compliance Services:Nitramine manufacturers are monetizing treatment technology licensing to smaller facilities facing discharge rule tightening.
Industry Challenges
- Explosives Chemist Talent Scarcity:Specialized synthesis expertise for Bachmann process optimization is retiring faster than training pipelines replenish.
- Dual-Use Export Control Complexity:ITAR and MTCR classification reviews are extending international contract execution timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RDX and HMX Market |
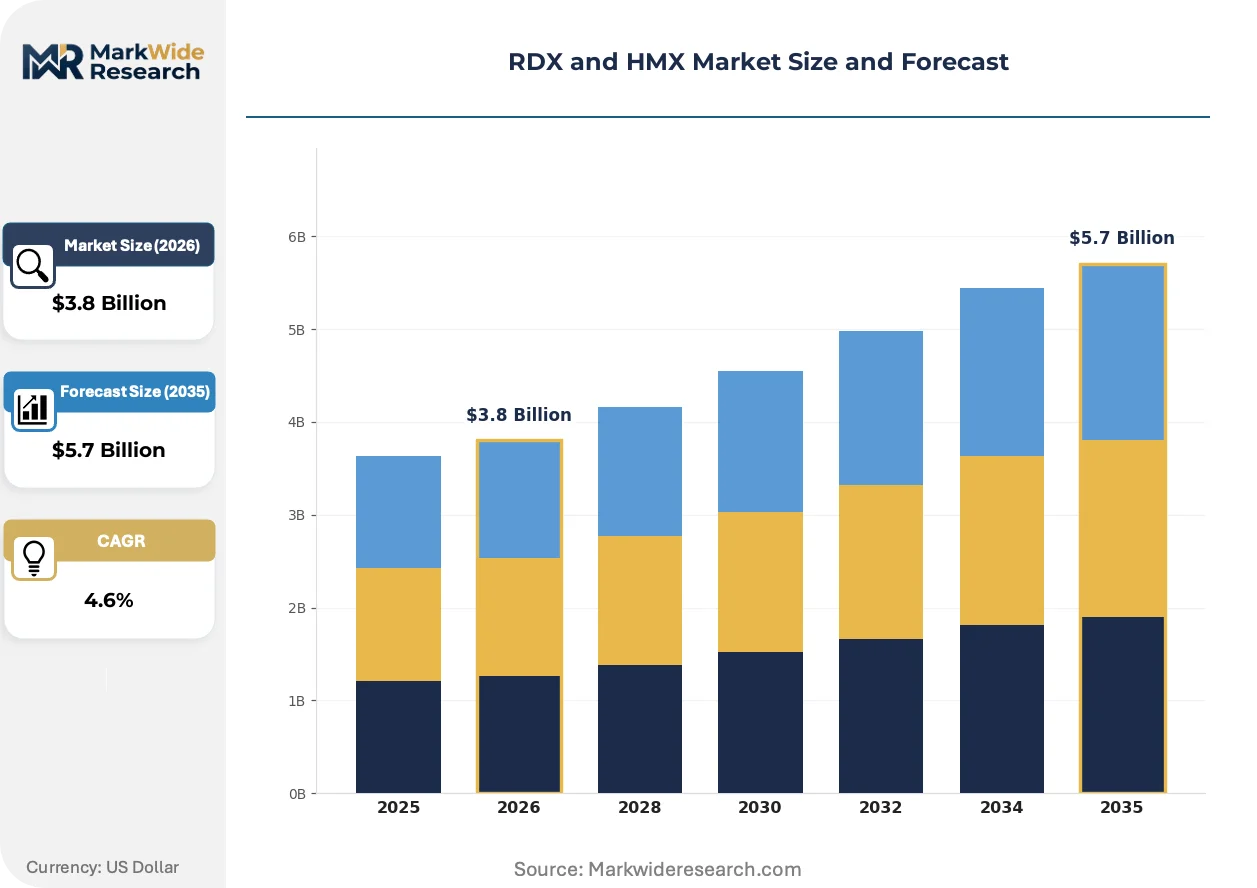
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RDX, HMX, Explosive Blends, Additives End User: Military, Defense Contractors, Mining, Industrial Application: Demolition, Military Operations, Space Exploration, Ordnance Form: Granular, Liquid, Powder, Pellet |
| Companies Covered | Austin Powder, PT. Dahana, BAE Systems, Solar Industries India Ltd, PRVA ISKRA - NAMENSKA A.D, Rheinmetall AG, Eurenco, Nuberg EPC, Chemring Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RDX and HMX Market Evolving Landscape
Continuous processing technology and green chemistry mandates are restructuring how nitramines are synthesized, tested, and qualified for defense and industrial end uses.
Continuous flow reactor technology is consolidating batch-process nitramine manufacturing by slashing solvent waste volumes and compressing reaction times from hours to minutes. Defense contractors in the United States are piloting these systems for HMX production to meet EPA wastewater discharge limits. The shift is consolidating capital deployment around integrated synthesis-purification lines that legacy batch plants cannot retrofit economically.
REACH authorization requirements for substances of very high concern are forcing nitramine manufacturers to submit full chemical safety dossiers or face market withdrawal. ECHA's tightening scrutiny on explosive precursors is raising compliance costs for European suppliers while creating competitive moats for dossier-holders. Formulators serving NATO ordnance programs are absorbing these costs through multi-year framework pricing adjustments.
Defense buyers are unbundling after-sales technical support from bulk explosive supply contracts and sourcing formulation expertise separately. Prime contractors in shaped charge applications are bringing blending and loading capabilities in-house while outsourcing raw nitramine production. This pattern is most visible in United States Army ammunition plants where Qualified Products List maintenance now separates material certification from engineering services.
RDX and HMX Market Segmentation
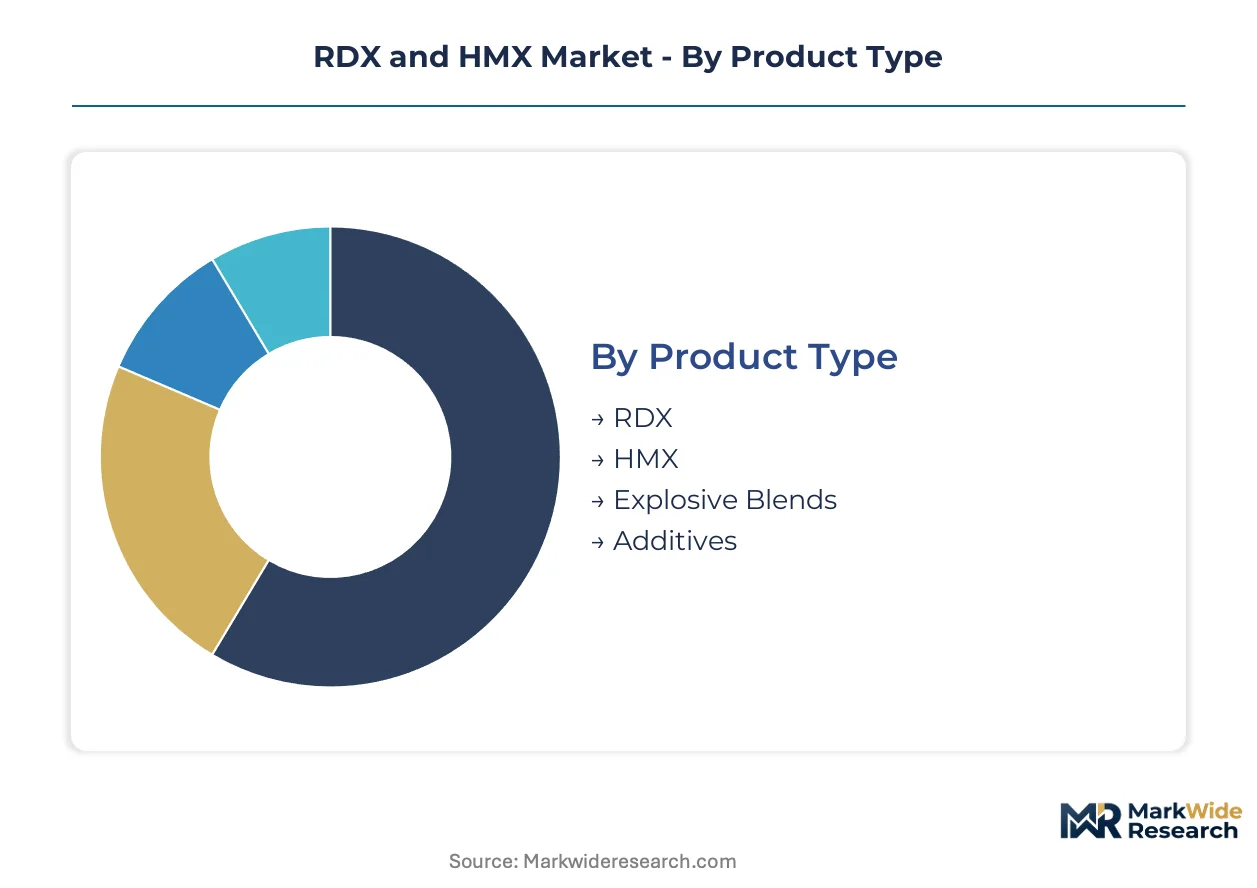
RDX and HMX procurement splits across multiple technical and operational dimensions. Defense buyers prioritize detonation velocity and thermal stability, while industrial users weigh handling safety and metering precision. Understanding these segment boundaries clarifies where suppliers can defend margin and where commoditization pressures concentrate.
Product Type:
Purity specifications and synthesis complexity separate military-grade contracts from industrial supply tiers.
- RDX:Cyclotrimethylenetrinitramine synthesized via Bachmann process dominates volume across shaped charge and booster applications. United States Army ammunition plants absorb the largest qualified supply pools under multi-year framework agreements.
- HMX:Cyclotetramethylenetetranitramine delivers superior detonation velocity and thermal stability for solid rocket propellants and nuclear weapon primaries. Demand concentrates in next-generation munitions programs where insensitive explosive requirements are tightening.
- Explosive Blends:PBX formulations and melt-cast compositions combine nitramines with binders and plasticizers for specific blast profiles.
- Additives:Stabilizers, desensitizers, and burn-rate modifiers adjust handling characteristics and shelf-life performance.
RDX leads volumes today; HMX is gaining share fastest in next-generation propellant designs.
End User:
Procurement authority and qualification rigor define contract eligibility and pricing power across buyer categories.
- Military:National arsenals and defense ministries operate under Qualified Products Lists with 18-36 month certification cycles. Pentagon procurement frameworks lock in multi-year nitramine supply agreements with backward-integrated manufacturers.
- Defense Contractors:Prime ordnance suppliers source raw nitramines separately from blending and loading services. United States Army ammunition plants now unbundle material certification from engineering support contracts.
- Mining:Civilian blasting operations pull granular RDX formulations for controlled demolition in corridor decommissioning projects.
- Industrial:Specialized demolition contractors and aerospace testing facilities purchase smaller volumes with less stringent purity thresholds.
Military buyers anchor contract values; mining is expanding most quickly as infrastructure removal accelerates.
Application:
Detonation environment and safety requirements dictate form factor selection and handling protocols.
- Demolition:Controlled blasting for infrastructure removal and mining decommissioning demands granular formulations with precise metering compatibility. EPA wastewater discharge rules from nitramine manufacturing are tightening compliance costs for suppliers serving this segment.
- Military Operations:Warhead fills, booster charges, and shaped penetrators require military-grade purity with trace impurity thresholds below 0.1 percent. NATO ordnance programs absorb these costs through framework pricing adjustments.
- Space Exploration:Solid rocket propellants for launch vehicle boosters leverage HMX thermal stability.
- Ordnance:Ammunition stockpiling and replenishment cycles drive predictable procurement volumes.
Military operations dominate value capture; demolition climbs the fastest on civilian infrastructure spending.
Form:
Physical state determines automation compatibility, safety profile, and transportation classification.
- Granular:Free-flowing crystalline particles enable precise volumetric metering in automated loading systems. Robotics integration in United States ammunition plants is consolidating demand around this form factor.
- Pellet:Pre-pressed cylindrical charges simplify handling and reduce dust exposure for shaped charge assembly. Premium positioning reflects safer logistics profiles and reduced occupational exposure liability.
- Powder:Fine particulate requires more stringent static electricity controls and respiratory protection.
- Liquid:Melt-cast suspensions and slurries serve specialized formulation and casting processes.
Granular forms command volume leadership; pellet configurations are expanding most quickly in robotic handling lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized explosives chemists and Bachmann process technicians cluster around defense-industrial corridors in the United States, Germany, and India, anchoring regional production capabilities.
United States
Pentagon ordnance modernization programs and Army ammunition plant replenishment cycles drive nitramine consumption. EPA wastewater discharge regulations govern nitramine manufacturing effluent limits. The Tennessee Valley and Midwest defense corridor host backward-integrated suppliers serving Qualified Products List contracts.
Germany
NATO munitions standardization and Bundeswehr stockpile rotation sustain HMX demand for shaped charge applications. REACH authorization requirements for explosive precursors mandate full chemical safety dossiers. The Rhineland-Palatinate and Bavaria chemical clusters concentrate nitramine synthesis and formulation expertise.
India
Domestic defense procurement mandates under the PLI scheme and mining corridor decommissioning projects expand RDX absorption. DGFT export controls and BIS quality standards regulate explosive precursor commerce. Maharashtra and Gujarat host integrated suppliers leveraging captive hexamine feedstock for nitramine production.
United Kingdom
Ministry of Defence munitions replenishment and nuclear weapon primary maintenance sustain precision nitramine demand. REACH alignment post-Brexit maintains chemical safety dossier obligations for explosive precursors. The North West and South West England defense clusters concentrate ordnance formulation and loading capabilities.
South Korea
Korea Aerospace Industries propellant programs and Hanwha Defense munitions exports drive HMX procurement for solid rocket applications. MFDS chemical substance registration and dual-use export controls administered by the Ministry of Trade regulate nitramine commerce. The Daejeon-Sejong corridor hosts research institutes advancing energetic material synthesis.
RDX and HMX Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RDX and HMX landscape. The vendor base splits between backward-integrated chemical conglomerates and specialized ordnance formulators. Three archetypes dominate: defense-prime captive producers, independent nitramine specialists, and diversified explosives houses. Competitive moves concentrate on qualification timeline compression and automated loading system integration.
Within the European defense-prime tier, Eurenco and Rheinmetall AG exemplify backward-integrated suppliers controlling nitramine synthesis through in-house Bachmann process capacity. Among Asia-Pacific diversified explosives houses, Solar Industries India Ltd occupies a position bridging domestic defense mandates and mining sector demand.
| Leading Market Players |
|---|
| Austin Powder |
| PT. Dahana |
| BAE Systems |
| Solar Industries India Ltd |
| PRVA ISKRA - NAMENSKA A.D |
| Rheinmetall AG |
| Eurenco |
| Nuberg EPC |
| Chemring Group PLC |
| Others |
Value Network & Pricing Analysis
Defense procurement unbundling of raw nitramine supply from formulation services is forcing suppliers to reposition pricing around material certification alone. This shift compresses margins on bulk RDX and HMX while elevating premiums for pellet and granular forms compatible with robotic ammunition handling systems.
Pricing Analysis
The bundled-versus-unbundled service split now defines contract economics across military supply tiers. Three-tier pricing structure across military-grade, defense-contractor, and industrial-demolition levels separates trace-impurity certification from technical support services. Price differentiation reflects purity thresholds and qualification status rather than volume scale alone. Pricing pressure stems from hexamine feedstock volatility and REACH compliance cost absorption, with mining contractors exhibiting highest price sensitivity and Pentagon arsenals showing lowest.
Supply Chain Analysis
Hexamine supply rests on petrochemical producers in the United States, Germany, and India, with nitramine synthesis concentrated around defense-industrial corridors in these same markets. Raw material dependencies span hexamine feedstock, acetic anhydride reagents, and specialized Bachmann process catalysts. Single-source vulnerability runs through qualified Bachmann process technicians whose specialized expertise is retiring faster than training pipelines replenish. Distribution runs through defense-qualified products lists and long-term framework agreements rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where defense buyers are consolidating procurement around qualified suppliers capable of meeting tightening REACH and EPA purity mandates for next-generation munitions.
For Market Incumbents: Hedge against green chemistry substitution pressure by deepening captive synthesis capabilities and accelerating continuous flow reactor deployment to meet EPA wastewater discharge limits. Lock in multi-year hexamine supply agreements to insulate margins from petrochemical price swings. Prioritize automated loading system compatibility certifications to capture pellet and granular form premiums. For New Entrants and Emerging Players: Launch via EPA wastewater compliance technology licensing to smaller nitramine facilities facing discharge rule tightening. Target Indian defense indigenization mandates under the PLI scheme where domestic procurement requirements are opening captive demand for locally synthesized nitramines. Lead with continuous processing technology partnerships rather than batch-process capacity builds. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated Bachmann process specialists holding active Qualified Products List positions. Long-term viability favors suppliers controlling hexamine feedstock and synthesis purification in single integrated lines. Watch for REACH authorization timeline acceleration as the inflection signal for European competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | Slashes solvent waste volumes and compresses HMX reaction times to meet EPA discharge limits. |
| REACH Chemical Safety Dossier Submission | Creates competitive moats for ECHA-authorized suppliers serving NATO ordnance programs. |
| Automated Loading System Integration | Captures pellet and granular premiums in United States Army ammunition plant robotics lines. |
| Hexamine Feedstock Backward Integration | Insulates margins from petrochemical volatility through captive supply agreements. |
| EPA Wastewater Treatment Licensing | Monetizes compliance technology to smaller facilities facing discharge rule tightening. |
Research Methodology
Bottom-up defense procurement modeling reconciled against top-down nitramine production tracking forms the analytical core of this study. Primary interviews with Bachmann process technicians, Pentagon procurement officers, explosives chemists, and mining demolition contractors combined with secondary validation from EPA enforcement databases, REACH authorization registers, Department of Defense Qualified Products Lists, and customs trade records. Triangulation across these sources ensures supply-side capacity estimates align with demand-side contract flows.
Input-output matrices map hexamine feedstock availability against Bachmann process capacity utilization across qualified production facilities. Segmentation dimensions span product type, end user procurement authority, application environment, and physical form factor. CAGRs derive from defense modernization program timelines and mining corridor decommissioning project pipelines. Forecast inputs include explosives chemist retirement rates and REACH authorization processing velocities.
Several conditions sit outside the modeled scope, including classified munitions program specifications and ITAR-restricted contract values. Forecasts reflect documented assumptions about qualification timeline stability and regulatory enforcement continuity. Geopolitical disruption to hexamine supply chains and accelerated insensitive munition adoption represent specific risk factors that could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Para Cresol Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Global Chiral Chemicals Market
Chemicals
China Inorganic Iodide Market
Chemicals
Paint Remover Market
Chemicals
Fluorochemicals Market
Chemicals
Trichlorosilane Market
Chemicals
Acetophenone Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Selenium Sulfide Market
Chemicals
Potassium Iodide Market
Chemicals
Trifluoroacetic Acid (TFA) Market