
 Sodium Azide Market | 2026-2036
Sodium Azide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Azide Market Intelligence
A shift from single-source to multi-source procurement is repositioning how pharmaceutical and automotive buyers secure sodium azide supply. Shandong IFT Science & Technology leverages its integrated manufacturing base in Shandong province to dominate industrial-grade output. Zhejiang Hailan Chemical Group anchors the laboratory and reagent-grade segments through specialized purification capabilities. Azide & Allied Chemicals competes on geographic proximity to Indian pharmaceutical clusters, sustaining cost-advantaged distribution.
Sodium azide is an inorganic salt with the formula NaN₃, typically manufactured through the reaction of sodium amide with nitrous oxide or via hydrazine-based processes; it decomposes explosively above 275°C to release nitrogen gas, a property exploited in automotive airbag inflators and pharmaceutical synthesis. Pharmaceutical-grade material commands premium positioning due to stringent purity requirements for active pharmaceutical ingredient production, while industrial-grade output serves high-volume airbag propellant applications with thinner margin pools. Laboratory-grade supply supports academic and research institutions, though this segment matures as institutional budgets tighten across North American and European universities.
China's NMPA and SAMR enforce dual-use precursor licensing for sodium azide under national chemical control frameworks, constraining unlicensed production and elevating compliance costs for smaller manufacturers. The US EPA classifies sodium azide as an acutely toxic hazardous substance under RCRA, shaping waste disposal protocols and transport liability for American chemical handlers. Buyers must monitor evolving pharmaceutical-grade certification standards and precursor-control harmonization between Chinese and Indian regulatory regimes to secure uninterrupted supply access.
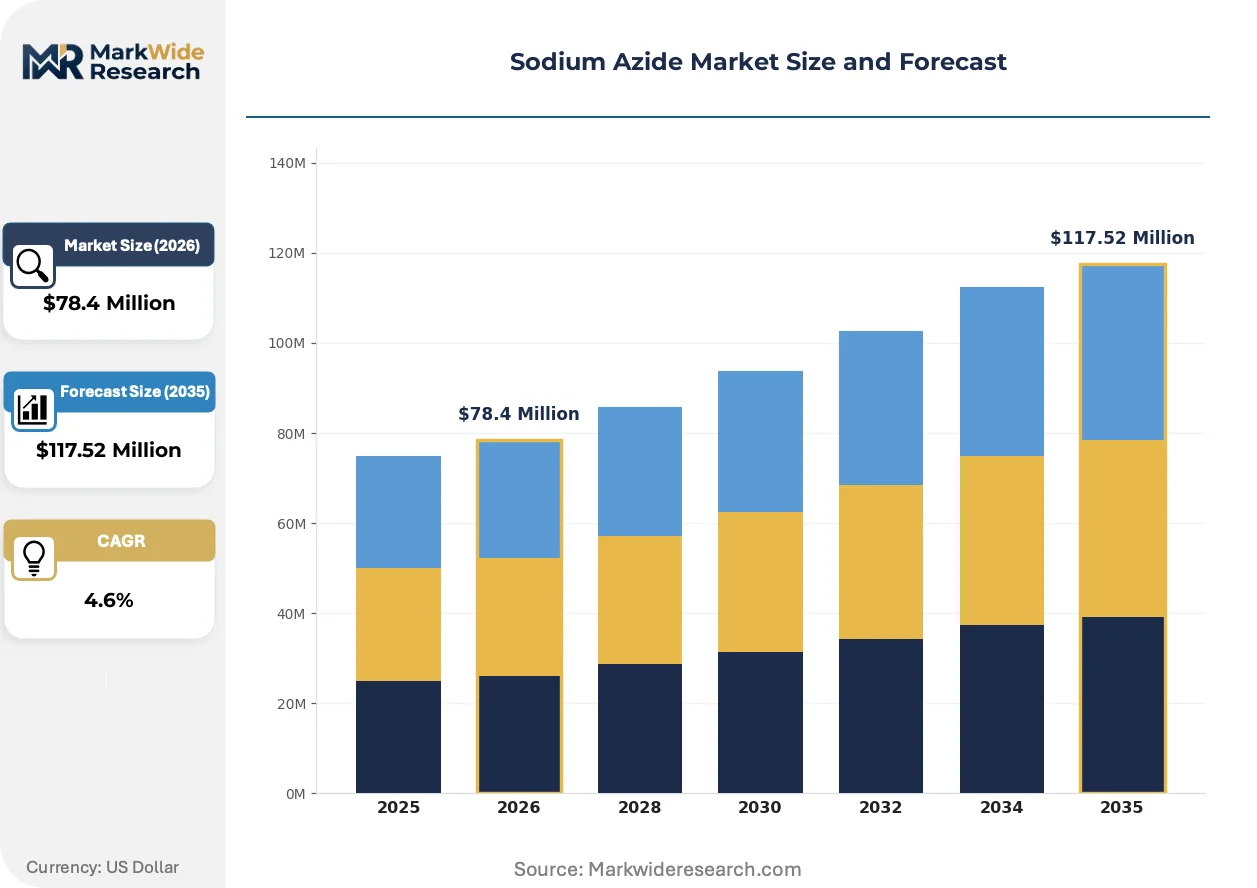
Market Dynamics
Dual-use precursor licensing under China's NMPA and SAMR frameworks is compressing unlicensed production capacity while elevating compliance thresholds for pharmaceutical-grade supply chains.
Growth Catalysts
- Automotive airbag propellant demand:NaN₃ decomposition above 275°C releases nitrogen gas rapidly, a property automakers exploit for occupant protection systems in passenger vehicle safety modules.
- REACH-compliant pharmaceutical synthesis:European antibiotic and antihypertensive manufacturers require certified sodium azide for active pharmaceutical ingredient production under EMA purity standards.
- Shandong-Zhejiang production corridor:East China's concentrated chemical manufacturing infrastructure enables integrated feedstock access and captive hydrazine supply for azide synthesis.
Market Restraints
- Hydrazine feedstock volatility:Hydrazine hydrate prices fluctuate with natural gas derivatives, compressing margins for non-integrated sodium azide producers lacking captive ammonia supply.
- Acute toxicity classification:The US EPA's RCRA hazardous substance designation imposes stringent waste disposal protocols and transport liability premiums on American chemical handlers.
- Non-azide airbag alternatives:Guanidine nitrate and ammonium nitrate-based gas generants are displacing sodium azide in next-generation inflator designs for certain vehicle platforms.
Strategic Opportunities
- Indian pharmaceutical cluster proximity:Azide & Allied Chemicals demonstrates cost-advantaged distribution to Mumbai-Pune and Hyderabad API manufacturing zones under CDSCO import frameworks.
- Laboratory-grade reagent specialization:Zhejiang Hailan Chemical Group's purification capabilities address tightening purity specifications for genomic and proteomic research applications.
- EU Green Deal chemical recycling mandates:Waste sodium azide from decommissioned airbag units creates feedstock recovery opportunities under ECHA circular economy guidelines.
Industry Challenges
- Pharmaceutical-grade certification timelines:NMPA precursor licensing and GMP facility audits extend qualification periods for new API suppliers entering Chinese antibiotic synthesis chains.
- Cross-border harmonization friction:Divergent dual-use chemical controls between China's SAMR and India's DGFT create documentation complexity for multinational pharmaceutical procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Azide Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $117.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Reagent Grade Application: Aerosol Propellants, Pharmaceuticals, Chemical Synthesis, Laboratory Research End User: Chemical Manufacturers, Academic Institutions, Pharmaceutical Companies, Research Laboratories Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Shandong IFT Science & Technology, TCI Chemicals, Zhejiang Hailan Chemical Group, SHINYA CHEM, Fluorochem, Jiangxi Fushine Pharmaceutical, Anhui Ruihua Pharmaceutical Technology, Azide & Allied Chemicals, Fujian Shaowu Ronghui Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Azide Market Strategic Shifts & Innovations
Continuous-flow reactor technology and modular synthesis platforms are redistributing production economics away from centralized batch facilities toward flexible, smaller-scale operations.
Microreactor-based sodium azide synthesis is decentralizing manufacturing footprints by enabling on-site generation at pharmaceutical API facilities. Bayer and Lonza contract manufacturing sites in Switzerland and Germany are piloting skid-mounted units to reduce transport of hazardous intermediates. This technology is decentralizing supply chain risk by eliminating cross-border shipment of bulk azide salts while compressing working capital requirements for just-in-time antibiotic production.
REACH Annex XIV authorization requirements for sodium azide under sunset date provisions are forcing pharmaceutical manufacturers to submit chemical safety reports or seek substitute reagents. ECHA's 2023-2025 evaluation window for azide salts is accelerating substitution research among European generic drug producers. Laboratory reagent distributors in Germany and France are diversifying into guanidine-based click chemistry alternatives to preempt authorization denial scenarios.
Multi-source qualification protocols are replacing single-source contracts among automotive Tier-1 inflator suppliers. Autoliv and ZF Lifetec procurement teams now mandate dual-qualified sodium azide sources for airbag propellant formulations, compressing supplier switching cycles from 18-month to 6-month validation timelines. This pattern is most visible in German and Japanese automotive safety system supply chains where NHTSA recall liability exposure drives redundancy requirements.
Sodium Azide Market Segmentation
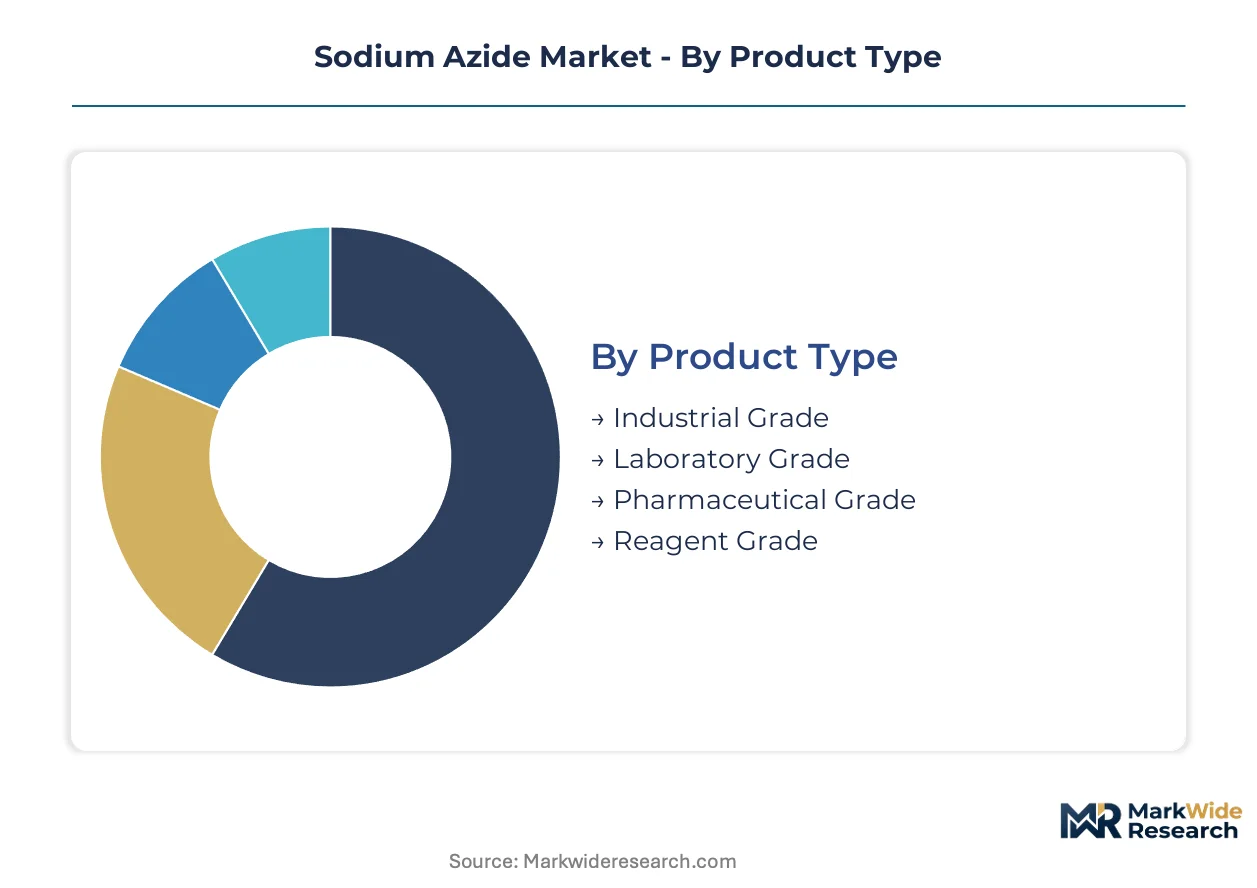
Sodium azide's hazardous material classification fragments procurement patterns across purity tiers and regulatory jurisdictions. Each segment demands distinct certification protocols, transport infrastructure, and customer qualification timelines that reshape competitive positioning.
Product Type:
Capital intensity escalates sharply with purity specifications, as pharmaceutical-grade synthesis requires GMP-certified cleanroom infrastructure and continuous analytical verification systems.
- Industrial Grade:Bulk material serves automotive airbag inflator manufacturing with tolerance for trace metal contaminants. Demand concentrates in Shandong province's integrated chemical corridors where captive hydrazine supply compresses unit economics for high-volume propellant contracts.
- Pharmaceutical Grade:Ultra-pure sodium azide meets EMA and NMPA standards for antibiotic and antihypertensive API synthesis. European generic drug manufacturers under REACH Annex XIV pressure are consolidating procurement through qualified Chinese suppliers with dual-use precursor licensing.
- Laboratory Grade:Moderate-purity material supports academic research protocols requiring consistent batch documentation without pharmaceutical certification overhead.
- Reagent Grade:Specialized formulations for analytical chemistry and quality control laboratories emphasize solubility specifications and minimal particulate contamination.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
Volume concentration diverges between mature automotive safety systems and emerging pharmaceutical synthesis pathways.
- Pharmaceuticals:Sodium azide functions as a nitrogen source in triazole ring formation for antihypertensive APIs and β-lactam antibiotic precursors. CDSCO-registered Indian manufacturers are redirecting procurement toward SAMR-licensed Chinese exporters following NMPA's tightened precursor controls.
- Aerosol Propellants:Controlled thermal decomposition generates nitrogen gas for passenger vehicle occupant protection modules. Autoliv and ZF Lifetec qualification protocols now mandate dual-source sodium azide supply to mitigate NHTSA recall exposure.
- Chemical Synthesis:Azide transfer reagents and click chemistry intermediates drive demand from agrochemical and specialty polymer manufacturers.
- Laboratory Research:Declining institutional budgets across North American and European universities are compressing reagent-grade volume growth despite proteomic and genomic application expansion.
Aerosol propellants dominate current offtake volumes; pharmaceuticals are climbing the fastest.
End User:
Procurement sophistication separates multinational chemical manufacturers from fragmented academic buyers.
- Chemical Manufacturers:Integrated producers with captive hydrazine supply and batch reactor infrastructure control cost structures for industrial-grade output. Shandong and Zhejiang province facilities leverage East China's concentrated feedstock access.
- Pharmaceutical Companies:API producers under EMA and NMPA jurisdiction require certificate-of-analysis documentation and precursor-chain custody records. Multi-source qualification protocols are compressing supplier switching cycles from 18-month to 6-month validation timelines.
- Academic Institutions:Budget-constrained universities prioritize cost over certification depth, exposing them to supply discontinuity risks during regulatory enforcement waves.
- Research Laboratories:Contract research organizations and government institutes demand flexible lot sizes with rapid analytical turnaround for method development work.
Chemical manufacturers command the deepest supplier relationships; pharmaceutical companies are driving the steepest expansion trajectory.
Distribution Channel:
Hazardous material transport liability shapes channel economics more than conventional chemical logistics.
- Direct Sales:Bulk pharmaceutical and industrial contracts bypass intermediaries to secure chain-of-custody documentation for dual-use precursor compliance. Shandong IFT Science & Technology and Zhejiang Hailan Chemical Group maintain dedicated account management for airbag propellant and API manufacturers.
- Distributors:Regional chemical distributors with hazardous materials licensing serve mid-volume laboratory and reagent-grade customers requiring localized inventory positioning.
- Online Sales:E-commerce platforms with restricted substance verification protocols handle small-lot reagent orders from qualified institutional buyers.
- Retail:Minimal presence limited to educational supply channels with stringent purchaser credentialing requirements.
Direct sales capture the majority of value; distributor networks are gaining share fastest in laboratory-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's hydrazine production belt anchors global sodium azide manufacturing, with captive ammonia supply chains feeding concentrated synthesis corridors. Regulatory divergence between Chinese precursor controls and European REACH authorization timelines is fragmenting procurement patterns across pharmaceutical and automotive demand centers.
China
Shandong and Zhejiang provinces host the dominant industrial-grade capacity, with NMPA dual-use licensing compressing unlicensed production. SAMR enforcement of pharmaceutical precursor controls since 2023 has redirected API supply chains toward certified exporters. The Yangtze River Delta chemical corridor integrates captive hydrazine supply with azide synthesis for both domestic airbag manufacturers and export pharmaceutical contracts.
United States
Automotive safety module assembly in Michigan and Ohio sustains industrial-grade import demand despite domestic synthesis decline. EPA RCRA hazardous substance classification elevates transport liability premiums and shapes waste disposal protocols for chemical handlers. Gulf Coast petrochemical infrastructure provides residual hydrazine feedstock access for specialty azide production serving laboratory and research segments.
Germany
EMA pharmaceutical-grade certification requirements and ECHA REACH Annex XIV sunset provisions are compressing European synthesis capacity. Autoliv and ZF Lifetec procurement teams mandate dual-qualified sodium azide sources for airbag propellant formulations. The Rhine-Ruhr chemical cluster maintains residual azide handling infrastructure despite regulatory pressure favoring guanidine nitrate alternatives.
India
Mumbai-Pune and Hyderabad API manufacturing zones drive pharmaceutical-grade import demand under CDSCO registration frameworks. DGFT import licensing for dual-use chemicals creates documentation friction with Chinese SAMR export controls. Azide & Allied Chemicals leverages geographic proximity to sustain cost-advantaged distribution to domestic pharmaceutical clusters.
Japan
METI chemical control ordinances align with international precursor regimes, constraining unlicensed handling of sodium azide for pharmaceutical synthesis. Automotive airbag assembly in Nagoya and Tokyo metropolitan areas sustains industrial-grade procurement from certified Chinese exporters. PMDA pharmaceutical-grade standards limit domestic synthesis to specialized cleanroom facilities serving domestic API manufacturers.
Sodium Azide Market Key Industry Players
Multi-source qualification mandates dominate the current landscape as automotive Tier-1 suppliers compress supplier validation timelines. The vendor base separates into three tiers: integrated chemical conglomerates with captive feedstock, specialized pharmaceutical-grade purifiers, and regional distributors serving laboratory segments. Strategic archetypes include hydrazine-integrated mass producers, purity-specialist API suppliers, and proximity-based distributors to Indian pharmaceutical clusters. Capacity expansion in East China's chemical corridor and backward integration into ammonia supply chains represent the dominant competitive moves.
Among China-based integrated producers, Shandong IFT Science & Technology and Zhejiang Hailan Chemical Group exemplify the hydrazine-captive archetype, occupying positions that leverage East China's concentrated feedstock access. Azide & Allied Chemicals represents the geographic-proximity model, anchoring distribution efficiency to Indian pharmaceutical demand centers. TCI Chemicals sits within the reagent-grade specialist tier, serving laboratory and research institutional buyers with certified small-lot supply.
| Leading Market Players |
|---|
| Shandong IFT Science & Technology |
| TCI Chemicals |
| Zhejiang Hailan Chemical Group |
| SHINYA CHEM |
| Fluorochem |
| Jiangxi Fushine Pharmaceutical |
| Anhui Ruihua Pharmaceutical Technology |
| Azide & Allied Chemicals |
| Fujian Shaowu Ronghui Chemical |
| Others |
Cost & Logistics Intelligence
Skilled chemical process engineers concentrated in East China's Shandong-Zhejiang corridor command wage premiums that compress labor-cost differentials between pharmaceutical-grade and industrial-grade sodium azide production tiers.
Pricing Analysis
After-sales technical support and regulatory compliance documentation are bundled into pharmaceutical-grade contracts while laboratory-grade sales run unbundled. Three-tier pricing structure across pharmaceutical, industrial, and laboratory levels separates EMA-certified API supply from airbag propellant bulk and research reagent lots. Price differentiation centers on NMPA dual-use licensing overhead and captive hydrazine integration, with non-integrated producers absorbing margin compression from feedstock volatility. Automotive Tier-1 inflator manufacturers exhibit lowest price sensitivity due to NHTSA recall liability exposure, while budget-constrained academic institutions drive hardest bargaining.
Supply Chain Analysis
India's DGFT local-content documentation requirements for pharmaceutical precursors are reshaping procurement routing toward CDSCO-registered intermediaries. Manufacturing gravity centers on China, India, and Germany, with hydrazine hydrate, ammonia derivatives, and nitrous oxide feedstock drawing from regional petrochemical corridors. Single-source vulnerability concentrates in Shandong province's integrated chemical belt where SAMR licensing has eliminated unqualified capacity. Distribution runs through direct sales for bulk pharmaceutical and industrial contracts, with regional hazardous-material distributors serving laboratory-grade fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where NMPA precursor licensing compression forces sub-scale producers toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into captive hydrazine supply and accelerated NMPA dual-use licensing to outpace regulatory compliance timelines. Shandong and Zhejiang province capacity expansion addresses Autoliv and ZF Lifetec dual-source mandates while guanidine nitrate substitution threats in automotive applications demand purity-specialist differentiation. For New Entrants and Emerging Players: Microreactor-based continuous-flow synthesis technology offers a technology-first wedge into pharmaceutical API on-site generation contracts. Laboratory-grade reagent specialization for genomic and proteomic research applications presents the most penetrable white-space target, with go-to-market execution through German and French distributors preempting REACH Annex XIV authorization denial scenarios. For Investors and Strategic Acquirers: Re-rating potential sits with hydrazine-integrated mid-cap specialists given ECHA circular economy guidelines for waste azide recovery feedstock. Long-term viability over a multi-year horizon favors producers with SAMR licensing and EMA certification dual-qualification. The signal to watch is CDSCO-registered Indian pharmaceutical manufacturers consolidating procurement toward fewer qualified Chinese exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrazine | Captive ammonia supply from East China petrochemical corridors compresses unit economics for industrial-grade contracts. |
| NMPA Dual-Use Licensing Investment | SAMR precursor compliance separates qualified pharmaceutical-grade exporters from unlicensed capacity elimination. |
| Microreactor Pilot Deployment | Bayer and Lonza contract manufacturing sites in Switzerland and Germany reduce hazardous intermediate transport liability. |
| REACH Annex XIV Substitution R&D | ECHA sunset provisions for azide salts accelerate guanidine-based click chemistry alternative development among European generics. |
| Waste Azide Recovery Infrastructure | EU Green Deal chemical recycling mandates create circular economy feedstock opportunities from decommissioned airbag units. |
Research Approach
Trade flow databases, ECHA regulatory filings, and CDSCO import registration records formed the secondary backbone for supply chain mapping and regulatory timeline tracking. Primary interviews with plant managers at Shandong and Zhejiang chemical facilities, procurement leads at Autoliv and ZF Lifetec, pharmaceutical API manufacturing directors, and hazardous-material distribution channel partners validated capacity estimates and qualification timelines. Bottom-up and top-down triangulation reconciled production volume estimates with end-use demand segmentation across automotive, pharmaceutical, and laboratory applications.
Bottom-up modeling anchored volume projections in named production facility capacities and end-use offtake patterns, while top-down verification cross-checked against regional chemical output trends and import-export customs data across the analysis window. Segmentation dimensions included purity grade tier, end-use industry concentration, and regional regulatory cluster alignment. CAGRs derived from slope-log analysis of normalized production indices and pharmaceutical API demand curves, with hydrazine feedstock price volatility and REACH authorization timeline uncertainty incorporated as scenario inputs.
Several conditions sit outside the modeled scope, including unannounced SAMR enforcement actions, abrupt ECHA authorization denial outcomes, and automotive OEM platform decisions to accelerate non-azide inflator adoption. Forecasts reflect documented assumptions regarding NMPA licensing continuity and CDSCO import framework stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
p-Coumaric Acid Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Triethylaluminum Market
Chemicals
Zinc Chemicals Market
Chemicals
Maleic Acid Market
Chemicals
Calcium Hydride Market
Chemicals
South America Construction Chemicals Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Ethanolamine Market
Chemicals
Aerosol Insecticides Market
Chemicals
Ferric Phosphate Market
Chemicals
Methylamines Market
Chemicals
Global Amines Market
Chemicals
Phenothiazine Market