
 Cultured Non-Fat Dairy Ingredients Market | 2026-2036
Cultured Non-Fat Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Non-Fat Dairy Ingredients Market Outlook
Plant-based stabilizers and fermented protein isolates is recalibrating cost structures for traditional cultured dairy formulations. Arla Foods Ingredients Group leverages its Scandinavian dairy cooperative network to sustain bulk supply contracts with European food manufacturers. Chr. Hansen Holding anchors its position through specialized starter culture portfolios that reduce fermentation variability for non-fat yogurt base production.
Cultured non-fat dairy ingredients comprise fermented milk solids with less than 0.5% milkfat content, produced through controlled lactic acid fermentation of skim milk followed by drying or concentration to achieve specified protein and acidity profiles. These ingredients deliver emulsification, flavor development, and moisture retention in processed foods without contributing fat content. Yogurt-derived cultured bases command the largest volume share within product type segmentation due to established supply chains and versatile functionality across applications. Bakery products represent the fastest-growing application segment as manufacturers replace full-fat dairy powders to achieve cleaner nutritional labels. Food manufacturers dominate end-user demand, though private labels are capturing margin pools through direct sourcing from regional dairy cooperatives.
The FDA enforces standards of identity for fermented dairy products under 21 CFR 131, directly influencing permissible labeling claims for non-fat cultured ingredients in US interstate commerce. EFSA evaluates novel fermentation processes and microbial strain safety through qualified presumption of safety protocols, shaping which starter cultures gain market access across European member states. China's SAMR implements GB standards for fermented milk powders that govern import specifications and domestic production licensing. Stakeholders must monitor evolving strain approval pathways and fat-content threshold definitions as regulators tighten alignment between product nomenclature and compositional reality.
Market Dynamics
Fermented protein isolates and plant-based stabilizers are compressing margins for traditional cultured dairy formulations, forcing processors to reconfigure fermentation protocols and renegotiate long-term supply contracts with food manufacturers.
Growth Catalysts
- Clean-label mandates:FDA standards of identity under 21 CFR 131 are compelling reformulation toward fermented skim milk concentrates in US interstate commerce. Food manufacturers accelerate procurement of non-fat cultured bases to satisfy nutritional panel requirements.
- Bakery sector demand:Processed food producers replace full-fat dairy powders with yogurt-derived cultured ingredients to achieve cleaner nutritional labels in bread and pastry applications.
- Starter culture standardization:Specialized microbial strain portfolios reduce fermentation variability, enabling consistent non-fat yogurt base production at industrial scale.
Market Restraints
- Input cost volatility:Skim milk powder prices fluctuate with global dairy commodity cycles, squeezing processor margins on fermented concentrate production.
- Supply concentration risk:Scandinavian dairy cooperative networks dominate bulk supply contracts for European food manufacturers, creating dependency on limited geographic sourcing.
- Technical limitation:Controlled lactic acid fermentation requires precise temperature and pH management that smaller facilities struggle to maintain consistently.
Strategic Opportunities
- Underpenetrated geography:China's SAMR GB standards for fermented milk powders create import specification clarity that foreign suppliers can exploit as domestic production licensing expands.
- Emerging application:Sauce and dressing manufacturers represent untapped volume potential for cultured non-fat dairy bases seeking emulsification without fat contribution.
- Technology convergence:Precision fermentation combined with membrane filtration enables protein concentration at lower energy intensity than traditional evaporation methods.
Industry Challenges
- Strain approval timelines:EFSA qualified presumption of safety protocols delay market access for novel starter cultures across European member states.
- Certification complexity:Divergent fat-content threshold definitions between FDA, EFSA, and SAMR force processors to maintain multiple product specifications for cross-border trade.
- Skill gap:Industrial microbiologists capable of managing controlled fermentation at commercial scale remain scarce in emerging dairy processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Non-Fat Dairy Ingredients Market |
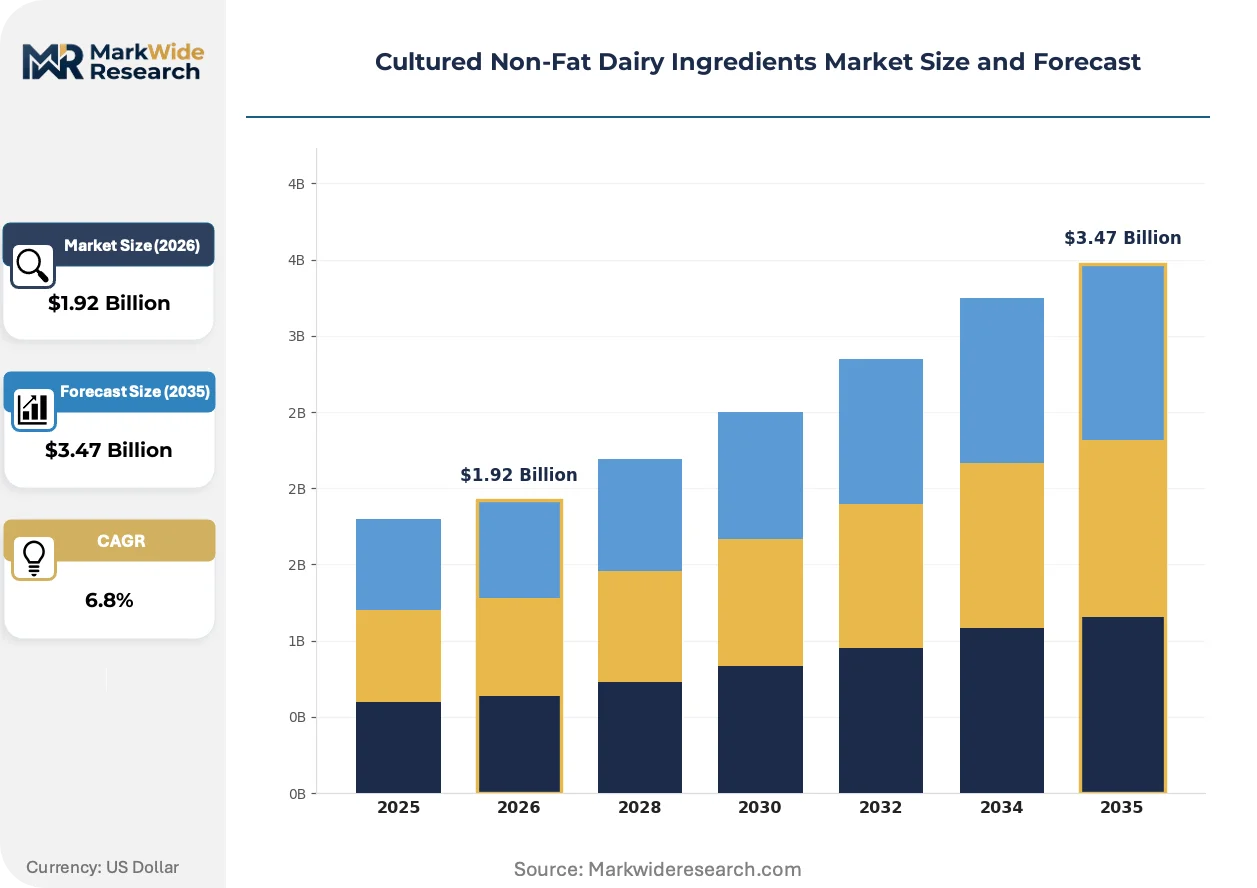
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Skim Milk Powder, Cream Cheese, Sour Cream Application: Bakery Products, Ice Cream, Dressings, Sauces End User: Food Manufacturers, Retailers, Food Service, Private Labels Packing Type: Tubs, Pouches, Bottles, Cartons |
| Companies Covered | Koninklijke DSM, Arla Foods Ingredients Group, Cargill Incorporated, Chr. Hansen Holding, Archer Daniels Midland Company, Ingredion Incorporated, Novozymes, The Tatua Cooperative Dairy Company, CSK Food Enrichment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Non-Fat Dairy Ingredients Market Strategic Shifts
Bioprocessing advances and regulatory recalibration are restructuring how cultured non-fat dairy ingredients achieve functional parity with conventional alternatives while satisfying tightening compositional disclosure requirements.
Precision fermentation using engineered microbial strains is overtaking traditional starter culture methods for protein concentration. Specialty ingredient houses adopt these platforms to reduce batch-to-batch acidity variation. The technology is overtaking capital-intensive evaporative drying in new facility designs, compressing equipment payback periods.
EFSA's evolving qualified presumption of safety protocols are reshaping which microbial strains gain European market access. Strain developers must now submit comprehensive toxicological dossiers before commercial deployment. Non-fat yogurt base producers with established culture libraries hold defensive advantages against new entrants facing extended approval timelines.
Direct sourcing from regional dairy cooperatives is fragmenting traditional distributor relationships. Private label food manufacturers build captive supply chains to capture margin pools previously absorbed by intermediaries. Germany and the United States exhibit the most pronounced channel disintermediation as buyer concentration enables volume-based negotiation leverage.
Cultured Non-Fat Dairy Ingredients Market Segmentation
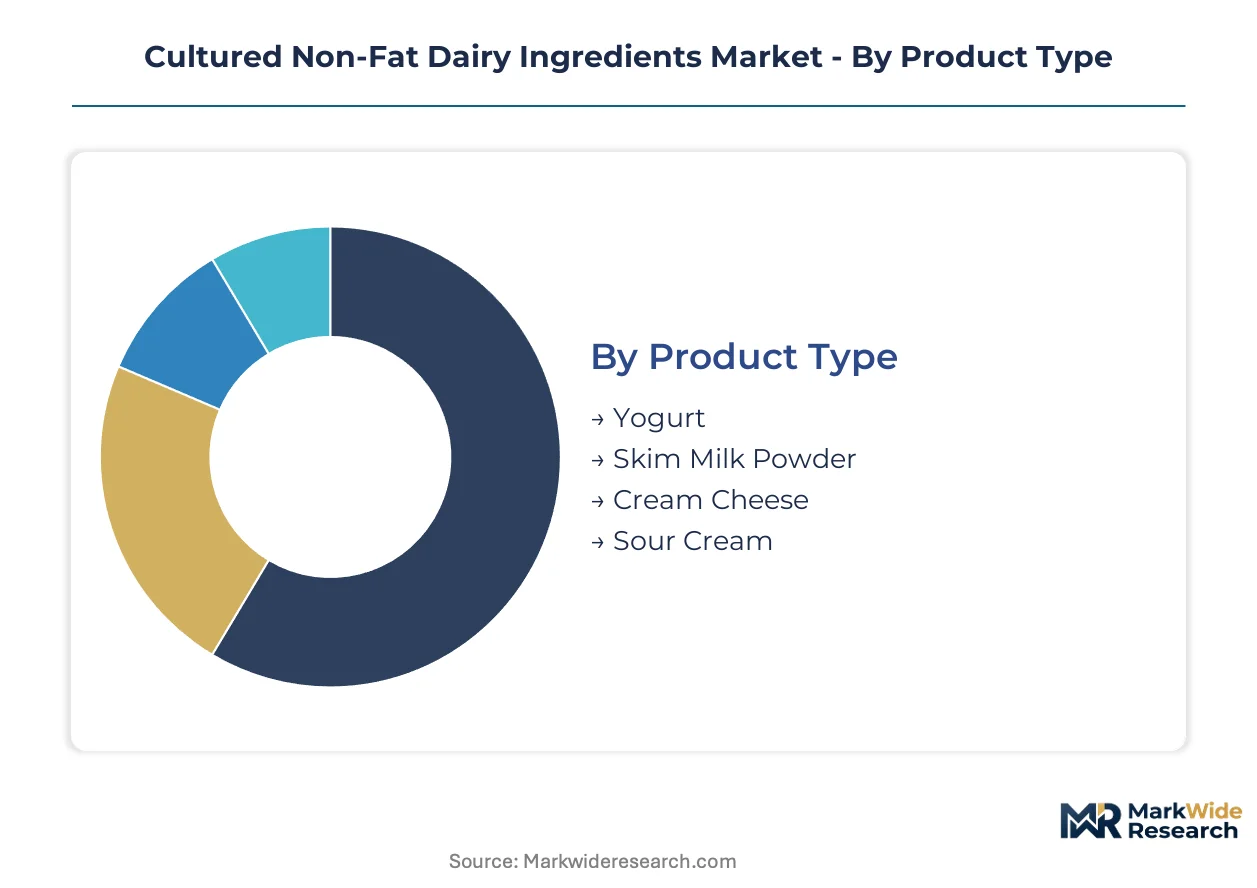
Segmentation in the cultured non-fat dairy ingredients market reveals how functional requirements, supply chain configurations, and regulatory exposure shape procurement decisions across buyer categories. Distinct specification standards and volume thresholds separate industrial purchasers from retail-facing channels.
Product Type:
Buyers differentiate primarily by protein concentration thresholds and fermentation acidity profiles that determine reformulation economics in target applications.
- Yogurt:Fermented skim milk bases with standardized lactic acid content between 0.8-1.2% provide emulsification stability in bakery and sauce applications. Food manufacturers in the United States and Germany concentrate procurement here due to established supplier qualification programs and FDA 21 CFR 131 compliance documentation.
- Skim Milk Powder:Dried fermented solids with protein content exceeding 34% enable clean-label protein fortification without fat contribution. Chinese food manufacturers under SAMR GB standards drive import demand as domestic fermentation capacity remains limited.
- Cream Cheese:Cultured non-fat curds deliver spreadable texture in reduced-fat bakery fillings.
- Sour Cream:Acidified skim concentrates provide tang profiles in dressing applications.
Yogurt leads volumes today; skim milk powder is gaining share fastest.
Application:
End-use specifications diverge sharply on moisture retention requirements and thermal stability under processing conditions.
- Bakery Products:Bread and pastry manufacturers require fermented dairy bases that maintain protein functionality through shear mixing and oven temperatures exceeding 180°C. Clean-label reformulation in Germany and US commercial bakeries accelerates substitution of full-fat powders.
- Dressings:Emulsion stability without fat contribution attracts mayonnaise and vinaigrette producers seeking nutritional panel optimization. Food service distributors in China specify SAMR-compliant import grades for centralized kitchen supply.
- Ice Cream:Fermented protein isolates improve overrun in reduced-fat frozen dessert formulations.
- Sauces:Acid stability during retort processing determines suitability for shelf-stable applications.
Bakery products dominate current procurement volumes; dressings are expanding most quickly.
End User:
Contract structures and technical service requirements separate commodity buyers from those needing fermentation protocol customization.
- Food Manufacturers:Industrial processors negotiate annual volume contracts with specified starter culture documentation and batch-to-batch acidity tolerances. Major bakery and sauce producers in the United States, Germany, and China qualify suppliers through multi-year technical audits.
- Private Labels:Retailer-controlled brands source directly from regional dairy cooperatives to capture margin pools previously absorbed by ingredient distributors. German discount retailers and US club stores lead this disintermediation.
- Food Service:Distributors prioritize shelf-stable formats and simplified reconstitution protocols.
- Retailers:Branded CPG companies specify consumer-facing packaging with extended refrigerated shelf life claims.
Food manufacturers lead volumes today; private labels are climbing the fastest.
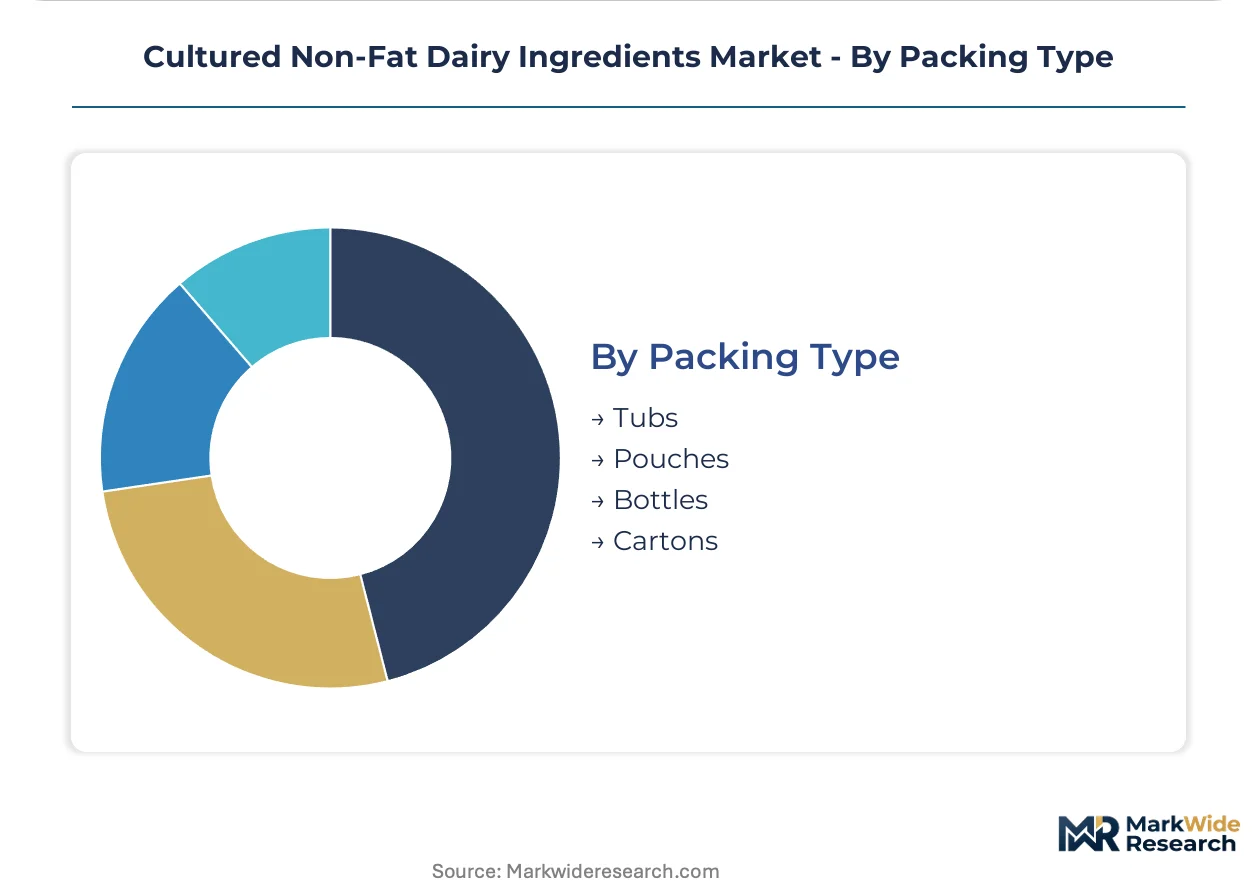
Packing Type:
Logistics economics and contamination risk tolerance drive format selection across customer types.
- Tubs:Rigid containers suit high-volume food manufacturing with dedicated ingredient handling systems and rapid inventory turnover. German dairy cooperatives supply European bakery processors through reusable tub programs.
- Pouches:Flexible packaging reduces freight cost per unit protein for intercontinental shipment to Chinese importers. SAMR registration requirements favor pre-qualified pouch suppliers with established import documentation.
- Bottles:Pourable formats target food service reconstitution applications.
- Cartons:Rectangular geometry optimizes pallet density for retail ingredient distribution.
Tubs lead volumes today; pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian dairy cooperative networks anchor supply capacity for cultured non-fat dairy ingredients, with fermentation clusters concentrated in Denmark and Sweden serving European food manufacturers. Regulatory divergence across FDA, EFSA, and SAMR jurisdictions shapes import specifications and domestic production licensing requirements.
United States
Commercial bakeries and sauce manufacturers drive procurement volumes for fermented skim milk concentrates. FDA standards of identity under 21 CFR 131 govern permissible labeling claims for interstate commerce. Midwest dairy processing clusters in Wisconsin and Minnesota supply bulk yogurt-derived bases to national food manufacturers.
Germany
Discount retailers and private label food manufacturers accelerate direct sourcing from regional dairy cooperatives. EFSA qualified presumption of safety protocols strain approval timelines for novel starter cultures. Bavarian fermentation facilities supply clean-label bakery ingredients across Central European manufacturing hubs.
China
Food manufacturers under SAMR GB standards import fermented milk powders as domestic fermentation capacity remains constrained. Stricter import specifications for protein concentration and microbial safety reshape supplier qualification programs. Yangtze River Delta processing clusters concentrate demand for sauce and dressing applications.
Denmark
Specialized starter culture portfolios from biotechnology firms reduce fermentation variability for industrial-scale production. EFSA microbial strain safety evaluations influence which cultures gain European market access. Copenhagen-area dairy cooperatives maintain bulk supply contracts with multinational food manufacturers.
Australia
Tatua Cooperative Dairy Company anchors regional supply for Asia-Pacific food service distributors. TGA alignment with Codex standards streamlines export certification for fermented dairy ingredients. Victorian dairy processing clusters serve Southeast Asian import demand through established cold-chain logistics.
Cultured Non-Fat Dairy Ingredients Market Competitive Environment
Global majors compete with regional champions across starter culture technology and dairy cooperative supply networks. Market structure tilts toward consolidation at the culture technology tier while remaining fragmented among regional dairy processors. Three archetypes dominate: Scandinavian cooperative networks, multinational enzyme and culture specialists, and Asia-Pacific dairy federations. Capacity expansion in precision fermentation platforms and backward integration into captive milk supply represent the dominant competitive moves reshaping procurement relationships.
Within the cooperative network archetype, Arla Foods Ingredients Group and The Tatua Cooperative Dairy Company exemplify geographic supply concentration strategies that secure bulk contracts with European and Asia-Pacific food manufacturers respectively. Chr. Hansen Holding occupies a position among culture technology specialists, anchoring the starter culture tier through microbial strain portfolios that reduce fermentation variability. Koninklijke DSM and Novozymes sit within the enzyme and biotechnology tier, representing the convergence of precision fermentation platforms with traditional dairy processing.
| Leading Market Players |
|---|
| Koninklijke DSM |
| Arla Foods Ingredients Group |
| Cargill Incorporated |
| Chr. Hansen Holding |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Novozymes |
| The Tatua Cooperative Dairy Company |
| CSK Food Enrichment |
| Others |
Value Chain & Pricing Dynamics
Clean-label procurement mandates from US and German food manufacturers are compressing supplier margins as reformulation toward fermented skim milk concentrates demands tighter batch-to-batch acidity tolerances and extended starter culture documentation. Scandinavian dairy cooperatives and precision fermentation specialists must absorb these specification costs or cede volume to plant-based stabilizer alternatives.
Pricing Analysis
Skim milk powder commodity cycles pass through directly to fermented concentrate pricing, with contract-based long-term offtake agreements dominating procurement between major food manufacturers and Danish or Swedish suppliers. Price differentiation rests on starter culture certification tier—EFSA-qualified presumption of safety strains command premium positioning against generic alternatives—and volume scale, with annual tonnage commitments securing 15-20 point spreads. Cost compression in standard-grade yogurt bases is intensifying because precision fermentation platforms reduce energy intensity versus evaporative drying. Private label retailers exhibit highest price sensitivity through direct cooperative sourcing, while multinational food manufacturers prioritize acidity consistency over unit cost.
Supply Chain Analysis
Industrial microbiologist shortages in Wisconsin, Minnesota, and Bavarian processing clusters constrain fermentation capacity expansion despite equipment availability. Geographic supply concentrates in Denmark, Sweden, and Germany, with Yangtze River Delta import demand drawing from Australian and Scandinavian exporters. Raw material dependencies span skim milk powder, specialized starter cultures, and membrane filtration equipment. Single-source vulnerability runs through Chr. Hansen Holding's strain libraries for EFSA-compliant cultures. Distribution runs through regional dairy cooperative networks for European food manufacturers, while Chinese importers rely on pre-qualified pouch suppliers with established SAMR documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Bakery sector reformulation toward clean-label fermented bases is elevating specification premiums for EFSA-qualified and FDA-documented suppliers.
For Market Incumbents: Lock in multi-year starter culture supply agreements with Scandinavian cooperatives before strain approval timelines extend under evolving EFSA protocols. Deepen backward integration into captive skim milk supply in Wisconsin or Bavaria to insulate margin from commodity volatility. Precision fermentation platform investment represents the critical defensive lever against plant-based stabilizer displacement. For New Entrants and Emerging Players: Begin with sauce and dressing applications in China's Yangtze River Delta, where SAMR GB standard clarity enables import qualification without domestic fermentation capacity competition. Private label direct sourcing relationships in German discount retail offer the most penetrable channel. A go-to-market angle anchored in membrane filtration energy efficiency distinguishes against evaporative drying incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation platform specialists possessing engineered microbial strain libraries and existing EFSA safety dossiers. Five-to-ten year viability favors technology-convergent players over traditional evaporative processors. The signal to watch is EFSA approval velocity for novel starter cultures—acceleration indicates defensive moat erosion for established culture houses.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Deployment | Reduces batch-to-batch acidity variation for industrial-scale yogurt base production. |
| EFSA Qualified Presumption of Safety Dossier Submission | Accelerates European market access for novel starter culture portfolios. |
| Direct Sourcing Partnership with Regional Dairy Cooperatives | Captures margin pools previously absorbed by ingredient distributors. |
| Membrane Filtration Capacity Expansion | Lowers energy intensity versus evaporative drying in protein concentration. |
| SAMR GB Standard Pre-qualification Program | Streamlines import documentation for Chinese food manufacturer procurement. |
Study Parameters
Bottom-up bakery and sauce application modeling reconciled against top-down dairy cooperative supply tracking forms the analytical core of this study. Primary interviews with fermentation facility managers, food manufacturer procurement directors, regulatory affairs specialists at culture technology houses, and private label supply chain executives were validated against secondary sources including FDA 21 CFR 131 standards documentation, EFSA qualified presumption of safety protocols, SAMR GB standards filings, and Scandinavian dairy cooperative annual disclosures. Triangulation across these sources ensures specification accuracy for protein concentration thresholds and acidity profile requirements.
Input-output matrix framing connects skim milk powder commodity inputs to fermented concentrate pricing outputs across product type, application, and end-user segmentation dimensions. Modeled variables include yogurt versus skim milk powder protein concentration tiers, bakery versus dressing thermal stability requirements, and food manufacturer versus private label contract structures. CAGRs were derived through regression against historical dairy commodity cycles and projected clean-label reformulation penetration. Industry-specific forecast inputs encompass EFSA strain approval velocity and SAMR domestic licensing expansion rates.
Several conditions sit outside the modeled scope, including abrupt shifts in FDA standards of identity for fermented dairy nomenclature, trade restriction imposition between EU and China dairy sectors, and breakthrough precision fermentation cost parity events. Forecasts reflect documented assumptions regarding regulatory pathway stability and commodity input continuity. Material deviation in EFSA approval timelines or skim milk powder price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
US Plant-Based Oils Market
Ingredients
Chickpea Flour Market
Ingredients
Sunflower Lecithin Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Pepsin Market
Ingredients
Edible Fiber Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Chlorella Ingredients Market
Ingredients
Microbial Food Ingredients Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Botanical Extracts Market
Ingredients
Cooking Coconut Milk Market
Ingredients
China Cane Sugar Market