
 Botanical Extracts Market | 2026-2036
Botanical Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Extracts Market Analysis
Asset-light toll manufacturing and third-party extraction contracts is rewriting competitive entry barriers in botanical supply chains. Symrise AG leverages captive cultivation partnerships across multiple temperate zones to secure raw material consistency. ADM anchors its position through backward integration into seed selection and agricultural advisory services for medicinal herb growers. Kerry Group differentiates via extraction-to-application service bundles that link standardized actives directly to finished flavor systems.
Botanical extracts are concentrated preparations derived from plant tissues through solvent extraction, steam distillation, or mechanical pressing, typically standardized to marker compound percentages for batch-to-batch uniformity. Their primary commercial purpose centers on delivering bioactive functionality—antioxidant, antimicrobial, or organoleptic properties—into downstream formulations where synthetic alternatives face consumer rejection. Essential oils command premium positioning in cosmetics and personal care due to fragrance complexity and clean-label appeal, while herbal powders dominate pharmaceutical tableting operations where excipient compatibility and flow properties determine manufacturing yields. Nutraceutical applications represent the fastest-growing demand pool, driven by condition-specific supplement formats that require documented phytochemical profiles.
FDA dietary supplement cGMPs and EMA herbal medicine guidelines jointly determine extract quality benchmarks, with EFSA novel food assessments creating additional entry barriers for innovative botanical sources in European food applications. REACH registration requirements for solvent residues and contaminant limits shape extraction technology choices, particularly pressuring hexane-dependent processors toward supercritical CO2 or ethanol-based methods. Stakeholders must monitor evolving pharmacovigilance obligations under the EU Traditional Herbal Medicinal Products Directive, as post-market safety signals can trigger rapid reformulation requirements across entire extract portfolios.
Market Dynamics
Standardization requirements under EMA herbal monographs and FDA cGMPs are compressing supplier margins while rewarding processors with validated analytical capabilities and captive cultivation networks.
Growth Catalysts
- REACH solvent residue thresholds:Supercritical CO2 extraction adoption accelerates as processors eliminate hexane-dependent methods to meet European chemical safety mandates.
- Nutraceutical condition-specific formats:Documented phytochemical profiles for targeted supplements pull standardized extracts into cardiovascular and cognitive health applications.
- India BIS-certified Ayurvedic supply:Domestic manufacturers and export markets draw from Bureau of Indian Standards-verified extraction capacity concentrated in Maharashtra and Karnataka.
Market Restraints
- Raw material cost volatility:Climate-sensitive medicinal herb harvests in temperate cultivation zones expose processors to yield-driven price swings for ginkgo and St. John's wort.
- Supply concentration risk:Captive cultivation partnerships controlled by integrated multinationals limit independent processors' access to genetically consistent seed stock.
- EFSA novel food assessment timelines:European Food Safety Authority safety evaluations for innovative botanical sources extend commercialization cycles by 18-24 months.
Strategic Opportunities
- German pharmaceutical formulator demand:EMA-compliant standardized extracts for prescription herbal medicines create premium positioning for validated suppliers.
- Extraction-to-application service bundling:Integrated flavor and active ingredient delivery systems link botanical actives directly to finished product specifications.
- Supercritical CO2 and ethanol convergence:Dual-technology processors capture both lipophilic and polar compound extraction contracts from clean-label cosmetic formulators.
Industry Challenges
- Phytochemical analytical talent scarcity:Validated HPLC and GC-MS method development expertise concentrates in contract laboratories, constraining in-house standardization capabilities.
- EU Traditional Herbal Medicinal Products Directive compliance:Post-market pharmacovigilance obligations require rapid reformulation response infrastructure across entire extract portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Extracts Market |
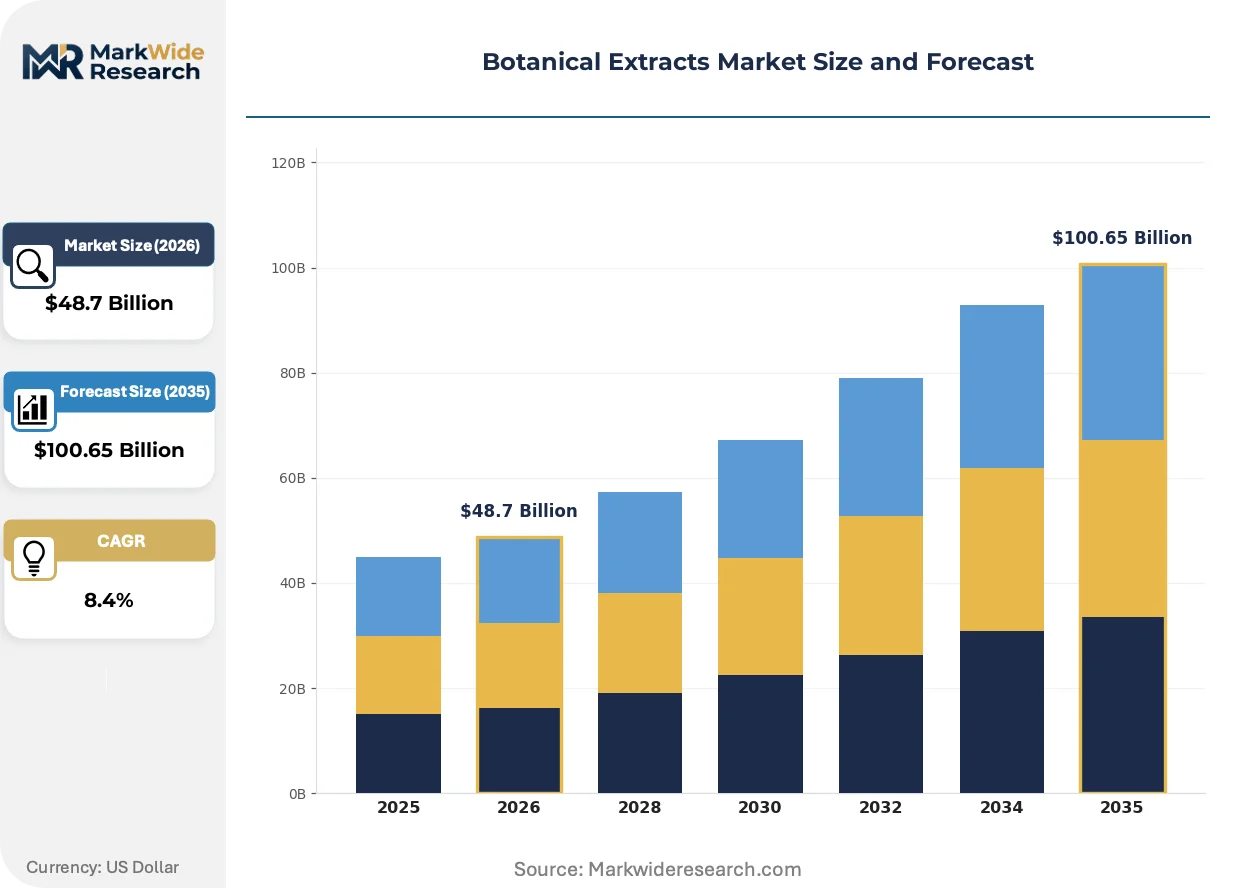
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Powders, Tinctures, Resins Application: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Researchers Form: Liquid, Powder, Solid, Paste |
| Companies Covered | Symrise AG, ADM, Givaudan, Kerry Group, Indesso, International Flavors & Fragrances Inc., Synthite Industries Ltd, Döhler, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Extracts Market Emerging Trajectories
Extraction technology and regulatory verification systems are converging to compress batch-to-batch variability while expanding addressable applications beyond traditional pharmaceutical and flavor segments.
Supercritical CO2 extraction systems with integrated in-line spectroscopic monitoring are digitizing quality assurance workflows for high-value essential oil production. Cosmetic formulators in France and Switzerland adopt these platforms to document terpene profiles for clean-label fragrance claims. Real-time compositional feedback loops compress release-to-market timelines from weeks to days.
EMA's revised herbal medicine guidelines now mandate quantitative marker compound specifications for all new monograph applications. German and Austrian processors invest in reference standard libraries to preempt compliance gaps. Small-batch Ayurvedic exporters face exclusion from European pharmaceutical channels without equivalent analytical documentation.
Condition-specific supplement brands now specify documented bioactive thresholds in procurement contracts rather than accepting generic extract grades. North American direct-to-consumer nutraceutical companies drive this specification escalation. Third-party certification by USP or NSF substitutes for historical supplier relationships in vendor selection decisions.
Botanical Extracts Market Segmentation
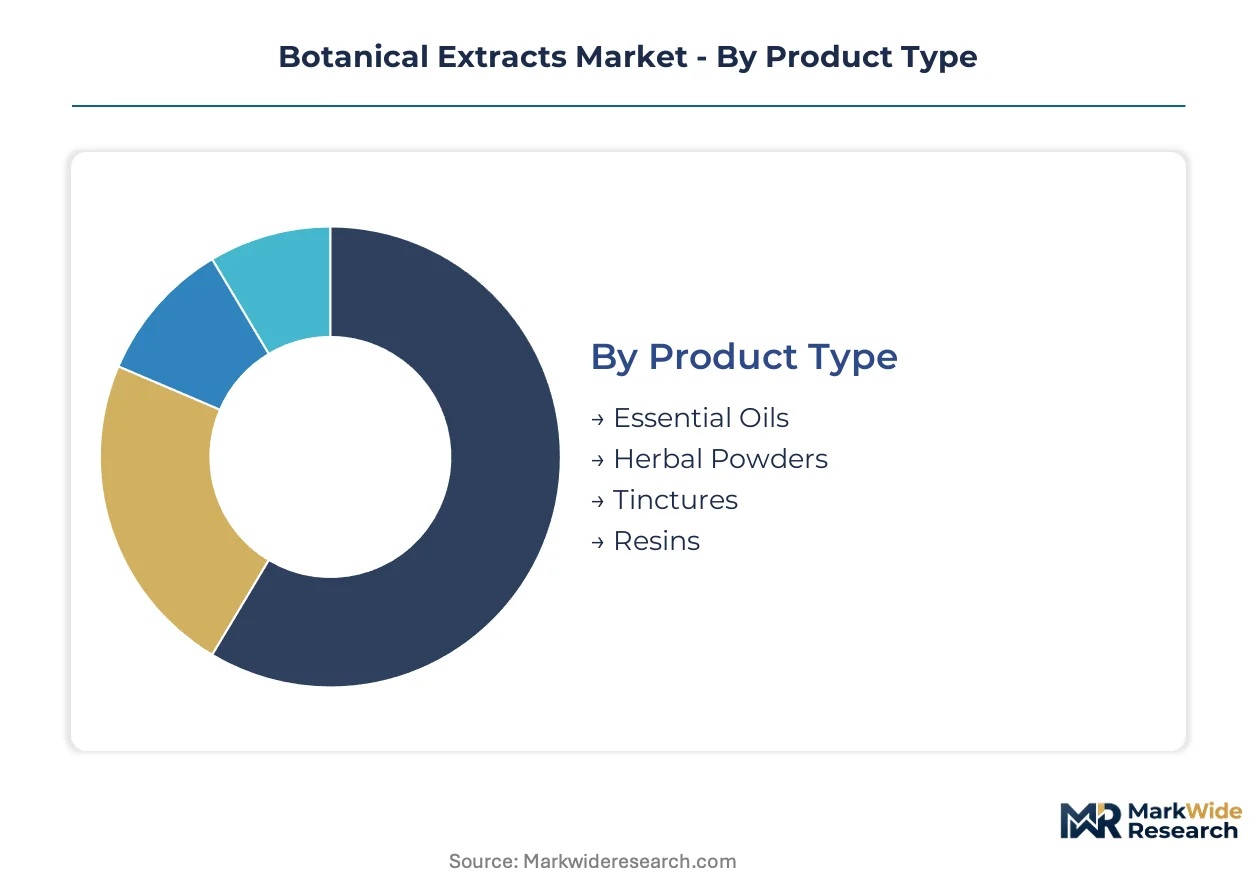
Segmentation in botanical extracts reflects divergent technical requirements across extraction methods and end-use specifications. Pharmaceutical formulators demand standardized marker compounds, while cosmetic buyers prioritize terpene complexity for fragrance differentiation. Each segment carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
Cost tier determines equipment intensity and solvent recovery economics across extraction categories.
- Essential Oils:Steam-distilled or supercritical CO2-extracted volatile concentrates standardized to terpene profiles. French and Swiss cosmetic formulators document these compositions for clean-label fragrance claims, with real-time spectroscopic monitoring compressing quality assurance cycles from weeks to days.
- Herbal Powders:Dried, milled plant material with defined particle size distributions for tableting flow properties. German pharmaceutical manufacturers source these under EMA monograph compliance for prescription herbal medicines, where excipient compatibility determines manufacturing yields.
- Tinctures:Hydroalcoholic extracts with defined herb-to-solvent ratios preserving polar bioactives.
- Resins:Lipophilic concentrated exudates requiring solvent recovery systems to meet REACH residue thresholds.
Essential oils hold installed capacity. Herbal powders are rotating up the share rankings.
Application:
End-use specifications diverge sharply between regulated pharmaceutical channels and discretionary cosmetic markets.
- Pharmaceuticals:EMA-compliant standardized extracts with validated HPLC marker compound documentation. German formulators source ginkgo and St. John's wort under herbal medicine guidelines, where post-market pharmacovigilance obligations trigger rapid reformulation requirements.
- Nutraceuticals:Condition-specific supplements with documented phytochemical thresholds specified in procurement contracts. North American direct-to-consumer brands drive specification escalation, with USP or NSF certification substituting for historical supplier relationships.
- Cosmetics:Fragrance and active ingredient applications prioritizing clean-label appeal and terpene complexity.
- Food & Beverage:Flavor systems requiring EFSA novel food assessments for innovative botanical sources.
Pharmaceuticals hold installed capacity. Nutraceuticals are climbing the fastest.
End User:
Customer type shapes procurement sophistication and specification stringency in contract structures.
- Manufacturers:Integrated formulators with captive analytical capabilities and backward integration into seed selection. These buyers specify batch-to-batch uniformity through validated reference standard libraries, excluding small-batch suppliers without equivalent documentation.
- Distributors:Intermediaries consolidating fragmented supply from BIS-certified Indian Ayurvedic processors for export markets.
- Retailers:Private-label buyers demanding third-party certification to substitute for direct supplier auditing.
- Researchers:Low-volume procurement with exacting phytochemical characterization requirements.
Manufacturers hold installed capacity. Distributors are rotating up the share rankings.
Form:
Physical state determines stability, dosing precision, and compatibility with downstream processing equipment.
- Liquid:Hydroalcoholic tinctures and oil-based concentrates offering rapid bioavailability. Supercritical CO2 extraction systems with in-line monitoring dominate high-value production for cosmetic and nutraceutical channels.
- Powder:Spray-dried or mechanically milled forms with defined flow properties for pharmaceutical tableting and encapsulation operations.
- Solid:Resin matrices and compressed extracts requiring solvent recovery compliance.
- Paste:Semi-solid concentrates for topical and flavor applications.
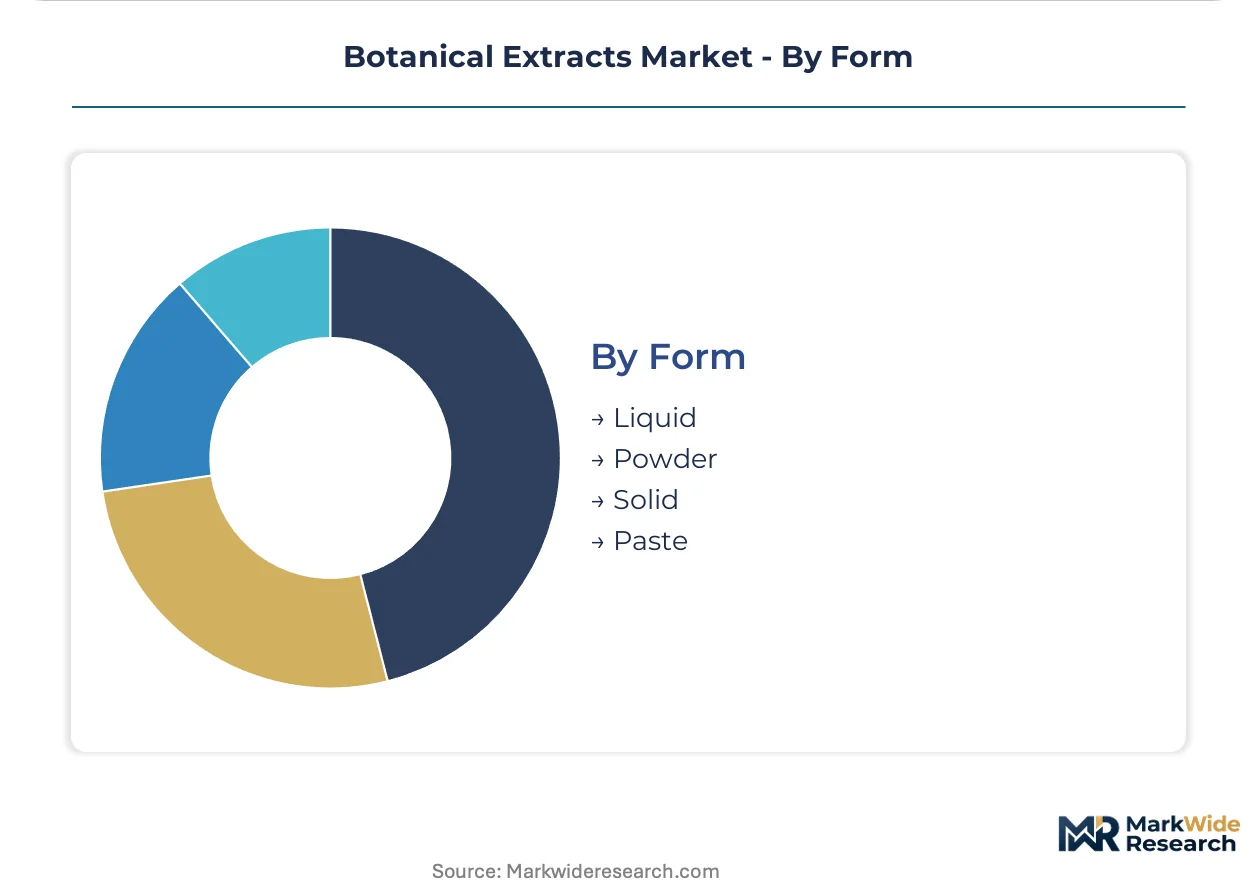
Liquid holds installed capacity. Powder is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA herbal medicine guidelines and FDA cGMPs are compressing supplier margins while rewarding processors with validated analytical capabilities. REACH solvent residue thresholds and BIS certification requirements in India are reshaping extraction technology choices across major supply zones.
Germany
Pharmaceutical formulators in Germany source standardized ginkgo and St. John's wort extracts under EMA monograph compliance. The country's national pharmaceutical regulator mandates quantitative marker compound specifications for all new herbal medicine applications. Processing clusters concentrate in Bavaria and Baden-Württemberg, where reference standard libraries preempt compliance gaps for prescription herbal channels.
India
BIS-certified Ayurvedic extracts supply domestic nutraceutical manufacturers and export markets from Maharashtra and Karnataka. The Bureau of Indian Standards verification requirements concentrate extraction capacity in these western and southern states. Mumbai and Bangalore anchor contract manufacturing networks that serve North American and European direct-to-consumer supplement brands.
United States
North American direct-to-consumer nutraceutical companies drive specification escalation for condition-specific supplement formats. FDA dietary supplement cGMPs determine extract quality benchmarks, with USP or NSF certification substituting for historical supplier relationships. Botanical processing clusters in California and New York Metro link standardized actives to finished product specifications for premium supplement brands.
Switzerland
Swiss cosmetic formulators adopt supercritical CO2 extraction platforms with in-line spectroscopic monitoring to document terpene profiles. Swissmedic guidelines align with EMA herbal medicine frameworks for cross-border pharmaceutical trade. Geneva and Basel host extraction-to-application service providers that link botanical actives directly to clean-label fragrance claims for European luxury cosmetics.
France
French cosmetic and flavor houses demand documented phytochemical profiles for clean-label positioning in premium personal care. EFSA novel food assessments create entry barriers for innovative botanical sources in food applications. Extraction specialists in Provence-Alpes-Côte d'Azur and Île-de-France compress release-to-market timelines through real-time compositional feedback loops.
Botanical Extracts Market Vendor Landscape
On the supply side, the industry is consolidating around processors with validated analytical capabilities and captive cultivation networks. Tiered competitive positioning separates integrated multinationals with backward integration into seed selection from independent toll manufacturers dependent on third-party raw material access. Strategic archetypes include extraction-to-application bundlers, dual-technology processors, and BIS-certified Ayurvedic specialists. Dominant competitive moves encompass strategic partnerships for temperate zone cultivation access and technology licensing for supercritical CO2 platform adoption.
Among integrated flavor and active ingredient houses, Symrise AG, Kerry Group, and ADM occupy positions spanning extraction through finished formulation delivery. Symrise AG exemplifies the captive cultivation archetype through multi-zone agricultural partnerships. Kerry Group represents extraction-to-application bundling that links standardized actives directly to flavor system specifications. ADM anchors the agricultural advisory model through upstream control over medicinal herb grower networks. These three structures illustrate how competitive positioning in botanical extracts depends on supply chain configuration rather than extraction capacity alone.
| Leading Market Players |
|---|
| Symrise AG |
| ADM |
| Givaudan |
| Kerry Group |
| Indesso |
| International Flavors & Fragrances Inc. |
| Synthite Industries Ltd |
| Döhler |
| Sensient Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Maharashtra and Karnataka extraction clusters concentrate BIS-certified Ayurvedic capacity, translating raw material consistency into premium pricing power for export-grade standardized extracts. German pharmaceutical formulators absorb cost premiums for EMA-compliant ginkgo and St. John's wort, while North American nutraceutical buyers negotiate documented phytochemical thresholds into contract structures.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. EMA-compliant standardized extracts for German prescription channels command substantial premiums over generic herbal grades. REACH solvent residue compliance pressures hexane-dependent processors toward supercritical CO2 methods, compressing margins in the mid-tier. North American direct-to-consumer supplement brands exhibit highest price sensitivity, substituting USP-certified suppliers for historical relationships.
Supply Chain Analysis
Contract manufacturing concentrates in Symrise AG's captive cultivation partnerships across multiple temperate zones and ADM's agricultural advisory networks for medicinal herb growers. Raw material dependencies center on climate-sensitive ginkgo and St. John's wort harvests, genetically consistent seed stock, and REACH-compliant solvent systems. Single-source vulnerability runs through integrated multinational seed partnerships. Distribution runs through Mumbai and Bangalore contract manufacturing networks serving export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
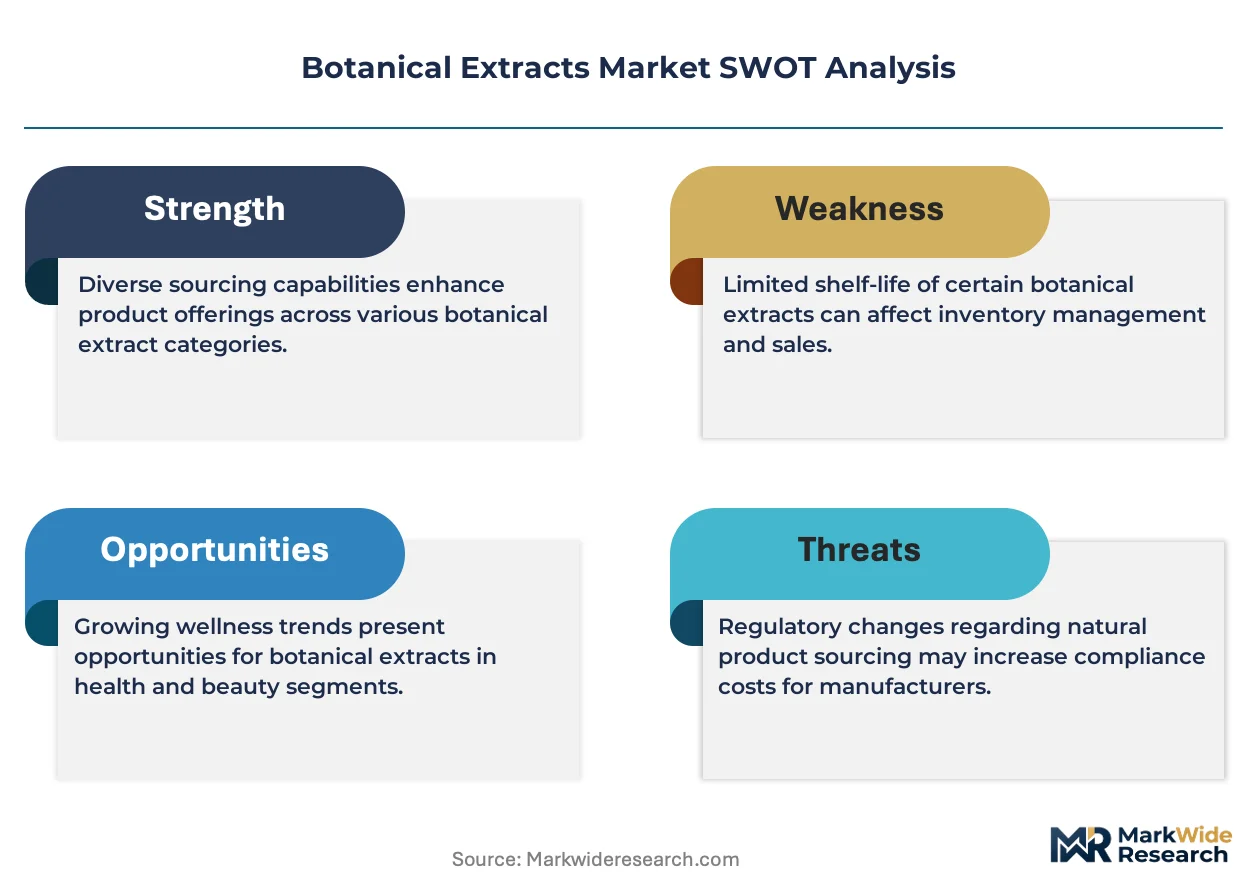
Botanical extracts sit in early-cycle expansion as condition-specific nutraceutical formats penetrate cardiovascular and cognitive health applications. Supercritical CO2 technology adoption and EMA guideline revisions compress batch-to-batch variability while expanding addressable segments.
For Market Incumbents: Entrench analytical capabilities through reference standard library investment to preempt EMA monograph compliance gaps. Secure captive cultivation partnerships across temperate zones to isolate from climate-driven raw material volatility. Threats concentrate in toll manufacturers with asset-light extraction contracts and BIS-certified Indian exporters scaling analytical documentation. For New Entrants and Emerging Players: Pursue extraction-to-application service bundling for North American direct-to-consumer supplement brands demanding documented bioactive thresholds. White-space concentrates in dual-technology processors capturing both lipophilic and polar compound contracts from clean-label cosmetic formulators. Go-to-market through USP or NSF certification to substitute for absent historical supplier relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EMA and FDA standardization requirements reward validated analytical infrastructure over commodity extraction capacity. Acquisition targets center on processors with integrated spectroscopic monitoring platforms and established reference standard libraries. Signal to watch is EFSA novel food assessment timeline compression for innovative botanical sources.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Platform Adoption | Eliminates hexane residues to secure REACH compliance for European pharmaceutical channels. |
| Captive Cultivation Partnerships | Secures genetically consistent seed stock across multiple temperate climate zones. |
| Reference Standard Library Investment | Preempts EMA monograph compliance gaps for quantitative marker compound specifications. |
| Extraction-to-Application Bundling | Links standardized actives directly to finished flavor and nutraceutical system specifications. |
| Dual-Technology Processing Capacity | Captures both lipophilic resin and polar tincture contracts from clean-label formulators. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with extraction technology directors, pharmaceutical procurement managers, and Ayurvedic processing facility heads; and secondary validation through EMA herbal medicine guideline documents, FDA cGMP inspection records, BIS certification registries, and REACH solvent residue compliance databases. Bottom-up capacity modeling across Maharashtra, Karnataka, Bavaria, and California clusters triangulated against top-down demand estimates from German prescription herbal channels and North American supplement brands.
Forecast inputs incorporated extraction method segmentation, certification tier stratification, and end-use application splits across pharmaceutical, nutraceutical, cosmetic, and food channels. CAGRs derived from capacity utilization trajectories and procurement contract value analysis across the projection horizon. Industry-specific variables included EFSA novel food assessment pipeline velocity and supercritical CO2 equipment installation rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices and European chemical regulatory enforcement intensity would shift the trajectory. Forecasts reflect assumptions around EMA monograph revision timelines and climate stability in temperate cultivation zones. Quarterly review of BIS certification issuance rates and REACH compliance violation reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Flakes Market
Ingredients
Textured Soy Flour Market
Ingredients
Algae-Based Ingredients Market
Ingredients
United States Soy Protein Market
Ingredients
Pet Food Premix Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Rose Extract Market
Ingredients
North America Dairy Protein Market
Ingredients
Edible Animal Fat Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Cocoa Beans Market
Ingredients
Kilned Malt Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Plant Extracts Market
Ingredients
Corn Steep Liquor Market