
 Global Cultured Dairy Products Market | 2026-2036
Global Cultured Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cultured Dairy Products Market Analysis
European probiotic fermentation capacity is broadening as dairies retrofit plants for strained and drinkable yogurt formats. Danone leverages its Paris-based R&D hub to sustain formulation leadership in live-culture SKUs. Chobani LLC anchors North American Greek yogurt production through its Idaho and New York facilities. Yakult Honsha competes in Asia via dedicated lactobacillus strain supply chains and pharmacy-channel penetration.
Cultured dairy products encompass milk-based foods fermented with defined bacterial cultures, typically containing live or heat-treated Lactobacillus and Streptococcus strains at minimum counts of 10^6 CFU per gram for probiotic claims. These products deliver controlled acidification, extended shelf stability, and targeted digestive health benefits for commercial food manufacturing and direct consumer consumption. Yogurt occupies the dominant margin pool within product type due to premium positioning and flavor innovation pipelines, while kefir generates the fastest volume growth trajectory among fermented milk drinks. The household end-user segment concentrates demand for multipack and family-size formats, whereas foodservice channels pull bulk cultured dairy for ingredient applications in bakery and prepared foods.
The FDA governs live and active culture labeling claims in the United States, while EFSA evaluates European probiotic health assertions under the Nutrition and Health Claims Regulation. Codex Alimentarius standards harmonize international safety thresholds for pathogen limits and starter culture purity, shaping export market access for multinational suppliers. Stakeholders must monitor evolving strain-specific approval pathways and clean-label fermentation protocols as regulatory scrutiny intensifies across major dairy-exporting jurisdictions.
Market Dynamics
Fermentation technology standardization is compressing production timelines across strained yogurt and kefir lines, forcing dairies to retrofit legacy plants or cede share to purpose-built facilities.
Growth Catalysts
- EFSA strain-specific approvals:Live-culture health claims under EU Regulation 1924/2006 are unlocking pharmacy-channel distribution for probiotic SKUs across Germany and France.
- Clean-label fermentation protocols:Starter culture suppliers are eliminating synthetic stabilizers to meet retailer clean-list requirements in the United States and United Kingdom.
- Drinkable yogurt expansion:Foodservice operators in South Korea and Japan are integrating fermented milk beverages into grab-and-go breakfast programs.
Market Restraints
- Milk powder price volatility:Input cost swings in New Zealand and Australia are squeezing margin structures for powder-dependent cultured dairy exporters.
- Cold-chain infrastructure gaps:Last-mile refrigeration deficits in Indonesia and Vietnam are limiting probiotic viability for ambient-format products.
- Plant-based substitution:Oat and coconut fermented alternatives are capturing shelf space in Scandinavian retail, pressuring conventional cultured dairy volumes.
Strategic Opportunities
- Indian pharmacy-channel penetration:Lactobacillus-based digestive health products face limited competition in urban Indian drugstore networks.
- Precision fermentation convergence:Bioreactor-based dairy protein synthesis is intersecting with traditional fermentation to enable novel texture profiles.
- Direct-to-consumer subscription models:Refrigerated logistics platforms are enabling recurring delivery of live-culture products in Australian metropolitan zones.
Industry Challenges
- Microbiome assay standardization:Inconsistent CFU enumeration methods across laboratories are complicating label-claim defensibility under FDA and EFSA scrutiny.
- Legacy ERP integration:Batch-level traceability requirements for Codex Alimentarius compliance are forcing costly upgrades to decades-old dairy plant software systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cultured Dairy Products Market |
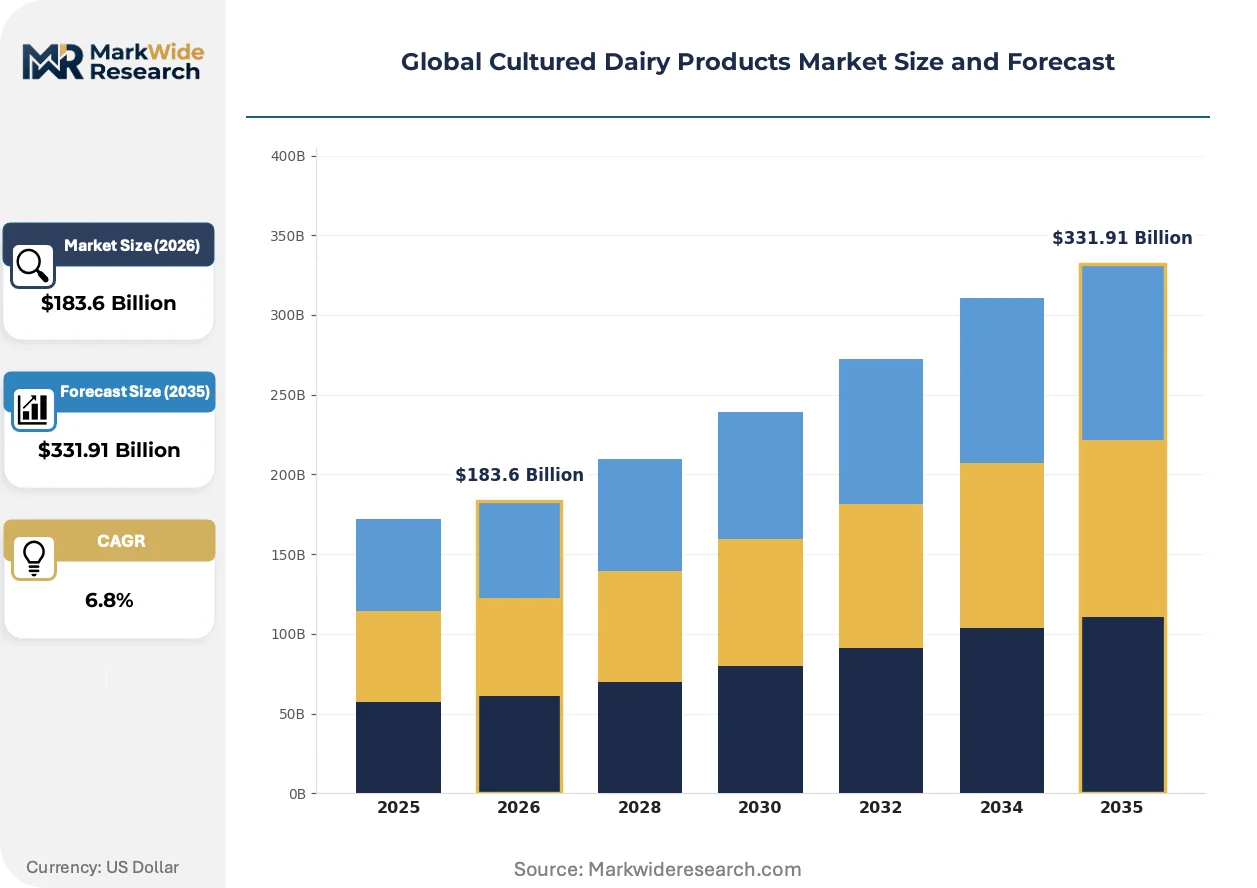
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Buttermilk, Cream Cheese End User: Household, Foodservice, Retail, Bakery Distribution Channel: Supermarkets, Grocery Stores, Online, Convenience Stores Form: Liquid, Solid, Powdered, Frozen |
| Companies Covered | Chobani LLC, Arla Foods, Danone, Amul, Fonterra, Nestlé, Yakult Honsha, Yili Group, Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cultured Dairy Products Market Emerging Trajectories
Continuous flow fermentation is displacing batch processing in large-scale yogurt operations, while regulatory strain-registration pathways are lengthening approval timelines for novel probiotic entrants.
High-pressure processing technology is automating pathogen reduction in drinkable yogurt without thermal degradation of live cultures. Mid-sized dairies in the Netherlands and Canada are adopting HPP lines at accelerating rates. This automation is compressing the traditional pasteurization-cooling-fermentation sequence into single-pass continuous systems.
EFSA's 2023 guidance on "fermented milk" category health claims is tightening evidentiary requirements for digestive benefit assertions. Manufacturers must now submit human intervention studies for strain-specific approvals. Greek and Italian yogurt exporters are restructuring R&D budgets to fund clinical trial programs.
Household buyers are consolidating purchases around multipack formats with extended refrigerator-life claims. Supermarket private-label cultured dairy in Poland and Spain is displacing branded single-serve units. This concentration is most visible in German discounter channels, where family-size kefir and skyr SKUs now dominate refrigerated aisle placement.
Global Cultured Dairy Products Market Segmentation
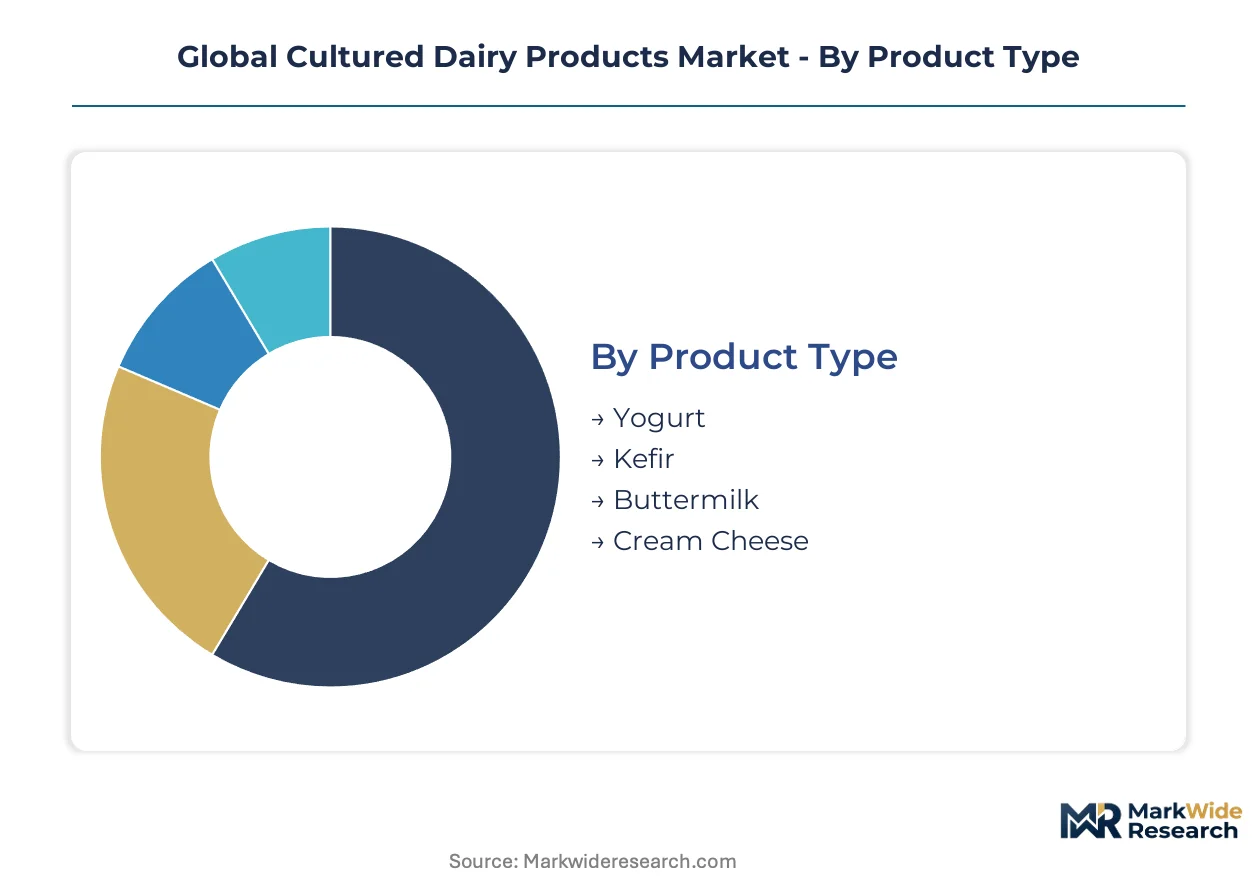
Cultured dairy supply chains require precise segmentation alignment between fermentation specifications and channel economics. Product viscosity, live culture stability, and cold-chain requirements dictate which formats succeed in household versus foodservice environments.
Product Type:
Fermentation protocols differentiate margin structures across this category, with strain selection and processing intensity determining shelf positioning.
- Yogurt:Thermophilic fermentation with Lactobacillus delbrueckii subsp. bulgaricus and Streptococcus thermophilus produces the gelled matrix defining this segment. Household demand concentrates in Germany and France for multipack SKUs with extended refrigerator-life claims. Strained Greek variants command premium placement through elevated protein density and thicker viscosity profiles.
- Kefir:Mesophilic fermentation employing kefir grains containing multiple yeast and bacterial species generates effervescent, pourable textures. Drinkable formats are expanding most quickly in South Korea and Japan through foodservice breakfast programs. The broader microbiome complexity supports digestive health positioning in pharmacy-channel distribution.
- Buttermilk:Traditional acidified dairy liquid retains bakery and industrial ingredient applications through controlled acidity levels.
- Cream Cheese:Lactic acid fermentation of cream and milk creates spreadable matrices for bagel chains and home cooking segments.
Mature deployment sits with Yogurt. Newer deployment is concentrated in Kefir.
End User:
Volume scale and purchase frequency separate this category, with direct consumption patterns diverging sharply from ingredient procurement cycles.
- Household:Multipack and family-size formats dominate refrigerated purchases in Poland and Spain, with German discounter channels consolidating demand around extended-life kefir and skyr SKUs. Live culture viability through home storage duration shapes brand loyalty and repurchase rates.
- Foodservice:Bulk cultured dairy procurement for bakery and prepared food manufacturing concentrates in Idaho and New York production clusters. Operators prioritize batch consistency and neutral flavor bases for ingredient flexibility.
- Retail:Private-label cultured dairy in Scandinavian markets faces pressure from oat and coconut fermented alternatives capturing shelf space.
- Bakery:Acidified buttermilk and cultured cream supply chains serve industrial mixing operations requiring precise pH control for leavening chemistry.
Volume leadership resides with Household. Margin expansion concentrates in Foodservice.
Distribution Channel:
Cold-chain integrity and last-mile logistics determine viable pathways for live-culture product viability.
- Supermarkets:Refrigerated aisle placement in Netherlands and Canada outlets increasingly incorporates high-pressure processing lines for pathogen reduction without thermal culture degradation.
- Grocery Stores:Traditional independent retail maintains family-size format concentration in urban Indian and Vietnamese markets despite refrigeration infrastructure gaps limiting probiotic viability.
- Online:Refrigerated logistics platforms enable recurring delivery models in Australian metropolitan zones, climbing the fastest among channel expansion trajectories.
- Convenience Stores:Ambient-format cultured dairy with heat-treated cultures penetrates grab-and-go consumption in Indonesia where cold-chain deficits persist.
Channel maturity centers on Supermarkets. Digital infrastructure investment concentrates in Online.
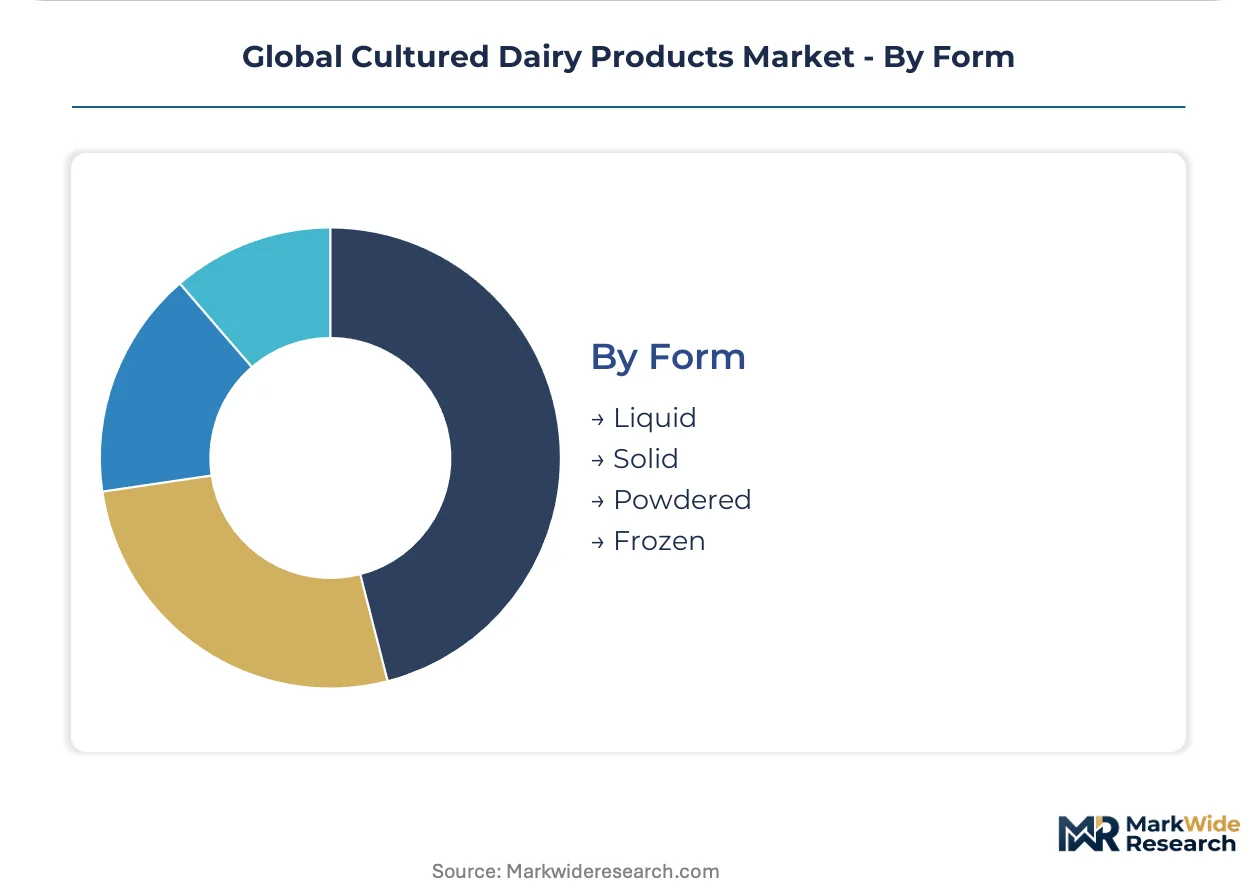
Form:
Physical state determines packaging requirements, fermentation endpoint control, and reconstitution behavior across use cases.
- Liquid:Pourable yogurt and kefir beverages integrate into South Korean and Japanese foodservice breakfast programs through single-serve portability.
- Solid:Set yogurt and strained varieties occupy dominant refrigerated placement in Paris-based R&D hub formulations and Idaho production facilities.
- Powdered:Spray-dried fermented milk powders serve export markets from New Zealand and Australia despite input cost volatility squeezing margin structures.
- Frozen:Fermented dairy desserts and novelties extend seasonal consumption patterns through controlled ice crystal formation during blast freezing.
Production scale favors Solid formats. Format innovation concentrates in Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's grass-fed dairy herds supply protein concentrates that anchor cultured dairy formulations across export markets. The country's Fonterra cooperative channels milk solids into fermentation-ready bases for manufacturers in Asia and the Middle East.
United States
Household demand for Greek yogurt multipacks drives refrigerated aisle expansion in Idaho and New York production corridors. The FDA governs live and active culture labeling claims under 21 CFR 131.200, mandating minimum bacterial counts for probiotic assertions. Chobani LLC operates manufacturing clusters in Twin Falls and South Edmeston, retrofitting legacy lines for strained yogurt viscosity profiles.
Germany
Discounter channels consolidate family-size kefir and skyr purchases around extended refrigerator-life positioning. EFSA evaluates digestive health claims under EU Regulation 1924/2006, requiring human intervention studies for strain-specific approvals. Bavarian dairies retrofit batch fermentation systems to meet pharmacy-channel distribution standards for live-culture SKUs.
Japan
Foodservice operators integrate drinkable yogurt into metropolitan grab-and-go breakfast programs through convenience-store penetration. METI oversees functional food labeling standards that govern lactobacillus strain health assertions. Yakult Honsha maintains dedicated supply chains for its proprietary bacterial cultures, distributing through pharmacy networks in Tokyo and Osaka.
India
Urban pharmacy channels present underexploited distribution pathways for digestive health-positioned fermented products. FSSAI regulates probiotic food standards under the Food Safety and Standards Act, establishing minimum viability thresholds for live cultures. Gujarat and Maharashtra dairy cooperatives expand ambient-format production despite last-mile refrigeration deficits limiting viability in southern states.
Australia
Direct-to-consumer subscription models leverage refrigerated logistics platforms in Sydney and Melbourne metropolitan zones. The country's national dairy regulator enforces Codex Alimentarius-aligned pathogen limits for export certification. Victorian processing facilities adopt high-pressure processing lines to compress pasteurization-fermentation sequences without thermal culture degradation.
Global Cultured Dairy Products Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and plant-adjacent alternatives. The market structures around three maturity tiers: multinational dairy conglomerates with integrated fermentation capacity, regional specialists commanding strain-specific expertise, and biotechnology startups exploring recombinant protein synthesis. Competitive moves concentrate on capacity retrofitting for continuous flow systems and pharmacy-channel licensing partnerships for probiotic health claims.
Within the multinational tier, Danone and Nestlé occupy positions defined by R&D scale and geographic diversification. Danone exemplifies the European fermentation archetype through its Paris-based formulation hub. Nestlé represents the diversified nutrition conglomerate model with cultured dairy embedded within broader dairy portfolios. Yakult Honsha anchors the strain-specialist archetype, with its company name signaling dedicated lactobacillus supply chain concentration. These three entities collectively illustrate competitive positioning around live-culture viability, regulatory health claim navigation, and channel-specific distribution depth.
| Leading Market Players |
|---|
| Chobani LLC |
| Arla Foods |
| Danone |
| Amul |
| Fonterra |
| Nestlé |
| Yakult Honsha |
| Yili Group |
| Lactalis |
| Others |
Supply Flow & Price Mechanics
Global Dairy Trade auction prices for whole milk powder cascade through cultured dairy supply chains, compressing margin structures for powder-dependent exporters while amplifying pricing power for integrated processors with captive milk supplies.
Pricing Analysis
Extended refrigerator-life warranties differentiate premium cultured dairy SKUs from standard variants with shorter viability windows. Three-tier pricing structure across premium, standard, and economy levels reflects strain certification status under FDA and EFSA frameworks plus cold-chain reliability guarantees. Pricing pressure stems from New Zealand and Australian milk powder input cost volatility squeezing powder-reliant manufacturers. Foodservice bulk buyers exhibit highest price sensitivity due to ingredient substitution flexibility, while pharmacy-channel distributors accept premium positioning for strain-specific probiotic claims.
Supply Chain Analysis
Starter culture supply rests on dedicated fermentation laboratories in France, Japan, and Denmark maintaining proprietary Lactobacillus and Streptococcus strain banks. Raw milk procurement draws from grass-fed herds in New Zealand, consolidated cooperatives in the Netherlands, and dairy clusters in Idaho and New York. Single-source vulnerability concentrates in specialized kefir grain suppliers with limited geographic diversification. Distribution runs through refrigerated logistics platforms serving supermarkets in Germany and direct-to-consumer subscription models in Australian metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-culture fermentation capacity constraints in pharmacy-channel grade facilities prop pricing premiums, creating defendable margin pools for operators with EFSA-approved strain portfolios.
For Market Incumbents: Hedge against plant-based substitution by securing backward integration into precision fermentation capacity for novel dairy protein synthesis. Acquire certification investments for Codex Alimentarius-aligned export standards before regulatory scrutiny intensifies across major dairy-exporting jurisdictions.
For New Entrants and Emerging Players: Urban Indian pharmacy networks represent an underserved buyer archetype with limited Lactobacillus-based digestive health competition. Target ambient-format production for cold-chain-deficient Southeast Asian markets through heat-treated culture formulations. Pursue direct-to-consumer subscription angles in Australian metropolitan zones where refrigerated logistics platforms enable recurring delivery models.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized dairies with retrofit-ready batch fermentation systems in Bavaria and Victoria. Long-term viability over a five-to-ten-year window hinges on continuous flow fermentation adoption and pharmacy-channel licensing partnerships. Watch EFSA strain-specific approval timelines as the critical inflection signal for probiotic health claim defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Fermentation Retrofit | Compresses production timelines for strained yogurt lines at Netherlands and Canadian facilities. |
| EFSA Strain Registration Investment | Unlocks pharmacy-channel distribution for live-culture SKUs across German and French networks. |
| High-Pressure Processing Line Adoption | Automates pathogen reduction without thermal degradation of live cultures in drinkable formats. |
| Direct-to-Consumer Platform Launch | Enables recurring delivery models leveraging refrigerated logistics in Sydney and Melbourne zones. |
| Precision Fermentation Partnership | Intersects bioreactor-based dairy protein synthesis with traditional fermentation for novel textures. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dairy plant managers, fermentation R&D directors, pharmacy-channel procurement leads, and cold-chain logistics operators combined with FDA 21 CFR submissions, EFSA health claim registers, Fonterra auction results, and Codex Alimentarius standards. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Granularity-level modeling operated at product-type, end-user, distribution channel, and form dimensions across the analysis window. Strain-specific regulatory approval status, cold-chain infrastructure maturity, and pharmacy-channel penetration depth served as industry-specific forecast inputs. CAGRs derived from trend extrapolation anchored in historical trade flows and capacity expansion announcements.
Revisions become necessary when EFSA strain approval timelines extend, milk powder auction volatility exceeds historical bands, or precision fermentation achieves cost parity with traditional dairy proteins. Forecasts reflect documented assumptions about live-culture viability thresholds and clean-label fermentation protocol adoption. A small set of named triggers—regulatory strain registration delays, cold-chain infrastructure investments in Southeast Asia, and plant-based substitution rates in Scandinavian retail—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Japan Casein Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Middle East Dairy Market
Dairy Products
GCC Casein Market
Dairy Products
Global Milk Powder Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Global Milk Protein Market
Dairy Products
Canada Dairy Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Flavored Yogurt Market
Dairy Products
A2 Protein Milk Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Fat-Rich Dairy Products Market