
 APAC Savoury Ingredients Market | 2026-2036
APAC Savoury Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Savoury Ingredients Market Outlook
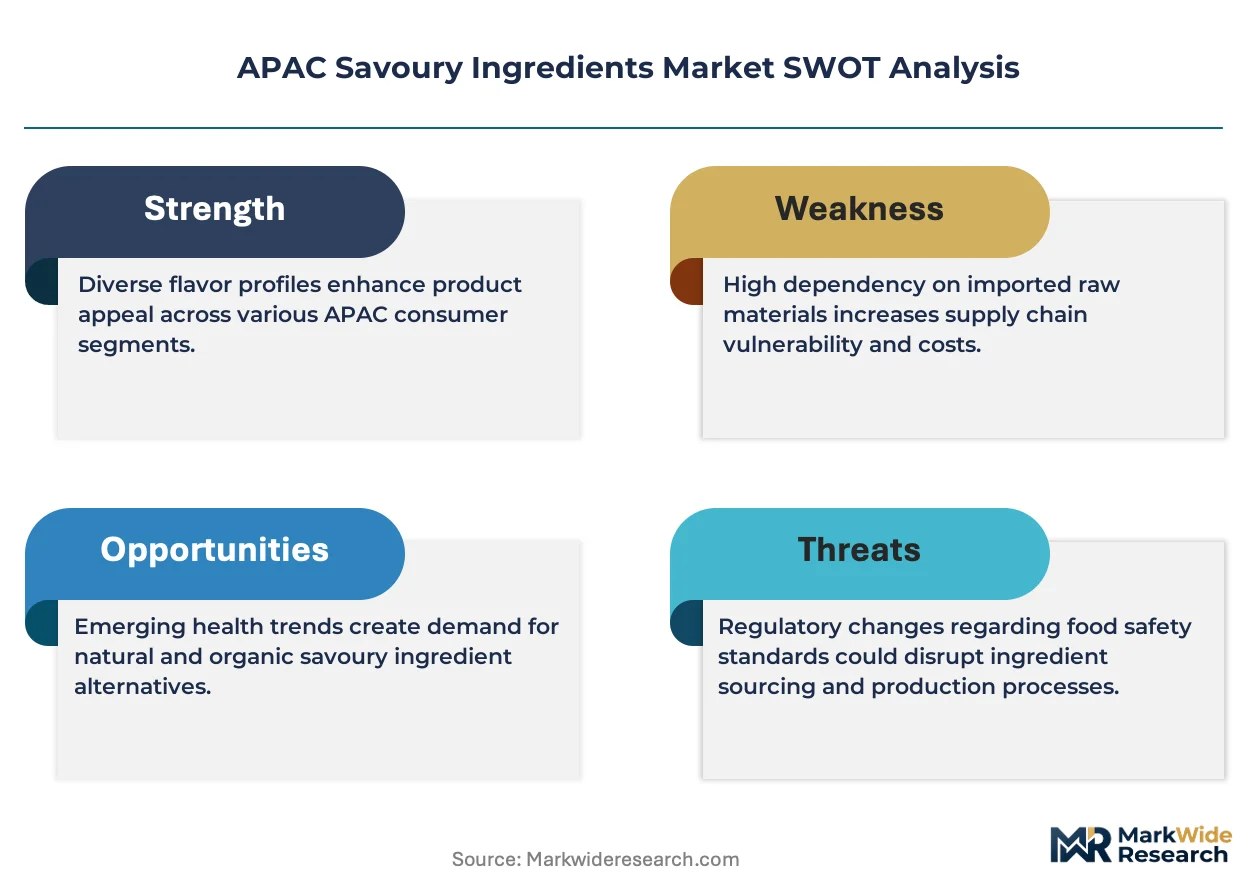
Japan's sodium-reduction mandates under METI is decoupling traditional MSG-reliant formulations from premium product lines. Ajinomoto Co., Inc. leverages its fermentation expertise to anchor low-sodium umami solutions across East Asian food manufacturers. Kerry Group plc competes through localized taste-modulation labs in Southeast Asia, while AngelYeast Co., Ltd. specializes in yeast-derived savoury bases that sustain clean-label positioning for Chinese snack producers.
APAC savoury ingredients comprise formulated taste-active compounds, hydrolyzed proteins, yeast extracts, and fermented seasonings designed to deliver umami, kokumi, and aromatic depth in processed foods. These inputs typically achieve flavor potency at inclusion rates below two percent by weight, enabling manufacturers to reduce sodium or artificial additives without sensory compromise. Seasonings and flavorings occupy the deepest margin pools due to formulation complexity and customer stickiness, while powder and granular forms lead volume given shelf stability and logistics efficiency across fragmented Asian supply chains. Ready meals and snacks represent the fastest-growing application vectors as urbanization compresses cooking time.
China's SAMR enforces GB standards on food additive labeling and microbial limits, while India's FSSAI mandates progressively stricter contaminant thresholds for imported savoury inputs. Japan's PMDA and METI coordinate on novel food ingredient approvals, creating a multi-layered compliance landscape that shapes R&D allocation and cross-border formulation strategies. Stakeholders must monitor how divergent sodium caps and clean-label definitions across these jurisdictions reshape product architecture and regional manufacturing footprints.
Market Dynamics
Japan's METI sodium-reduction mandates are fragmenting traditional umami supply chains as manufacturers reformulate away from MSG-heavy bases toward yeast-derived and fermented alternatives that preserve sensory intensity at lower inclusion rates.
Growth Catalysts
- Clean-label fermentation:Chinese snack producers under SAMR labeling scrutiny are accelerating adoption of yeast extract systems that deliver kokumi depth without E-number declarations.
- India's QSR procurement surge:Quick-service restaurant chains across Maharashtra and Karnataka are consolidating savoury ingredient contracts to secure consistent hydrolyzed vegetable protein supply for standardized flavor profiles.
- Dual carbon sourcing requirements:China's MEE enforcement of carbon intensity disclosures is redirecting procurement toward domestic fermentation facilities with verified renewable energy inputs.
Market Restraints
- Input cost volatility:Molasses and sugar beet feedstock prices for yeast fermentation fluctuate with agricultural commodity cycles, compressing margin stability for extract producers.
- Supply concentration risk:Premium hydrolyzed vegetable protein capacity clusters in Shandong and Jiangsu provinces, creating geographic vulnerability to regional logistics disruptions.
- Regulatory friction:India's FSSAI progressively tightens heavy metal and microbial limits on imported savoury inputs, extending customs clearance timelines for Southeast Asian suppliers.
Strategic Opportunities
- Vietnam's underpenetrated processing sector:Emerging ready-meal manufacturers in Ho Chi Minh City industrial zones seek localized umami compound suppliers to reduce import dependency.
- Indonesia's halal certification pathway:MUI halal verification for fermentation-derived ingredients opens access to packaged food exporters serving Middle Eastern markets.
- Plant-protein convergence:Blending yeast extracts with pea and soy protein hydrolysates creates hybrid savoury bases for meat-alternative applications in South Korean food tech ventures.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology talent pools in India and Southeast Asia remain shallow relative to scaled production requirements, inflating R&D team compensation.
- Legacy equipment retrofit costs:Converting spray-drying facilities from synthetic flavor production to clean-label extract handling demands stainless steel infrastructure replacement and HACCP recertification.
- Cross-border formulation complexity:Divergent sodium cap definitions between Japan's METI guidelines and China's GB standards force manufacturers to maintain parallel product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Savoury Ingredients Market |
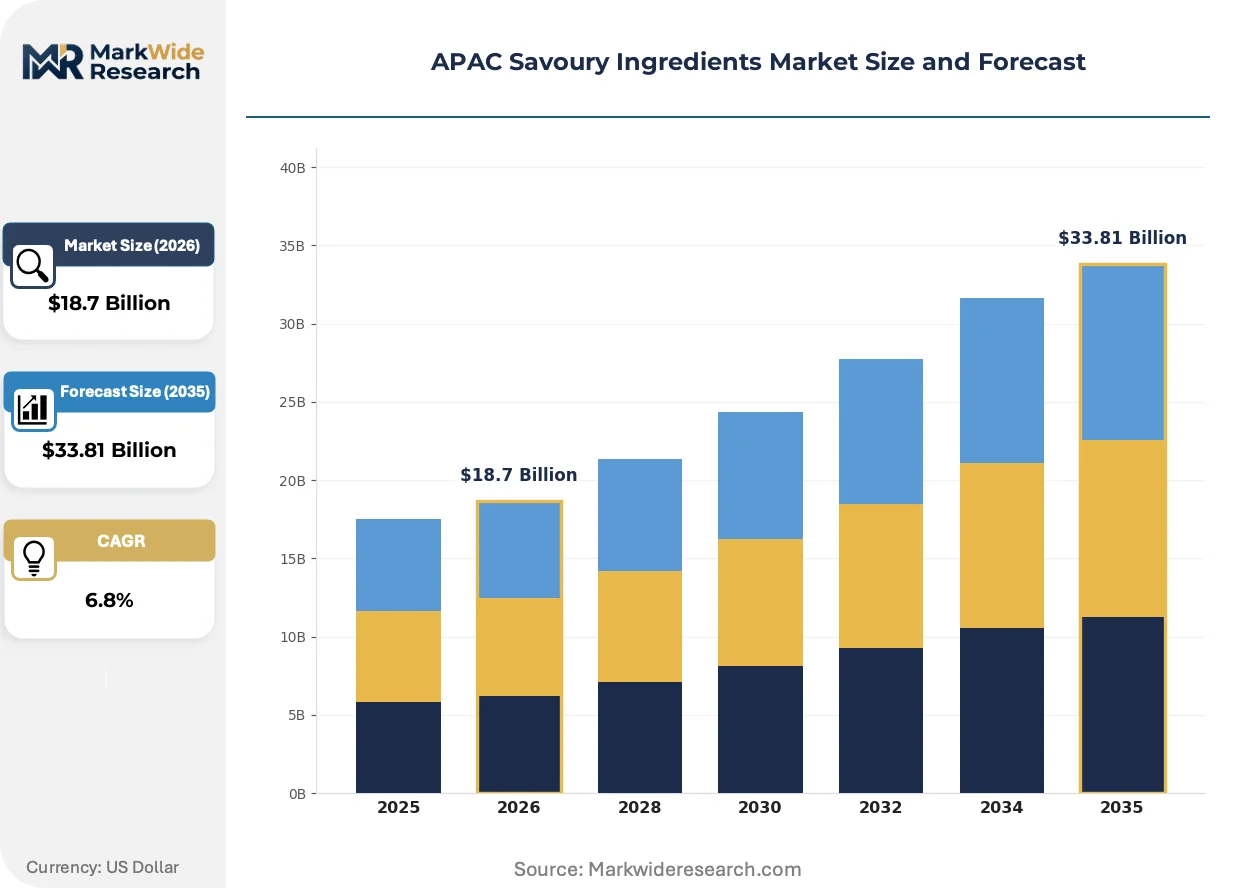
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasonings, Sauces, Marinades, Flavorings End User: Food Manufacturers, Restaurants, Retailers, Catering Services Form: Liquid, Powder, Granular, Paste Application: Snacks, Dips, Soups, Ready Meals |
| Companies Covered | Tate & Lyle plc, Givaudan SA, Ajinomoto Co., Inc., AngelYeast Co., Ltd., Archer Daniels Midland Company, Koninklijke DSM N.V., Symrise AG, Sensient Technologies Corporation, Kerry Group plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Savoury Ingredients Market Strategic Shifts
Fermentation science and precision bioprocessing are redrawing competitive boundaries in APAC savoury ingredients as established synthetic pathways face regulatory and consumer headwinds.
Continuous fermentation systems with real-time metabolite monitoring are absorbing capital allocation from batch-process infrastructure across Chinese and Japanese production facilities. AngelYeast and domestic competitors in Hubei province are retrofitting plants with sensor arrays that optimize yeast cell viability and umami nucleotide yield. This technology compression is shortening product development cycles from eighteen months to under nine for new savoury base formulations.
Japan's PMDA and METI coordination on novel food ingredient approvals is tightening safety documentation requirements for fermented savoury extracts derived from non-conventional substrates. Manufacturers must now submit extended toxicology dossiers for yeast strains engineered to produce elevated glutamate levels. Premium product lines targeting elderly nutrition and reduced-sodium clinical foods bear the heaviest compliance burden, with some reformulations delayed pending joint regulator review.
Direct procurement contracts between savoury ingredient suppliers and retail-ready meal producers are displacing traditional distributor intermediaries in South Korea and Australia. CJ CheilJedang and domestic Australian manufacturers now negotiate volume commitments spanning three-year horizons with price escalation clauses tied to agricultural input indices. This channel consolidation concentrates negotiation leverage with buyers possessing scale, squeezing margin buffers for mid-tier extract suppliers serving fragmented snack producers.
APAC Savoury Ingredients Market Segmentation
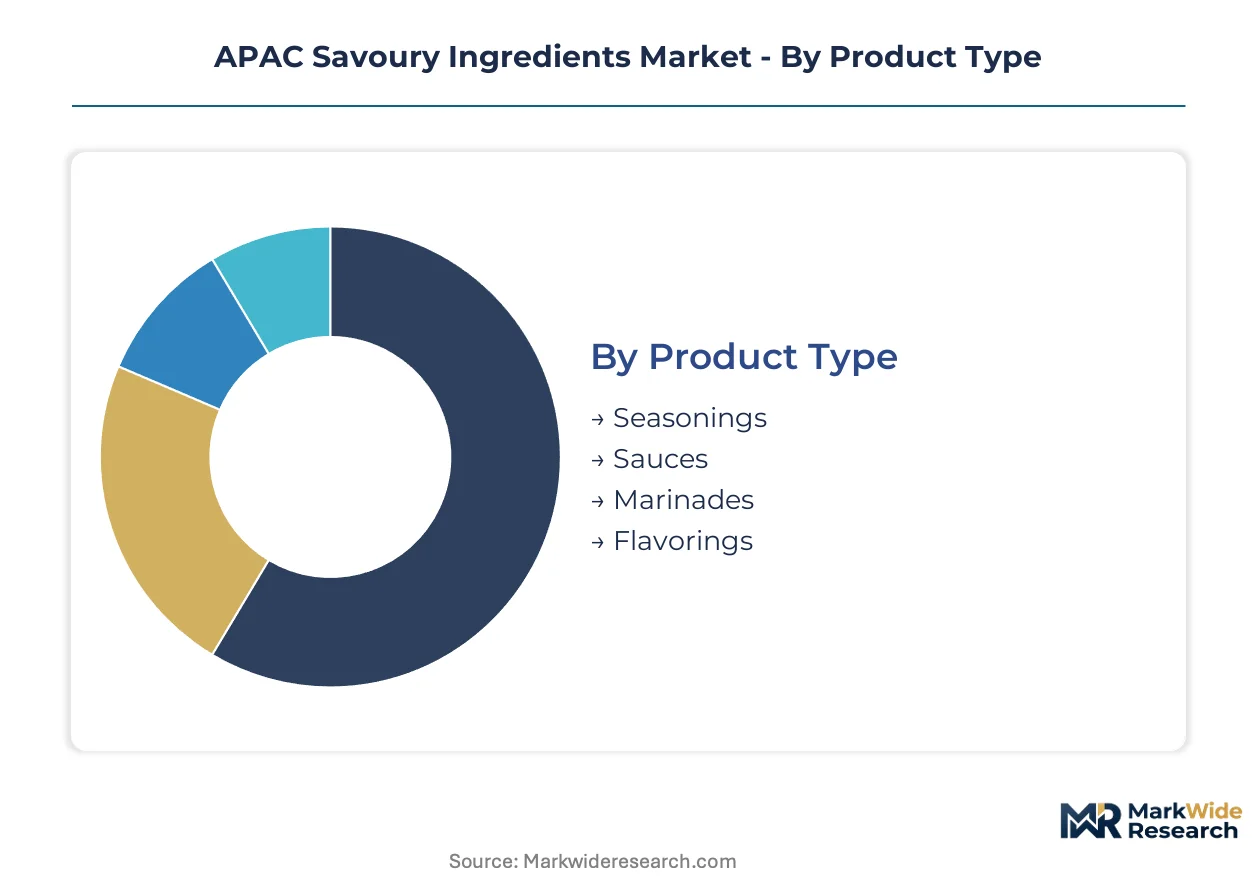
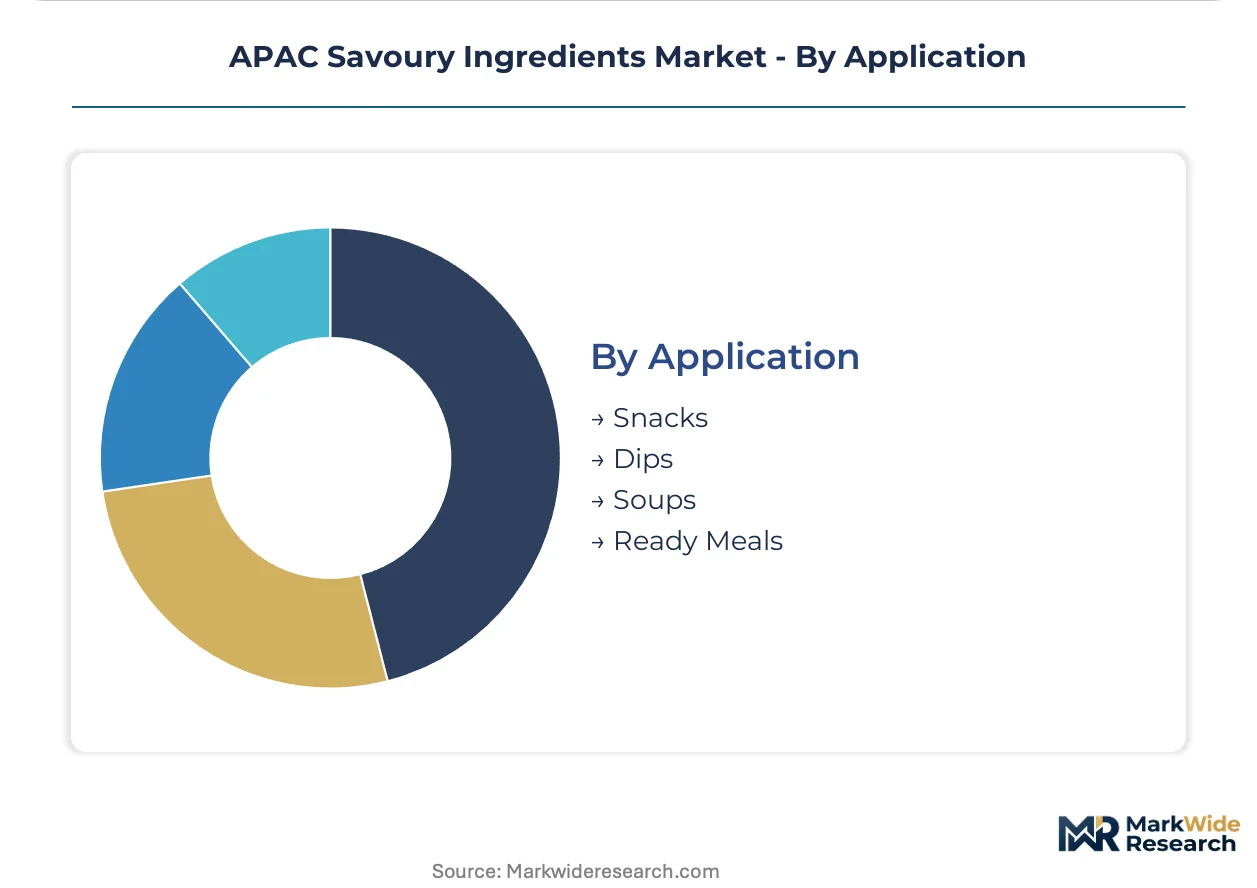
APAC savoury ingredients fragment across four functional axes that reshape procurement patterns and margin capture. Formulation complexity, regulatory labeling requirements, and supply chain logistics each favor distinct segment combinations across Japanese sodium-reduction mandates and India's QSR expansion.
Product Type:
Fermentation-derived systems and synthetic compound portfolios define competitive positioning across Japanese, Chinese, and Indian food manufacturing bases.
- Seasonings:Blended salt-spice-umami matrices incorporating yeast extracts and hydrolyzed vegetable proteins to achieve METI-compliant sodium thresholds. Indian snack producers in Maharashtra and Gujarat concentrate procurement here for standardized flavor profiles across distributed production networks.
- Sauces:Liquid or semi-liquid emulsions combining fermented soy bases, hydrolyzed proteins, and lipid-phase aromatics. China's SAMR labeling scrutiny accelerates clean-label reformulation in Shandong and Guangdong processing corridors.
- Marinades:Acid-enzyme-protein systems for protein tenderization and flavor penetration. South Korean ready-meal manufacturers leverage these for refrigerated protein applications.
- Flavorings:High-potency taste-active compounds—nucleotides, amino acids, Maillard reaction products—delivering umami and kokumi at sub-2% inclusion rates.
Seasonings lead on scale; flavorings lead on momentum.
End User:
Procurement concentration and contract duration separate volume-driven buyers from specification-sensitive accounts across the region.
- Food Manufacturers:Packaged snack, sauce, and ready-meal producers negotiating multi-year supply agreements with price escalation clauses tied to molasses and agricultural input indices. South Korean and Australian manufacturers now consolidate three-year volume commitments directly with extract suppliers.
- Restaurants:Quick-service chains across Maharashtra and Karnataka standardizing hydrolyzed vegetable protein inputs for consistent cross-location flavor delivery. India's QSR procurement surge centers here.
- Retailers:Private-label ready-meal and sauce developers sourcing clean-label fermented bases under SAMR and FSSAI compliance frameworks.
- Catering Services:Institutional volume buyers prioritizing shelf-stable powder and granular forms for logistics efficiency across fragmented Asian supply chains.
Food manufacturers dominate contract value; restaurants expand most quickly.
Form:
Physical state determines shelf stability, dissolution kinetics, and clean-label positioning across divergent regulatory environments.
- Liquid:Aqueous extracts and concentrated sauces requiring refrigerated logistics or aseptic packaging. Japanese premium product lines favor these for reduced-sodium clinical and elderly nutrition applications.
- Powder:Spray-dried yeast extracts and hydrolyzed protein isolates with extended ambient shelf life. Powder and granular forms lead volume given logistics efficiency across fragmented Asian supply chains.
- Granular:Agglomerated particles balancing flowability with rapid hydration. Chinese snack producers adopt these for seasoning drum applications.
- Paste:High-solids fermented concentrates—miso-derived, soy sauce reductions—delivering intense umami with minimal water activity.
Powder leads on scale; liquid gains share fastest.
Application:
End-use functionality and consumption occasion reshape inclusion rates and regulatory exposure for savoury input suppliers.
- Snacks:Extruded, fried, and baked products requiring surface-seasoning adherence and flavor stability through high-temperature processing. China's SAMR enforcement of GB additive labeling standards accelerates yeast extract adoption here.
- Dips:Emulsified or aqueous systems combining fermented bases with stabilizers and acidulants. Australian and South Korean retail-ready meal producers concentrate procurement for chilled distribution channels.
- Soups:Dehydrated and retorted formats demanding instant dissolution and heat-stable flavor delivery. Japanese sodium-reduction mandates reshape formulation architectures most acutely in this segment.
- Ready Meals:Refrigerated and shelf-stable complete dishes requiring multi-component flavor systems. Urbanization across India and Southeast Asia drives steepest expansion trajectory here as cooking time compresses.
Snacks lead on scale; ready meals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based savoury ingredient production first scaled in post-war Japan before spreading to Chinese coastal provinces and Indian industrial corridors. The industry now distributes across four distinct national manufacturing bases, each shaped by divergent regulatory frameworks and end-use demand patterns.
Japan
Japan's METI sodium-reduction mandates drive reformulation toward yeast-derived umami systems in Tokyo and Osaka food manufacturing clusters. PMDA coordination on novel ingredient approvals tightens toxicology documentation for engineered yeast strains. Kanto-based extract producers retrofit continuous fermentation lines with real-time metabolite monitoring to compress development cycles.
China
Chinese snack producers under SAMR labeling scrutiny accelerate clean-label yeast extract procurement from Shandong and Jiangsu fermentation facilities. MEE enforcement of carbon intensity disclosures redirects sourcing toward domestic plants with verified renewable energy inputs. Yangtze River Delta manufacturers blend yeast extracts with pea protein hydrolysates for meat-alternative applications.
India
Quick-service restaurant chains across Maharashtra and Karnataka consolidate hydrolyzed vegetable protein contracts for standardized flavor delivery. FSSAI progressively tightens heavy metal and microbial limits on imported savoury inputs, extending customs timelines for Southeast Asian suppliers. Gujarat-based snack producers drive procurement volume for powdered seasoning matrices.
South Korea
Ready-meal manufacturers in Seoul Capital Area negotiate direct three-year procurement contracts with extract suppliers, displacing traditional distributor intermediaries. MFDS labeling requirements shape clean-label reformulation strategies for refrigerated protein applications. Busan-Ulsan industrial zones concentrate aseptic liquid extract capacity for premium product lines.
Australia
Retail-ready meal developers in New South Wales and Victoria source fermented savoury bases under TGA-aligned compliance frameworks for export markets. Domestic manufacturers face input cost pressure from molasses feedstock volatility tied to agricultural commodity cycles. Melbourne-based food tech ventures experiment with hybrid yeast-plant protein systems for alternative protein applications.
APAC Savoury Ingredients Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and customer stickiness. The market structures around fermentation specialists with proprietary strain libraries, diversified ingredient conglomerates with taste-modulation labs, and regional extract producers with cost-optimized capacity. Strategic moves concentrate on backward integration into molasses and sugar beet feedstock sourcing, plus geographic expansion through localized fermentation facilities to satisfy carbon-disclosure requirements.
Among fermentation-derived specialists, Ajinomoto Co., Inc. and AngelYeast Co., Ltd. exemplify the premium-tier archetype anchored in East Asian manufacturing bases. Kerry Group plc occupies a position bridging technical service capabilities with regional taste-localization infrastructure. Tate & Lyle plc and Givaudan SA represent diversified ingredient portfolios that compete through formulation breadth rather than fermentation depth. Archer Daniels Midland Company and Koninklijke DSM N.V. sit within the scale-driven tier, leveraging agricultural input networks and biotechnology platforms respectively. Symrise AG, Sensient Technologies Corporation, and others fragment across specialized application segments.
| Leading Market Players |
|---|
| Tate & Lyle plc |
| Givaudan SA |
| Ajinomoto Co., Inc. |
| AngelYeast Co., Ltd. |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Symrise AG |
| Sensient Technologies Corporation |
| Kerry Group plc |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists across Shandong and Jiangsu provinces anchor supply discipline through backward integration into molasses sourcing, while their pricing power over yeast extract grades tightens as METI sodium caps and SAMR labeling rules simultaneously reshape procurement priorities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates METI-compliant low-sodium extracts from commodity MSG alternatives and generic hydrolyzed proteins. Certification grade under FSSAI and SAMR frameworks, alongside volume scale commitments from South Korean ready-meal manufacturers, drives price differentiation most acutely. Cost compression in standard-tier yeast extracts is intensifying because molasses feedstock volatility feeds directly into margin pressure. India's QSR chains exhibit highest price sensitivity, while Japanese clinical nutrition developers show least elasticity due to reformulation rigidity.
Supply Chain Analysis
Molasses and sugar beet feedstock supply rests on agricultural commodity producers in Brazil, India, and Thailand, with fermentation capacity clustering in China's Yangtze River Delta and Japan's Kanto corridor. Premium hydrolyzed vegetable protein output draws from Shandong and Jiangsu facilities, while yeast strain libraries concentrate in Hubei and Tokyo-Osaka industrial zones. Single-source vulnerability runs through concentrated fermentation equipment suppliers in Germany and Japan. Distribution runs through direct procurement contracts displacing traditional distributor networks across South Korea and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC savoury ingredients function as a geographic-arbitrage play where India's FSSAI import restrictions create cost premiums for domestic fermentation capacity against China's SAMR-compliant export surplus.
For Market Incumbents: Hedge against METI sodium-reduction mandate acceleration by diversifying strain libraries toward kokumi-enhancing peptides, while securing captive molasses supply through upstream partnerships in Maharashtra and Gujarat agricultural zones. Reinforce position in Japan's elderly nutrition segment where PMDA approval timelines deter new entrants. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated ready-meal processing corridor, where Ho Chi Minh City manufacturers seek localized umami compound suppliers to reduce Chinese import dependency. Target halal-certified fermentation outputs for Indonesian exporters serving Middle Eastern markets through MUI verification pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Indian hydrolyzed vegetable protein producers facing FSSAI compliance upgrade costs. Long-term viability frames around fermentation specialist scarcity across Southeast Asia relative to scaled production requirements. Watch METI-PMDA coordination timelines on novel yeast strain approvals as inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Molasses sourcing partnerships in Maharashtra and Gujarat insulate margin stability against agricultural commodity cycles. |
| Continuous Fermentation Retrofit | Real-time metabolite monitoring systems in Hubei and Kanto facilities compress product development cycles for new savoury bases. |
| Halal Certification Pathway | MUI verification for Indonesian fermentation outputs unlocks packaged food export access to Middle Eastern retail channels. |
| Direct Procurement Contracting | Three-year volume commitments with South Korean ready-meal manufacturers displace distributor intermediaries and concentrate buyer leverage. |
| Hybrid Protein System Development | Blending yeast extracts with pea and soy hydrolysates serves South Korean food tech ventures in meat-alternative applications. |
Study Parameters
Direct dialogue with fermentation plant managers, procurement leads at Japanese and Indian food manufacturers, FSSAI regulatory affairs specialists, and SAMR compliance officers combined with secondary validation from customs trade data, SEC filings of listed ingredient suppliers, METI guideline releases, and FSSAI contaminant threshold notifications. Bottom-up capacity assessments across Shandong, Jiangsu, and Maharashtra production facilities triangulated against top-down demand modeling from QSR chain expansion data and ready-meal retail audit trends.
Bottom-up modeling of fermentation capacity utilization, strain yield coefficients, and inclusion rate trends across snack, soup, and ready-meal applications triangulated against top-down expenditure patterns from food manufacturer R&D disclosures. Segmentation dimensions span product type, end user contract structure, physical form, and application functionality across the projection horizon. CAGRs derived from elasticity-adjusted volume projections incorporating METI sodium cap implementation schedules and India's QSR outlet expansion trajectories.
Several conditions sit outside the modeled scope, including abrupt FSSAI heavy metal limit revisions, force majeure disruptions to Brazilian molasses harvests, and PMDA novel food ingredient approval delays beyond standard review windows. Forecasts reflect assumptions around continuous fermentation adoption rates and SAMR enforcement consistency. A small set of named triggers warrants ongoing watch: METI guideline acceleration, MEE carbon intensity disclosure tightening, and Southeast Asian halal certification mutual recognition agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Fats and Oil Market
Ingredients
Calendula Oil Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Dry Malt Products Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Almond Flour Market
Ingredients
Rose Hips Extract Market
Ingredients
Fermented Rennet Market
Ingredients
North America Carrageenan Market
Ingredients
Non-PHO Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Chickpea Protein Market
Ingredients
Proteose Peptone Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Baobab Ingredient Market