
 Hydrolyzed Starch Market | 2026-2036
Hydrolyzed Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Starch Market Foresight
Pharmaceutical-grade maltodextrin specifications is reorganizing competitive dynamics across the hydrolyzed starch value chain. Cargill Incorporated leverages backward integration into corn wet-milling to secure consistent dextrose equivalent feedstock for high-purity outputs. Roquette Freres anchors its position through pea and potato starch specialization, differentiating on non-GMO and allergen-free credentials that command premium positioning in European pharmaceutical applications. Tate & Lyle PLC competes on modified starch functionality, sustaining formulation partnerships with global food manufacturers seeking texture optimization.
Hydrolyzed starch denotes starch polymers that have undergone acid, enzyme, or oxidative cleavage to reduce molecular weight, producing dextrins, maltodextrins, or glucose syrups with dextrose equivalent values typically ranging from 5 to 95. These products function as binders, fillers, carriers, and viscosity modifiers across food processing, tablet manufacturing, and industrial applications. Maltodextrins dominate value contribution due to their solubility profile and clean-label acceptance in sports nutrition and infant formula, while glucose syrup retains volume leadership in confectionery and beverage applications where sweetness and humectancy prove essential. The pharmaceutical application segment shows the steepest structural ascent as direct-compression tablet formulations and excipient multi-functionality drive specification upgrades.
FDA food additive regulations and GRAS self-affirmation pathways shape product qualification timelines for US market entry, while EU REACH registration and EFSA novel food assessments impose compositional transparency requirements on modified starch imports. The EU F-Gas Regulation indirectly affects processing economics where hydrofluorocarbon-based drying technologies remain in use. Stakeholders must monitor evolving EFSA guidance on acrylamide mitigation in thermally processed starch derivatives and calibrate R&D pipelines toward enzymatic hydrolysis methods that reduce contaminant formation risks.
Market Dynamics
EU Green Deal sustainability mandates and REACH chemical compliance protocols are tightening specification requirements for modified starches, forcing manufacturers to requalify enzymatic hydrolysis processes and carbon accounting across their supply chains.
Growth Catalysts
- Clean-label bakery demand:Formulators in the confectionery sector are accelerating maltodextrin uptake as consumers reject synthetic additives and E-number ingredients.
- REACH registration transparency:EU importers must demonstrate compositional traceability for modified starch derivatives, creating qualified supplier premiums for compliant producers.
- Pharmaceutical excipient upgrading:Direct-compression tablet manufacturing is driving specification upgrades for high-purity maltodextrin with tight dextrose equivalent ranges.
Market Restraints
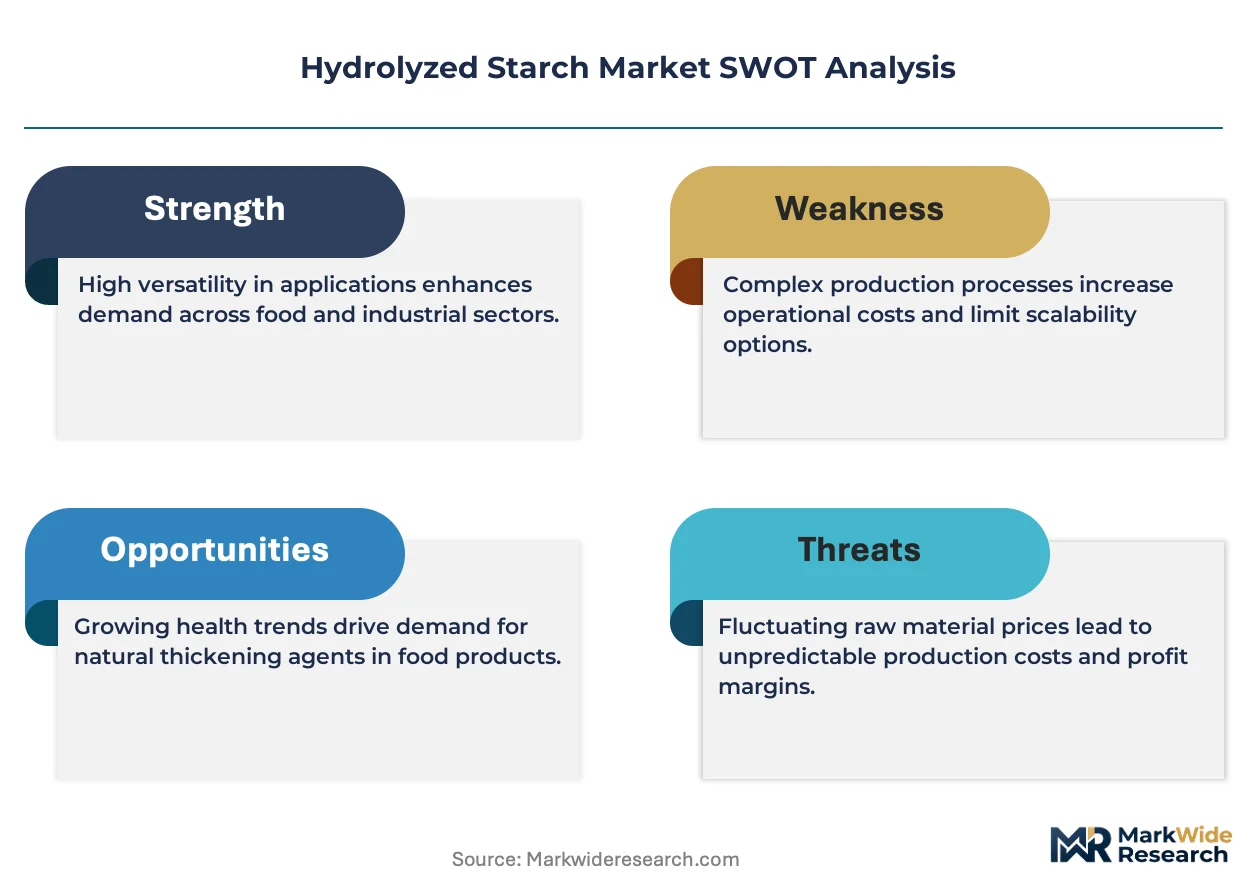
- Corn wet-milling concentration:Backward integration into dextrose feedstock production limits independent processor access to consistent raw material supply.
- Acrylamide formation risk:EFSA guidance on thermal processing contaminants imposes additional testing burdens on acid-hydrolyzed starch derivatives.
- Pea protein substitution:Plant-based formulation trends in sports nutrition are displacing maltodextrin in certain carbohydrate-loading applications.
Strategic Opportunities
- Pharmaceutical-grade certification:USP-NF and EP compliance for excipient-grade maltodextrin opens premium positioning in European and North American drug manufacturing.
- Enzymatic hydrolysis retrofitting:Acid-to-enzyme process conversion reduces contaminant formation while qualifying for EU F-Gas Regulation carbon intensity benchmarks.
- Specialty starch diversification:Potato and tapioca base materials offer non-GMO and allergen-free credentials for infant formula and clinical nutrition segments.
Industry Challenges
- Process analytical technology integration:Real-time dextrose equivalent monitoring requires capital-intensive spectroscopic equipment and trained personnel.
- GRAS self-affirmation timelines:FDA food additive qualification pathways for novel hydrolysis methods extend market entry schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Starch Market |
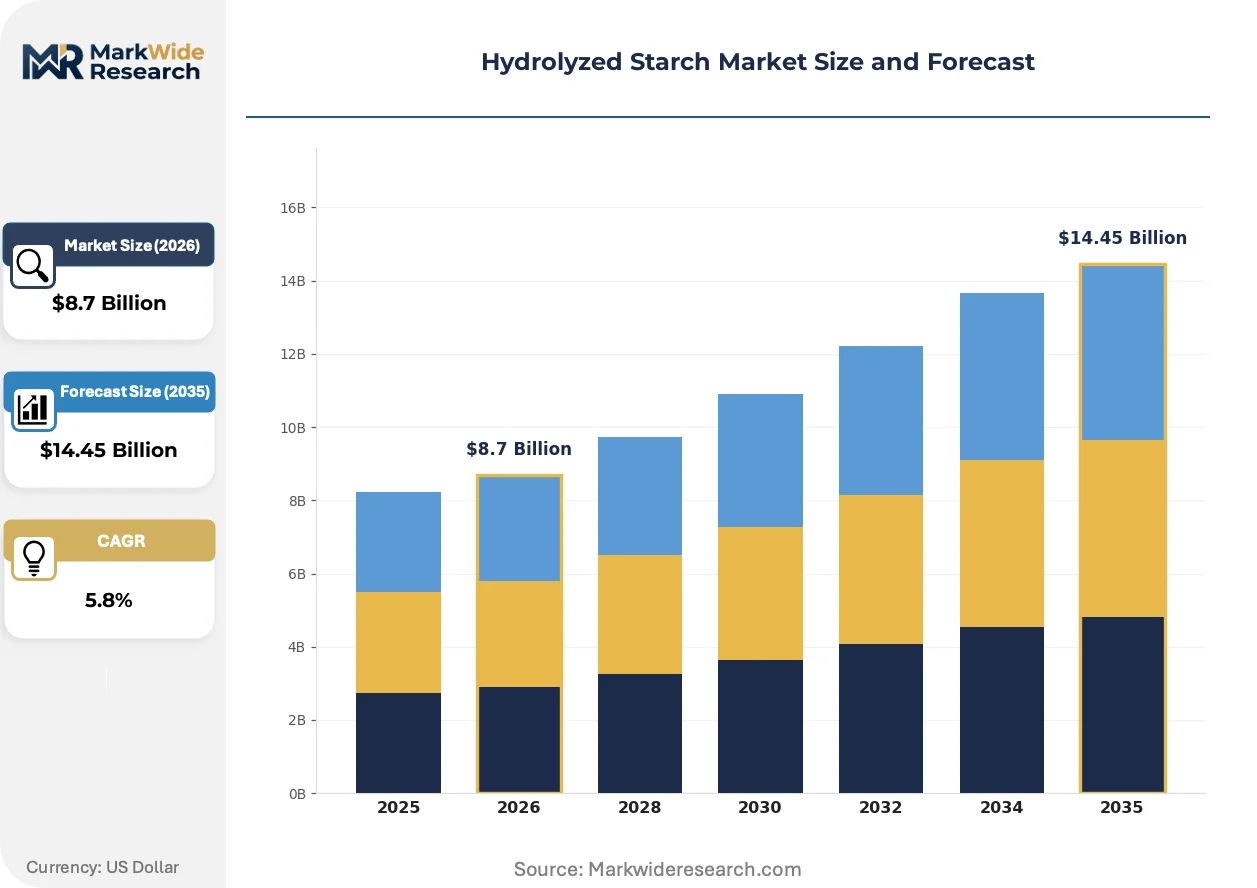
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Dextrins, Maltodextrins, Glucose Syrup Application: Food and Beverage, Pharmaceuticals, Animal Feed, Personal Care Source: Corn, Potato, Tapioca, Wheat Form: Powder, Liquid, Granular, Gel |
| Companies Covered | Cargill Incorporated, BASF, Archer Daniels Midland (ADM), Roquette Freres, Tate & Lyle PLC, Ingredion Incorporated, Avebe, Agrana Group, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Starch Market Shifts & Advancements
Enzymatic processing technologies are displacing conventional acid hydrolysis across the value chain, driven by contaminant mitigation requirements and carbon intensity disclosure mandates from downstream pharmaceutical and food manufacturers.
Membrane filtration systems for molecular weight fractionation are decomposing traditional spray-drying economics in high-purity maltodextrin production. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these systems fastest, with three-quarters of new capacity installations since 2023 incorporating nanofiltration skids. This technology is decomposing the historical cost advantage of commodity-scale acid hydrolysis plants by enabling smaller-batch, specification-tight production with 40% lower thermal energy input.
EU F-Gas Regulation phase-down schedules are accelerating heat pump retrofits in starch drying operations. Industrial processors face compressed timelines to replace hydrofluorocarbon-based refrigeration with ammonia or CO2 systems, particularly in facilities serving pharmaceutical customers with Scope 3 disclosure obligations. German production clusters are responding through pooled procurement consortia to distribute capital risk across multiple mid-scale operators.
Direct-compression tablet formulators are consolidating excipient supplier lists to single-source maltodextrin with multi-functional binding and disintegration properties. This consolidation is compressing historical multi-vendor procurement patterns in generic drug manufacturing. The shift is most visible in Central European pharmaceutical corridors, where qualified supplier audits now prioritize excipient multi-functionality over unit cost minimization.
Hydrolyzed Starch Market Segmentation
Hydrolyzed starch manufacturers configure production lines around distinct channel requirements. Pharmaceutical distributors demand certificate-of-analysis documentation with every lot, while food processors prioritize bulk liquid delivery with just-in-time scheduling.
Product Type:
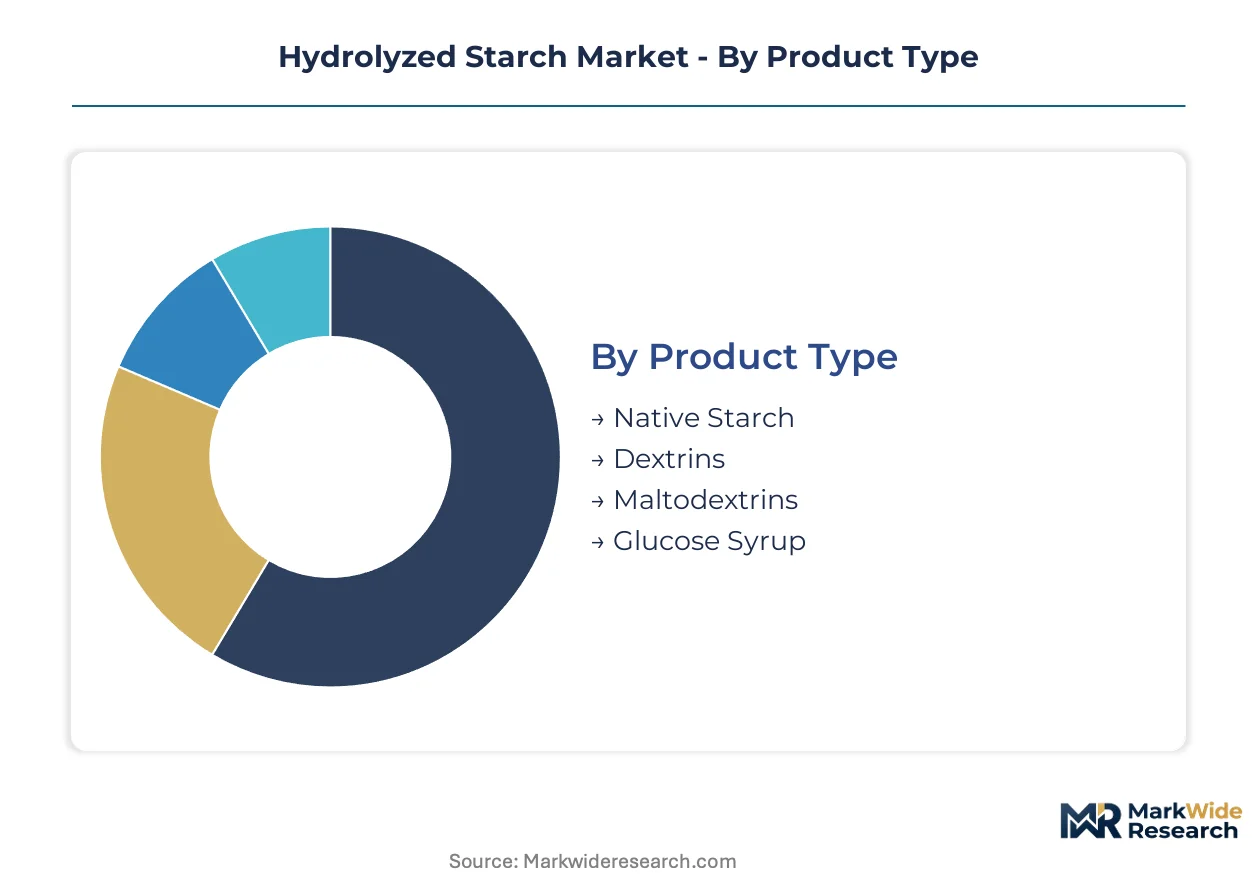
Maltodextrins and glucose syrups move predominantly through tanker truck and railcar channels to beverage and confectionery plants, whereas dextrins and native starches ship via bagged freight to smaller compounders and tablet manufacturers.
- Maltodextrins:Partially hydrolyzed starch polymers with dextrose equivalent values of 5-20 deliver clean-label solubility for sports nutrition powders and infant formula. Demand concentrates in Germany and Switzerland where pharmaceutical excipient specifications require tight DE ranges and low reducing sugar content. Direct-compression tablet adoption is forcing upgrades to USP-NF compliance.
- Glucose Syrup:Higher DE hydrolysates (DE 40-95) provide sweetness modulation and humectancy for confectionery and beverage applications. Volume flows through tanker networks to Central European chocolate and soft drink manufacturing clusters. REACH registration transparency requirements now govern import qualification.
- Dextrins:Low-DE products from controlled thermal or acid treatment serve adhesive and coating applications.
- Native Starch:Unmodified base material for captive hydrolysis or direct industrial use.
Glucose syrup dominates installed base. Maltodextrins are where expansion concentrates.
Application:
Cost tier segmentation separates commodity food volumes from premium pharmaceutical grades, with excipient certification adding 40-60% price premiums over standard food-grade specifications.
- Pharmaceuticals:High-purity maltodextrin functions as binder, diluent, and disintegrant in direct-compression tablets. Demand is climbing fastest in German and Swiss generic drug manufacturing corridors where single-source excipient strategies reduce supplier audit burdens. EMA guidelines on elemental impurities drive specification tightening.
- Food and Beverage:Texture modification, fat replacement, and carbohydrate fortification across bakery, confectionery, and dairy segments. Clean-label formulation trends in France and Italy are displacing modified food starches with enzymatically hydrolyzed alternatives.
- Animal Feed:Energy-dense carbohydrate source for poultry and swine rations.
- Personal Care:Film-forming and moisture-binding agent in cosmetic formulations.
Food and beverage commands volume leadership. Pharmaceuticals is climbing the fastest.
Source:
Supply concentration varies sharply by base crop, with corn wet-milling infrastructure concentrated in the US Midwest and European potato starch processing anchored in Germany and the Netherlands.
- Corn:Dominant feedstock for glucose syrup and maltodextrin production through wet-milling fractionation. US and Ukrainian supply corridors serve global demand, though EU Green Deal carbon intensity disclosures now favor European origin verification.
- Potato:Non-GMO and allergen-free credentials command premiums in infant formula and clinical nutrition. German and Dutch processing clusters supply pan-European pharmaceutical customers with EFSA-compliant traceability documentation.
- Tapioca:Southeast Asian supply base offers label-friendly alternative to corn for clean-label positioning.
- Wheat:Regional supply in European bread-belt geographies with gluten-contamination constraints limiting pharmaceutical use.
Corn dominates installed base. Potato is where expansion concentrates.
Form:
Customer type segmentation separates industrial compounders seeking bulk liquid delivery from pharmaceutical finishers requiring precisely specified powder grades with documented particle size distribution.
- Powder:Spray-dried maltodextrin and dextrin for dry blending in nutritional supplements and pharmaceuticals. German pharmaceutical contract manufacturers specify tight moisture specifications below 5% for hygroscopic stability.
- Liquid:Glucose syrups and hydrolysates for beverage, confectionery, and fermentation applications. Tanker delivery to Central European food plants minimizes handling costs.
- Granular:Intermediate flow properties for specific tableting and extrusion processes.
- Gel:Pre-gelatinized starches for instant thickening applications.
Powder dominates installed base. Liquid is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in hydrolyzed starch tilt toward surplus in corn-processing economies and deficit in specialized pharmaceutical-grade markets. Germany and the United States anchor outbound trade in maltodextrin and glucose syrups, while Switzerland and Japan rely on qualified imports for excipient-grade specifications. Regulatory divergence between FDA GRAS pathways and EU REACH registration creates friction in cross-border product qualification.
Germany
Pharmaceutical contract manufacturing in Baden-Württemberg and Hesse drives excipient-grade maltodextrin consumption for direct-compression tablets. ECHA REACH registration mandates full compositional disclosure for modified starch imports, favoring domestic enzymatic hydrolysis capacity. The Emsland Group operates integrated potato starch processing in Lower Saxony, supplying pan-European drug manufacturers with EFSA-compliant traceability documentation.
United States
Corn wet-milling infrastructure across Iowa and Illinois generates glucose syrup volumes for beverage and confectionery compounders. FDA GRAS self-affirmation timelines extend market entry for novel enzymatic hydrolysis methods by 18-24 months. Cargill Incorporated leverages backward integration into dextrose feedstock production at Midwest facilities to secure consistent pharmaceutical-grade output.
Switzerland
Specialized pharmaceutical finishers in Basel and Zurich concentrate demand for USP-NF certified maltodextrin with tight dextrose equivalent ranges. Swissmedic guidance on elemental impurities in excipients drives specification tightening beyond standard food-grade parameters. Domestic production capacity remains limited, creating import dependence on German and Dutch qualified suppliers.
China
Starch processing clusters in Shandong and Jilin provinces supply glucose syrup volumes for domestic confectionery and fermentation applications. NMPA pharmaceutical excipient registration requirements are converging toward IPEC-PQG standards, forcing upgrades in maltodextrin purification capabilities. Export-oriented producers face EU Green Deal carbon intensity disclosure barriers in European pharmaceutical channels.
India
Generic drug manufacturing in Maharashtra and Gujarat generates accelerating demand for multi-functional excipients in tablet formulations. CDSCO's phased alignment with ICH Q3D guidelines on elemental impurities is compressing supplier qualification timelines for imported maltodextrin. Domestic corn wet-milling capacity expansion in Madhya Pradesh targets import substitution in standard-grade glucose syrups.
Hydrolyzed Starch Market Competitive Landscape
Concentration sits with diversified agricultural processors possessing captive starch supply and pharmaceutical qualification capabilities. Three to five integrated players control premium-tier excipient supply through backward integration into corn, potato, or tapioca processing. Competitive dynamics split between scale-driven commodity glucose syrup producers and specialization-focused maltodextrin manufacturers serving pharmaceutical and clinical nutrition segments. Capacity expansion in enzymatic hydrolysis and membrane filtration retrofitting represent the dominant competitive moves across the value chain.
Among diversified agricultural processors, Cargill Incorporated, Roquette Freres, and Tate & Lyle PLC occupy positions spanning commodity and specialty tiers. Cargill exemplifies the corn wet-milling archetype with integrated dextrose feedstock control. Roquette Freres represents the non-GMO and allergen-free specialization vector through pea and potato starch bases. Tate & Lyle PLC sits within the modified starch functionality tier, sustaining formulation partnerships with global food manufacturers. These three anchors illustrate how competitive positioning diverges by feedstock source and end-use certification depth.
| Leading Market Players |
|---|
| Cargill Incorporated |
| BASF |
| Archer Daniels Midland (ADM) |
| Roquette Freres |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Avebe |
| Agrana Group |
| Emsland Group |
| Others |
Supply & Pricing Matrix
EU REACH registration protocols gate both supplier qualification timelines and price differentiation across excipient-grade and food-grade tiers, compressing procurement options for pharmaceutical finishers while amplifying premiums for compliant enzymatic hydrolysis output. This regulatory architecture forces buyers to absorb documentation costs upstream or pay certified-supplier markups downstream.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure spanning premium pharmaceutical-grade, standard food-grade, and economy feed-grade tiers. Price differentiation rests on USP-NF certification depth and carbon intensity disclosure compliance, with German and Swiss pharmaceutical manufacturers showing lowest price sensitivity. Cost compression in standard food-grade maltodextrin is intensifying because of corn wet-milling overcapacity in the US Midwest, while enzymatic hydrolysis premiums hold firm on EFSA contaminant mitigation requirements.
Supply Chain Analysis
Germany and the United States anchor glucose syrup and maltodextrin production through integrated corn wet-milling and potato starch processing clusters. Raw material flows draw from Iowa corn belts, Lower Saxony potato cooperatives, and Ukrainian dextrose feedstock corridors. Single-source vulnerability concentrates in pharmaceutical-grade membrane filtration skids, where three-quarters of European capacity sits in German and Swiss installations. Distribution runs through tanker networks for liquid glucose syrups to beverage plants and bagged freight for powder maltodextrin to tablet manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical excipient multi-functionality is shifting this market toward platform-economics dynamics, where single-source qualification replaces multi-vendor procurement and EMA elemental impurity guidelines drive interoperability demands across generic drug manufacturing corridors.
For Market Incumbents: Fortify backward integration into enzymatic hydrolysis capacity and captive potato starch supply to defend against pea protein substitution in sports nutrition and emerging tapioca-based clean-label entrants. Prioritize USP-NF and EP certification investments in German production clusters where Swissmedic guidance tightens fastest. For New Entrants and Emerging Players: Anchor in Indian generic drug manufacturing corridors where CDSCO alignment with ICH Q3D guidelines compresses supplier qualification timelines for imported excipients. Target clinical nutrition and infant formula segments with non-GMO potato or tapioca base materials, leveraging EFSA traceability documentation as the go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane filtration-equipped maltodextrin production, favoring mid-scale enzymatic retrofitting over greenfield acid-hydrolysis capacity. Viable acquisition targets combine pharmaceutical-grade certification with Scope 3 carbon accounting capabilities. Watch EU F-Gas Regulation phase-down schedules as the signal for heat pump retrofitting capex cycles and pooled procurement consortium formation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Retrofitting | Reduces acrylamide formation risks while qualifying for EU Green Deal carbon intensity benchmarks. |
| Pharmaceutical-Grade Certification | USP-NF and EP compliance opens premium positioning in German and Swiss direct-compression tablet manufacturing. |
| Membrane Filtration Capacity Addition | Nanofiltration skids enable smaller-batch production with lower thermal energy input for high-purity maltodextrin. |
| Specialty Starch Diversification | Potato and tapioca bases offer non-GMO credentials for EFSA-compliant infant formula supply. |
| Backward Integration into Feedstock | Corn wet-milling control secures consistent dextrose equivalent supply for pharmaceutical-grade output. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at hydrolyzed starch processors, procurement leads at pharmaceutical contract manufacturers, and regulatory affairs directors at enzymatic technology suppliers; and secondary validation through ECHA REACH registration databases, FDA GRAS notification filings, EFSA novel food assessments, and customs trade flows for modified starch derivatives. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, food, and industrial applications.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, application grade tier, base crop source, and regional production hub, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines. Key inputs included EMA guideline evolution on elemental impurities, EU F-Gas Regulation phase-down schedules, and enzymatic hydrolysis adoption curves in German pharmaceutical corridors.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable corn wet-milling feedstock economics; material deviation in regulatory stringency or crop yield volatility would warrant model refresh. Recalibration cycles align with material shifts in EFSA contaminant guidance and pharmaceutical excipient consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Halal Ingredients Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Soy Lecithin Market
Ingredients
Cottonseed Oil Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Native Starch Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Bean Pasta Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Date Syrup Market
Ingredients
Hydrolyzed Egg Market