
 Marine Collagen Ingredients Market | 2026-2036
Marine Collagen Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Collagen Ingredients Market Analytics
A capital-intensity divergence between integrated hydrolysis operators and peptide specialists is rotating competitive advantage toward upstream asset control. Rousselot leverages its wet processing infrastructure across North Atlantic fishing ports. Gelita sustains multi-ton capacity through backward integration into cod skin supply chains. Vital Proteins differentiates via direct-to-consumer branding that commands premium shelf positioning in specialty retail.
Marine collagen ingredients comprise extracted and hydrolyzed structural proteins sourced from fish skins, scales, and bones, yielding peptides with molecular weights typically below 10 kDa for enhanced bioavailability in human absorption. These ingredients function as functional additives that improve tissue repair signaling, moisture retention, and protein fortification across consumer products. Fish skin-derived hydrolyzed collagen leads volume output due to established Nordic and North Pacific processing infrastructure, while nutraceutical applications capture the fastest expansion as ingestible beauty formats gain shelf space in functional retail. Powder formulations occupy the dominant share of production economics, though liquid shots are gaining traction in South Korean and Japanese convenience channels.
EFSA novel food classifications, FDA GRAS self-affirmation pathways, and REACH chemical safety registrations collectively govern market access for marine-derived protein ingredients in Europe and North America. These frameworks elevate testing burdens for new entrants while rewarding established suppliers with validated safety dossiers. Stakeholders must monitor evolving allergen labeling requirements for mollusk-derived collagens as regulatory scrutiny tightens across multiple jurisdictions.
Market Dynamics
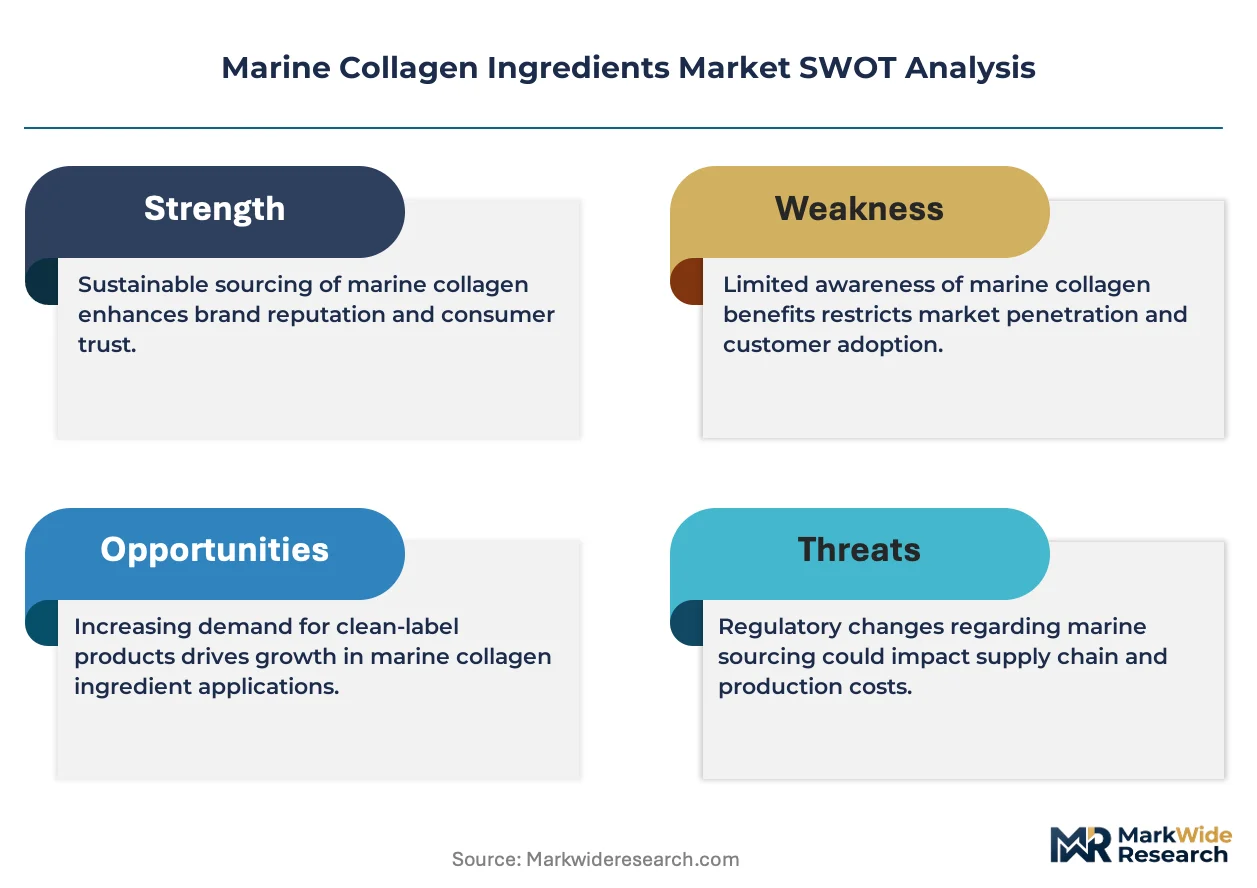
Upstream hydrolysis capacity concentration around North Atlantic fishing ports is fragmenting sourcing leverage, forcing downstream brands to secure multi-year offtake agreements or build captive wet-processing assets to stabilize peptide supply.
Growth Catalysts
- EFSA novel food pathways:Validated safety dossiers accelerate European market entry for hydrolyzed fish collagen, reducing time-to-shelf for new entrants with compliant documentation.
- Nutraceutical formulation expansion:Beauty-from-within supplements in South Korea are absorbing rising peptide volumes as MFDS regulatory clarity supports ingestible cosmetic claims.
- Cod skin hydrolysis infrastructure:Nordic processing clusters achieve economies of scale through continuous-flow enzymatic systems that lower unit costs for cosmetic-grade peptides.
Market Restraints
- Fishmeal price volatility:Competing demand from aquaculture feed markets elevates raw skin procurement costs during El Niño-driven catch disruptions.
- Single-source geography risk:North Atlantic fleet concentration exposes peptide supply to seasonal quota restrictions and warming-driven stock migration.
- Mollusk allergen labeling:EFSA tightening of crustacean-derived collagen disclosure requirements creates compliance friction for multi-source suppliers.
Strategic Opportunities
- Japanese convenience channel penetration:Liquid shot formats in Tokyo and Osaka retail are capturing commuter-driven consumption occasions underserved by powder sachets.
- REACH-registered suppliers:ECHA chemical safety dossier holders command premium positioning as EU clean-label standards elevate traceability requirements.
- Enzymatic hydrolysis-AI process control convergence:Real-time molecular weight monitoring is enabling batch-to-batch consistency that satisfies pharmaceutical-grade specifications.
Industry Challenges
- Marine biochemistry specialization gap:Shortage of process engineers with combined enzymology and fisheries science training constrains facility expansion timelines.
- GRAS self-affirmation documentation:FDA pathway complexity delays US market entry for novel peptide fractions without established safety literature.
- Legacy ERP integration:Wet-processing facilities struggle to connect batch-level quality data to downstream customer traceability portals.
Report Scope
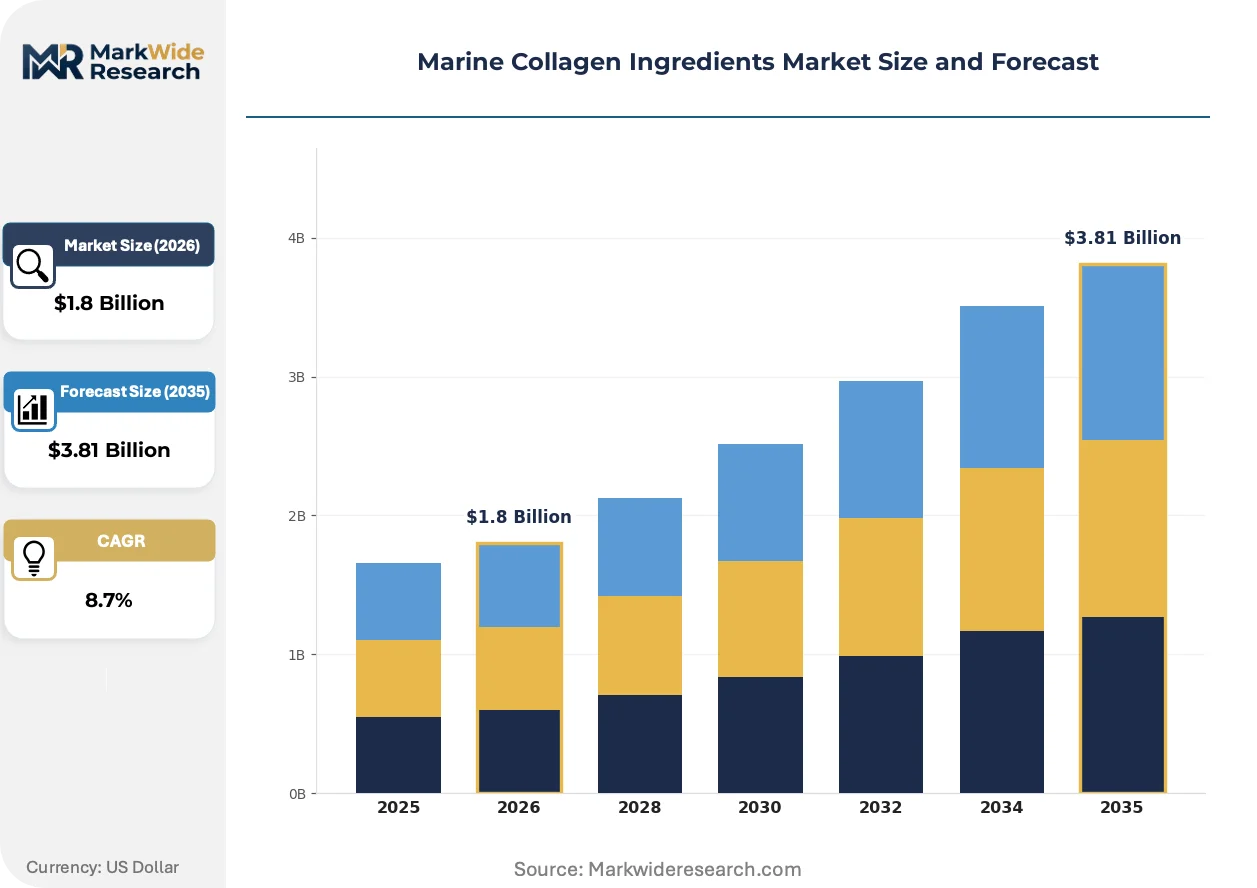
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Collagen Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Peptides, Gelatin, Powders Application: Healthcare, Cosmetics, Nutraceuticals, Food & Beverage Source: Fish Skin, Fish Scales, Shellfish, Others Form: Liquid, Powder, Capsules, Tablets |
| Companies Covered | Rousselot, Nitta Gelatin, Weishardt, Gelita, Seagarden, Vital Proteins, Ashland, Norland Products, PB Gelatins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Collagen Ingredients Market Evolving Landscape
Enzymatic specificity advances and regulatory data requirements are compressing the viable supplier base while elevating technical barriers to peptide standardization across cosmetic and nutraceutical end-uses.
Precision enzymatic hydrolysis using substrate-specific proteases is decomposing the traditional acid-hydrolysis dominance in industrial collagen processing. Cosmetic formulators in France and Germany are adopting these biocatalytic routes to achieve sub-3 kDa peptide fractions with reproducible bioactivity profiles. The technology is decomposing cost advantages held by legacy acid-based operators who lack enzymology R&D capabilities.
REACH chemical safety registration deadlines for protein hydrolysates are compressing formulation choices available to European cosmetic brands. ECHA data requirements for skin sensitization and aquatic toxicity are disqualifying smaller importers lacking toxicology dossier resources. Personal care contract manufacturers in Italy and Spain are consolidating supplier panels to pre-registered peptide sources to avoid formulation disruption.
Direct-to-consumer subscription models are displacing traditional wholesale distribution for premium marine collagen peptides. South Korean and Japanese buyers are migrating toward auto-replenishment platforms that bundle personalized dosage guidance with loyalty incentives. This channel shift concentrates customer data ownership with vertically integrated brands and weakens conventional retail pharmacy leverage in Seoul and Tokyo metropolitan markets.
Marine Collagen Ingredients Market Segmentation
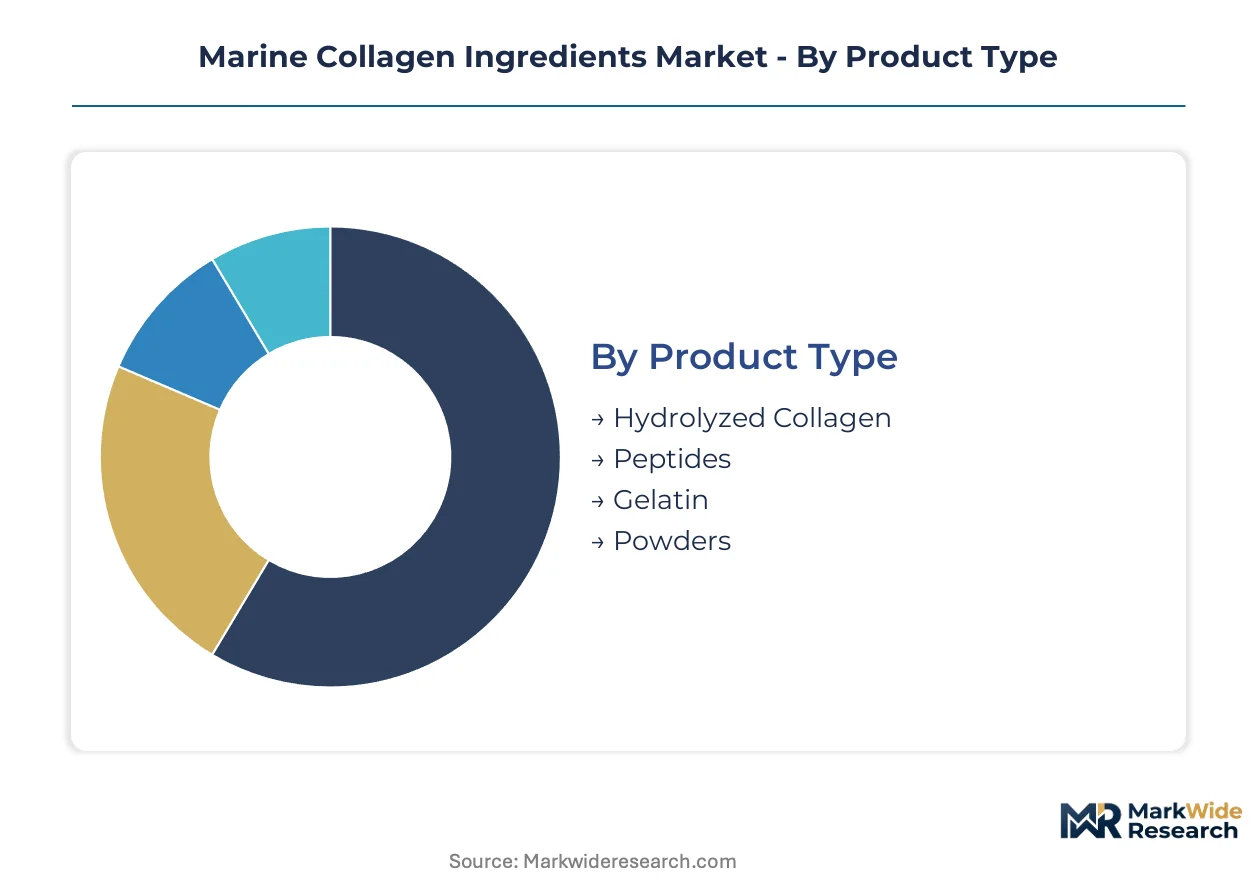
Marine collagen ingredient economics fragment sharply across molecular weight specifications, hydrolysis intensity, and end-use certification requirements. Margin capture varies by threefold between commodity gelatin and pharmaceutical-grade peptide fractions, making segment selection decisive for supplier positioning.
Product Type:
Premium pricing concentrates in low-molecular-weight peptide fractions below 3 kDa, where enzymatic specificity commands cosmetic and nutraceutical premiums over commodity hydrolysates.
- Hydrolyzed Collagen:Acid or enzymatically treated proteins with molecular weights typically spanning 10-50 kDa, serving bulk fortification applications in functional foods and lower-tier cosmetics. Nordic continuous-flow processors dominate volume economics through North Atlantic cod skin supply chains, though price compression from Asian acid-hydrolysis entrants is eroding margin stability.
- Peptides:Sub-10 kDa fractions produced through substrate-specific protease treatment, enabling bioactive signaling claims in ingestible beauty and wound care formulations. South Korean MFDS-compliant peptide suppliers capture the steepest expansion trajectory as Seoul-based nutraceutical brands scale beauty-from-within product lines.
- Gelatin:Partially hydrolyzed collagen with gelling properties, primarily serving food texturization and capsule shell applications where thermal reversibility is functionally required.
- Powders:Spray-dried hydrolysate formats dominating logistics economics and shelf stability across mass-market distribution channels.
The dominant share belongs to hydrolyzed collagen, while peptides are closing the gap fastest.
Application:
End-use diversification is redistributing volume toward ingestible formats as topical cosmetic growth moderates in mature European markets.
- Healthcare:Wound dressing matrices and surgical sealants requiring endotoxin-controlled peptide fractions with documented biocompatibility profiles. German medical device manufacturers source through EMA-registered suppliers with validated ISO 13485 quality systems.
- Cosmetics:Topical moisturization and anti-aging claims driving demand for sub-5 kDa fractions with demonstrated fibroblast stimulation data. French and German formulators are consolidating supplier panels to REACH-registered sources ahead of ECHA registration deadlines.
- Nutraceuticals:Ingestible beauty supplements in powder sachets and liquid shots, with South Korean convenience retail absorbing rising peptide volumes through auto-replenishment platforms.
- Food & Beverage:Protein fortification in functional beverages and sports nutrition, where neutral flavor profiles and cold-solubility specifications determine sourcing decisions.
Nutraceutical applications are expanding most quickly, though cosmetics retain the highest absolute margin per kilogram.
Source:
Raw material provenance governs allergen labeling obligations and sustainability credentialing intensity across supply contracts.
- Fish Skin:Cod and pollock skins from North Atlantic fisheries constitute the primary industrial feedstock, with Nordic processing clusters achieving scale economies through continuous enzymatic systems. EFSA tightening of crustacean-derived collagen disclosure requirements is elevating preference for finfish-only sourcing.
- Fish Scales:Tilapia and pangasius scale processing concentrated in Southeast Asian aquaculture byproduct recovery operations, serving cost-sensitive cosmetic markets with higher mineral content tolerances.
- Shellfish:Crab and shrimp-derived collagens requiring explicit mollusk allergen labeling under evolving EFSA and FDA frameworks, constraining formulation flexibility for multi-source suppliers.
- Others:Emerging jellyfish and squid cartilage sources, primarily experimental at pilot scale with unvalidated regulatory pathways for novel food approval.
Fish skin dominates procurement volumes, while fish scales are gaining share fastest through Asian aquaculture integration.
Form:
Dosage format selection reflects channel economics and consumption occasion targeting across metropolitan convenience retail versus pharmacy and e-commerce.
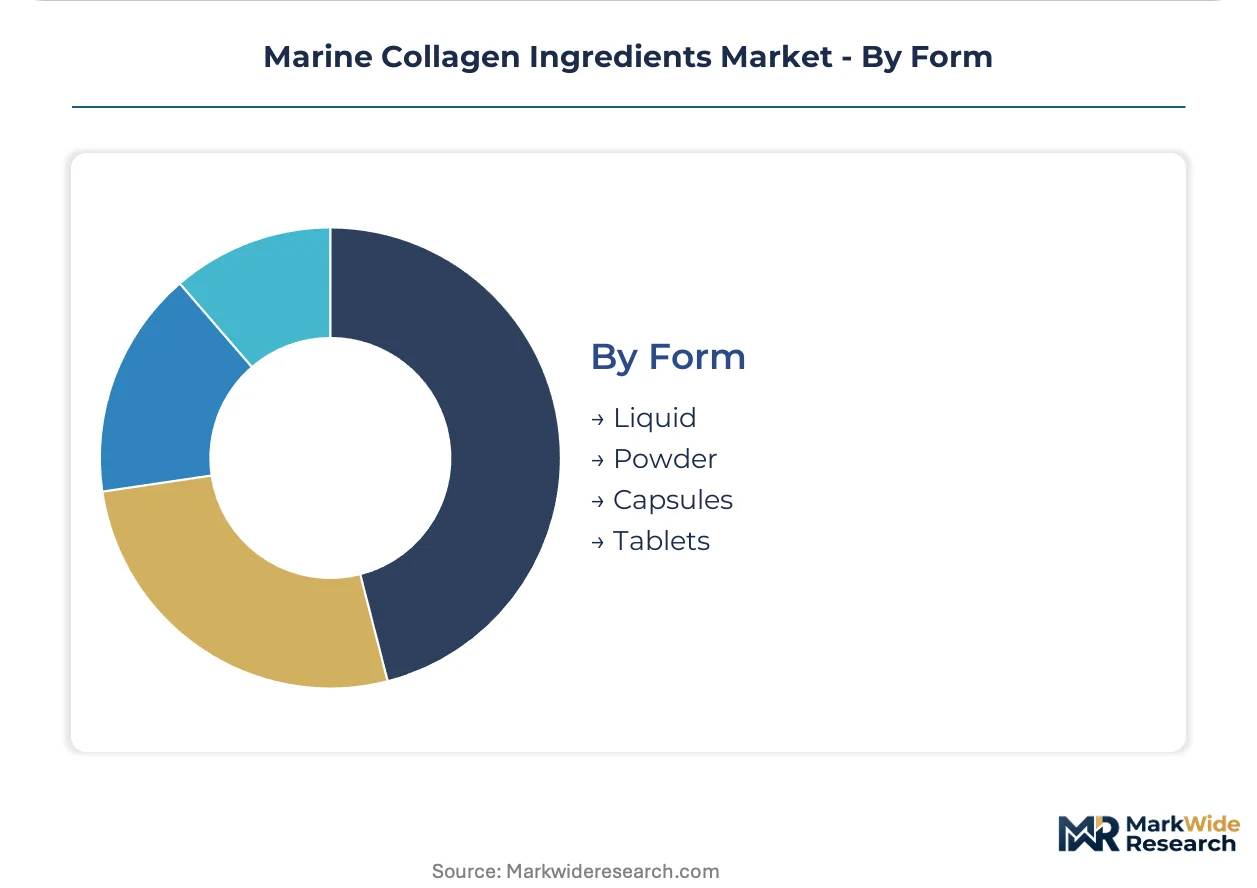
- Liquid:Ready-to-drink shots capturing commuter-driven consumption in Tokyo and Osaka convenience stores, with premium positioning enabled by single-serve portability and immediate consumption rituals.
- Powder:Bulk formats dominating production economics through lower packaging costs and extended shelf stability, preferred by functional food manufacturers and subscription-based direct-to-consumer brands.
- Capsules:Hard-shell gelatin or HPMC encapsulation for precise dosing in supplement protocols, where swallowability and odor masking support compliance-oriented positioning.
- Tablets:Compressed formats with binding agents, occupying niche positioning in pharmacy channels where tablet familiarity supports consumer trial conversion.
Powder formulations command the dominant production share, though liquid formats are climbing the fastest through Japanese and South Korean convenience channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine collagen peptide prices in South Korea command 40-60% premiums over equivalent grades in Vietnam, reflecting divergent regulatory compliance costs and channel positioning power. This asymmetry is reshaping supplier allocation decisions across the Pacific basin.
South Korea
Seoul-based nutraceutical brands are scaling beauty-from-within product lines through auto-replenishment platforms that bundle personalized dosing guidance. MFDS regulatory clarity on ingestible cosmetic claims has compressed approval timelines for novel peptide formats. The Seoul Capital Area concentrates contract manufacturing capacity for liquid shot formulations targeting convenience retail.
Japan
Tokyo and Osaka metropolitan markets absorb rising volumes of single-serve liquid collagen shots designed for commuter consumption rituals. METI guidance on functional food labeling provides a pathway for bioactive peptide claims that European suppliers struggle to match. The Kansai region hosts specialized enzymatic hydrolysis facilities serving pharmaceutical-grade specifications.
Germany
EMA-registered suppliers with validated ISO 13485 quality systems dominate procurement for medical device manufacturers requiring endotoxin-controlled peptide fractions. REACH chemical safety registration deadlines are compressing formulation choices available to cosmetic brands. The North Rhine-Westphalia cluster integrates wet-processing infrastructure with ECHA dossier management capabilities.
United States
FDA GRAS self-affirmation pathways govern market access for novel peptide fractions without established safety literature. Direct-to-consumer subscription models are displacing traditional wholesale distribution for premium marine collagen peptides. The Pacific Northwest maintains processing infrastructure tied to North Pacific fishing port supply chains.
France
Cosmetic formulators in Paris and Lyon are consolidating supplier panels to REACH-registered sources ahead of ECHA registration deadlines. ANSM oversight of cosmetic ingredient safety elevates preference for pre-validated toxicology dossiers. The Île-de-France region concentrates R&D activity for sub-3 kDa peptide fractions with reproducible bioactivity profiles.
Marine Collagen Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic specificity specialists commanding cosmetic premiums while acid-hydrolysis operators defend volume positions in functional foods. The vendor base fragments across integrated fishing-port processors and downstream peptide purification specialists. Three archetypes dominate: Nordic continuous-flow operators with captive cod skin supply, Asian scale processors leveraging aquaculture byproduct recovery, and direct-to-consumer brands capturing customer data through subscription platforms. Competitive moves concentrate on backward integration into wet-processing assets and multi-year offtake agreements that lock in peptide supply.
Among integrated hydrolysis operators, Rousselot and Gelita exemplify upstream asset control strategies that stabilize raw material access through North Atlantic fishing port infrastructure. Nitta Gelatin occupies a position within the Asian scale-processing tier, representing the cost-competitive archetype that serves functional food fortification markets. These three anchors illustrate the capital-intensity divergence rotating competitive advantage toward facilities with validated regulatory dossiers and continuous-flow enzymatic capabilities.
| Leading Market Players |
|---|
| Rousselot |
| Nitta Gelatin |
| Weishardt |
| Gelita |
| Seagarden |
| Vital Proteins |
| Ashland |
| Norland Products |
| PB Gelatins |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements with North Atlantic cod skin processors lock in peptide supply visibility for downstream nutraceutical brands while insulating contract holders from spot-market volatility during El Niño-driven catch disruptions. These structures concentrate pricing power among integrated hydrolysis operators with captive wet-processing assets.
Pricing Analysis
Configured-to-order peptide fractions command 40-60% premiums over standard hydrolysate grades, with sub-3 kDa cosmetic specifications and MFDS-compliant nutraceutical certifications driving the widest spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by molecular weight precision and regulatory dossier completeness. Price compression runs through commodity acid-hydrolysis tiers as Asian scale processors expand cod skin processing capacity. Functional food manufacturers exhibit highest price sensitivity, while Seoul-based beauty-from-within brands absorb premiums for validated bioactivity data.
Supply Chain Analysis
Strategic stockpiling of dried fish skins through Nordic continuous-flow processors dominates inventory strategy, with downstream brands maintaining 60-90 day peptide reserves against seasonal quota restrictions. Supply concentrates in Norway, Iceland, and Vietnam, with raw material flows drawing from North Atlantic cod fisheries and Southeast Asian tilapia aquaculture byproduct recovery. Single-source geography risk in North Atlantic fleet exposure creates vulnerability to warming-driven stock migration. Distribution runs through specialized ingredient distributors serving cosmetic contract manufacturers in France and Germany, plus direct-to-consumer subscription platforms in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision enzymatic hydrolysis convergence with AI process control is disrupting cost structures and compressing viable supplier bases, creating asymmetric returns for first-movers with validated ECHA dossiers.
For Market Incumbents: Fortify upstream asset control through backward integration into North Atlantic fishing port wet-processing infrastructure or multi-year offtake agreements that lock in cod skin supply. Invest in continuous-flow enzymatic systems to defend margin position against Asian acid-hydrolysis entrants eroding commodity tier pricing. Prioritize REACH registration maintenance and sub-3 kDa peptide R&D to sustain cosmetic-grade premium capture. For New Entrants and Emerging Players: Liquid shot formulation services for Japanese convenience retail represent a service-layer gap where incumbents under-serve commuter-driven consumption rituals with powder-centric portfolios. Target Tokyo and Osaka metropolitan markets through single-serve portability innovations and METI-compliant functional food labeling pathways. Pursue white-label manufacturing partnerships with Seoul-based subscription platforms to bypass capital-intensive hydrolysis infrastructure requirements. For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic specificity specialists with validated EFSA novel food dossiers and captive North Atlantic supply chains, positioned for 5-10 year regulatory moat durability. Monitor ECHA registration deadline compliance rates as an inflection signal for supplier consolidation velocity and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wet-Processing Assets | Captive cod skin supply from North Atlantic fishing ports stabilizes peptide input costs against El Niño volatility. |
| REACH Chemical Safety Registration | ECHA dossier holders command premium positioning as EU clean-label standards elevate traceability requirements. |
| Enzymatic Hydrolysis-AI Process Control Convergence | Real-time molecular weight monitoring enables pharmaceutical-grade batch consistency that acid-based operators cannot match. |
| Direct-to-Consumer Subscription Platform Launch | Auto-replenishment models in Seoul concentrate customer data ownership and weaken conventional pharmacy channel leverage. |
| MFDS-Compliant Peptide Format Development | Regulatory clarity on ingestible cosmetic claims compresses approval timelines for novel beauty-from-within products. |
Research Methodology
Initial hypotheses were tested against primary input from enzymatic hydrolysis process engineers, nutraceutical brand product development directors, cosmetic contract manufacturing procurement leads, and EFSA regulatory affairs specialists, then refined through secondary validation. Trade data from Norwegian Seafood Council export statistics, ECHA registration databases, MFDS cosmetic ingredient filings, and South Korean customs peptide import records anchored quantitative sizing. Bottom-up facility capacity estimates triangulated against top-down end-use consumption models across healthcare, cosmetics, nutraceuticals, and food applications.
Variance decomposition across molecular weight specifications, hydrolysis intensity tiers, and geographic regulatory clusters structured the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, application, source material, and form factor, with CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions. Industry-specific inputs incorporated enzymatic specificity adoption curves, EFSA novel food approval velocity, and North Atlantic cod quota allocation patterns.
Material uncertainties — El Niño frequency intensification, EFSA mollusk allergen labeling tightening, and enzymology talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and peptide bioavailability validation standards. Revision becomes warranted when North Atlantic cod biomass assessments cross sustainability thresholds or ECHA registration rejection rates exceed historical baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Fermented Ingredients Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Birch Sap Market
Ingredients
Hops Derivative Market
Ingredients
Soluble Fibers Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Millet Protein Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
MCT Oil Market
Ingredients
Cacao Bean Market
Ingredients
Global Apricot Oil Market
Ingredients
Vegetable Fats Market
Ingredients
Vegan Ingredients Market
Ingredients
Carob Protein Market