
 North America Soy Protein Concentrate Market | 2026-2036
North America Soy Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soy Protein Concentrate Market Analysis
Ingredient customization revenue is narrowing as commodity-grade concentrate margins compress against functional and organic variants. Archer Daniels Midland Company leverages its Midwest crushing network to sustain integrated feedstock costs. Cargill competes through specialty protein fractionation capabilities that serve meat alternative formulators. CHS Inc anchors its position through farmer-owned cooperative sourcing that controls origination logistics.
Soy protein concentrate denotes a defatted soybean meal processed to achieve protein content between 65% and 90% on a dry-weight basis, primarily serving as a functional binder and emulsifier in processed foods and nutritional products. Non-GMO and organic product types command premium positioning as clean-label procurement standards tighten across North American food manufacturing. Meat alternatives and dairy alternatives represent the fastest-growing application segments, while protein supplements retain mature volume leadership with steadier margin profiles.
The FDA oversees protein content claims and allergen labeling requirements that directly influence concentrate specification demand, while USDA organic certification governs premium tier market access. Health Canada and the Canadian Food Inspection Agency enforce parallel standards that shape cross-border product formulation strategies. Stakeholders must monitor evolving plant-based protein nomenclature rules and state-level labeling disputes that could redirect procurement toward certified non-GMO supply chains.
Market Dynamics
Midwest soybean crushing capacity concentration is restructuring procurement geography, binding protein concentrate supply to origination logistics and compressing delivered cost differentials between cooperative and merchant supply chains.
Growth Catalysts
- Plant-based meat formulation:Meat alternative processors in the United States are expanding soy protein concentrate volumes as clean-label emulsifier demand intensifies in refrigerated and frozen analog categories.
- FDA labeling guidance:Updated FDA plant-based protein nomenclature rules are pressuring manufacturers to reformulate with higher-protein concentrates to substantiate content claims.
- Organic certification pipeline:USDA organic certification expansion across Canadian prairie soybean acreage is diversifying non-GMO concentrate origination beyond U.S. Midwest dominance.
Market Restraints
- Input cost volatility:Soybean oil crush spread compression exposes concentrate processors to margin squeeze when vegetable oil prices retreat.
- Supply concentration risk:Iowa and Illinois crushing facility clustering creates origination dependency on specific rail and river logistics corridors.
- Regulatory friction:State-level labeling disputes over plant-based meat terminology in Missouri and Arkansas create interstate commerce formulation complexity.
Strategic Opportunities
- Prairie province expansion:Manitoba and Saskatchewan organic soybean acreage growth offers Canadian concentrate processors underutilized origination capacity.
- Sports nutrition application:Ready-to-drink protein beverage formulators represent emerging concentrate demand beyond traditional bakery and meat processing.
- Precision fermentation convergence:Hybrid formulations combining soy protein concentrate with microbial protein are opening functional texture innovation in dairy alternatives.
Industry Challenges
- Clean-label certification timeline:Non-GMO Project verification and organic transition protocols extend supplier qualification cycles by eighteen to thirty-six months.
- Fractionation capex intensity:Specialty protein isolation equipment requires capital deployment that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soy Protein Concentrate Market |
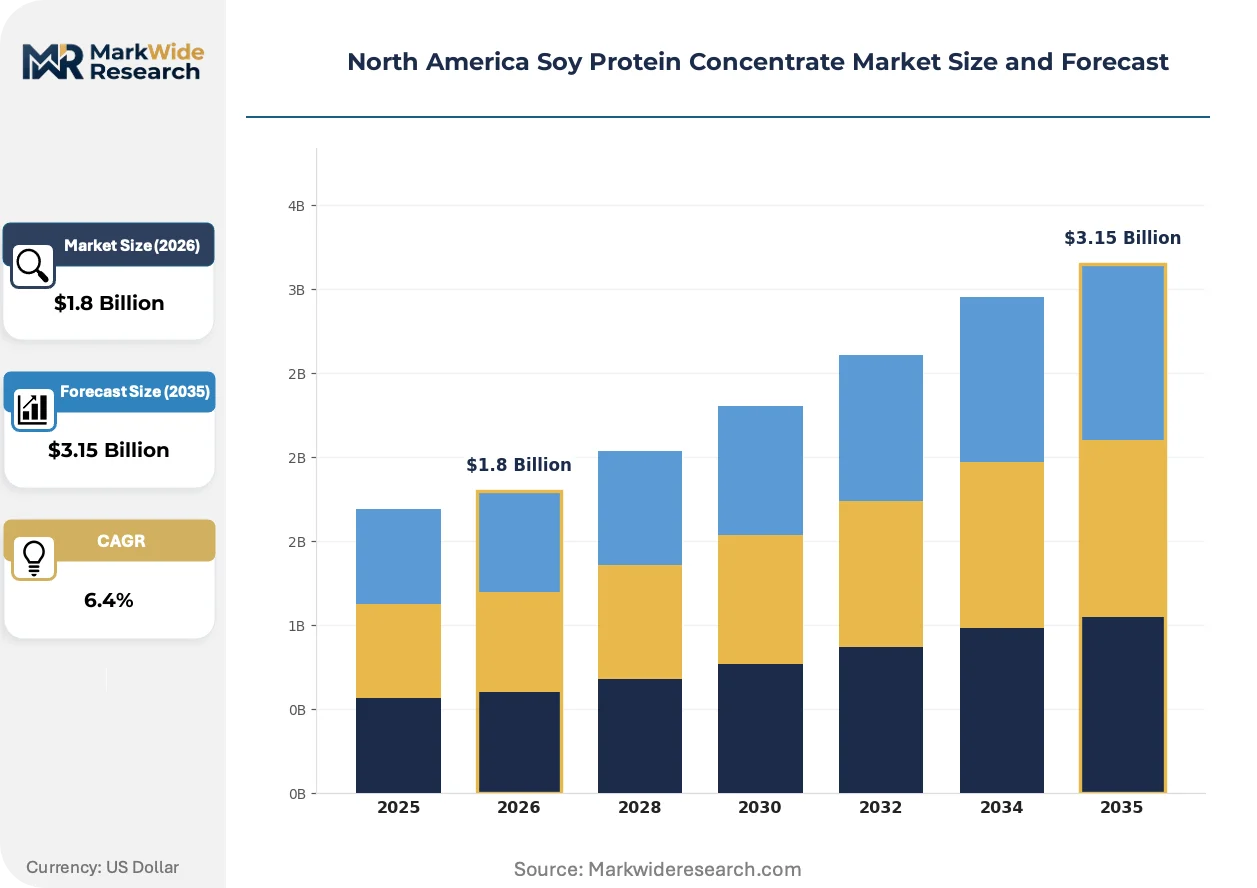
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-GMO, Organic, Isolated, Textured Application: Beverages, Dairy Alternatives, Meat Alternatives, Protein Supplements End User: Food Manufacturers, Dietary Supplement Producers, Foodservice Providers, Retailers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Wilmar International, The Scoular Company, Archer Daniels Midland Company, Bunge Limited, Food Chem International Corporation, Cargill, Kerry Group, CHS Inc, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soy Protein Concentrate Market Emerging Trajectories
Functional specification migration is compressing commodity-grade concentrate viability while elevating fractionation capabilities and organic traceability systems as competitive differentiators.
Enzymatic dehulling and low-temperature desolventizing is migrating from niche organic processors to mainstream Midwest facilities. Meat alternative formulators are demanding these processes to preserve protein solubility and emulsification capacity. This technology diffusion is compressing price premiums between commodity and functional-grade concentrates.
Health Canada updated plant-based protein labeling requirements are tightening protein quality scoring methods for nutrition claims. Canadian processors must reformulate to higher PDCAAS thresholds to maintain positioning in cross-border retail channels. U.S. exporters face parallel compliance burden when shipping concentrate into Canadian protein supplement manufacturing.
Direct contracting between meat alternative brands and farmer cooperatives is displacing spot market procurement in the upper Midwest. CHS Inc and similar cooperative structures are capturing volume commitments that bypass traditional merchant intermediaries. This channel compression is most visible in Illinois and Indiana, where crushing capacity sits adjacent to formulation facilities.
North America Soy Protein Concentrate Market Segmentation
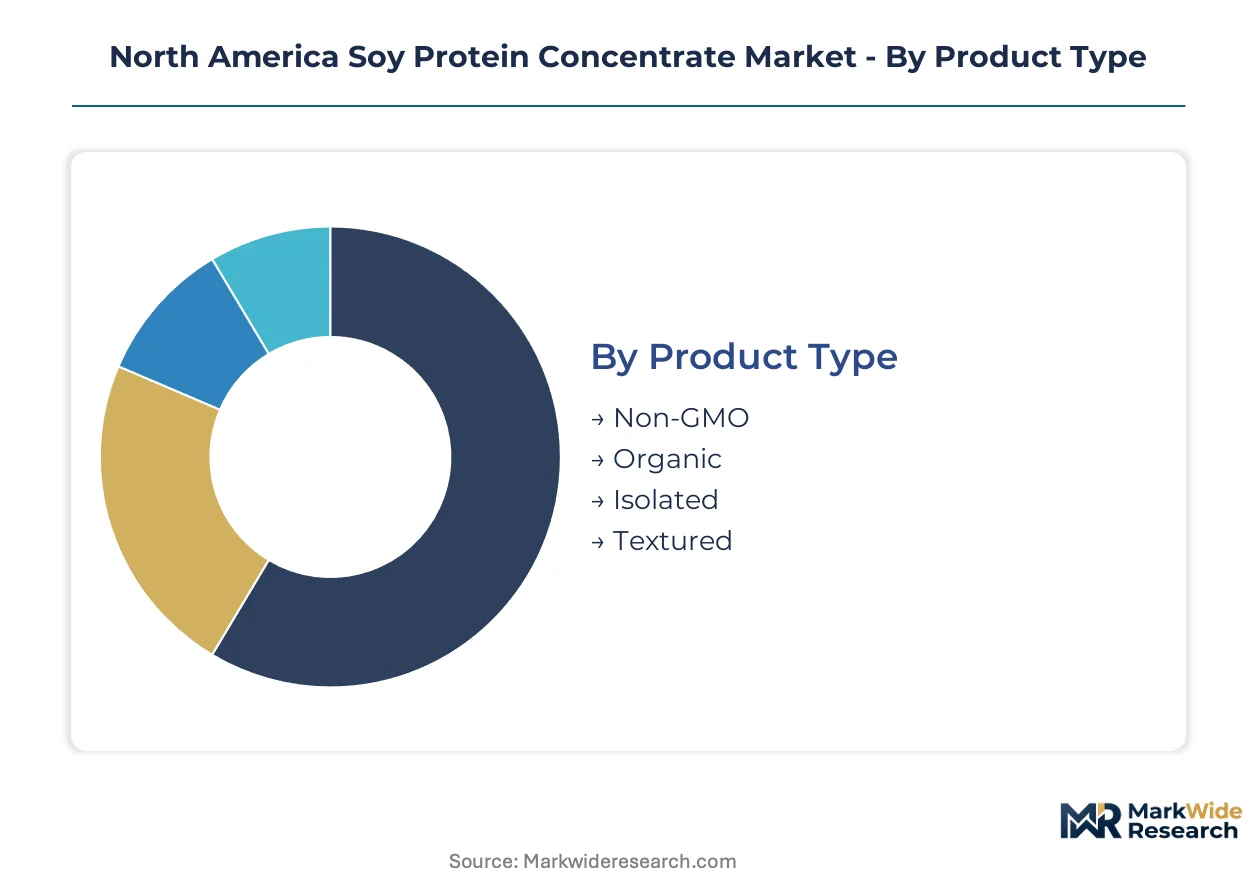
Soy protein concentrate procurement patterns diverge sharply across specification tiers, with organic and functional grades commanding extended qualification cycles while commodity volumes turn on crush economics. Understanding these segment dynamics reveals where margin compression concentrates and where pricing power persists.
Product Type:
Cycle times stretch longest for certified organic concentrates, where transition protocols and verification audits extend supplier onboarding to thirty-six months, while commodity-grade non-GMO product rotates quarterly with crush spreads.
- Non-GMO:Defatted meal processed to 65-70% protein content without genetic modification, serving as the volume baseline for processed food manufacturers. Clean-label procurement standards at U.S. Midwest meat alternative facilities are tightening specification tolerances for this grade.
- Organic:Certified organic soybeans processed through enzymatic dehulling and low-temperature desolventizing to preserve protein solubility. Prairie province acreage expansion in Manitoba and Saskatchewan is diversifying origination beyond U.S. Midwest dominance for this premium tier.
- Isolated:Higher-protein fraction achieving 90% concentration through additional processing steps. Sports nutrition formulators in the ready-to-drink beverage segment are pulling this specification for PDCAAS compliance.
- Textured:Extruded concentrate with fibrous structure replicating meat mouthfeel. Meat alternative processors in refrigerated and frozen analog categories specify this grade for emulsification capacity.
Non-GMO anchors the volume base while organic gains share at the steepest rate.
Application:
Cost tiers separate sharply here, with protein supplements and beverages competing on per-serving economics while meat and dairy alternatives absorb premium functional grades for texture performance.
- Meat Alternatives:Refrigerated and frozen plant-based analogs requiring emulsification and water-binding functionality. FDA labeling guidance on protein content claims is pressuring formulators toward higher-concentration specifications in this segment.
- Dairy Alternatives:Hybrid formulations combining soy concentrate with microbial protein for functional texture innovation. Precision fermentation convergence is opening new specification requirements for emulsion stability in this application.
- Protein Supplements:Mature volume category with steadier margin profiles and established supply contracts. Health Canada updated protein quality scoring methods are forcing reformulation to higher PDCAAS thresholds for cross-border positioning.
- Beverages:Ready-to-drink protein beverages demanding high solubility and neutral flavor profiles. This application represents emerging concentrate demand beyond traditional bakery and meat processing channels.
Protein supplements retain the largest shipment volumes while meat alternatives climb the fastest.
End User:
Customer type determines contract structure, with food manufacturers locking in multi-year supply agreements while foodservice procurement remains spot-market responsive.
- Food Manufacturers:Processed food and plant-based meat producers with integrated R&D specification control. Direct contracting with farmer cooperatives is displacing merchant intermediaries for this customer type in Illinois and Indiana.
- Dietary Supplement Producers:Brands requiring certified organic and non-GMO verification for premium positioning. Clean-label certification timelines extend supplier qualification cycles by eighteen to thirty-six months for this segment.
- Foodservice Providers:Institutional and chain restaurant procurement with cost-driven specification flexibility.
- Retailers:Private-label program managers balancing shelf-price positioning with clean-label requirements.
Food manufacturers dominate contract volume while dietary supplement producers expand specification premiums most aggressively.
Distribution Channel:
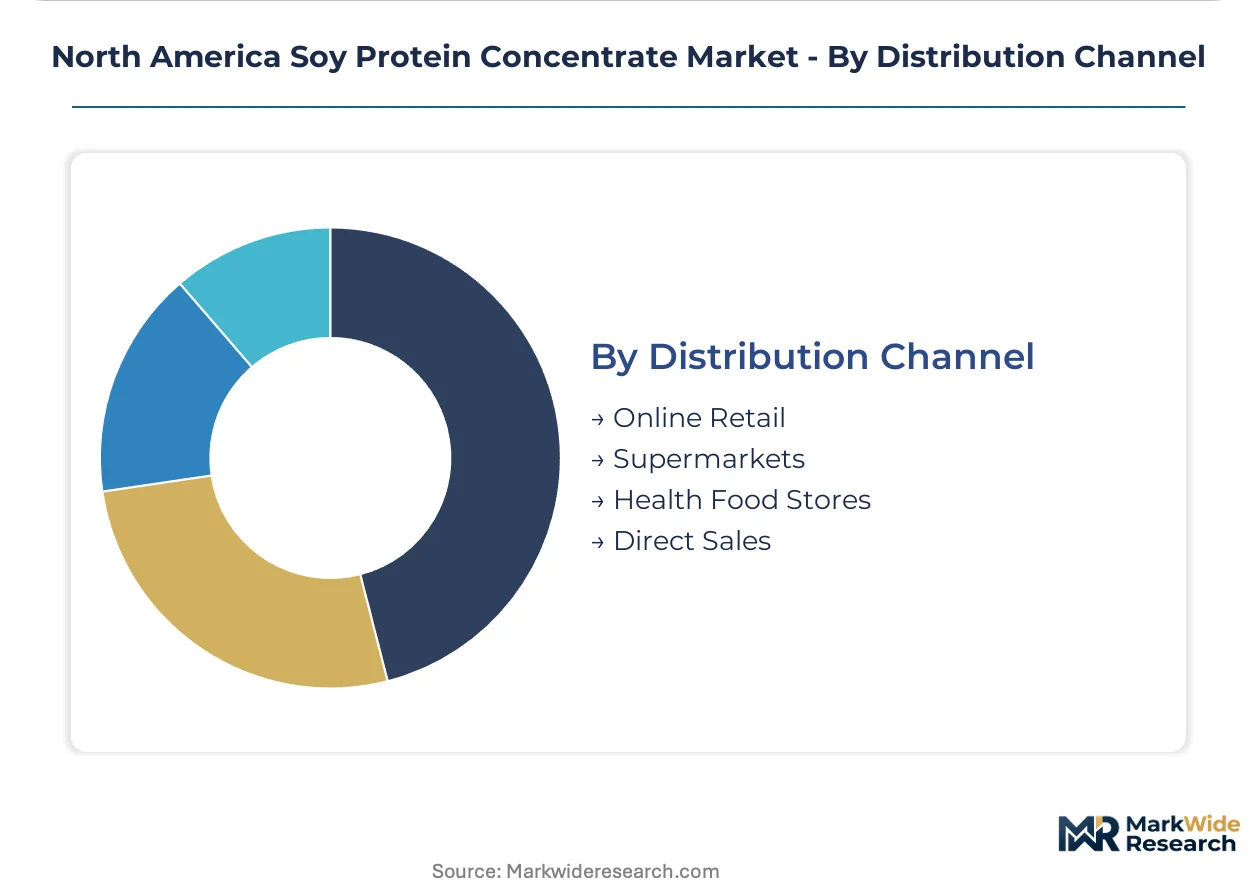
Supply concentration in Iowa and Illinois crushing corridors shapes channel economics, with direct sales capturing origination-adjacent volume while retail channels serve dispersed formulation demand.
- Direct Sales:Volume commitments between meat alternative brands and farmer cooperatives bypassing traditional merchant intermediaries. CHS Inc and similar cooperative structures are capturing this channel in the upper Midwest.
- Online Retail:E-commerce platforms serving small-batch formulators and regional supplement brands with fragmented order patterns.
- Supermarkets:Mass retail private-label procurement with standardized commodity specifications.
- Health Food Stores:Specialty retail demanding organic and non-GMO Project verification for consumer-facing positioning.
Direct sales command the largest shipment volumes while online retail expands access fastest for emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest soybean buyers absorb price swings with limited elasticity, while coastal meat-alternative formulators face sharper specification premiums that compress margin tolerance.
United States
Midwest crushing clusters in Iowa and Illinois bind concentrate supply to origination logistics, with meat-alternative processors in Chicago and Minneapolis expanding procurement volumes. FDA updated plant-based protein nomenclature rules pressure formulators toward higher-protein concentrates to substantiate content claims. The Prairie Lakes region anchors the highest crushing density, where CHS Inc and cooperative structures capture direct contracting volume that bypasses merchant intermediaries.
Canada
Prairie province organic soybean acreage in Manitoba and Saskatchewan diversifies non-GMO concentrate origination beyond U.S. Midwest dominance. Health Canada and the Canadian Food Inspection Agency enforce protein quality scoring methods that tighten PDCAAS thresholds for cross-border retail positioning. Crushing capacity concentrates in southern Manitoba near Winnipeg, where processors serve both domestic meat-alternative facilities and export demand into U.S. Great Lakes formulation plants.
Mexico
Import-dependent protein concentrate demand concentrates in central Mexico food manufacturing corridors, with processors sourcing primarily from U.S. Gulf Coast export terminals. Mexican regulators align with FDA-adjacent standards for plant-based protein labeling, creating compliance continuity for cross-border suppliers. The Bajío region around Guanajuato hosts expanding processed food and meat-alternative production that pulls concentrate through Laredo-Nuevo Laredo logistics corridors.
North America Soy Protein Concentrate Market Vendor Landscape
Capability concentration sits with specialty fractionation operators; scale advantage sits with integrated crush-and-process networks. The market structures around three tiers: multinational agribusinesses with captive soybean origination, mid-scale regional processors with organic certification pipelines, and commodity merchants with spot-market flexibility. Dominant competitive moves include direct contracting between brands and farmer cooperatives that displaces traditional merchant channels, and enzymatic processing technology licensing that compresses functional-grade price premiums.
Among integrated agribusinesses, Archer Daniels Midland Company and Cargill occupy positions that exemplify the scale-chemistry interface, while CHS Inc represents the cooperative-origination archetype with farmer-owned logistics control. These three entities anchor distinct competitive vectors: crush-network density, specialty protein fractionation, and origination-adjacent procurement structures.
| Leading Market Players |
|---|
| Wilmar International |
| The Scoular Company |
| Archer Daniels Midland Company |
| Bunge Limited |
| Food Chem International Corporation |
| Cargill |
| Kerry Group |
| CHS Inc |
| DuPont de Nemours |
| Others |
Supply Flow & Price Mechanics
Underutilized crushing capacity in Manitoba and Saskatchewan is compressing delivered cost differentials between Prairie province processors and U.S. Midwest cooperatives, forcing Iowa and Illinois facilities to absorb margin squeeze through longer-term contract structures. This utilization gap shapes both supplier qualification timelines and buyer procurement posture across the North American concentrate market.
Pricing Analysis
Long-term offtake contracts between meat alternative brands and farmer cooperatives now dominate volume procurement in Illinois and Indiana, displacing quarterly spot rotations that once set price benchmarks. Three-tier pricing structure across organic, functional-grade, and commodity concentrates separates certified supply from crush-spot economics, with organic certification extending supplier onboarding to thirty-six months. Pricing pressure stems from soybean oil crush spread compression when vegetable oil prices retreat, squeezing processor margins. Food manufacturers with integrated R&D specification control exhibit lowest price sensitivity, while foodservice providers remain most responsive to commodity-grade spot movements.
Supply Chain Analysis
Export-control regimes on enzymatic dehulling equipment from European suppliers limit technology diffusion to North American organic processors, constraining functional-grade capacity expansion. Supply concentrates in the U.S. Midwest—Iowa, Illinois, and Indiana—while Canadian Prairie provinces diversify origination through Manitoba and Saskatchewan organic acreage growth. Raw material dependencies center on defatted soybean meal, hexane solvent supply, and rail logistics capacity along Mississippi River corridors. Single-source vulnerability concentrates in Iowa-Illinois crushing clusters dependent on specific rail and river logistics corridors. Distribution runs through direct sales channels capturing origination-adjacent volume, with merchant intermediaries serving dispersed coastal formulation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification and technical service layers attached to organic and functional-grade concentrates are expanding faster than commodity volume, creating recurring-revenue opportunities that outpace hardware-equipment sales in supplier economics.
For Market Incumbents: Entrench position through enzymatic processing technology licensing that compresses functional-grade price premiums and locks in formulation partnerships. Expand backward integration into Prairie province organic soybean origination to diversify beyond Midwest supply concentration. Defend against precision fermentation substitutes by embedding soy concentrate in hybrid dairy alternative formulations through exclusive R&D collaboration structures. For New Entrants and Emerging Players: Prairie province organic processing capacity in Manitoba represents the most penetrable entry point, with underutilized crushing infrastructure and Health Canada compliance pathways offering faster qualification than U.S. FDA timelines. Ready-to-drink protein beverage formulators seeking high-solubility concentrates constitute a white-space application with limited incumbent specialization. Pursue direct contracting with regional supplement brands through e-commerce platform relationships that bypass established cooperative channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic fractionation equipment, favoring acquisition of mid-scale processors with existing organic certification pipelines over greenfield capacity deployment. Long-term viability over a multi-year horizon rests on positioning for hybrid protein formulations combining plant and microbial inputs. Target processors with Health Canada and FDA dual-compliance infrastructure. Monitor precision fermentation cost curves as the critical inflection signal for soy concentrate demand displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Pipeline Expansion | USDA and Canada Organic Regime compliance opens premium-tier pricing access across cross-border retail channels. |
| Enzymatic Processing Technology Licensing | Low-temperature desolventizing capabilities preserve protein solubility for meat alternative emulsification requirements. |
| Direct Brand-Cooperative Contracting | CHS Inc and similar structures capture volume commitments that displace traditional merchant intermediaries in Illinois. |
| Prairie Province Crushing Capacity Addition | Manitoba and Saskatchewan facilities diversify origination beyond Iowa-Illinois logistics corridor concentration. |
| Hybrid Protein Formulation R&D Partnership | Precision fermentation convergence with soy concentrate creates functional texture innovation in dairy alternatives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant-based meat formulators, soybean procurement managers at cooperatives, organic certification auditors, and sports nutrition brand product developers. Secondary validation drew from USDA organic certification databases, FDA plant-based protein labeling guidance documents, Health Canada regulatory filings, and Canadian Food Inspection Agency enforcement records. Bottom-up volume estimates from crushing capacity utilization and top-down market sizing from end-use application demand were triangulated to reconcile figures.
Calibration against historical crush spread data and organic premium realization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application category, end-user contract structure, and regional origination cluster. CAGRs were derived from trend extrapolation of clean-label procurement standards and meat alternative shelf-space expansion, with specific inputs from enzymatic processing technology diffusion rates and Prairie province organic acreage conversion timelines.
Macroeconomic conditions sit as an overlay; deviation in soybean commodity price cycles, rail freight rates, or biofuel policy support would shift the trajectory. Forecasts reflect documented assumptions regarding FDA and Health Canada regulatory stability. Material shifts in state-level plant-based meat labeling disputes or precision fermentation cost breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Cold Pressed Oil Market
Ingredients
Olive Oil Market
Ingredients
Gymnema Extract Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
North America Soy Protein Market
Ingredients
Omega 6 Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Fruit Pectin Market
Ingredients
Acacia Gum Market
Ingredients
Bouillon Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Low Calorie Oil Market
Ingredients
Hen Egg White Protein Market
Ingredients
Corn Starch Market