
 China Cane Sugar Market | 2026-2036
China Cane Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
China Cane Sugar Market Outlook
Beet sugar substitution in northern provinces is consolidating cane sugar's geographic footprint to southern growing belts. Guangxi Nanning Sugar Industry Co., Ltd. leverages vertical integration across crushing and refining stages. Bright Food (Group) Co., Ltd. anchors its position through diversified agribusiness holdings. COFCO Corporation competes via state-backed grain and sugar trading networks.
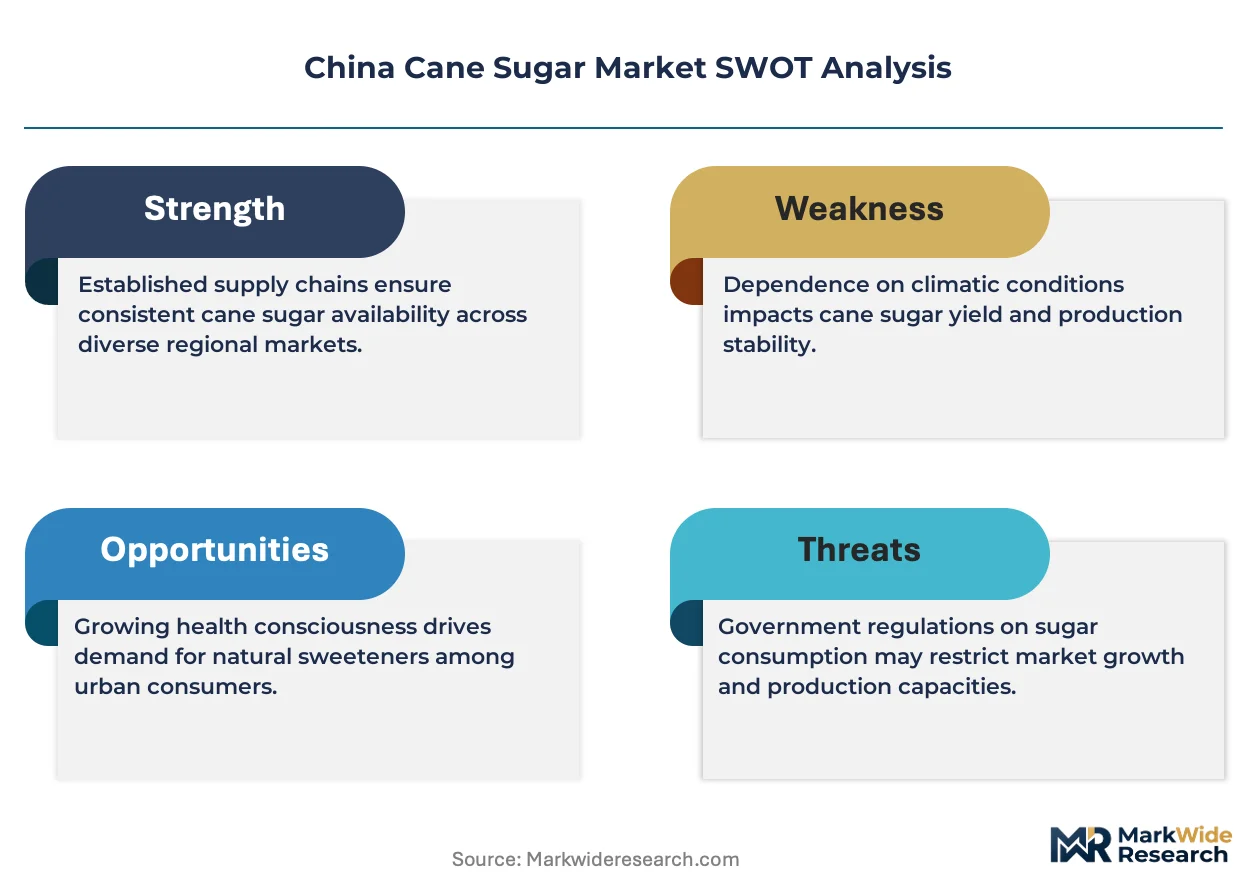
Cane sugar denotes sucrose extracted from Saccharum officinarum stalks through milling, clarification, and crystallization, typically yielding crystals of 99.5% minimum sucrose content in refined grades for industrial sweetening. White sugar dominates volume flows into beverage and confectionery channels where color neutrality commands premium positioning. Liquid sugar sustains the fastest growth trajectory among product types as food manufacturers automate batching processes and reduce handling costs.
SAMR enforces GB 13104 national food safety standards for sugar purity and labeling, while MIIT oversees industrial processing efficiency mandates under carbon-reduction protocols. These frameworks elevate compliance costs for smaller refiners and accelerate consolidation around scaled operators. Stakeholders must monitor water-use restrictions in Guangxi and Yunnan as environmental regulators tighten discharge limits on cane milling effluent.
Market Dynamics
SAMR's tightening of GB 13104 purity specifications is compressing margins for smaller refiners while rewarding scaled operators with integrated crushing and refining capabilities across Guangxi and Yunnan provinces.
Growth Catalysts
- Liquid Sugar Automation:Beverage manufacturers are retrofitting batching lines to accept liquid sucrose formulations, eliminating crystallization and dissolution steps while reducing handling labor by half.
- MIIT Carbon Protocols:Industrial processing efficiency mandates under dual carbon goals are accelerating capital deployment into cogeneration systems that convert bagasse waste into captive thermal power.
- Guangxi Cluster Density:Nanning processing facilities draw cane from radiuses under 50 kilometers, minimizing transport spoilage and preserving sucrose extraction yields above industry benchmarks.
Market Restraints
- Input Cost Volatility:Fertilizer and diesel prices swing with international commodity cycles, squeezing grower margins in Guangxi and Yunnan before cane reaches mill gates.
- Geographic Concentration Risk:Over 60 percent of national crushing capacity sits within 200 kilometers of Nanning, exposing supply chains to single-point weather disruptions during October-to-April harvest windows.
- Beet Sugar Substitution:Northern provinces are expanding beet cultivation under Xinjiang Agricultural Corps subsidies, displacing cane sugar from industrial buyers in Hebei and Shandong.
Strategic Opportunities
- Yunnan Underpenetration:Baoshan and Lincang prefectures host underdeveloped crushing infrastructure relative to their cane acreage, offering first-mover advantages for greenfield mill construction.
- Functional Sweetener Convergence:Blending cane sugar with monk fruit extract or stevia glycosides addresses clean-label demand from premium beverage brands without full sugar replacement.
- SAMR Labeling Revisions:Draft amendments to GB 7718 pre-packaged food standards will mandate added-sugar disclosure panels, creating demand for low-glycemic index formulations that command formulation premiums.
Industry Challenges
- Effluent Compliance Timelines:MEE discharge limits on cane milling wastewater require anaerobic digestion retrofits that demand 18-to-24-month installation cycles, delaying permit renewals for non-compliant facilities.
- Mechanization Skill Gaps:Automated harvesting equipment from John Deere and Zoomlion requires operators trained in GPS-guided cutting sequences, a competency scarce in Guangxi's aging agricultural workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cane Sugar Market |
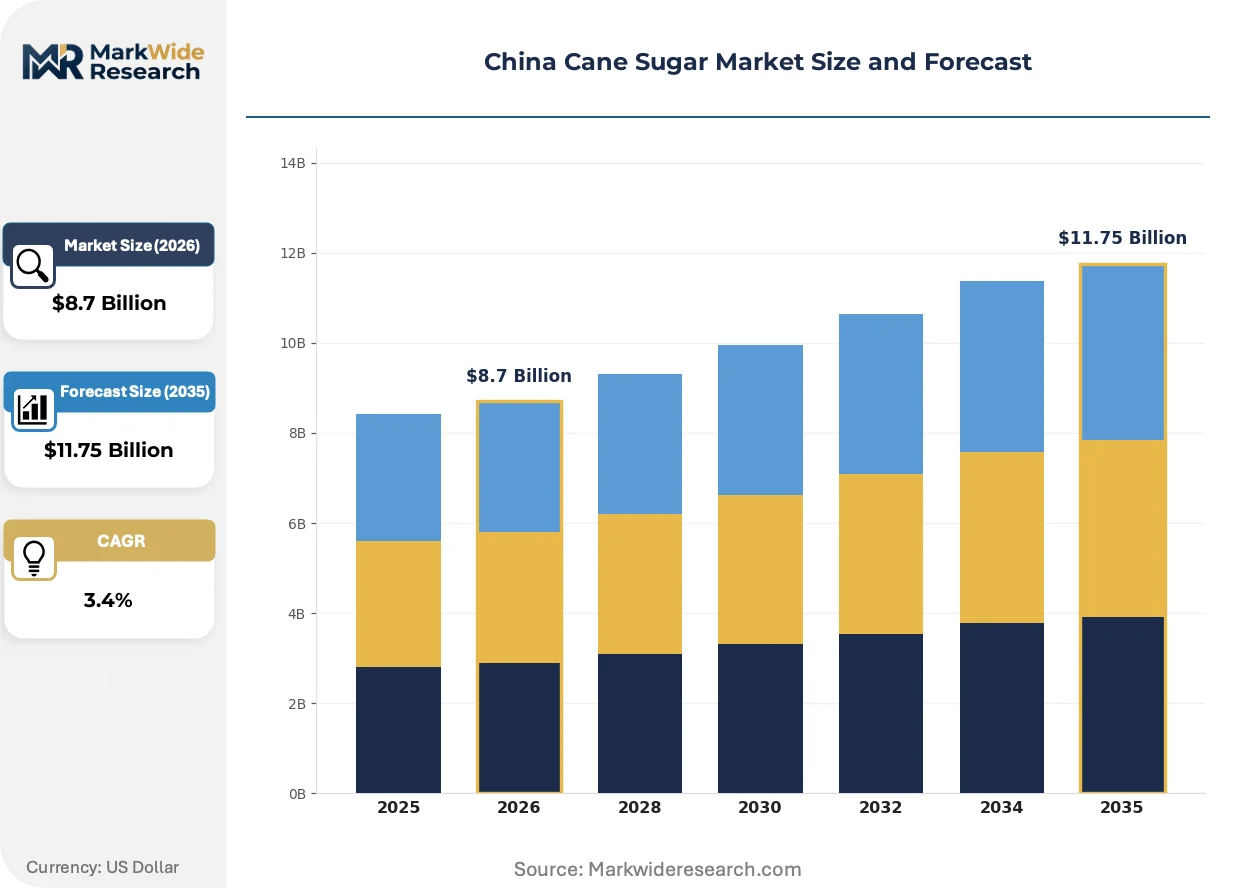
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Sugar, Refined Sugar, Liquid Sugar, White Sugar End User: Food Industry, Beverage Industry, Bakery, Confectionery Distribution Channel: Supermarkets, Online Retail, Wholesale, Traditional Markets Application: Baking, Sweetening, Preserving, Culinary Uses |
| Companies Covered | Guangxi Nanning Sugar Industry Co., Ltd., Bright Food (Group) Co., Ltd., COFCO Corporation, Guangxi Nanning East Asia Sugar Group Co., Ltd., Mitr Phol Group, Guangxi Guitang Group Co., Ltd., Guangxi Feng Sugar Group Co., Ltd., Nanhua Sugar Co., Ltd., Yunnan Yingfu Sugar Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cane Sugar Market Strategic Shifts
Processing technology and procurement logic are converging to reshape how cane sugar moves from field to formulation, with automation and environmental compliance acting as the twin levers of competitive differentiation.
Continuous centrifugal clarification systems are rewriting extraction economics across Guangxi refineries. These units replace batch-based carbonatation with real-time impurity separation, cutting energy consumption per ton of raw sugar. Nanning Sugar Industry and COFCO subsidiaries are piloting installations that recover an additional 0.3 percent sucrose from molasses streams. The technology is compressing capital payback periods for mid-scale mills below five years.
MIIT's 2024 industrial energy efficiency benchmarks are forcing heat-recovery investments across Yunnan processing corridors. Facilities must install bagasse-fired boilers or purchase verified carbon offsets through national emissions trading schemes. Smaller crushers without thermal integration face operating cost disadvantages of 80-to-120 yuan per ton against integrated competitors.
Beverage procurement desks are consolidating supplier rosters from eight-to-ten crystalline vendors toward three-to-four liquid sugar partners with dedicated tanker fleets. This concentration shifts price negotiation leverage toward buyers with annual offtake above 50,000 tons. Guangdong and Fujian bottling corridors are seeing the fastest contract restructuring, with multi-year supply agreements replacing spot purchases.
China Cane Sugar Market Segmentation
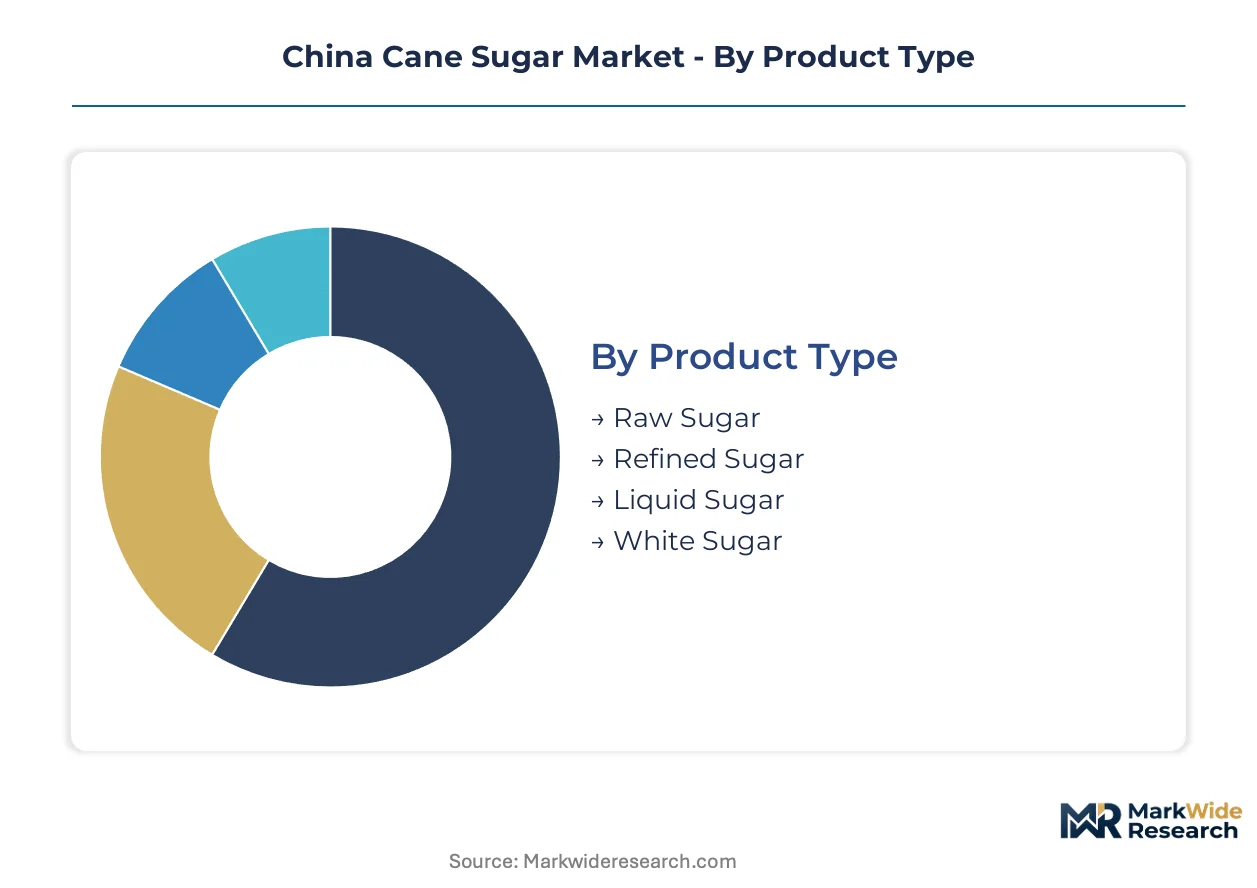
China's cane sugar market fragments along four axes that determine procurement logic and margin capture. Product type dictates processing investment and purity compliance burden. End-user concentration shapes contract structures and volume commitments. Distribution channel selection reflects buyer scale and geographic reach. Application specificity drives formulation requirements and technical service intensity.
Product Type:
Beverage manufacturers prioritize dissolution speed and color neutrality when selecting among crystalline and liquid formats.
- Raw Sugar:Crystalline sucrose of 96-98% purity extracted directly from cane juice without full refining. Nanning mills supply northern refiners who complete purification for industrial buyers in Shandong and Hebei. Input cost volatility and import quota constraints compress trading margins.
- Refined Sugar:Purified crystals meeting GB 13104 specifications of 99.5% minimum sucrose content. SAMR's tightening purity mandates favor scaled operators with integrated crushing and refining capabilities across Guangxi and Yunnan. Food safety audits now require batch-level traceability documentation.
- Liquid Sugar:Concentrated sucrose solutions eliminating crystallization and dissolution steps for automated batching lines. Guangdong bottling corridors are retrofitting procurement systems to accept tanker-delivered formulations, cutting handling labor by half.
- White Sugar:Decolorized refined crystals commanding premium positioning in confectionery channels where visual clarity determines shelf appeal. Color neutrality specifications from premium beverage brands in Fujian and Zhejiang sustain price premiums over standard refined grades.
Refined sugar leads on scale; liquid sugar leads on momentum.
End User:
Volume concentration and formulation complexity separate industrial buyers from artisanal channels.
- Food Industry:Processed food manufacturers requiring consistent granulation for dry mixing applications. Tomato sauce and condiment producers in Guangdong specify moisture content below 0.05% to prevent caking during humid storage seasons.
- Beverage Industry:Carbonated and bottled drink producers driving liquid sugar adoption through automated batching investments. Annual offtake agreements above 50,000 tons now dominate Guangdong and Fujian procurement desks, displacing spot crystalline purchases.
- Bakery:Artisan and industrial bread producers demanding specific crystal sizes for creaming methods and fermentation control. Regional chains in Shanghai and Beijing specify extra-fine granulation for consistent dough rheology.
- Confectionery:Hard candy and chocolate manufacturers prioritizing thermal stability and color neutrality. Premium brands command sucrose purity above 99.7% with specified ash content limits for transparent hard candy production.
Beverage industry leads on volume growth; confectionery leads on specification intensity.
Distribution Channel:
Buyer scale and geographic density determine channel economics and working capital requirements.
- Supermarkets:Modern retail chains stocking consumer-packaged white sugar in 500g to 5kg formats. Yonghui and RT-Mart centralize procurement through direct mill relationships, bypassing traditional wholesale layers.
- Online Retail:E-commerce platforms aggregating fragmented household demand through Tmall and JD.com flagship stores. Logistics networks now handle 25kg bulk packs for small food processors alongside consumer units.
- Wholesale:Regional distributors supplying industrial buyers with 50kg sacks and liquid sugar tanker dispatch. Guangxi-based traders maintain warehouse stocks within 100 kilometers of Nanning processing clusters to minimize transport spoilage.
- Traditional Markets:Wet markets and neighborhood grocers serving household purchasers in county-level cities. Cash-based transactions and minimal inventory rotation constrain product quality consistency.
Wholesale leads on industrial volume; online retail leads on growth trajectory.
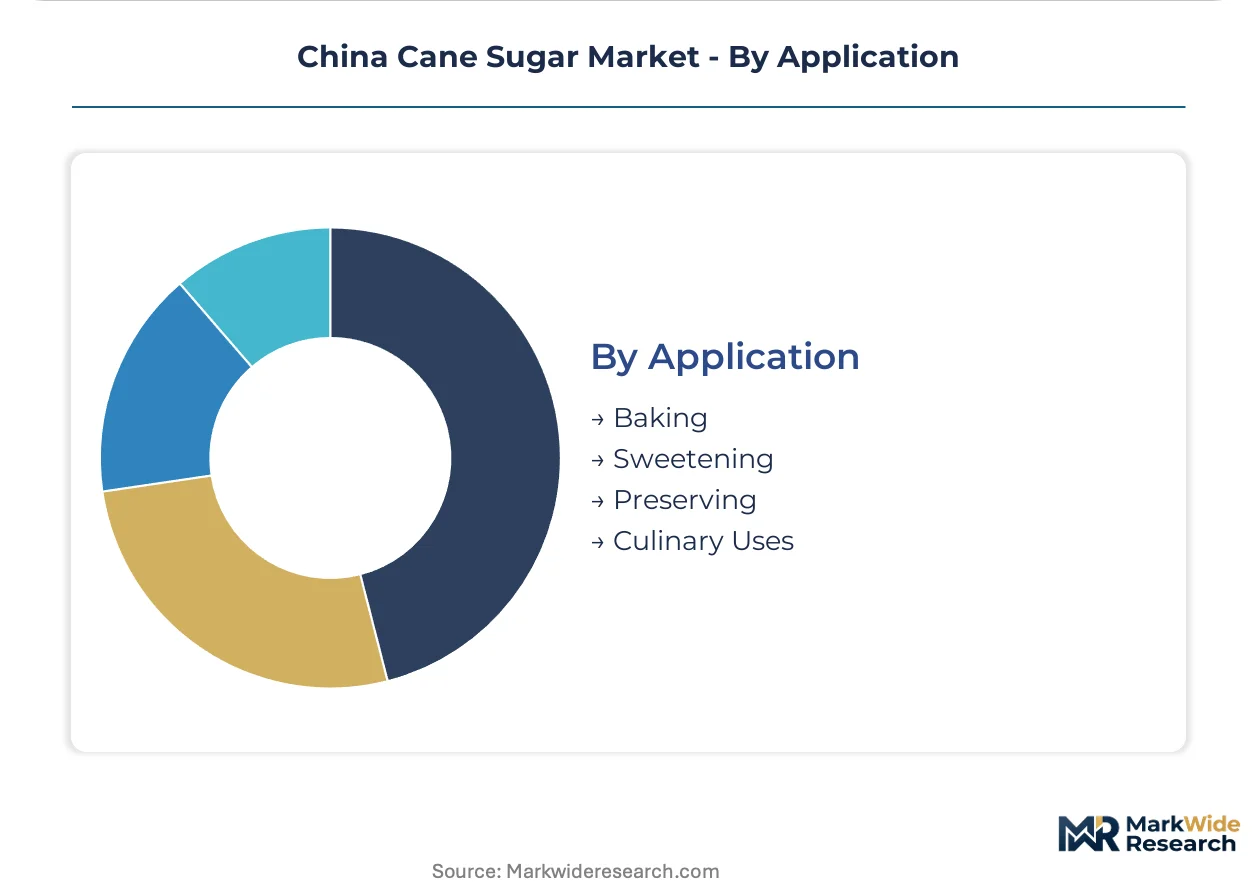
Application:
Functional requirements separate commodity sweetening from technical preservation and structural baking applications.
- Baking:Creaming, fermentation support, and Maillard browning in bread and pastry production. Crystal size distribution directly impacts air incorporation and final crumb structure.
- Sweetening:Basic taste modification in beverages, sauces, and prepared foods. Liquid formulations are displacing crystalline addition in automated production lines.
- Preserving:Osmotic dehydration and microbial inhibition in fruit processing and condiment manufacturing. High sucrose concentration requirements favor liquid sugar for consistent syrup preparation.
- Culinary Uses:Household cooking and restaurant preparation requiring rapid dissolution. Consumer-packaged formats dominate this price-sensitive segment.
Sweetening leads on absolute volume; baking leads on technical specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangxi Zhuang Autonomous Region anchors China's cane sugar production geography, hosting Nanning processing facilities that draw cane from cultivation clusters within 50-kilometer radiuses. Yunnan province and Guangdong province complete the southern growing belt where climatic conditions favor Saccharum officinarum cultivation. Provincial governments administer agricultural subsidies and environmental discharge permits that shape competitive positioning across these jurisdictions.
Guangxi Zhuang Autonomous Region
Nanning Sugar Industry and COFCO subsidiaries operate integrated crushing and refining complexes serving beverage manufacturers in Guangdong and Fujian. SAMR enforces GB 13104 purity standards through batch-level traceability audits that favor scaled operators with laboratory capabilities. Nanning processing clusters maintain sucrose extraction yields above industry benchmarks by minimizing transport spoilage from nearby cane fields.
Yunnan Province
Baoshan and Lincang prefectures host underdeveloped crushing infrastructure relative to their cane acreage, creating first-mover opportunities for greenfield mill construction. MEE discharge limits on cane milling wastewater require anaerobic digestion retrofits that demand 18-to-24-month installation cycles, delaying permit renewals for non-compliant facilities. Kunming-based trading networks coordinate raw sugar shipments to northern refiners in Sichuan and Guizhou.
Guangdong Province
Beverage bottling corridors in Guangzhou and Shenzhen are retrofitting procurement systems to accept tanker-delivered liquid sugar formulations, cutting handling labor by half. MIIT industrial energy efficiency benchmarks force heat-recovery investments across processing facilities supplying these buyers. Dongguan distribution hubs consolidate supplier rosters from eight-to-ten crystalline vendors toward three-to-four liquid sugar partners with dedicated fleets.
Fujian Province
Xiamen and Quanzhou confectionery manufacturers specify white sugar purity above 99.7% with controlled ash content for transparent hard candy production. SAMR draft amendments to GB 7718 pre-packaged food standards will mandate added-sugar disclosure panels, creating demand for low-glycemic index formulations. Zhangzhou processing intermediaries source refined crystals from Guangxi mills via long-term supply agreements replacing spot purchases.
Shandong Province
Tomato sauce and condiment producers specify moisture content below 0.05% to prevent caking during humid storage seasons, sourcing from northern distribution nodes. Beet sugar substitution under Xinjiang Agricultural Corps subsidies is displacing cane sugar from industrial buyers in Jinan and Qingdao. Weifang wholesale markets maintain warehouse stocks within 100 kilometers of processing clusters to minimize transport spoilage.
China Cane Sugar Market Competitive Environment
Capacity expansion dominates the current landscape as integrated operators deploy cogeneration systems converting bagasse waste into captive thermal power. The market structure concentrates around state-backed trading networks and provincial sugar bureaus with legacy milling assets. Three archetypes define competitive positioning: vertically integrated crushers with refining capabilities, diversified agribusiness conglomerates with cross-commodity hedging, and specialized liquid sugar processors serving automated beverage lines. M&A activity and environmental compliance investments represent the dominant competitive moves, with smaller refiners facing operating cost disadvantages of 80-to-120 yuan per ton against integrated competitors.
Within the state-backed trading tier, COFCO Corporation occupies a position reflecting its grain and sugar distribution networks across provincial boundaries. Among Guangxi-based integrated processors, Guangxi Nanning Sugar Industry Co., Ltd. and Guangxi Nanning East Asia Sugar Group Co., Ltd. exemplify the vertically integrated archetype with crushing and refining capabilities concentrated around Nanning facilities. These entities represent scaled operators positioned to absorb SAMR compliance cost escalations that compress margins for smaller competitors.
| Leading Market Players |
|---|
| Guangxi Nanning Sugar Industry Co., Ltd. |
| Bright Food (Group) Co., Ltd. |
| COFCO Corporation |
| Guangxi Nanning East Asia Sugar Group Co., Ltd. |
| Mitr Phol Group |
| Guangxi Guitang Group Co., Ltd. |
| Guangxi Feng Sugar Group Co., Ltd. |
| Nanhua Sugar Co., Ltd. |
| Yunnan Yingfu Sugar Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Refined-grade certification divergence between GB 13104-compliant mills and sub-scale operators manifests in both procurement premiums and supply chain consolidation. Buyers with automated beverage lines pay handling-cost differentials for liquid sugar tanker delivery while smaller crushers face margin compression from effluent compliance investments.
Pricing Analysis
Input-cost pass-through from fertilizer and diesel volatility squeezes grower margins before cane reaches Nanning mill gates. Contract-based long-term offtake dominates procurement above 50,000 tons annually, with price differentiation driven by sucrose purity grade and geographic delivery radius. Pricing pressure stems from beet sugar substitution in northern provinces under Xinjiang Agricultural Corps subsidies. Industrial buyers in Guangdong and Fujian show least price sensitivity for color-neutral white sugar, while traditional market household purchasers remain most sensitive.
Supply Chain Analysis
Single-source vulnerability sits with Guangxi's Nanning processing cluster, where over 60 percent of national crushing capacity concentrates within 200 kilometers. Supply draws from cane cultivation in Guangxi, Yunnan, and Guangdong provinces. Raw material dependencies include phosphate fertilizers, harvesting diesel, and bagasse for cogeneration. Tariff exposure on imported raw sugar creates procurement risk for northern refiners. Distribution runs through wholesale tanker fleets and 50-kilogram sack networks serving industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from cost differentials between Yunnan's underdeveloped Baoshan prefecture and Guangxi's mature Nanning cluster, where MEE discharge compliance investments have already been absorbed.
For Market Incumbents: To counter beet sugar displacement in northern provinces, backward integration into Yunnan greenfield crushing capacity secures cane supply while SAMR purity audits favor scaled laboratory capabilities. Channel control through dedicated liquid sugar tanker fleets locks in beverage manufacturer procurement desks against crystalline competitors. For New Entrants and Emerging Players: Beverage bottlers represent the most penetrable channel partner type for liquid sugar specialists, given Guangdong and Fujian retrofitting of automated batching lines. Functional sweetener convergence with monk fruit extract addresses clean-label demand from premium brands. First-mover positioning in Yunnan's Baoshan prefecture exploits underdeveloped crushing infrastructure relative to local cane acreage. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale refiners possessing integrated crushing-refining capabilities but lacking SAMR compliance scale. Long-term viability over a 5-to-10 year window favors operators with captive bagasse cogeneration and anaerobic digestion permits already secured. Watch MIIT carbon protocol enforcement timelines as the inflection signal for operating cost divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Greenfield Mill Construction | Yunnan prefectures offer first-mover positioning where crushing infrastructure lags behind cane acreage expansion. |
| Backward Integration | Captive cane supply within 50-kilometer radiuses preserves extraction yields above industry benchmarks. |
| Liquid Sugar Tanker Fleet Deployment | Guangdong bottling corridors consolidate supplier rosters toward dedicated delivery partners. |
| Bagasse Cogeneration Installation | MIIT carbon protocols force thermal integration to avoid 80-to-120 yuan per ton cost disadvantages. |
| Anaerobic Digestion Retrofit | MEE effluent compliance secures permit renewals that delay non-compliant competitors. |
Study Parameters
Multiple input streams — mill operations data, procurement desk interviews, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary discussions with crushing facility managers, beverage manufacturer procurement leads, and Guangxi distribution channel partners were validated against secondary sources including SAMR GB standard publications, MIIT industrial efficiency benchmarks, and provincial agricultural subsidy disclosures. Cross-referencing of cane acreage reports against processing capacity registries ensured supply-side accuracy.
Data-stream reconciliation across product type, end-user concentration, and regional production hub dimensions anchored the analytical framework. CAGRs were derived from volume and value trajectory modeling across the projection horizon. Segmentation incorporated liquid sugar automation penetration, SAMR compliance tier stratification, and beet sugar substitution rates in northern provinces as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Xinjiang beet subsidy expansion and MEE discharge limit enforcement. Forecasts reflect documented assumptions on cane yield stability and beverage automation adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Lentils Flour Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Arachidonic Acid Market
Ingredients
Rendered Products Market
Ingredients
Sugar Beet Pectin Market
Ingredients
North America Corn Starch Market
Ingredients
Vegetable Powder Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Australia Soy Protein Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
White Mulberry Leaves Extract Market