
 Chickpea Flour Market | 2026-2036
Chickpea Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea Flour Market Intelligence
Stricter allergen labeling regulations, including the U.S. FDA's FALCPA and the EU's FIC Regulation, is broadening the addressable market for gluten-free alternatives. Major agricultural traders like Archer Daniels Midland Company leverage extensive global sourcing networks to manage raw material costs. Ingredion Incorporated differentiates through its focus on functional plant-based ingredients for food manufacturers. Meanwhile, Cargill, Incorporated sustains a strong position by supplying large-scale bakeries and snack producers.
Chickpea flour is a pulse-based powder derived from finely milled raw or roasted chickpeas, known scientifically as Cicer arietinum. Its primary commercial purpose is to serve as a high-protein, gluten-free alternative in food formulation. The expansion of gluten-free product applications represents the fastest-growing demand segment. Traditional Besan flour, a key product type, continues to command significant volume due to its foundational role in South Asian and Middle Eastern cuisines.
Food safety and quality standards are defined by national and international bodies. Regulations from the FSSAI in India, the FDA in the United States, and the EFSA in Europe dictate acceptable impurity levels and labeling requirements. Compliance with ISO 22000 for food safety management systems is also critical for market access. Future success will hinge on securing consistent raw chickpea supply and developing flours with tailored functional properties for specific food applications.
Market Dynamics
The central structural force shaping the chickpea flour market is the convergence of consumer health trends and stringent food allergen regulations. Mandates from the FDA and EFSA are compelling food manufacturers to reformulate products, expanding the addressable market beyond niche health food stores.
Growth Catalysts
- Allergen-Free Labeling Mandates:Regulations like the U.S. FDA's FALCPA and the EU's FIC Regulation require clear labeling of major allergens, directly stimulating demand from food manufacturers for verifiable gluten-free ingredients like chickpea flour.
- Plant-Based Protein Adoption:The expansion of the meat analogue and sports nutrition industries creates demand for high-protein, functional flours. Chickpea flour's binding and nutritional properties make it a preferred ingredient in these formulations.
- Culinary Staple Demand:India's consistent, large-scale consumption of Besan for traditional cuisine provides a stable volume base for the global market, underpinning production economics and encouraging investment in processing capacity.
Market Restraints
- Raw Material Price Volatility:Chickpea crop yields are sensitive to climatic conditions like drought or excessive rain in primary cultivation regions such as India and Australia, leading to unpredictable fluctuations in raw material costs for millers.
- Flavor Profile Limitations:The inherent "beany" or earthy flavor of chickpea flour can be undesirable in delicately flavored applications like cakes and pastries, requiring additional masking ingredients or costly deodorization processes.
- Substitution from Other Pulses:Lentil, pea, and fava bean flours offer similar gluten-free and high-protein profiles. These alternatives compete directly on price and specific functional attributes like water absorption, posing a constant substitution threat.
Strategic Opportunities
- Functional Flour Development:There is a significant opportunity to develop chickpea flours with tailored functional properties, such as high-gelation or high-solubility variants, specifically for use in emerging categories like plant-based dairy and egg replacement products.
- Extruded Snack and Pasta Formulation:The use of chickpea flour in gluten-free extruded snacks and high-protein pasta remains a key growth area. Its binding properties improve texture and durability in these applications, which are expanding in North American and European markets.
- Geographic Expansion in Latin America:Markets such as Brazil and Mexico represent underpenetrated regions. Promoting chickpea flour as a nutritional and functional ingredient for local baked goods and traditional foods can unlock new volume demand.
Industry Challenges
- Functional Consistency Control:Maintaining consistent functional characteristics, such as water-holding capacity and emulsification properties, across different crop batches and geographic origins presents a significant quality control challenge for processors.
- Compliance with Multiple Food Standards:Producers exporting globally face the complex and costly challenge of simultaneously complying with disparate food safety and import regulations from bodies like India's FSSAI, the U.S. FDA, and Europe's EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea Flour Market |
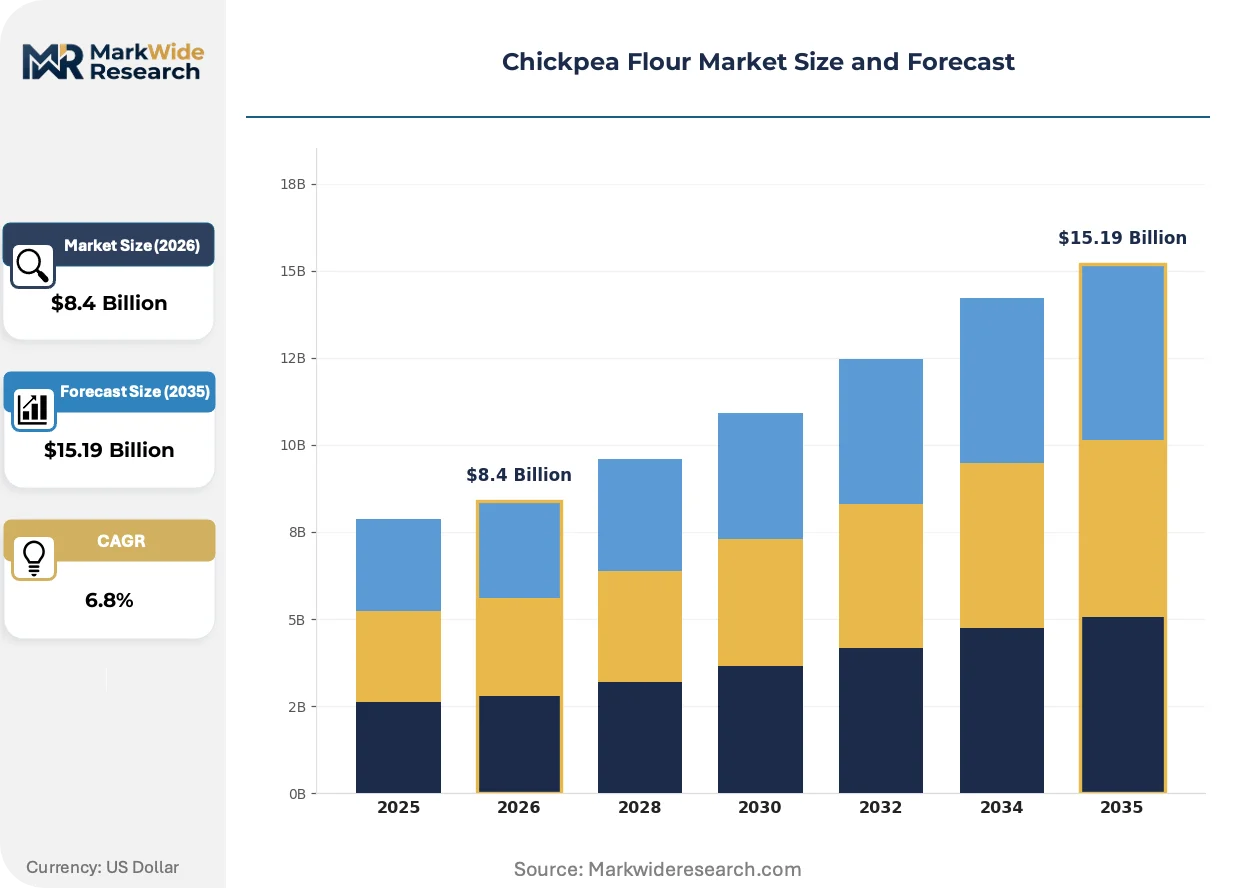
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Besan, Gram Flour, Kabuli Flour, Desi Flour, Others Application: Baking, Snack Production, Gluten-Free Products, Baby Food, Nutritional Supplements End User: Food Manufacturers, Bakeries, Health Food Stores, Catering Services, Home Consumers Packaging Type: Plastic Bags, Paper Bags, Bulk Sacks, Pouches, Jars |
| Companies Covered | Cargill, Incorporated, SunOpta, Ingredion Incorporated, Bob's Red Mill Natural Foods, Inc., Batory Foods, Archer Daniels Midland Company, Roquette Frères S.A., AGT Food and Ingredients, The Scoular Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea Flour Market Strategic Shifts & Innovations
Product development is pivoting from providing a simple gluten-free alternative to engineering highly functional, application-specific ingredients. This shift involves advanced processing to isolate or enhance specific properties, transforming chickpea flour into a strategic tool for food formulators.
Advanced fractionation and air-classification technologies are being used to separate chickpea flour into distinct protein-rich and starch-rich components. Food science teams at plant-based food companies are rapidly adopting these fractions to achieve specific textures and nutritional targets. This capability is electrifying new product development, enabling the creation of novel items like high-protein yogurts and meat analogues with improved mouthfeel.
Regulatory frameworks like the European Union's Farm to Fork Strategy are creating powerful tailwinds. The strategy's emphasis on sustainable food production and plant-based diets implicitly favors pulse crops like chickpeas due to their nitrogen-fixing properties and lower environmental impact. Consequently, food manufacturers across the EU are increasingly motivated to incorporate chickpea flour into product reformulations to align with sustainability goals and appeal to eco-conscious consumers.
A notable behavioral shift is occurring in how commercial bakeries and snack producers source ingredients. Instead of purchasing chickpea flour as a standalone commodity, many are now procuring pre-formulated, functional flour systems from specialized ingredient suppliers. This trend, most visible in North America, streamlines production for end-users by delivering a ready-to-use blend optimized for a specific application, such as a high-protein bread or a gluten-free cracker.
Chickpea Flour Market Segmentation
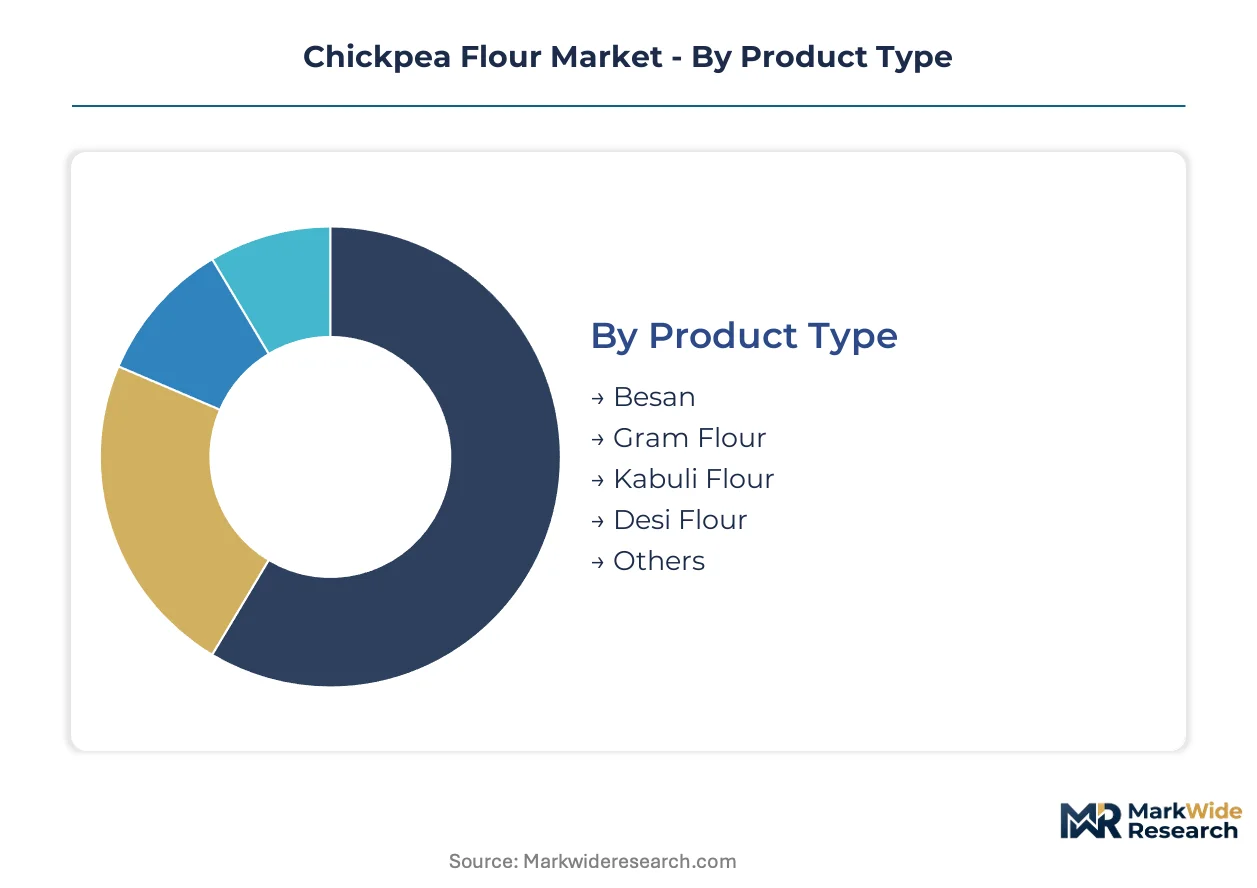
Chickpea flour market segmentation reflects the diverse product forms and end-use applications across the food industry. This granularity helps manufacturers tailor offerings to specific consumer needs and navigate various regulatory requirements. Understanding these segments is crucial for identifying distinct growth pockets and optimizing supply chain strategies.
Product Type:
Product type segmentation in chickpea flour ranges from highly standardized, commodity-grade flours to specialized variants engineered for specific functional properties.
- Besan:This traditional product is a finely milled flour derived from roasted chickpeas, characterized by its distinct earthy flavor and fine texture. Demand remains consistently high in India for batters, sweets, and savory dishes, underpinning market volume.
- Gram Flour:Often used interchangeably with besan, gram flour typically refers to flour produced from split brown chickpeas (chana dal). Its versatility makes it a foundational ingredient in Indian and Middle Eastern cooking, driving significant demand in traditional food manufacturing.
- Kabuli Flour:Derived from larger, lighter-colored Kabuli chickpeas, this flour offers a milder flavor profile suitable for Western-style baking and gluten-free formulations.
- Desi Flour:Produced from smaller, darker Desi chickpeas, this variant provides a more robust flavor and higher protein content for specific culinary applications.
- Others:This category encompasses specialized chickpea flour derivatives, including air-classified protein fractions and starches, targeting advanced food formulations.
Leading the category by volume: Besan. Growing fastest: Others, driven by functional ingredient development.
Application:
Application segments delineate where chickpea flour delivers the greatest volumetric impact across diverse food sectors.
- Gluten-Free Products:Chickpea flour serves as a primary ingredient in gluten-free breads, pastas, and baked goods, providing essential structure and nutritional value. Demand is accelerating due to stringent allergen labeling regulations from the U.S. FDA and EFSA in Europe.
- Snack Production:Utilized in extruded snacks, crackers, and savory bites, chickpea flour significantly enhances protein content and crispness. North American and European snack manufacturers increasingly incorporate it for healthier product reformulations.
- Baking:Integrated into various baked goods, chickpea flour improves texture and adds plant-based protein, particularly in specialty breads and plant-based pastries.
- Baby Food:Its high protein and nutrient density make chickpea flour a valuable component in infant cereals and purees, addressing early childhood nutrition requirements.
- Nutritional Supplements:Employed in protein powders and functional food bars, chickpea flour contributes plant-based protein for sports nutrition and general wellness products.
Dominant application: Gluten-Free Products. High-growth area: Nutritional Supplements.
End User:
End user segmentation reflects the varying scale and operational needs of chickpea flour purchasers, from industrial processors to individual consumers.
- Food Manufacturers:Large-scale food companies integrate chickpea flour into a broad portfolio of products, including ready meals, processed snacks, and plant-based alternatives. Compliance with ISO 22000 is critical for these industrial buyers.
- Bakeries:Commercial and artisan bakeries use chickpea flour for gluten-free and specialty breads, pastries, and savory items. Consistency in functional properties, like water absorption, is paramount for their production processes.
- Health Food Stores:These retailers cater to consumers seeking natural, organic, and allergen-free ingredients, stocking chickpea flour for home use and niche dietary needs.
- Catering Services:Food service providers utilize chickpea flour in large quantities for diverse menus, especially for vegetarian, vegan, and gluten-free options in institutional settings.
- Home Consumers:Individual households purchase chickpea flour for traditional cooking and experimental baking, driven by health trends and culinary interests.
Largest segment by consumption: Food Manufacturers. Emerging segment: Catering Services.
Packaging Type:
Packaging type differentiation addresses cost efficiency, shelf-life requirements, and convenience for various distribution channels and end-user volumes.
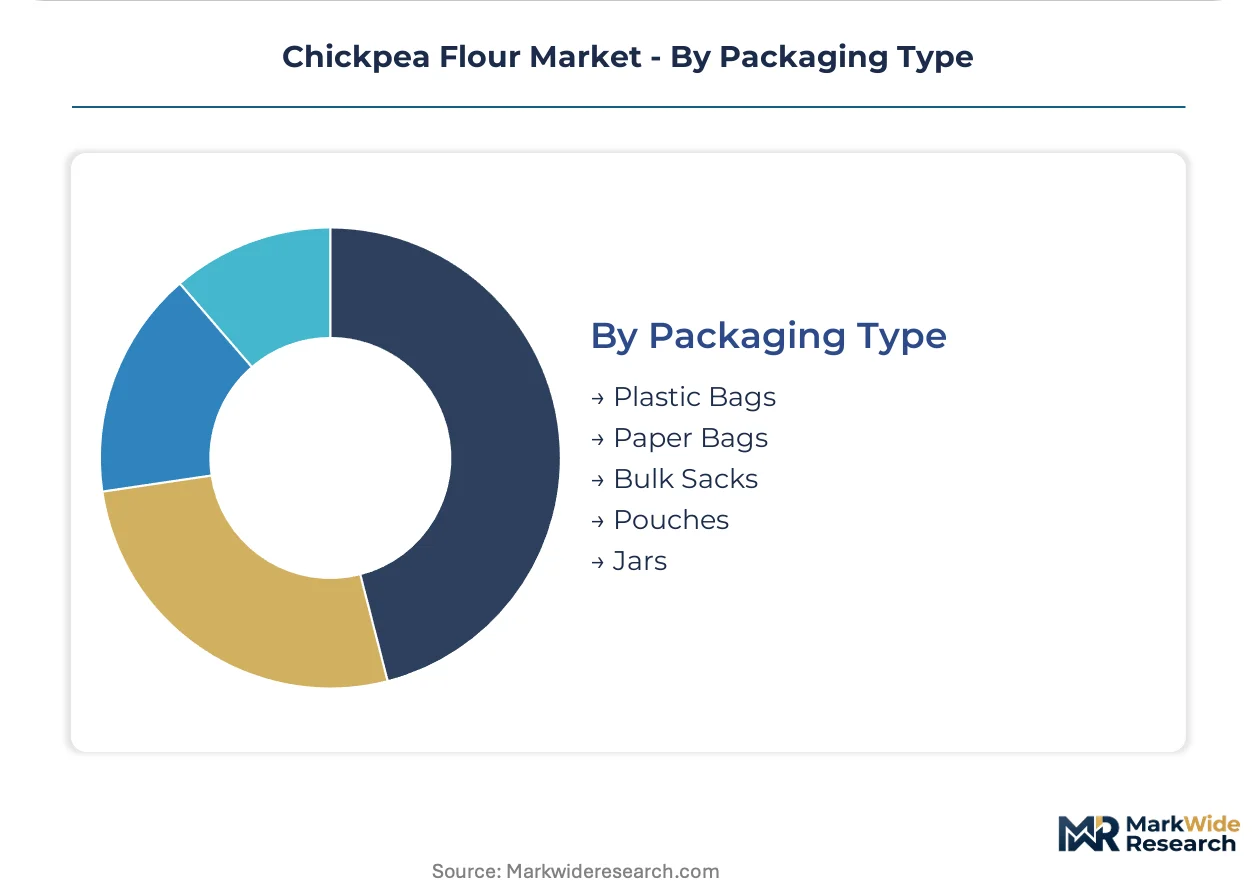
- Bulk Sacks:Large industrial sacks, typically ranging from 25kg to 1000kg, are designed for high-volume food manufacturers and bakeries, optimizing transport and storage costs. Raw material cost volatility directly influences procurement of these bulk quantities.
- Plastic Bags:Commonly used for retail and medium-volume commercial distribution, plastic bags offer effective moisture protection and durability. These are prevalent in markets like India for traditional besan.
- Paper Bags:Preferred for their eco-friendly attributes and breathability, paper bags are utilized for both retail and smaller commercial quantities of chickpea flour.
- Pouches:Flexible pouches provide enhanced convenience and extended shelf life for smaller, premium, or specialty chickpea flour products.
- Jars:Glass or plastic jars offer premium presentation and reusability, typically for gourmet or niche chickpea flour variants in specialty stores.
Most prevalent packaging for industrial scale: Bulk Sacks. Gaining traction in retail: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's extensive domestic market for besan, driven by its foundational role in South Asian cuisine, anchors significant chickpea flour production. The FSSAI regulations ensure quality standards for this staple, influencing global trade flows. This concentration of demand and processing capacity shapes regional market dynamics.
India
India's consistent consumption of Besan for traditional cuisine provides a stable volume base for chickpea flour. The FSSAI dictates food safety and quality standards, ensuring purity for both domestic and export markets. Processing hubs in Maharashtra and Gujarat actively mill chickpeas, supporting local demand and international trade requirements.
United States
Demand in the United States accelerates from the expanding gluten-free products sector and plant-based protein adoption. The U.S. FDA's FALCPA mandates clear allergen labeling, directly stimulating demand for verifiable gluten-free ingredients. Food manufacturers in California and the Midwest are actively integrating chickpea flour into new snack and bakery formulations.
Germany
Germany shows strong demand for chickpea flour driven by the European Union's Farm to Fork Strategy and plant-based diets. EFSA regulations on food safety and labeling guide product reformulations across the country. Ingredient suppliers in Bavaria and North Rhine-Westphalia develop specialized functional flours for meat analogues and baked goods.
Australia
Australia serves as a significant raw material supplier for the global chickpea flour market due to its large-scale cultivation. The country's food safety standards and export protocols ensure compliance for international shipments. Processing facilities in New South Wales and Queensland focus on milling chickpeas for both domestic consumption and export to Asian markets.
Chickpea Flour Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the chickpea flour market. This creates a tiered structure, with large agricultural traders dominating raw material sourcing and specialized ingredient firms innovating in functional flours. Strategic partnerships and capacity expansions are common competitive moves as companies aim to secure consistent raw material supply. Portfolio diversification into plant-based proteins also remains a key strategy for market participants.
Global agricultural traders like Archer Daniels Midland Company exemplify extensive sourcing network capabilities for managing raw material costs. Cargill, Incorporated sustains a strong position by anchoring large-scale bakery and snack producer supply requirements. Ingredion Incorporated differentiates through its focus on functional plant-based ingredients for food manufacturers. These major entities represent the larger scale players who often pursue backward integration to control their supply chains and ensure product consistency. Their strategic efforts also involve developing flours with tailored functional properties for specific food applications, meeting diverse industry demands.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| SunOpta |
| Ingredion Incorporated |
| Bob's Red Mill Natural Foods, Inc. |
| Batory Foods |
| Archer Daniels Midland Company |
| Roquette Frères S.A. |
| AGT Food and Ingredients |
| The Scoular Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap processors and large agricultural traders influence chickpea flour pricing by leveraging extensive global sourcing networks. This control over raw material procurement directly impacts the pricing discipline across the market.
Pricing Analysis
Premium pricing for short lead times reflects immediate demand, while discounts apply for spot inventory. The market primarily operates on a hybrid model, combining commodity spot pricing with contract-based long-term offtake agreements for large buyers. Price differentiation stems from quality grade, certification level like ISO 22000 compliance, and geographic delivery costs. Pricing softness reflects raw material price volatility, driven by climatic conditions affecting chickpea crop yields in India and Australia. Food manufacturers purchasing bulk quantities exhibit the highest price sensitivity, unlike health food stores catering to niche dietary needs.
Supply Chain Analysis
Skilled labor availability in processing hubs like India's Maharashtra and Australia's New South Wales underpins chickpea flour production. The global supply chain draws from concentrated cultivation regions, primarily India and Australia, which are critical raw chickpea suppliers. Commodity price volatility, stemming from weather-dependent crop yields, represents a significant structural supply chain risk. Distribution runs through bulk sales to large food manufacturers and commercial bakeries, alongside packaged retail channels for health food stores and home consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chickpea flour market presents a supply-constrained narrative, with consistent raw chickpea supply and processing capacity in key regions actively propping pricing.
For Market Incumbents:
To counter raw material price volatility, incumbents should deepen backward integration into chickpea cultivation or secure long-term supply contracts with growers in Australia and India. Investing in advanced R&D for functional flour development helps differentiate products and mitigate substitution threats from other pulse flours. Pursuing ISO 22000 certification for all new processing facilities reinforces quality standards for industrial buyers. Consolidating processing capacity in strategic regions ensures economies of scale and consistent product quality.
For New Entrants and Emerging Players:
Manufacturers of plant-based dairy and egg replacement products represent an underserved buyer archetype. New entrants should target this segment by developing highly functional chickpea flour derivatives with tailored properties like high gelation or solubility. A go-to-market strategy focused on technical collaboration with food formulators in North America and Europe can accelerate adoption. Geographic expansion into Latin American markets, promoting chickpea flour for local baked goods, offers a pathway to new volume demand.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor specialized ingredient firms with advanced processing technologies in India and Australia. The long-term viability of the chickpea flour market is underpinned by sustained consumer health trends and stringent allergen labeling regulations. Acquisition targets should possess strong R&D capabilities in functional flour development and established sourcing networks. Investment in advanced fractionation and air-classification technologies signals a commitment to high-value product segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Processing Hubs | Increases overall production volume to meet rising global demand for chickpea flour. |
| Functional Ingredient Research & Development | Develops specialized flours with tailored properties for emerging plant-based applications. |
| Geographic Market Entry in Latin America | Unlocks new volume demand by promoting chickpea flour in underpenetrated regions. |
| Supply Chain Optimization for Raw Chickpeas | Secures consistent raw material flow and mitigates price volatility for processors. |
| Investment in Advanced Processing Technologies | Enhances product differentiation and enables creation of high-value chickpea flour fractions. |
Research Approach
FSSAI reports, FDA guidelines, and EFSA directives formed the secondary backbone, providing regulatory context and market data. Primary research involved interviews with food manufacturers, ingredient suppliers, regulatory experts, and food scientists. This combination of primary and secondary data supported bottom-up and top-down triangulation for market sizing.
Historical trendline analysis informed the forecast framework, applying statistical modeling techniques over the projection horizon. The analysis modeled segmentation dimensions including product type, application, end user, packaging type, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from regression analysis of past market performance. Key forecast inputs included raw chickpea crop yields and the growth trajectory of the global plant-based food industry.
Revisions become necessary when significant climatic events affecting crop yields or major shifts in global trade policies materialize. Forecasts reflect assumptions regarding consumer dietary preferences and regulatory stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Brazil Starch Derivatives Market
Ingredients
Cacao Bean Market
Ingredients
European Brewing Enzymes Market
Ingredients
Spain Fermentation Ingredients Market
Ingredients
Pine Needle Oil Market
Ingredients
Oyster Shell Powder Market
Ingredients
Pepsin Market
Ingredients
Specialty Starch Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Bouillon Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Europe Amino Acid Market
Ingredients
Europe Protein Market
Ingredients
Carob Protein Market
Ingredients
Europe Fats and Oil Market
Ingredients
Fluid Lecithin Market