
 Crypto Wallet Market | 2026-2036
Crypto Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Wallet Market Intelligence
The crypto wallet sector is rebalancing between premium hardware security and commodity software accessibility. Ledger SAS leverages its secure element chip architecture to dominate high-assurance cold storage for institutional treasuries. Coinbase sustains retail inflows through exchange-embedded wallet flows that reduce onboarding friction. Zengo Ltd. differentiates through keyless MPC infrastructure that eliminates seed phrase vulnerability without hardware dependency.
A crypto wallet is a cryptographic key management interface that stores, generates, and signs blockchain transactions using public-private key pairs, typically implementing BIP-32 hierarchical deterministic derivation for address generation. Its commercial purpose centers on enabling self-custody of digital assets while providing transaction broadcast capabilities to distributed ledger networks. Hardware wallets anchor the highest margin pools due to semiconductor-grade secure element costs and limited manufacturing sources, while mobile wallets capture the broadest user base through app store distribution. Software wallets specializing in multi-signature configurations attract institutional demand where governance thresholds require multiple approvers for treasury movements.
SEC registration requirements and state money transmitter frameworks in the United States impose compliance burdens that favor capitalized incumbents over bootstrapped entrants. MiCA implementation across EU member states mandates reserve transparency and operational resilience standards for custody wallet providers serving European residents. Stakeholders must monitor how jurisdictional licensing fragmentation affects cross-border wallet service architecture and user access continuity.
Market Dynamics
Multi-party computation infrastructure is compressing hardware wallet margins while expanding software wallet addressable markets through seedless recovery architectures. This cryptographic shift redistributes security assurance from physical secure elements to distributed key shard protocols.
Growth Catalysts
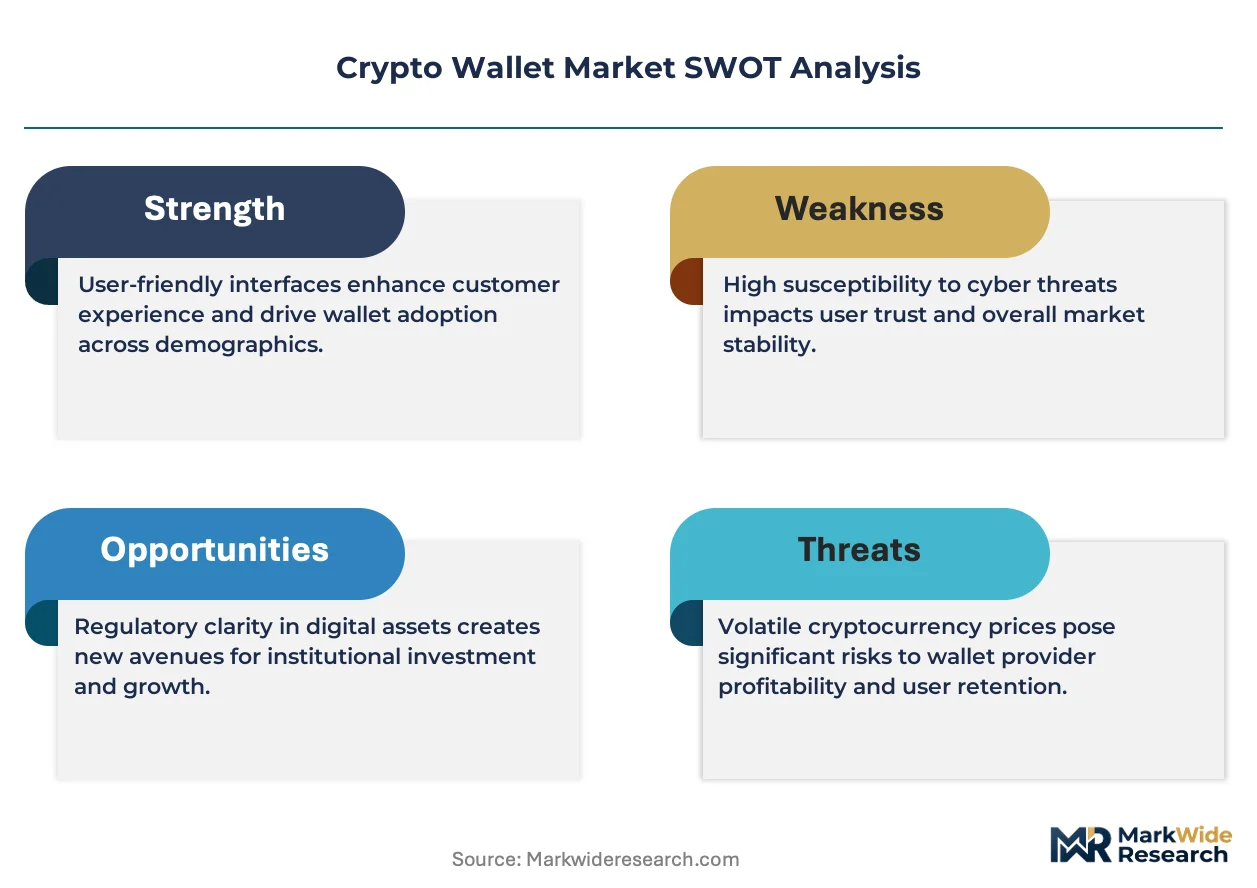
- MiCA Framework Implementation:The EU's Markets in Crypto-Assets regulation mandates operational resilience standards for custody providers, accelerating institutional wallet adoption among asset managers seeking compliant infrastructure.
- Hedge Fund Treasury Diversification:Alternative asset managers are deploying dedicated cold storage solutions for digital asset allocations, creating demand for multi-signature governance configurations.
- Mobile-First Emerging Markets:Smartphone penetration in Sub-Saharan Africa and Southeast Asia is driving software wallet downloads where traditional banking infrastructure remains underdeveloped.
Market Restraints
- Secure Element Supply Concentration:Cold storage hardware depends on semiconductor fabrication concentrated in Taiwan and South Korea, exposing manufacturers to single-source vulnerability.
- State Money Transmitter Licensing:US wallet providers face fragmented 50-state compliance requirements where Texas, New York, and California impose divergent capital reserve and audit standards.
- Quantum Computing Threat Horizon:Elliptic curve cryptography underlying current wallet key generation faces theoretical vulnerability to Shor's algorithm attacks, creating long-term obsolescence risk.
Strategic Opportunities
- Social Recovery Protocols:Smart contract-based guardian systems eliminate seed phrase single points of failure, attracting retail users intimidated by traditional key management.
- Institutional Staking Integration:Wallets embedding Ethereum validator node operations capture yield-seeking treasury managers requiring non-custodial delegation infrastructure.
- India's Digital Rupee Pilot:The Reserve Bank of India's central bank digital currency rollout creates wallet interface demand for retail and merchant payment use cases.
Industry Challenges
- Smart Contract Auditor Scarcity:Wallet-integrated DeFi protocols require formal verification expertise that remains concentrated among fewer than two hundred specialized engineers globally.
- Cross-Chain Key Derivation Complexity:Supporting Bitcoin, Ethereum, and Solana address formats within unified interfaces demands BIP-44 path management that fragments user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Wallet Market |
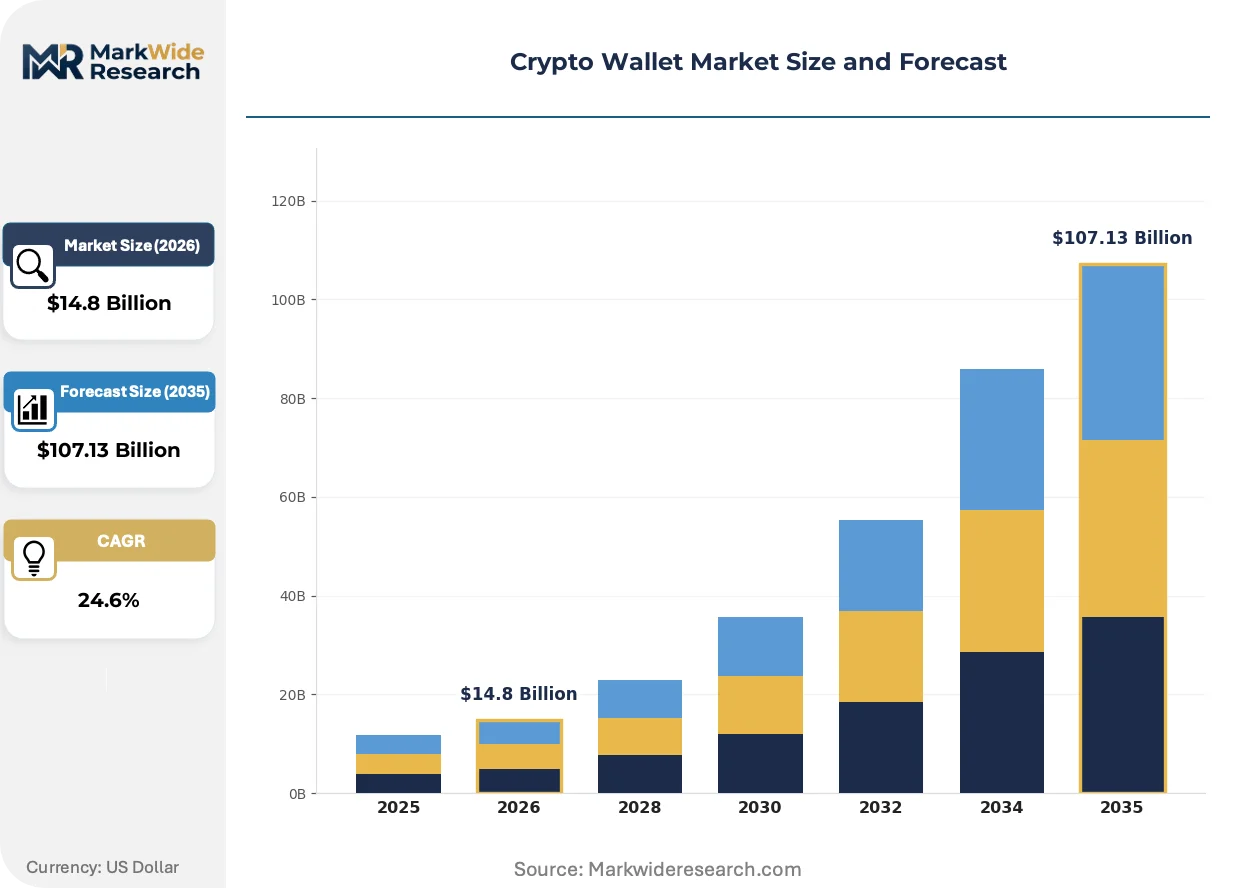
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Wallet Type: Hardware Wallet, Software Wallet, Mobile Wallet, Paper Wallet Security Feature: Multi-Signature, Biometric, Two-Factor Authentication, Encryption Integration Channel: Exchange Integration, Standalone Application, API Integration, Hardware Integration User Type: Retail Users, Institutional Investors, Developers, Traders |
| Companies Covered | Ledger SAS, Trezor, Coinbase, Binance, BitGo, BitPay, Exodus Movement, Inc., Zengo Ltd., MetaMask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Wallet Market Strategic Shifts & Innovations
Biometric authentication modules are displacing PIN and password interfaces across consumer wallet applications. This shift reflects broader hardware convergence between mobile device secure enclaves and cryptographic key storage.
Passkey-based authentication is electrifying mobile wallet security architectures by binding private key access to device-native fingerprint and facial recognition systems. Retail users in South Korea and Japan are adopting these interfaces faster than traditional seed phrase backups. This convergence is compressing onboarding friction for non-technical entrants while reducing support ticket volumes related to password recovery.
The SEC's custody rule proposals for investment advisers are forcing wallet providers to demonstrate qualified custodian status or exit institutional segments. This regulatory pressure is consolidating service provision toward capitalized entities capable of maintaining segregated cold storage and independent audit trails. Hedge fund administrators in Delaware and New York are prioritizing wallet vendors with SOC 2 Type II certification and dedicated insurance coverage.
Self-custody education content is proliferating through hardware manufacturer affiliate channels and crypto-native media platforms. First-time buyers in Germany and Switzerland are completing structured onboarding modules before purchasing devices, extending consideration cycles but reducing return rates. This behavioral shift favors wallet brands investing in localized documentation and video tutorial libraries over pure price competition.
Crypto Wallet Market Segmentation
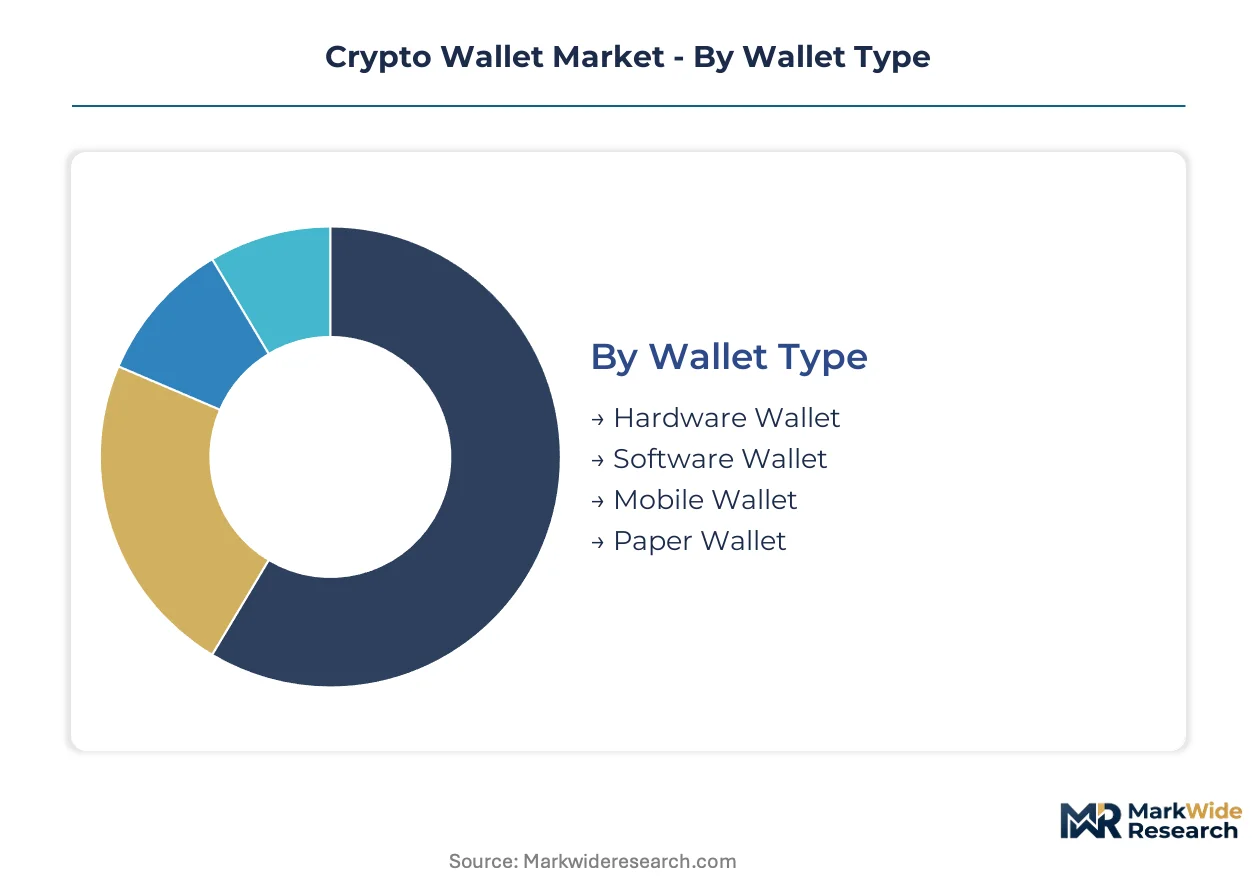
Crypto wallet segmentation reveals how security architecture, distribution channels, and user sophistication create divergent compliance obligations and margin structures across the value chain. Each dimension carries distinct regulatory triggers that reshape vendor investment priorities and geographic targeting strategies.
Wallet Type:
Certification burdens cluster heavily on hardware variants requiring secure element validation and tamper-resistance testing, while software formats face lighter scrutiny focused on application security audits.
- Hardware Wallet:Semiconductor-grade secure elements anchor cold storage for institutional treasuries and high-net-worth holders. Ledger SAS and BitGo dominate this tier where SOC 2 Type II certification and dedicated insurance coverage serve as table stakes for hedge fund administrators in Delaware and New York. Demand concentrates among asset managers deploying dedicated cold storage for digital asset allocations.
- Software Wallet:Desktop and browser-based interfaces capture the broadest user base through reduced onboarding friction. Zengo Ltd. differentiates through keyless MPC infrastructure that eliminates seed phrase vulnerability without hardware dependency, appealing to retail users intimidated by traditional key management. This segment climbs fastest as multi-party computation compresses hardware margins.
- Mobile Wallet:Smartphone-native applications drive penetration in Sub-Saharan Africa and Southeast Asia where traditional banking infrastructure remains underdeveloped.
- Paper Wallet:Physical key printouts serve offline backup and gifting use cases with minimal ongoing technical support requirements.
Software wallets sit at the top of the volume ranking, with mobile wallets climbing the fastest.
Security Feature:
Cost tiers separate enterprise-grade multi-signature deployments from consumer-facing biometric modules, with authentication complexity directly mapping to implementation budgets and technical support overhead.
- Multi-Signature:Governance thresholds requiring multiple approvers for treasury movements attract institutional demand from alternative asset managers. This architecture demands formal verification expertise that remains concentrated among fewer than two hundred specialized engineers globally, creating capability scarcity and premium pricing power.
- Biometric:Fingerprint and facial recognition modules displace PIN interfaces across consumer applications, with South Korean and Japanese retail users adopting these formats faster than traditional seed phrase backups. This convergence compresses onboarding friction for non-technical entrants.
- Two-Factor Authentication:SMS and authenticator-based verification layers add compliance-friendly audit trails for regulated exchanges.
- Encryption:AES-256 and comparable standards provide baseline data protection across all wallet categories without differentiation.
Biometric authentication sits at the top of the volume ranking, with multi-signature configurations gaining share fastest among institutional segments.
Integration Channel:
Application maturity separates embedded exchange flows from standalone deployments, with API and hardware integration representing adjacent expansion vectors for specialized use cases.
- Exchange Integration:Embedded wallet flows through Coinbase and comparable platforms reduce onboarding friction by eliminating separate application downloads. The SEC's custody rule proposals for investment advisers are forcing providers to demonstrate qualified custodian status or exit institutional segments, consolidating service provision toward capitalized entities.
- Standalone Application:Independent wallet software targets self-custody purists with full key control and reduced counterparty exposure.
- API Integration:White-label infrastructure enables neobanks and fintech platforms to embed crypto custody without proprietary development.
- Hardware Integration:Dedicated device pairings serve high-assurance environments requiring air-gapped transaction signing.
Exchange integration sits at the top of the volume ranking, with API integration climbing the fastest as embedded finance expands.
User Type:
Customer sophistication creates divergent support intensity and regulatory exposure, with institutional segments triggering custody rule compliance and retail flows driving volume scale.
- Retail Users:First-time buyers in Germany and Switzerland complete structured onboarding modules before purchasing devices, extending consideration cycles but reducing return rates. This behavioral shift favors brands investing in localized documentation and video tutorial libraries.
- Institutional Investors:Hedge funds and asset managers demand segregated cold storage, independent audit trails, and multi-signature governance. MiCA implementation across EU member states mandates reserve transparency and operational resilience standards for custody providers serving European residents.
- Developers:Technical users requiring testnet access and smart contract interaction capabilities represent a narrow but influential segment.
- Traders:High-frequency participants prioritize execution speed and exchange connectivity over self-custody assurances.
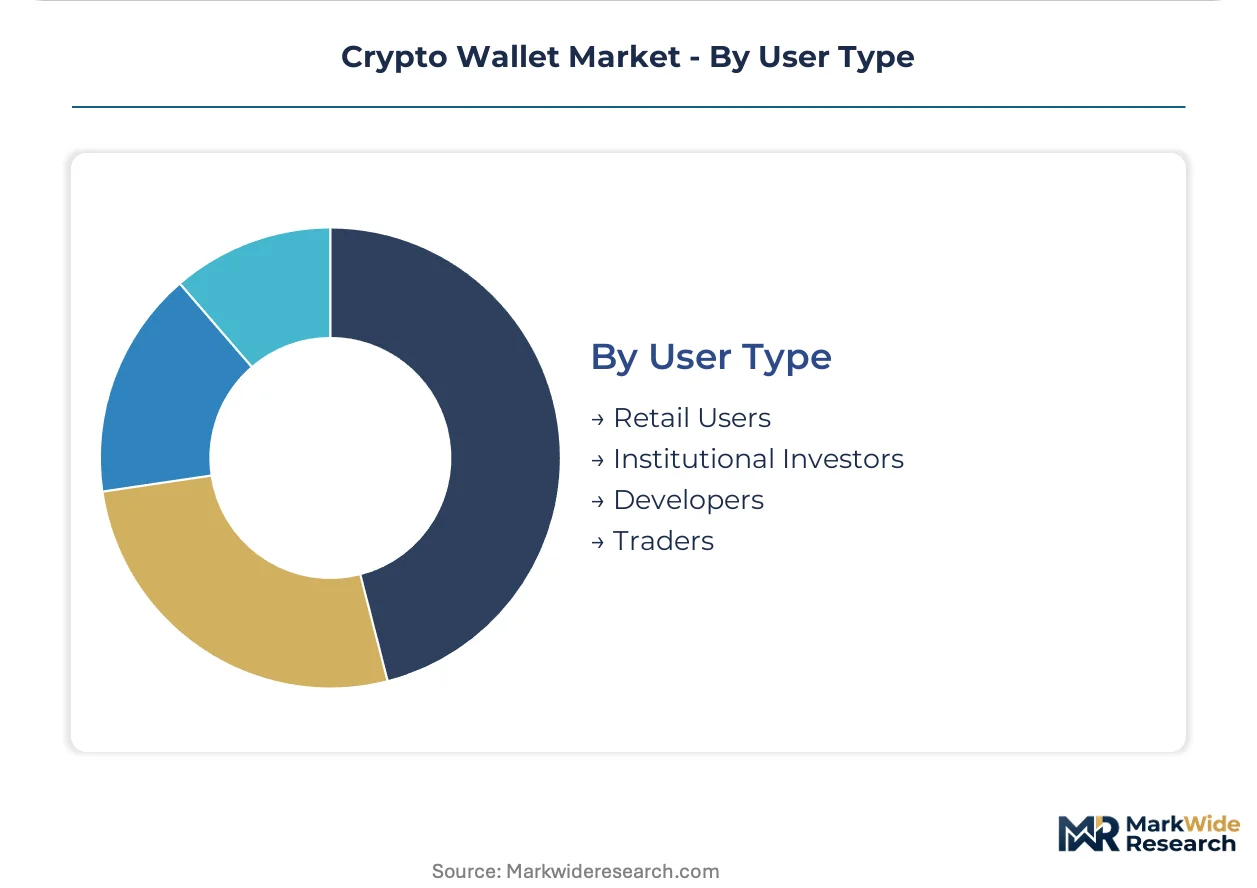
Retail users sit at the top of the volume ranking, with institutional investors expanding most quickly as MiCA framework implementation accelerates compliant infrastructure adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blockchain developer density in the San Francisco Bay Area, London, and Singapore anchors geographic wallet innovation clusters. Regulatory divergence across jurisdictions is fragmenting service architectures. Institutional custody demand concentrates where hedge fund administrators and asset managers cluster.
United States
Hedge fund treasury diversification into digital assets drives institutional wallet demand across Delaware and New York. SEC registration thresholds and state-level money transmitter licenses from Texas, New York, and California impose divergent capital reserve requirements. The Delaware-Wilmington financial cluster hosts administrators prioritizing SOC 2 Type II certification and dedicated insurance coverage.
Germany
First-time retail buyers complete structured onboarding modules before purchasing hardware devices, extending consideration cycles. BaFin oversight of crypto custody businesses mandates operational resilience standards aligned with broader EU frameworks. The Frankfurt financial center concentrates institutional wallet providers serving asset managers seeking compliant infrastructure.
Switzerland
High-net-worth holders seeking cold storage anchor premium hardware demand in Zurich and Geneva. FINMA guidance on blockchain and distributed ledger technology shapes custody service requirements for banks and securities dealers. The Zug "Crypto Valley" cluster hosts wallet developers and blockchain infrastructure firms.
Singapore
Fintech platforms embedding white-label custody APIs drive software wallet integration demand. Monetary Authority of Singapore licensing frameworks for digital payment token service providers establish operational standards. The Marina Bay financial district concentrates neobanks and wealth managers requiring non-custodial delegation infrastructure.
India
Smartphone penetration in underserved banking regions accelerates mobile wallet downloads for retail payments. Reserve Bank of India central bank digital currency pilots create wallet interface demand for merchant and consumer use cases. The Mumbai-Pune corridor hosts fintech developers building embedded finance solutions.
Crypto Wallet Market Key Industry Players
Top-tier vendors anchor institutional custody, while mid-tier specialists compete on MPC infrastructure and retail accessibility. The vendor base spans semiconductor-grade hardware manufacturers, exchange-embedded platforms, and keyless software architects. Strategic archetypes include secure element fabricators, MPC-native developers, and exchange-integrated custody providers. Competitive moves concentrate on qualified custodian status attainment and biometric authentication module integration.
Within the hardware-anchored tier, Ledger SAS and Trezor exemplify secure element-dependent cold storage architectures. Coinbase occupies a position bridging exchange liquidity with embedded wallet flows. Zengo Ltd. represents the MPC-native archetype eliminating seed phrase dependency through distributed key shard protocols.
| Leading Market Players |
|---|
| Ledger SAS |
| Trezor |
| Coinbase |
| Binance |
| BitGo |
| BitPay |
| Exodus Movement, Inc. |
| Zengo Ltd. |
| MetaMask |
| Others |
Cost & Logistics Intelligence
Captive semiconductor fabrication anchors hardware wallet margins while compressing pricing power for software-native competitors. Ledger SAS and Trezor draw from Taiwan Semiconductor Manufacturing Company and Samsung Foundry secure element output, tethering cost structures to single-source foundry economics. This upstream control separates premium cold storage pricing from commodity software wallet tiers.
Pricing Analysis
Bundled custody services versus unbundled self-custody tools split pricing architectures across the crypto wallet sector. Hardware manufacturers command premium positioning through secure element certification costs and limited manufacturing sources. Software wallets face downward price pressure as multi-party computation eliminates physical security dependencies. Retail users in emerging markets exhibit highest price sensitivity, while hedge fund administrators absorb premium tiers for SOC 2 Type II compliance and dedicated insurance coverage.
Supply Chain Analysis
Reverse logistics for hardware wallet refurbishment and warranty replacement flows through regional distribution centers in the Netherlands, Singapore, and Nevada. Secure element chip supply concentrates in Taiwan and South Korea, with assembly operations in China and Vietnam. Single-source foundry vulnerability exposes manufacturers to geopolitical disruption. Distribution runs through direct-to-consumer e-commerce channels, enterprise VAR networks, and exchange-embedded procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crypto wallet sector reads as a late-cycle quality story where institutional treasury demand shifts toward qualified custodian infrastructure with segregated cold storage and independent audit trails.
For Market Incumbents: Anchor market position through backward integration into secure element supply agreements with Taiwan and South Korea foundries. Deepen certification investment for SOC 2 Type II and MiCA operational resilience standards before regulatory deadlines compress serviceable addressable markets. Defend against MPC-native entrants by embedding institutional staking and social recovery protocols into existing hardware architectures. For New Entrants and Emerging Players: Capture white-space in India's digital rupee wallet interface development and Sub-Saharan Africa mobile-first penetration. Target API integration channels for neobanks and fintech platforms seeking embedded custody without proprietary infrastructure buildout. Pursue go-to-market partnerships with regional exchange operators lacking qualified custodian status. For Investors and Strategic Acquirers: Roll-up economics work for MPC-native software specialists because cryptographic talent scarcity and seedless recovery patent portfolios create defensible moats. Five-to-ten year viability hinges on quantum-resistant key generation transition timelines. Monitor SEC qualified custodian rule finalization and MiCA enforcement patterns as inflection indicators for institutional segment consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Qualified Custodian Certification | SEC registration separates institutional service providers from retail-only competitors in Delaware and New York. |
| MPC Infrastructure Development | Seedless key management eliminates hardware dependency while expanding software wallet addressable markets. |
| Secure Element Supply Agreement | Taiwan and South Korea foundry partnerships anchor hardware wallet cost structures and manufacturing capacity. |
| Social Recovery Protocol Launch | Smart contract guardian systems reduce retail user support burdens and seed phrase loss incidents. |
| Biometric Authentication Integration | South Korean and Japanese consumer adoption of passkey-based interfaces compresses onboarding friction. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with wallet platform executives, custody infrastructure engineers, hedge fund treasury managers, and regulatory compliance officers with secondary validation. SEC registration filings, MiCA implementation notices, SOC 2 Type II certification databases, and app store download analytics anchored bottom-up sizing. Top-down triangulation cross-checked against blockchain address growth metrics and exchange-embedded wallet transaction volumes.
Comparable historical periods anchored the projection horizon across hardware shipment cycles, software download trajectories, and institutional adoption waves. Segmentation modeling incorporated wallet type, security architecture, integration channel, and user sophistication tiers. CAGRs derived from fitted growth curves adjusted for regulatory inflection points and technology substitution patterns. Forecast inputs included secure element supply constraints, MPC cryptographic advancement timelines, and central bank digital currency pilot expansion.
Underlying measurement precision varies by segment; hardware wallet shipment data carries tighter precision than nascent MPC software adoption estimates. Forecasts reflect documented assumptions about MiCA enforcement intensity and SEC custody rule finalization. Practitioners should monitor quantum computing threat horizon developments and secure element foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market