
 Crypto ATM Market | 2026-2036
Crypto ATM Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto ATM Market Analysis
Two-way transaction capability is redrawing competitive benchmarks across the Crypto ATM landscape. GENERAL BYTES s.r.o. leverages its open-source software architecture to sustain deployment flexibility across diverse retail environments. Genesis Coin Inc. anchors its position through extensive hardware customization options that serve independent operators. Bitcoin Depot Inc. dominates the United States footprint through aggressive kiosk network expansion in high-traffic convenience locations.
A crypto ATM is a self-service kiosk that enables users to buy or sell cryptocurrency using cash, debit cards, or digital wallets, typically incorporating biometric identity verification and blockchain transaction broadcasting with confirmation thresholds of one to six blocks. These machines serve unbanked populations, crypto-native consumers seeking physical on-ramps, and retail venues generating ancillary foot traffic revenue. Two-way machines command premium placement economics while one-way units penetrate lower-density markets through reduced capital requirements. Cloud-based management platforms are displacing on-premise architectures as operators prioritize remote diagnostics and real-time compliance reporting across distributed fleets.
The Financial Crimes Enforcement Network enforces Bank Secrecy Act obligations including anti-money laundering program maintenance and suspicious activity reporting for crypto ATM operators in the United States. State-level money transmitter licenses from Texas, New York, and Wyoming regulators create a fragmented compliance map that shapes expansion feasibility. The European Union's Markets in Crypto-Assets framework introduces custody and operational reserve requirements that will recalibrate cross-border deployment strategies. Stakeholders must monitor evolving state-by-state licensing reciprocity agreements and MiCA implementation timelines to anticipate where operational costs will shift most dramatically.
Market Dynamics
Two-way transaction capability is redrawing competitive benchmarks across the Crypto ATM landscape, forcing operators to upgrade hardware footprints or cede premium retail placements to rivals offering full buy-sell functionality.
Growth Catalysts
- Bank Secrecy Act compliance maturation:FinCEN's clarified guidance on money services businesses has reduced licensing ambiguity for US operators, accelerating state-by-state network expansion.
- Convenience store channel penetration:Major retail chains in Texas and Wyoming are dedicating floor space to crypto ATMs, capturing ancillary foot traffic revenue from digital-native consumers.
- Biometric identity verification:Fingerprint and facial recognition integration is reducing transaction friction and fraud exposure, improving unit economics in high-traffic locations.
Market Restraints
- State-level licensing fragmentation:Non-reciprocal money transmitter requirements across Texas, New York, and Wyoming create compliance cost barriers that deter multi-state operators.
- Hardware supply concentration:ASIC chip fabrication for secure transaction modules concentrates in East Asian foundries, exposing deployment timelines to geopolitical supply disruptions.
- Cash handling infrastructure:Armored courier services for kiosk cash replenishment command premium pricing in rural zip codes, compressing margins in lower-density markets.
Strategic Opportunities
- EU MiCA framework implementation:The Markets in Crypto-Assets regulation introduces harmonized custody standards that will streamline cross-border kiosk deployment across member states.
- Remittance corridor integration:Mexico-US corridor markets present underpenetrated demand for cash-to-crypto conversion serving unbanked migrant workers.
- Cloud-native management platforms:Remote diagnostics and real-time compliance reporting capabilities are enabling operator consolidation of fragmented independent kiosk fleets.
Industry Challenges
- Blockchain confirmation latency:One-to-six block confirmation thresholds for transaction finality create customer wait times that degrade user experience in high-volume retail settings.
- AML program staffing scarcity:Qualified compliance officers familiar with both Bank Secrecy Act obligations and cryptocurrency transaction monitoring command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto ATM Market |
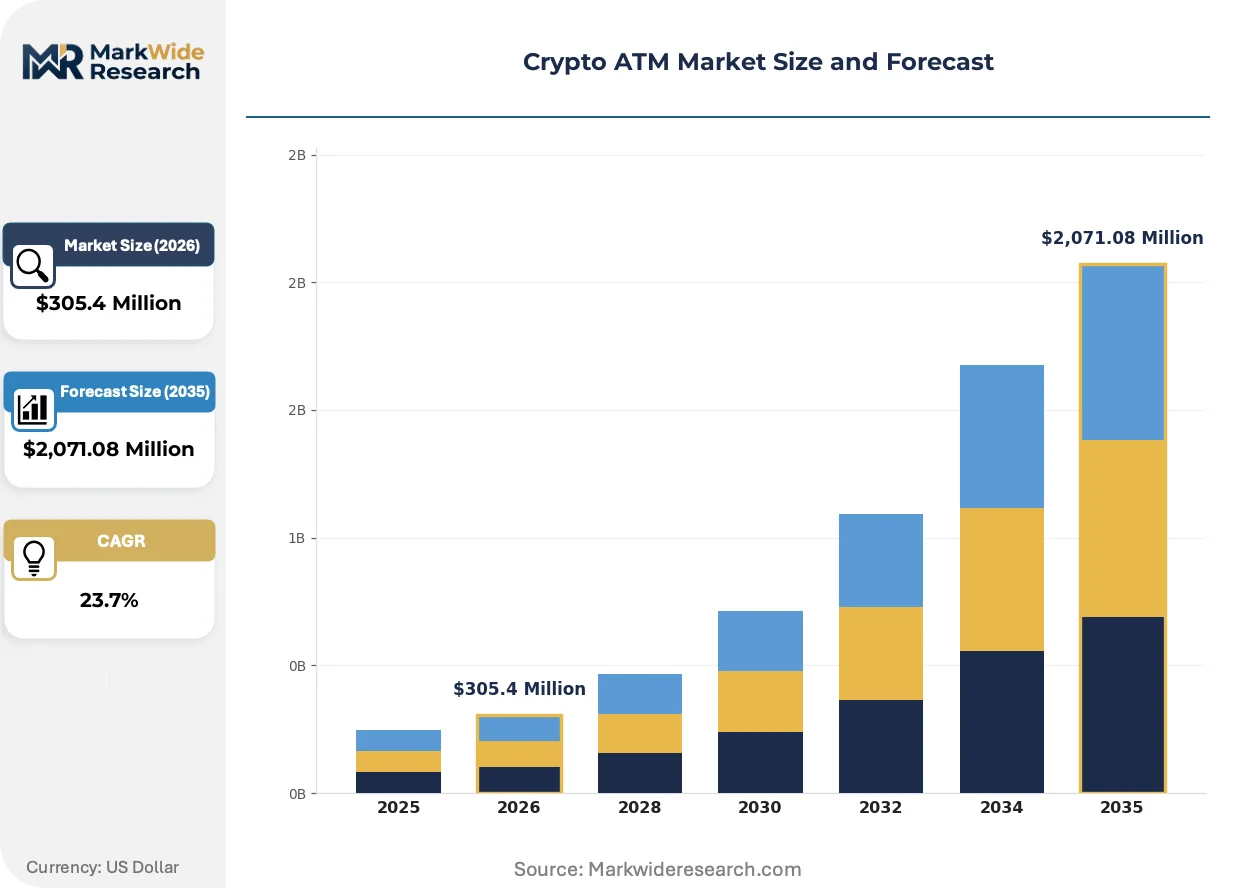
| Market Size in 2026 | $305.4 Million |
| Market Size in 2035 | $2,071.08 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Two-Way, One-Way, Multi-Currency, Bitcoin Only Technology: Cloud-Based, On-Premise, Hybrid, Blockchain Deployment: Public Locations, Private Establishments, Event Spaces, Kiosk Networks Service Type: Transaction Services, Maintenance, Upgrades, Customer Support |
| Companies Covered | GENERAL BYTES s.r.o., Genesis Coin Inc., Bitcoin Depot Inc., Bitstop, Byte Federal, Inc., RockItCoin, Lamassu Industries AG, Bitaccess, Coinsource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto ATM Market Emerging Trajectories
Cloud-based architectures are displacing on-premise management systems as operators prioritize centralized fleet oversight, while biometric verification modules and real-time blockchain analytics reshape hardware specifications and compliance workflows.
Embedded biometric identity verification is decomposing traditional card-based authentication workflows in next-generation kiosk deployments. Independent operators in high-fraud metropolitan markets are adopting fingerprint and facial recognition modules at accelerated refresh cycles. This technology is decomposing the legacy two-step verification stack, compressing hardware BOM costs while raising software licensing expenditures.
Europe's Markets in Crypto-Assets framework introduces custody and operational reserve requirements that will recalibrate cross-border deployment strategies. Operators must maintain segregated cold storage reserves and publish audited proof-of-reserves documentation, raising working capital intensity. MiCA's phased implementation timeline pressures kiosk manufacturers to certify hardware against EU cybersecurity standards before 2025 enforcement deadlines.
Buyer procurement patterns are gravitating toward managed service contracts that bundle hardware, software, cash logistics, and compliance reporting under single-vendor arrangements. Independent convenience store operators are displacing self-managed kiosk ownership with revenue-share partnerships that transfer regulatory liability to specialized ATM deployers. This shift concentrates most visibly in Texas metropolitan corridors where multi-unit retail chains negotiate master service agreements covering dozens of locations.
Crypto ATM Market Segmentation
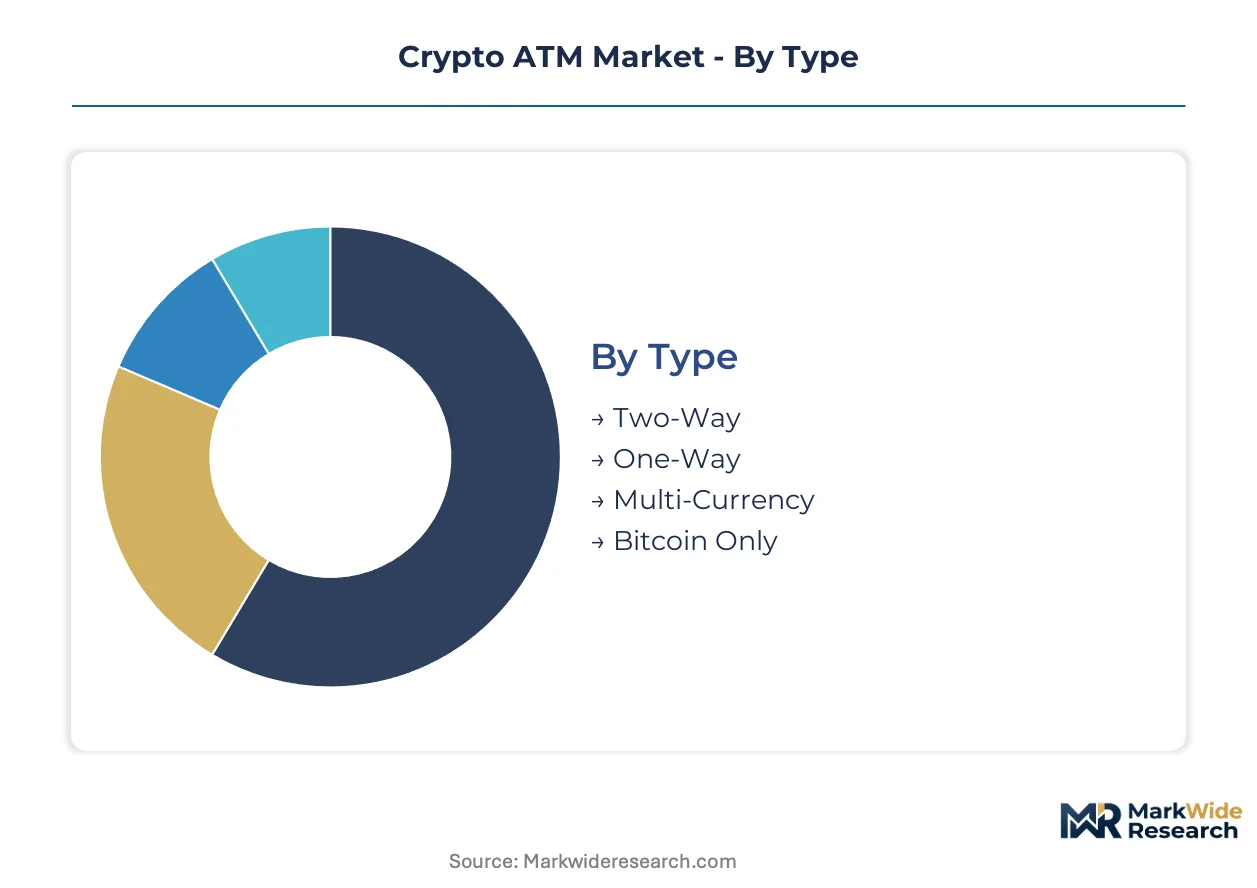
Segmentation in crypto ATMs reveals how hardware configuration, software architecture, and placement strategy determine operator profitability across divergent regulatory and demographic environments. Understanding these divisions exposes where capital requirements, compliance burdens, and revenue potential concentrate.
Type:
Domestic US operators favor one-way and Bitcoin-only units for cost-controlled rural penetration, while two-way and multi-currency machines dominate export-led deployments in European and Latin American corridors seeking full-service functionality.
- Two-Way:Buy-sell capability requires dual cash handling systems and enhanced AML software stacks. Demand clusters in Texas metropolitan zones and Wyoming retail chains where consumers expect immediate liquidity conversion.
- One-Way:Single-direction purchase-only units strip hardware complexity and reduce per-unit capital outlay by roughly half. Rural zip codes across the US Mountain West absorb these machines where transaction volumes cannot amortize two-way infrastructure.
- Multi-Currency:Support for Ethereum, Litecoin, and stablecoin pairs demands expanded blockchain node integration and dynamic pricing feeds.
- Bitcoin Only:Stripped-down firmware and simplified compliance reporting attract independent operators with limited technical staffing.
One-Way commands the established base. The steepest expansion runs through Two-Way.
Technology:
Cost tier separation is pronounced: cloud-native platforms carry recurring SaaS expenditures but eliminate server hardware, while on-premise installations demand upfront capital and dedicated IT personnel.
- Cloud-Based:Centralized fleet management enables remote diagnostics, real-time transaction monitoring, and automated compliance reporting across dispersed kiosk networks. Large multi-state operators in the US Southwest prioritize this architecture to manage hundreds of units without regional technical staff.
- On-Premise:Local server installations retain transaction data within physical operator control, satisfying conservative risk assessments at single-location independent deployers.
- Hybrid:Edge computing with cloud backup balances latency sensitivity against redundancy requirements.
- Blockchain:Direct node connectivity eliminates third-party API dependencies but demands specialized maintenance expertise.
On-Premise retains the legacy installed base. Cloud-Based is climbing the fastest as operator consolidation accelerates.
Deployment:
Volume concentration follows foot traffic patterns: public locations and kiosk networks absorb high-transaction machines, while private establishments and event spaces serve episodic or captive-audience demand.
- Public Locations:Convenience stores, gas stations, and shopping malls expose machines to continuous consumer flow. Major Texas retail chains now dedicate standardized floor space configurations for crypto ATM placement, generating ancillary revenue from digital-native foot traffic.
- Kiosk Networks:Branded machine fleets under unified operational control achieve economies in cash logistics and compliance staffing. Wyoming-based operators leverage this model across dozens of coordinated placements.
- Private Establishments:Corporate campuses and membership clubs restrict access to vetted user pools, reducing fraud exposure.
- Event Spaces:Temporary installations at conferences and festivals demand rapid deployment and teardown capabilities.
Public Locations command the established base. Kiosk Networks are gaining share fastest through operator consolidation.
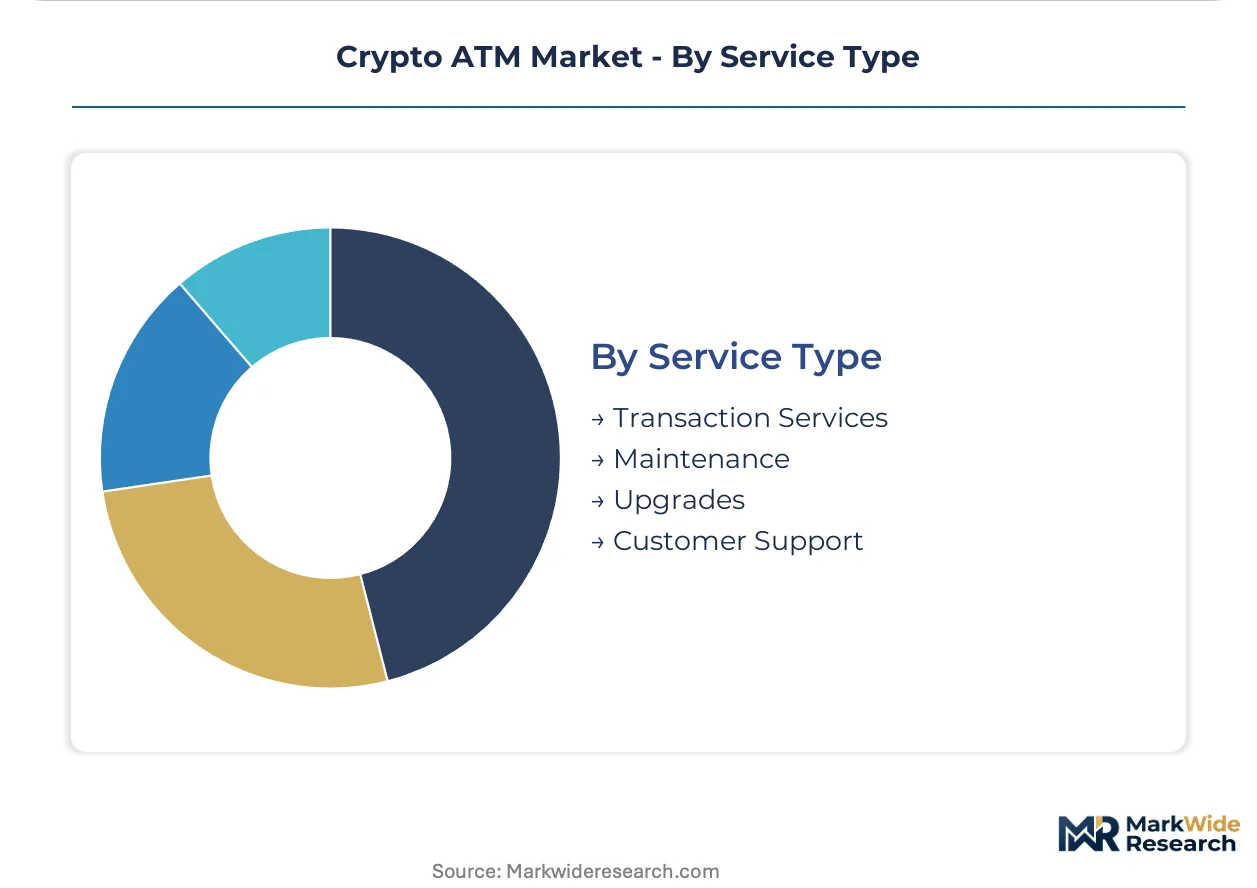
Service Type:
Customer type differentiation separates transaction-heavy users seeking immediate execution from operational-dependent operators requiring ongoing technical and regulatory support.
- Transaction Services:Per-transaction revenue models dominate operator economics, with fees typically structured as percentage spreads or flat charges. Unbanked populations in US-Mexico corridor markets drive sustained cash-to-crypto conversion demand.
- Maintenance:Hardware upkeep, software patching, and cash replenishment coordination command recurring contracts. Armored courier integration and biometric module calibration concentrate service value in high-traffic urban deployments.
- Upgrades:Firmware updates and hardware refreshes extend machine operational life against evolving regulatory requirements.
- Customer Support:Dispute resolution and transaction troubleshooting reduce churn among retail venue partners.
Transaction Services command the established base. Maintenance is expanding most quickly as fleet aging and compliance complexity deepen operator reliance on outsourced technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports crypto ATM hardware and software architectures while importing specialized ASIC components from East Asian foundries. This trade pattern shapes deployment economics across North American and European corridors. Regulatory fragmentation between jurisdictions creates divergent expansion feasibility for operators seeking cross-border scale.
United States
Convenience store chains in Texas and Wyoming dedicate standardized floor space to crypto ATM placements, capturing ancillary foot traffic from digital-native consumers. FinCEN enforces Bank Secrecy Act obligations including AML program maintenance and suspicious activity reporting for all money services businesses. Houston and Dallas metropolitan clusters absorb two-way machines where immediate liquidity conversion commands premium placement economics.
Canada
Retail payment networks in Ontario and British Columbia expand crypto ATM footprints as consumer familiarity with digital assets broadens. The Financial Transactions and Reports Analysis Centre of Canada administers anti-money laundering compliance standards for virtual currency service providers. Toronto and Vancouver urban cores concentrate kiosk deployments where unbanked populations and crypto-native users intersect.
Germany
BaFin licensing requirements for crypto custody businesses create structured entry pathways for ATM operators seeking European market presence. The Federal Financial Supervisory Authority mandates operational reserve maintenance and cybersecurity certification for digital asset infrastructure. Berlin and Frankfurt banking corridors host pilot deployments testing MiCA-aligned compliance workflows ahead of full regulatory enforcement.
Switzerland
FINMA guidance on blockchain-based financial infrastructure attracts operators seeking regulatory clarity for multi-currency kiosk offerings. The Swiss Financial Market Supervisory Authority distinguishes between payment tokens and asset tokens for licensing classification purposes. Zug's Crypto Valley cluster serves as a testbed for hardware-software integration before broader European rollout.
United Kingdom
FCA registration requirements for cryptoasset firms filter market entry toward compliant operators with established AML frameworks. The Financial Conduct Authority mandates ongoing compliance monitoring and annual reporting for registered virtual asset service providers. London fintech corridors concentrate managed service providers offering bundled hardware, software, and regulatory liability transfer to retail venue partners.
Crypto ATM Market Vendor Landscape
Listed leaders compete with private specialists across capital access and regulatory agility dimensions, producing a tiered structure where scale-driven deployers face nimble regional operators. The vendor base separates into three strategic archetypes: open-source platform providers, hardware customization specialists, and network expansion aggregators. Consolidation pressure intensifies as managed service contracts displace self-managed kiosk ownership. Geographic expansion and technology licensing dominate competitive moves as operators seek state-by-state licensing reciprocity and cloud-native management capabilities.
Within the open-source platform tier, GENERAL BYTES s.r.o. exemplifies deployment flexibility across diverse retail environments. Genesis Coin Inc. occupies a position among hardware customization specialists serving independent operators with extensive configuration options. Bitcoin Depot Inc. anchors the network expansion archetype through aggressive kiosk footprint growth in high-traffic convenience locations. These three entities represent divergent strategic bets on software modularity, hardware adaptability, and placement density as sources of competitive position.
| Leading Market Players |
|---|
| GENERAL BYTES s.r.o. |
| Genesis Coin Inc. |
| Bitcoin Depot Inc. |
| Bitstop |
| Byte Federal, Inc. |
| RockItCoin |
| Lamassu Industries AG |
| Bitaccess |
| Coinsource |
| Others |
Supply Flow & Price Mechanics
Cloud-native management platforms replacing on-premise server architectures are redrawing procurement economics while compressing hardware capital requirements and elevating recurring SaaS expenditures across operator balance sheets.
Pricing Analysis
Independent convenience store operators anchor kiosk pricing through revenue-share partnerships that transfer regulatory liability to specialized deployers. Pricing stratifies across premium two-way machines with biometric modules, standard cloud-managed one-way units, and economy-tier Bitcoin-only hardware for rural penetration. Cost compression in the hardware tier intensifies as ASIC chip fabrication concentrates in East Asian foundries. Multi-state operators exhibit lowest price sensitivity due to volume-scale procurement, while single-location independents face acute margin pressure from per-unit licensing fees.
Supply Chain Analysis
Port congestion on transpacific lanes from Taiwan and South Korea disrupts ASIC chip delivery schedules for secure transaction modules. Component sourcing draws from Chinese firmware developers, German engineering houses for biometric hardware, and US-based cloud infrastructure providers. Single-source vulnerability in East Asian semiconductor fabrication exposes deployment timelines to geopolitical friction. Distribution runs through direct manufacturer-to-operator channels for large deployers, while independent operators rely on value-added resellers bundling compliance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crypto ATM market functions as a service-attach opportunity where maintenance and compliance reporting contracts expand faster than hardware deployment as fleet aging and regulatory complexity deepen operator reliance on outsourced technical support.
For Market Incumbents: Secure cloud-native management platform acquisitions to consolidate fragmented independent kiosk fleets before specialized software vendors achieve critical mass. Defend Texas and Wyoming market positions through exclusive master service agreements with multi-unit retail chains facing heightened FinCEN scrutiny. Prioritize backward integration into biometric hardware supply to reduce ASIC chip dependency exposure.
For New Entrants and Emerging Players: MiCA certification fast-tracks for EU market entry present underpenetrated white-space ahead of full regulatory enforcement deadlines. Target Mexico-US remittance corridor markets where cash-to-crypto conversion serves unbanked migrant workers with limited incumbent presence. Pursue revenue-share partnerships with rural convenience store operators displaced by managed service consolidation in metropolitan zones.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cloud-native software specialists over hardware manufacturers facing commodity margin compression. Five-to-ten year viability hinges on regulatory compliance automation capabilities rather than kiosk placement density alone. Monitor state-by-state money transmitter license reciprocity agreements as the inflection signal for multi-state operator valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Acquisition | Consolidates fragmented independent fleets under unified compliance reporting architecture. |
| Biometric Hardware Integration | Reduces fraud exposure in high-traffic Texas metropolitan deployments. |
| MiCA Certification Pathway | Unlocks cross-border kiosk deployment across EU member states under harmonized custody standards. |
| Revenue-Share Partnership Model | Transfers FinCEN regulatory liability to specialized deployers serving independent retail venues. |
| Remittance Corridor Expansion | Captures cash-to-crypto demand from unbanked populations in Mexico-US border markets. |
Methodological Framework
The analysis maps hardware configuration tiers, software architecture types, and service contract structures, each validated through kiosk deployer executives, compliance officers at multi-state operators, convenience store procurement managers, and armored courier logistics coordinators. Primary interviews triangulate against FinCEN guidance documents, state money transmitter licensing databases, EU MiCA regulatory filings, and SEC disclosures from listed ATM operators. Bottom-up unit deployment counts reconcile with top-down market value estimates across the projection horizon.
Consistency checks validate volume and value outputs against hardware shipment data, cloud platform subscription records, and cash logistics service contract values. Segmentation dimensions span machine type, technology architecture, deployment venue, and service tier. CAGRs derive from fitted growth curves incorporating operator consolidation rates, regulatory implementation timelines, and biometric module adoption patterns across the analysis window.
Underlying assumptions cover steady MiCA implementation progress, sustained FinCEN enforcement posture, and stable East Asian semiconductor supply, with deviation risk concentrated in geopolitical trade disruptions and state-level licensing reciprocity failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market