
 Mexico Digital Wallet Market | 2026-2036
Mexico Digital Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital Wallet Market Insights
Merchant acceptance networks is broadening across Mexico's informal economy, drawing new small-business buyers into digital payment ecosystems. Mercado Pago leverages its e-commerce origin to anchor merchant onboarding in tier-two cities. Clip competes through point-of-sale hardware integration that sustains street-vendor adoption. Kueski specializes in credit-linked wallet services that differentiate its value proposition for underbanked segments.
A digital wallet constitutes a software-based payment system that stores encrypted financial credentials, transaction tokens, and authentication keys on mobile devices or cloud servers, executing fund transfers through tokenized card numbers or direct bank APIs. Its primary commercial purpose is to displace cash handling and card-present infrastructure for retail and service transactions. NFC-based contactless payments lead transaction volume among payment types due to terminal proliferation at Mexican retailers. QR code technology is accelerating fastest among small-business end users, where low hardware barriers reduce merchant setup costs. Blockchain-based remittances occupy a narrower but higher-margin service type segment, capturing cross-border flow commissions.
Banxico's instant payment infrastructure CoDi and CNBV fintech licensing requirements shape product architecture and capital reserves for wallet operators. SEPROB data protection standards and anti-money laundering protocols under the national banking regulator enforce KYC depth and transaction monitoring thresholds. Stakeholders must monitor regulatory tightening on open finance APIs and interchange fee caps, as these will determine margin structures and partnership economics for wallet providers serving Mexico's cash-dominant economy.
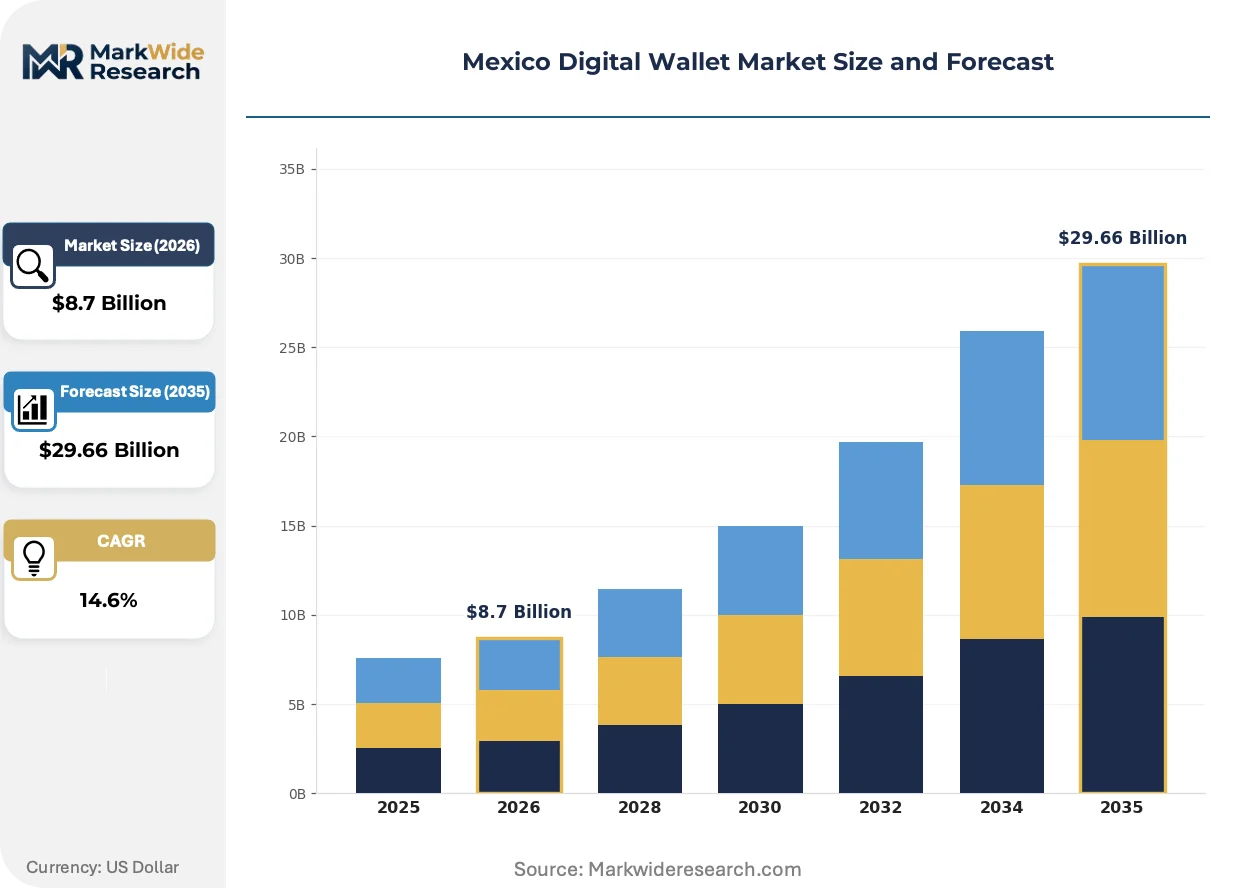
Market Dynamics
Banxico's CoDi instant payment infrastructure is compressing settlement timelines and forcing wallet operators to rebuild core architecture around real-time rails rather than batch-processed card networks.
Growth Catalysts
- CNBV Fintech Licensing:Mexico's structured licensing pathway under the national banking regulator reduces regulatory uncertainty for new entrants. Capital reserve requirements create tiered entry barriers that favor well-capitalized operators.
- QR Code Proliferation:Street vendors and informal merchants adopt QR-based acceptance due to minimal hardware requirements. Terminal-free onboarding expands addressable merchant base beyond traditional POS-dependent retailers.
- Guadalajara Cluster Density:Mexico's second-largest metropolitan area concentrates fintech talent and merchant digitization demand. Regional banking penetration intersects with high smartphone ownership rates.
Market Restraints
- Cash Handling Infrastructure:Mexico's extensive correspondent banking network for cash-in/cash-out services creates persistent operational drag. Last-mile cash logistics consume margin that digital-native models cannot easily displace.
- Interchange Fee Uncertainty:Banxico's ongoing review of merchant discount rates threatens revenue models built on card-present economics. Fee compression would force wallet providers toward alternative monetization paths.
- SEPROB Compliance Burden:Data protection standards mandate encryption protocols and breach notification timelines that increase fixed technology costs. Smaller operators face disproportionate compliance resource demands.
Strategic Opportunities
- Nuevo León Merchant Base:Monterrey's industrial corridor presents underpenetrated SME segments with higher transaction values than street-vendor economies. Manufacturing supply chain payments remain largely cash-based.
- CoDi-API Convergence:Open finance frameworks enable wallet providers to embed instant payment rails directly into accounting and ERP systems. B2B payment flows currently outside digital wallet capture represent expansion territory.
- Cross-Border Remittance Linkage:Blockchain settlement protocols for US-Mexico corridors command premium commissions unavailable in domestic P2P transfers. Regulatory clarity on virtual asset service providers would unlock this segment.
Industry Challenges
- KYC Engineering Talent Scarcity:Biometric identity verification and document authentication systems require specialized machine learning expertise. Mexican fintechs compete with global technology firms for this limited talent pool.
- Legacy Core Banking Integration:Incumbent financial institutions operate on batch-processed mainframe architectures. Real-time wallet connectivity demands expensive middleware development and sustained API maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital Wallet Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Contactless Payments, Peer-to-Peer Transfers, In-App Purchases, Bill Payments End User: Retail Customers, Small Businesses, Large Enterprises, E-commerce Platforms Technology: NFC, QR Code, EMV, Blockchain Service Type: Mobile Banking, Remittances, Loyalty Programs, Financial Management |
| Companies Covered | Mercado Pago, Clip, Kueski, PayPal Mexico, OXXO Pay, BBVA Wallet, Citibanamex, Nubank Mexico, Bitso, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital Wallet Market Trends and Innovations
Tokenized credential storage and NFC terminal proliferation are restructuring how Mexican consumers authenticate transactions. Three developments merit particular attention.
Cloud-native wallet architecture is modularizing core payment functions into discrete microservices. Tier-two city fintechs adopt containerized deployment faster than Mexico City incumbents burdened by legacy infrastructure. This modularization enables rapid feature iteration without full-stack rebuilds, compressing product development cycles from quarters to weeks.
Banxico's open finance regulatory roadmap is mandating standardized API disclosure for account aggregation and payment initiation. Wallet operators must rebuild data architecture around customer consent management and third-party access protocols. The SME lending segment faces the steepest compliance curve as credit-linked wallet services require enhanced data sharing frameworks.
Informal economy merchants are unbundling payment acceptance from banking relationships entirely. Street vendors now select wallet providers based on same-day settlement speed rather than traditional bank affiliation. Puebla and León exhibit the most pronounced behavioral shift, where merchant churn between competing wallet apps has compressed to under six months.
Mexico Digital Wallet Market Segmentation
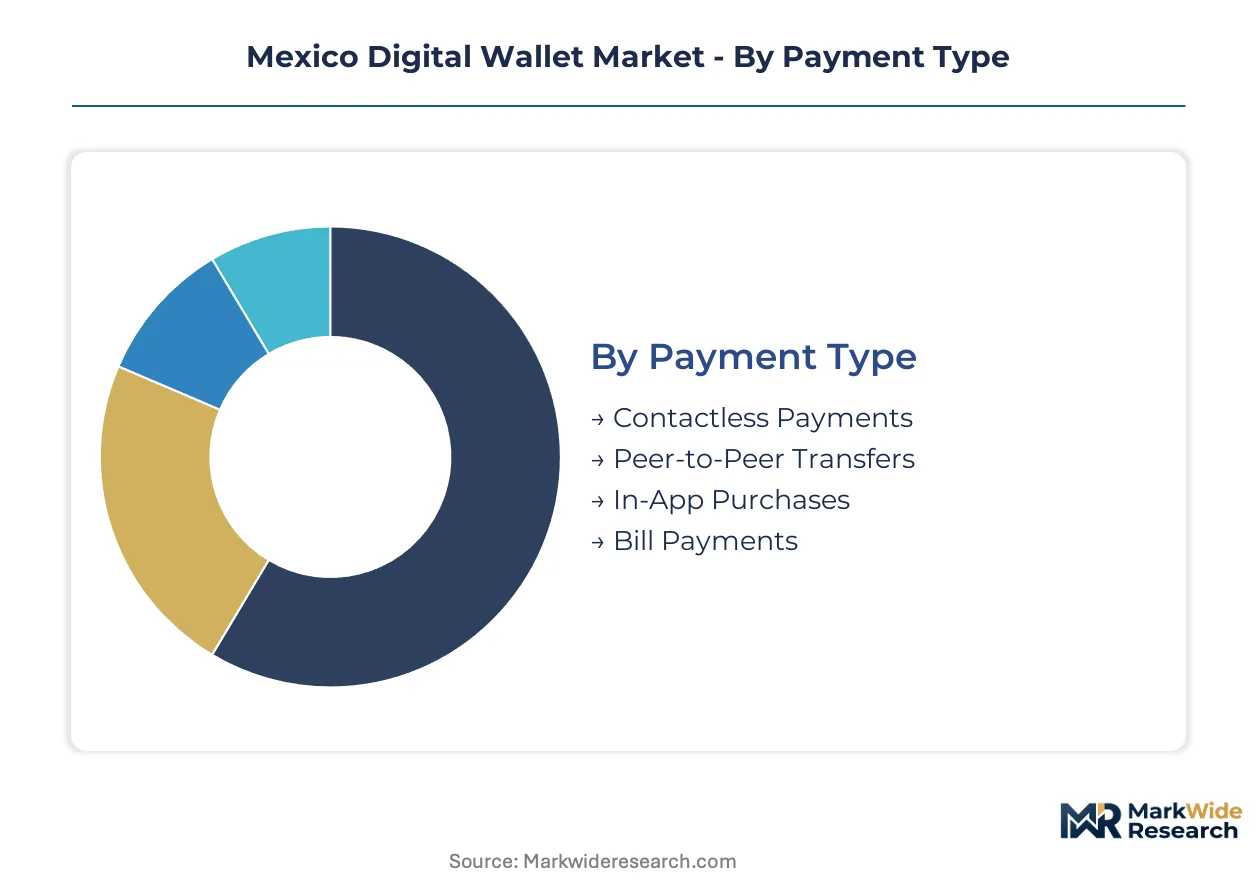
Mexico's digital wallet market segments around payment velocity requirements and merchant infrastructure maturity. Distinct technology choices and service models align with informal economy penetration versus formal banking integration.
Payment Type:
Merchant acceptance infrastructure and transaction settlement speed drive buyer selection across payment modalities.
- Contactless Payments:NFC-enabled terminals execute tokenized card credentials through proximity authentication. Mexico City and Guadalajara retailers concentrate demand where terminal density supports sub-second transaction completion.
- Peer-to-Peer Transfers:Direct wallet-to-wallet fund movement bypasses traditional banking rails through CoDi integration. Urban underbanked populations and informal workers concentrate adoption where cash displacement urgency intersects with smartphone penetration.
- In-App Purchases:Embedded checkout within merchant applications stores credential tokens for one-tap authorization.
- Bill Payments:Recurring utility and service settlements through scheduled wallet debits.
Contactless Payments leads on scale; Peer-to-Peer Transfers leads on momentum.
End User:
Operational complexity and transaction volume thresholds separate wallet feature requirements across customer tiers.
- Retail Customers:Individual consumers seeking personal fund storage, peer transfers, and retail checkout. Mexico City's dense merchant digitization drives concentration where smartphone ownership and informal employment overlap.
- Small Businesses:Street vendors and micro-merchants requiring low-friction acceptance without terminal investment. QR code technology enables penetration where hardware costs previously excluded informal merchants from electronic payments.
- Large Enterprises:Corporate treasury operations and employee disbursement programs.
- E-commerce Platforms:Online merchants integrating wallet checkout into digital storefronts.
Retail Customers dominates transaction volume; Small Businesses dominates expansion velocity.
Technology:
Hardware deployment economics and authentication reliability shape technology adoption curves.
- NFC:Near-field communication enables tap-to-pay authentication through encrypted token exchange. Established retailers in metropolitan corridors concentrate deployment where terminal infrastructure investment has already occurred.
- QR Code:Optical scanning of merchant-generated codes initiates payment without specialized hardware. Tier-two cities and street-vendor economies concentrate fastest uptake where zero terminal cost removes adoption barriers.
- EMV:Chip-card compliance standards for card-present security.
- Blockchain:Distributed ledger settlement for cross-border remittance corridors.
NFC retains installed base dominance; QR Code gains share fastest in new merchant acquisition.
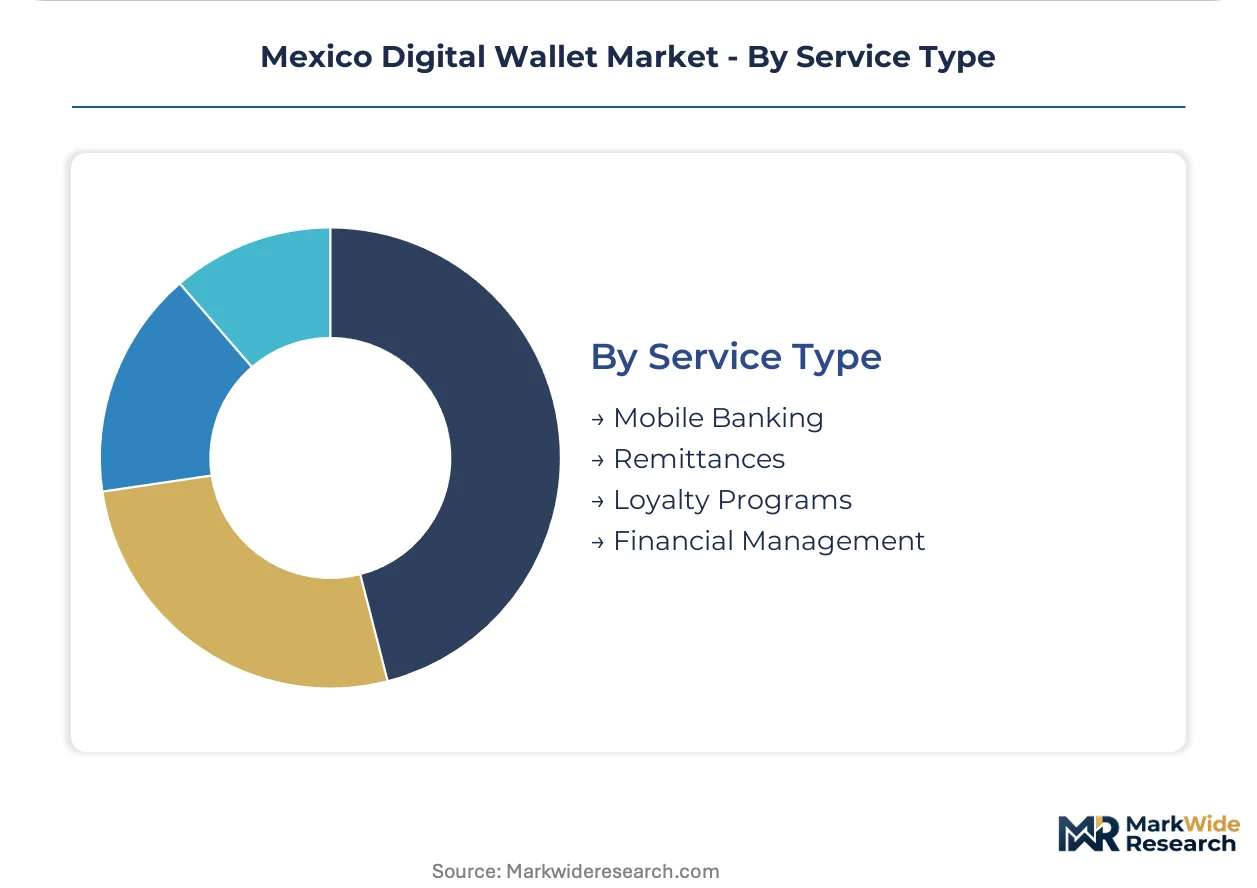
Service Type:
Revenue model sustainability and customer lifetime value differentiate service architecture choices.
- Mobile Banking:Core deposit, transfer, and payment functions replacing traditional checking accounts. Underbanked segments in Guadalajara and Puebla concentrate demand where branch banking access remains limited.
- Remittances:Cross-border fund movement capturing fees on US-Mexico corridor flows. Blockchain settlement protocols command premium pricing unavailable in domestic transfers.
- Loyalty Programs:Points accumulation and merchant-funded rewards integrated into wallet interfaces.
- Financial Management:Budgeting tools and spending analytics layered atop transaction data.
Mobile Banking anchors daily active usage; Remittances delivers highest per-transaction margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's digital wallet penetration outpaces Central American neighbors yet trails Brazil's merchant density, creating a mid-tier competitive intensity shaped by informal economy scale and regulatory maturation.
Mexico City Metro
Merchant digitization and consumer banking penetration intersect most densely here. Banxico's CoDi instant payment infrastructure mandates real-time settlement standards that reshape wallet architecture. Polanco and Santa Fe financial districts concentrate fintech talent pools where NFC terminal density supports sub-second transaction completion.
Nuevo León
Monterrey's industrial corridor presents underpenetrated SME segments with higher transaction values than street-vendor economies. CNBV fintech licensing requirements enforce capital reserve tiers that favor well-capitalized operators entering this manufacturing-heavy market. San Pedro Garza García anchors corporate treasury demand for B2B payment integration.
Jalisco
Guadalajara concentrates fintech talent and merchant digitization demand where regional banking penetration meets high smartphone ownership. SEPROB data protection standards mandate encryption protocols that increase fixed technology costs for operators. Zapopan's technology park clusters cloud-native wallet developers adopting containerized deployment.
Bajío Region
León and Puebla exhibit pronounced behavioral shifts where merchant churn between competing wallet apps has compressed to under six months. QR code proliferation enables street-vendor adoption where zero terminal cost removes hardware barriers. Automotive supply chain payments in Querétaro remain largely cash-based, representing expansion territory.
Northern Border States
Cross-border remittance flows from US-Mexico corridors command premium commissions unavailable in domestic transfers. Blockchain settlement protocols occupy a narrower but higher-margin service segment here. Tijuana and Ciudad Juárez concentrate demand for instant peso-dollar conversion where regulatory clarity on virtual asset service providers would unlock growth.
Mexico Digital Wallet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's digital wallet market. E-commerce origin platforms leverage merchant networks while banking incumbents deploy regulatory relationships. Three archetypes dominate: e-commerce-anchored wallets, banking-affiliated payment apps, and fintech-native specialists. Competitive moves center on QR code merchant acquisition and CoDi rail integration partnerships.
Among e-commerce-derived operators, Mercado Pago anchors merchant onboarding in tier-two cities through marketplace integration. Clip exemplifies hardware-integrated specialists competing via point-of-sale terminal penetration. Kueski occupies the credit-linked tier, differentiating through underbanked segment focus. These three represent distinct strategic positioning vectors rather than convergent capability stacks.
| Leading Market Players |
|---|
| Mercado Pago |
| Clip |
| Kueski |
| PayPal Mexico |
| OXXO Pay |
| BBVA Wallet |
| Citibanamex |
| Nubank Mexico |
| Bitso |
| Others |
Pricing and Supply Chain Analysis
CoDi instant payment rail adoption simultaneously compresses transaction settlement costs and concentrates infrastructure investment among wallet operators with sufficient capital reserves to rebuild core architecture around real-time settlement. This technology shift reshapes both merchant-facing pricing power and the geographic distribution of cloud-native development talent.
Pricing Analysis
Capacity additions in Guadalajara and Mexico City are reshaping price floors for QR-code merchant acquisition as competing wallet operators subsidize onboarding to capture informal economy market share. Three-tier pricing structure across premium API-integrated, standard self-serve, and economy cash-in/cash-out tiers dominates revenue architecture. Price differentiation rests on settlement speed tiers and KYC depth rather than hardware bundling. Cost compression in the economy tier is intensifying because OXXO's correspondent network maintains cash-out dominance. Small businesses in Puebla and León exhibit highest price sensitivity; corporate treasury clients in San Pedro Garza García show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries supplying NFC terminal chipsets and biometric authentication processors. Hardware manufacturing concentrates in China, Mexico, and Vietnam for point-of-sale terminals and QR display devices. Cloud infrastructure draws from US hyperscaler regions and São Paulo data centers. Supply chain risk centers on tariff exposure for terminal imports under USMCA compliance reviews. Distribution runs through direct enterprise sales teams for large merchants and independent agent networks for street-vendor acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's digital wallet market functions as a geographic-arbitrage play where Banxico's CoDi infrastructure costs undercut Brazil's higher regulatory compliance burdens while offering superior settlement speed to Central American corridors.
For Market Incumbents: Hedge against QR-code commoditization by deepening CoDi-API integration into SME accounting systems and securing exclusive partnerships with Nuevo León manufacturing clusters. Threat from credit-linked fintech specialists like Kueski demands defensive investment in embedded lending capabilities. Vertical integration into cloud-native microservices development preserves iteration speed against legacy banking competitors. For New Entrants and Emerging Players: Independent software vendors and ERP system integrators represent the most accessible channel partner type for white-label wallet embedding. Monterrey's industrial SME segment offers lowest competitive density with highest transaction values per merchant. Guadalajara's technology park ecosystem provides talent access for containerized deployment without Mexico City cost structures. Target automotive supply chain payments in Querétaro through B2B invoice factoring integration. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-integrated specialists with concentrated street-vendor bases and unproven path to software margin expansion. Long-term viability over the next decade hinges on open finance API monetization and cross-border remittance corridor capture. Acquisition target archetype: cloud-native developers with CoDi rail certification and established QR merchant networks in tier-two cities. Watch Banxico interchange fee rulings as the critical inflection signal for margin structure durability.| Strategic Initiative | Industry Significance |
|---|---|
| CoDi Rail Integration | Banxico's instant payment infrastructure mandates real-time settlement architecture rebuilds for competitive parity. |
| QR Merchant Acquisition | Terminal-free onboarding expands addressable base into street-vendor economies across Puebla and León. |
| Credit-Linked Wallet Services | Underbanked segment penetration through Kueski-style embedded lending differentiates beyond pure payments. |
| Cross-Border Remittance Blockchain | US-Mexico corridor premium commissions require regulatory clarity on virtual asset service provider licensing. |
| Open Finance API Partnership | SEPROB-compliant data sharing frameworks enable SME lending and accounting system embedding. |
Research Methodology
Bottom-up merchant and consumer adoption modeling reconciled against top-down fintech licensing and transaction volume tracking forms the analytical core of this study. Primary interviews with CNBV regulatory affairs officers, wallet platform CTOs, street-vendor merchant network managers, and correspondent banking operations heads combined with secondary validation from Banxico payment system reports, SEPROB data protection filings, and fintech capital reserve disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map CoDi transaction velocity, QR code deployment rates, and NFC terminal density against wallet operator revenue per user across the projection horizon. Segmentation dimensions include payment type, end-user tier, technology modality, and service architecture. CAGRs derive from curve-fitting adoption S-cycles against smartphone penetration thresholds and merchant digitization policy milestones. Forecast inputs incorporate Banxico regulatory roadmap timing and informal economy cash displacement elasticity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interchange fee cap rulings and open finance API standardization delays. Forecasts reflect documented assumptions about CoDi rail adoption velocity and CNBV licensing pace. Specific risks that could revise projections include SEPROB compliance burden increases, legacy core banking integration failures, and KYC engineering talent scarcity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Point of Sale (POS) Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Europe Payments Market
Payments
Sweden Payments Market
Payments
Saudi Arabia POS Terminal Market
Payments
United Kingdom Mobile Payments Market
Payments
Mobile Wallet Market
Payments
Latin America Payment Gateway Market
Payments
Norway Mobile Payments Market
Payments
Mexico Real Time Payments Market
Payments
Epayment System Market
Payments
Vietnam Payments Market
Payments
Telecom Cloud Billing Market
Payments
United Kingdom Payment Gateway Market
Payments
Smart POS System Market