
 United States Real Time Payments Market | 2026-2036
United States Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United States Real Time Payments Market Analytics
Developer talent with ISO 20022 messaging expertise is rotating toward real-time payment infrastructure projects, tightening supply for legacy batch-system programmers. Fiserv Inc. leverages its merchant-acquiring scale to embed instant payout capabilities across small-business banking portals. The Clearing House Payments Company L.L.C. sustains network dominance through RTP rail ownership that processes credit-push transactions in seconds. Visa Inc. competes by extending its Visa Direct platform into payroll and insurance disbursement verticals.
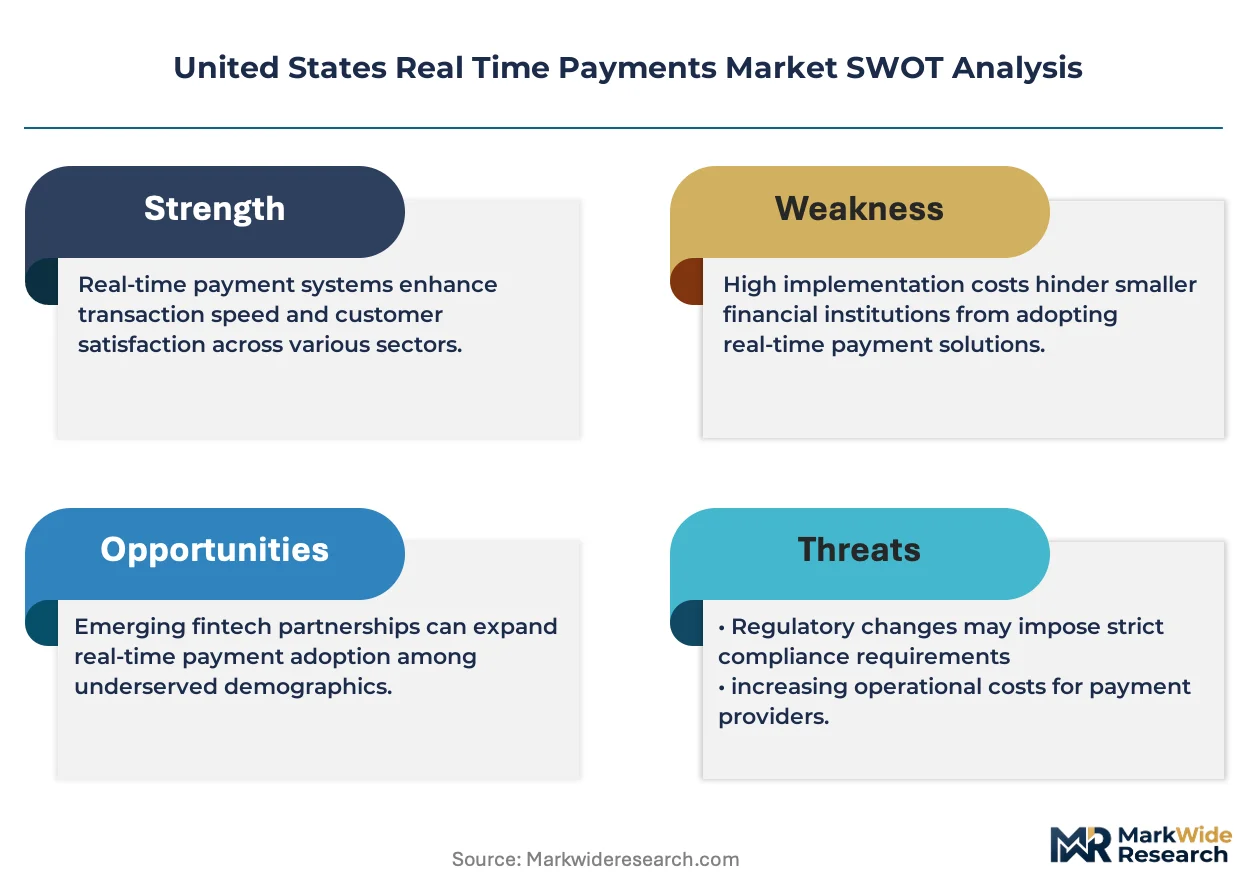
Real time payments denote electronic fund transfers that clear and settle between bank accounts within seconds, operating on ISO 20022 message formats that carry richer remittance data than legacy ACH files. The primary commercial purpose replaces batch-processed payment cycles with continuous availability, reducing working capital friction for businesses and enabling consumer immediacy for peer-to-peer and bill-pay use cases. Mobile Payments technology leads transaction volume growth as smartphone-native authentication displaces card-present habits. Payment Processing services anchor revenue pools, while Fraud Prevention commands expanding margin share as velocity exposes institutions to faster attack windows.
The Federal Reserve's FedNow Service and NACHA operating rules jointly define access standards and liability frameworks for instant payment participation. State-level money transmission licensing, administered variably across all fifty states, fragments provider market entry and elevates compliance costs for multi-state platforms. Stakeholders must monitor whether FedNow volume thresholds trigger correspondent banking repricing that reshapes fintech economics.
Market Dynamics
The Federal Reserve's FedNow Service launch is compressing settlement timelines from days to seconds, forcing banks to rebuild core infrastructure around ISO 20022 messaging standards while merchant demand for instant liquidity reshapes product roadmaps.
Growth Catalysts
- FedNow Service Mandate:The Federal Reserve's instant payment rail creates universal access standards that lower barriers for community banks and credit unions to offer real-time settlement.
- Merchant Working Capital Pressure:Small-business cash flow constraints drive demand for instant payout features embedded in point-of-sale and e-commerce platforms.
- Smartphone-First Authentication:Biometric mobile verification displaces card-present habits, expanding addressable transaction volume for instant push-to-card and account-to-account transfers.
Market Restraints
- State Licensing Fragmentation:Fifty-variable money transmission regimes impose compliance costs that scale disproportionately for multi-state fintech platforms seeking nationwide coverage.
- Core Banking Modernization Costs:Legacy batch-system architectures require wholesale replacement to support 24/7/365 message processing, straining regional bank technology budgets.
- ACH Network Stickiness:NACHA's Same Day ACH service offers sufficient speed for many use cases at lower cost, creating substitution pressure on premium instant rails.
Strategic Opportunities
- Payroll and Insurance Disbursements:Gig-economy worker payments and claims settlement represent underpenetrated verticals where instant settlement commands premium pricing.
- Request-for-Payment Messaging:ISO 20022's richer data fields enable invoice-to-payment automation that reduces accounts-receivable friction for B2B corridors.
- Texas and California Merchant Density:Fintech infrastructure overlap in these state corridors creates concentrated demand for instant settlement services.
Industry Challenges
- ISO 20022 Talent Scarcity:Developer expertise in real-time messaging protocols is rotating toward infrastructure projects, tightening supply for legacy system maintenance.
- Fraud Velocity Exposure:Settlement speed compresses detection windows, requiring real-time risk scoring investments that strain mid-tier bank operational budgets.
- Dual Rail Integration Complexity:Institutions must simultaneously operate The Clearing House's RTP network and FedNow, doubling connectivity and liquidity management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Real Time Payments Market |
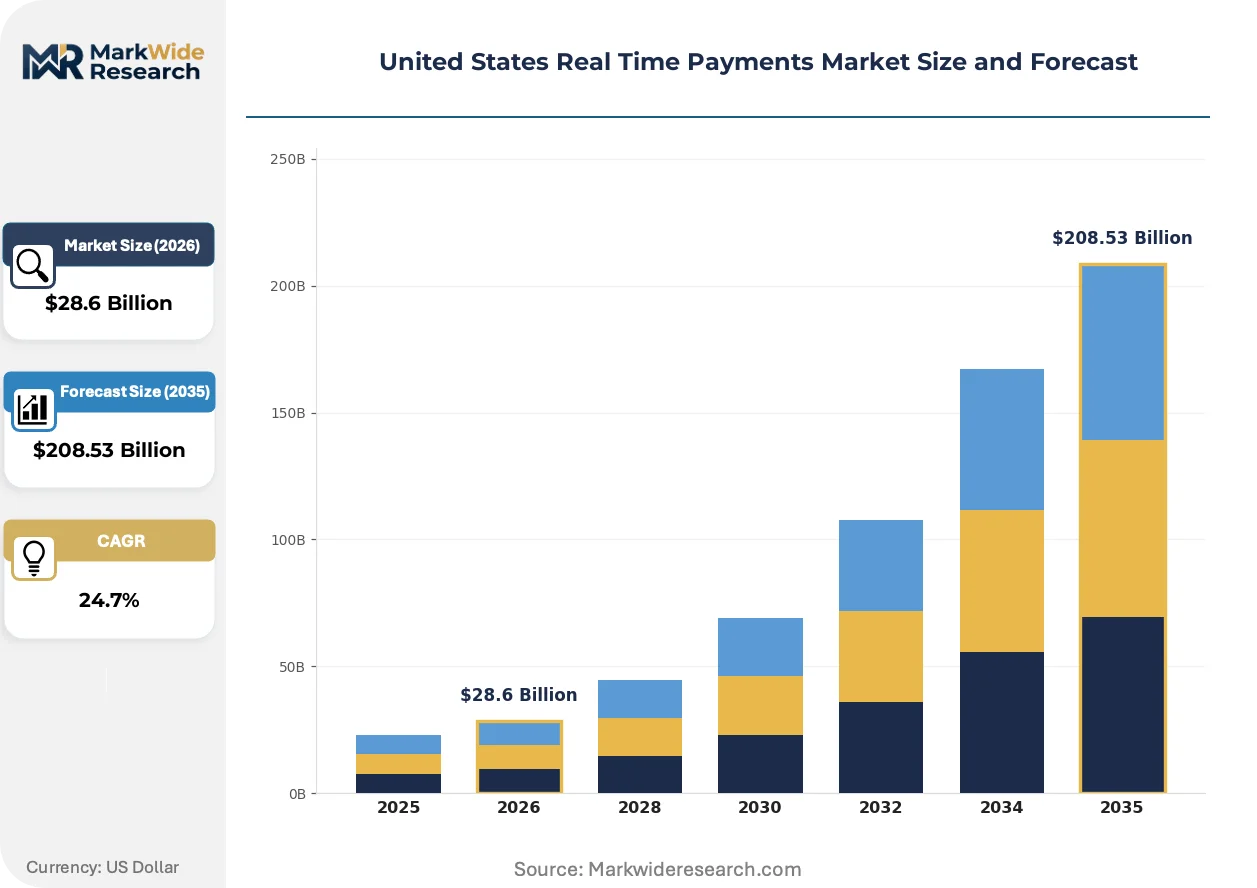
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, ACH, Wire Transfer, Mobile Payments End User: Retail, Banks, Corporates, Government Service Type: Payment Processing, Fraud Prevention, Reconciliation, Settlement Deployment: Cloud-Based, On-Premises, Hybrid, Others |
| Companies Covered | ACI Worldwide Inc., Fidelity National Information Services Inc., Fiserv Inc., Mastercard Incorporated, Visa Inc., The Clearing House Payments Company L.L.C., J.P. Morgan, PayPal Holdings Inc., Early Warning Services LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Real Time Payments Market Evolving Landscape
Payment infrastructure is bifurcating between legacy batch modernization and native real-time architectures, with merchant-facing platforms racing to embed instant settlement as a default feature rather than premium upgrade.
ISO 20022 message formats are fragmenting payment data standards across the United States market. Large banks and payment processors are adopting the richer schema for remittance detail and structured invoice data. Community institutions face compressed timelines to upgrade core systems or risk correspondent banking repricing that erodes fintech partnership economics.
The Federal Reserve's FedNow Service and NACHA operating rules jointly define access standards and liability frameworks for instant payment participation. State-level money transmission licensing fragments provider market entry and elevates compliance costs. Stakeholders must monitor whether FedNow volume thresholds trigger correspondent banking repricing that reshapes fintech economics.
Merchant procurement of payment services is compressing vendor evaluation cycles from annual RFPs to continuous platform switching. Small businesses prioritize instant payout speed over brand loyalty, enabling fintech challengers to displace incumbent bank relationships. This behavior concentrates in Texas and California corridors where merchant density and fintech infrastructure overlap.
United States Real Time Payments Market Segmentation
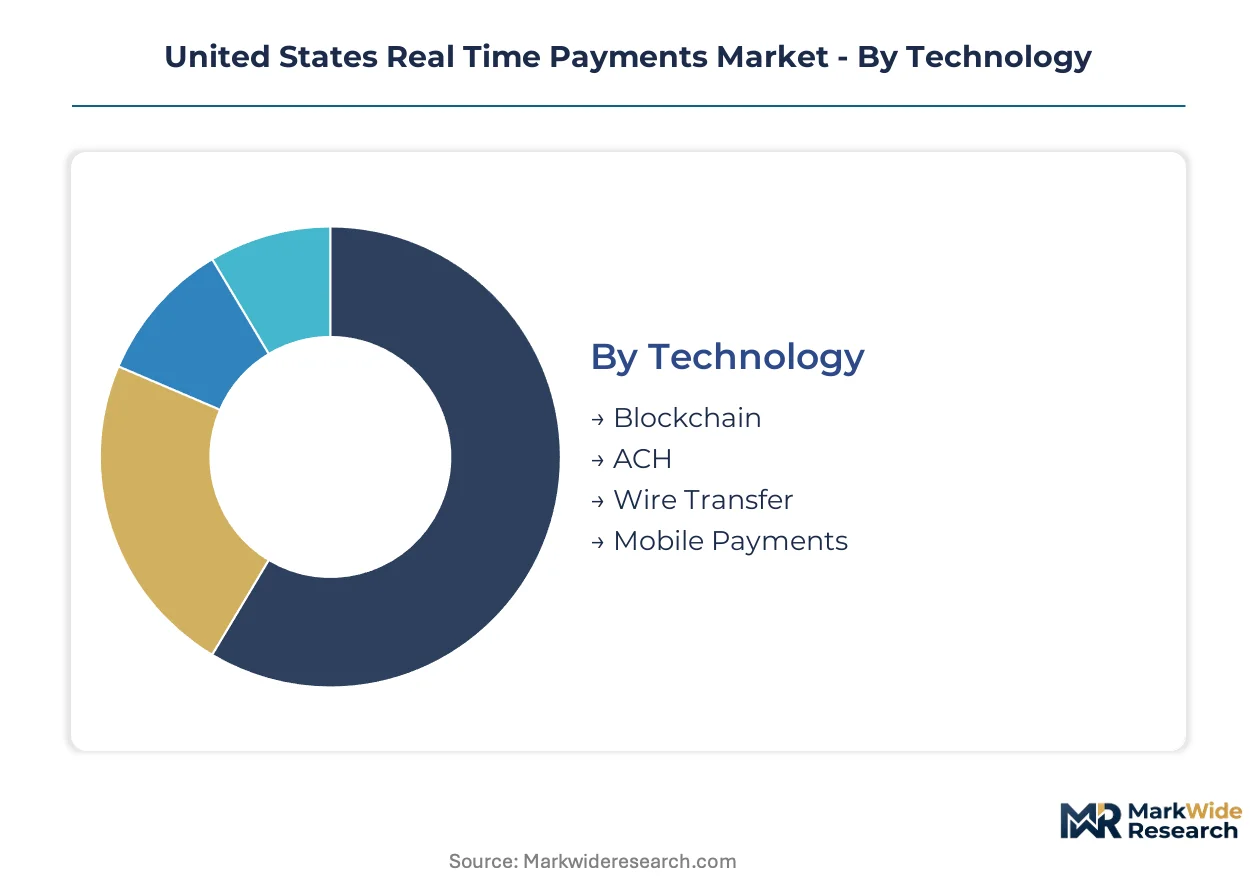
Segmentation in the United States real-time payments market reveals how infrastructure investments and risk appetites distribute across technology layers and institutional types. Understanding these partitions helps vendors align product roadmaps with where adoption friction is lowest and margin capture is highest.
Technology:
Margin pools concentrate in mobile-native authentication stacks and blockchain interoperability layers where implementation complexity sustains premium pricing.
- Mobile Payments:Smartphone-native biometric verification displaces card-present authentication, concentrating volume growth in Texas and California merchant corridors where fintech infrastructure density overlaps with small-business demand for instant settlement.
- ACH:NACHA's Same Day ACH service offers batch-processed speed at lower cost than instant rails, capturing working capital-sensitive merchants who prioritize cost over seconds-level settlement velocity.
- Blockchain:Distributed ledger protocols enable programmable settlement with atomic clearing, attracting crypto-native fintechs seeking disintermediation of correspondent banking relationships.
- Wire Transfer:Legacy high-value rails retain dominance for corporate treasury operations requiring irrevocable same-day settlement with documented audit trails.
Mobile Payments holds installed capacity. Blockchain is rotating up the share rankings.
End User:
Adoption velocity varies sharply by institutional sophistication and regulatory exposure, with tier-one banks moving fastest on FedNow integration.
- Banks:Core system modernization to ISO 20022 messaging standards absorbs the largest technology budgets, with regional institutions facing correspondent banking repricing pressure if volume thresholds lag.
- Retail:Small-business merchants prioritize instant payout features over brand loyalty, compressing vendor evaluation cycles and enabling fintech challengers to displace incumbent relationships in high-density state corridors.
- Corporates:Treasury departments demand Request-for-Payment messaging automation to reduce accounts-receivable friction, driving B2B corridor adoption where invoice-to-payment data richness justifies premium rail costs.
- Government:Federal and state disbursement programs require 24/7 availability for benefit payments, with FedNow Service mandate creating universal access standards that lower barriers for public sector participation.
Banks anchor current infrastructure spend. Retail is expanding most quickly as merchant-facing platforms embed instant settlement as default.
Service Type:
Revenue concentration follows transaction volume in processing services, while fraud prevention commands expanding margin share as settlement speed compresses detection windows.
- Payment Processing:Real-time message routing and liquidity management form the foundational revenue pool, with providers competing on FedNow and RTP rail connectivity redundancy.
- Fraud Prevention:Velocity-sensitive risk scoring requires sub-second decisioning infrastructure, straining mid-tier bank operational budgets and creating vendor consolidation opportunities.
- Settlement:Finality guarantees and prefunded liquidity positioning determine rail reliability, with dual FedNow-RTP integration complexity doubling connectivity overhead for participant institutions.
- Reconciliation:Richer ISO 20022 remittance data enables automated matching of payments to invoices, reducing manual intervention in B2B treasury workflows.
Payment Processing holds installed capacity. Fraud Prevention is climbing the fastest as attack exposure intensifies.
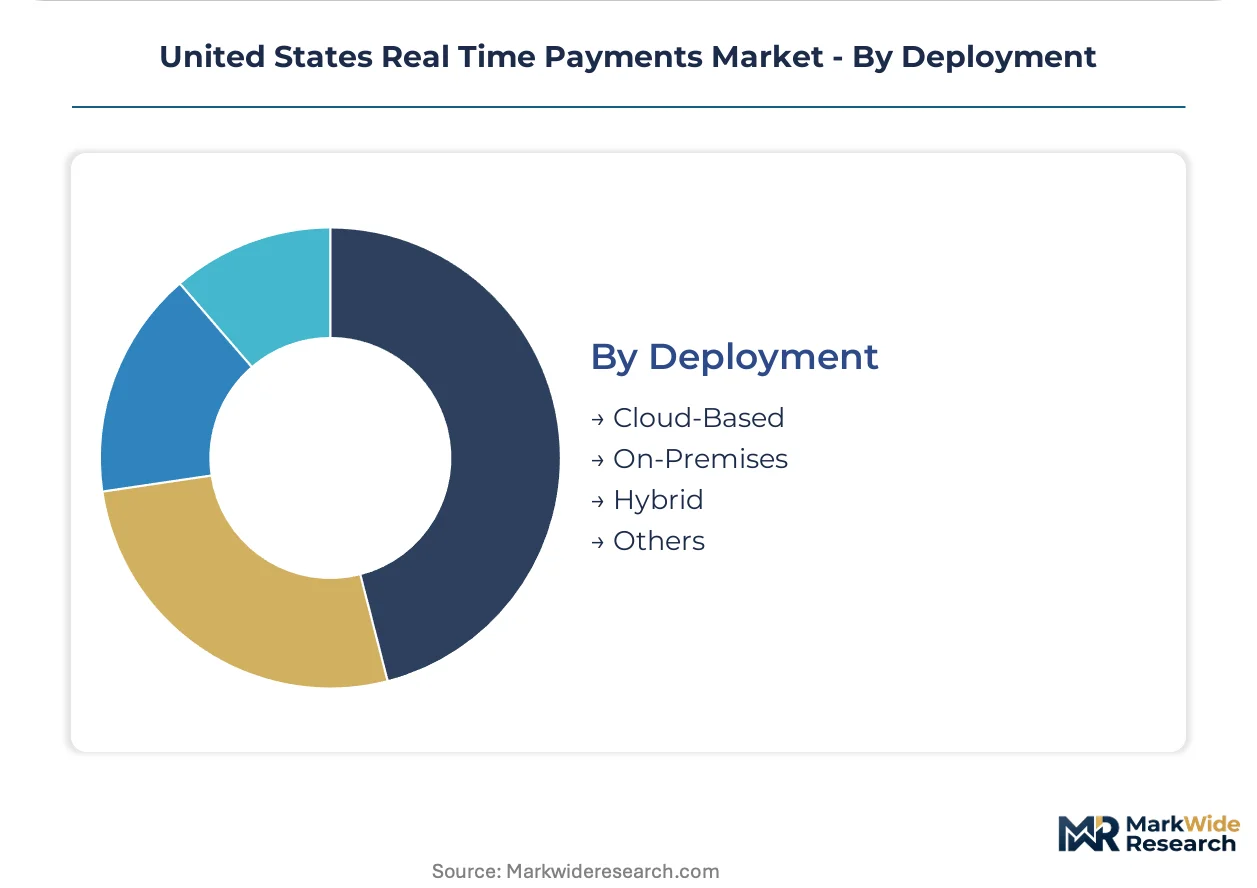
Deployment:
Cloud architectures dominate new implementations, though regulatory data residency requirements sustain hybrid demand among conservative institutions.
- Cloud-Based:Scalable infrastructure enables 24/7/365 message processing without capital-intensive core system replacement, accelerating adoption among community banks and credit unions.
- Hybrid:Sensitive transaction data remains on-premises while message routing leverages cloud elasticity, satisfying state-level money transmission licensing fragmentation without full legacy abandonment.
- On-Premises:Tier-one banks with existing mainframe investments pursue incremental ISO 20022 upgrades rather than wholesale migration, preserving sunk cost in batch-system architectures.
- Others:Managed service and private cloud variants address specific compliance requirements in fragmented regulatory environments.
Cloud-Based holds installed capacity. Hybrid is gaining share fastest as compliance complexity outpaces full modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California corridors exhibit distinct consumption patterns from Midwest and Northeast markets, with merchant density and fintech infrastructure overlap driving instant settlement adoption in Sun Belt corridors while legacy banking relationships slow conversion elsewhere.
Texas
Small-business merchant clusters in Dallas-Fort Worth and Houston generate concentrated demand for instant payout features embedded in point-of-sale platforms. State-level money transmission licensing administered by the Texas Department of Banking imposes compliance costs that favor established processors over new entrants. The Austin-San Antonio corridor anchors fintech infrastructure development, with real-time payment rail connectivity expanding through regional bank partnerships.
California
Silicon Valley technology firms and Los Angeles entertainment industry payroll operations drive B2B disbursement volume for instant settlement rails. The California Department of Financial Protection and Innovation enforces money transmission rules that fragment provider market entry across the nation's largest state economy. San Francisco and San Diego merchant corridors concentrate demand for smartphone-native authentication displacing card-present habits.
New York Metro
Treasury departments of financial services firms in Manhattan demand Request-for-Payment messaging automation for accounts-receivable friction reduction. The New York State Department of Financial Services administers BitLicense and money transmission frameworks that elevate compliance costs for multi-state platforms. Brooklyn and Queens small-business corridors show accelerating merchant switching behavior prioritizing instant payout speed over brand loyalty.
Florida
Miami-Dade tourism and hospitality merchants prioritize instant settlement for working capital liquidity management in seasonal revenue environments. The Florida Office of Financial Regulation oversees money transmission licensing with requirements that scale disproportionately for nationwide platform coverage. The Tampa-Orlando corridor exhibits growing fintech infrastructure density supporting real-time payment adoption among regional banks.
Illinois
Chicago corporate treasury operations sustain wire transfer dominance for high-value settlement requiring irrevocable same-day finality with documented audit trails. The Illinois Department of Financial and Professional Regulation administers state-level compliance frameworks affecting payment processor market entry. The metro area's community banks face correspondent banking repricing pressure as FedNow volume thresholds reshape fintech partnership economics.
United States Real Time Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with network ownership and merchant-acquiring scale determining competitive position in real-time payment infrastructure. The market structure concentrates around rail operators and payment processors with existing correspondent banking relationships. Three archetypes dominate: network infrastructure owners, merchant-facing platform integrators, and risk-scoring technology specialists. Competitive moves center on dual-rail connectivity investments and ISO 20022 messaging standard upgrades.
Within the network infrastructure tier, The Clearing House Payments Company L.L.C. and FedNow Service exemplify rail ownership models that process credit-push transactions in seconds. Among merchant-acquiring specialists, Fiserv Inc. and ACI Worldwide Inc. occupy positions leveraging scale to embed instant payout capabilities across small-business banking portals. Visa Inc. anchors the push-to-card segment, extending platform reach into payroll and insurance disbursement verticals.
| Leading Market Players |
|---|
| ACI Worldwide Inc. |
| Fidelity National Information Services Inc. |
| Fiserv Inc. |
| Mastercard Incorporated |
| Visa Inc. |
| The Clearing House Payments Company L.L.C. |
| J.P. Morgan |
| PayPal Holdings Inc. |
| Early Warning Services LLC |
| Others |
Value Network & Pricing Analysis
State-level money transmission licensing administered variably across all fifty states gates both provider qualification and price differentiation simultaneously, fragmenting market entry for multi-state platforms while enabling incumbent processors to command premium pricing through compliance scale economies.
Pricing Analysis
Long-term offtake contracts dominate enterprise banking relationships, while spot-market transactional pricing prevails among small-business merchants. Three-tier pricing structure across premium, standard, and economy levels differentiates by settlement speed tier and fraud protection depth. Cost compression in the standard tier is intensifying because NACHA's Same Day ACH offers sufficient velocity at lower cost. Regional banks exhibit highest price sensitivity due to core modernization budget constraints, while tier-one institutions prioritize rail redundancy over unit economics.
Supply Chain Analysis
Just-in-time liquidity positioning dominates real-time payment infrastructure, with participant institutions minimizing prefunded balances while maintaining settlement finality guarantees. Core technology supply concentrates in the United States, Ireland, and India, drawing from specialized ISO 20022 messaging protocol developers and cloud infrastructure providers. Single-source vulnerability in FedNow and RTP dual-rail connectivity creates operational risk for regional banks. Distribution runs through correspondent banking relationships and direct fintech-platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fraud prevention services represent the fastest-expanding recurring-revenue layer, outpacing hardware-dependent payment processing margins as settlement velocity compresses detection windows and mandates continuous risk-scoring investments.
For Market Incumbents: Consolidate ISO 20022 talent pools through targeted acquisition of messaging-protocol specialists before developer scarcity tightens further. Deepen correspondent banking relationships in Texas and California corridors where merchant density and fintech infrastructure overlap, defending against fintech challengers exploiting small-business switching behavior.
For New Entrants and Emerging Players: Anchor in payroll and insurance disbursement verticals where instant settlement commands premium pricing and incumbent penetration remains limited. Target mid-tier regional banks facing dual-rail integration complexity and fraud-velocity budget strain, offering managed-service ISO 20022 modernization to bypass core replacement timelines.
For Investors and Strategic Acquirers: FedNow volume threshold triggers reshaping correspondent banking repricing reshape the acquisition landscape toward fintech platforms with established rail connectivity and state-level licensing coverage. Long-term viability centers on recurring fraud-prevention revenue streams rather than transactional processing volume. The signal to watch is mid-tier bank outsourcing acceleration as operational budgets strain under 24/7/365 infrastructure demands.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Rail Connectivity Investment | Simultaneous FedNow and RTP integration reduces settlement risk for participant institutions. |
| ISO 20022 Talent Acquisition | Messaging-protocol expertise scarcity threatens modernization timelines for regional banks. |
| Fraud Prevention Platform Launch | Sub-second risk scoring addresses velocity-sensitive attack exposure in instant rails. |
| State Licensing Consolidation | Multi-state compliance scale economies create pricing power against fragmented entrants. |
| Request-for-Payment Automation | Richer remittance data reduces accounts-receivable friction in B2B treasury workflows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment infrastructure executives, core banking technology officers, merchant acquiring specialists, and fraud prevention vendors. Secondary validation drew from Federal Reserve payment system reports, NACHA operating rule filings, state banking regulator licensing databases, and SEC disclosures from publicly traded processors. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including technology layer, end-user institutional type, service category, and deployment architecture. CAGRs were derived from trend extrapolation of rail adoption curves and merchant switching behavior patterns. Forecast inputs incorporated FedNow volume threshold triggers and ISO 20022 migration timelines for correspondent banking repricing scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory fragmentation and merchant working capital pressure; material deviation would warrant model refresh. Revision becomes warranted when NACHA Same Day ACH velocity upgrades or federal preemption of state licensing regimes cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America Payment Analytics Software Market
Payments
Japan Mobile Payments Market
Payments
France Buy Now Pay Later Services Market
Payments
Argentina Mobile Wallet Market
Payments
Global Financial Cards and Payments Market
Payments
Estonia POS Terminal Market
Payments
China Real Time Payments Market
Payments
Cross-Border Payment Platform Market
Payments
Vietnam Payments Market
Payments
Canada Mobile Payments Market
Payments
Singapore Remittance Market
Payments
Master Recharge API Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Global Mobile Payment Technology Market
Payments
Europe Payment Analytics Software Market
Payments
Remote Mobile Payment Market