
 Crypto Asset Management Platform Market | 2026-2036
Crypto Asset Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Asset Management Platform Market Outlook
Multi-party computation technology is rewriting security architectures for digital asset custody, replacing single-signature wallets with distributed key management. Fireblocks leverages this infrastructure to anchor institutional settlement workflows across exchanges and custodians. Coinbase sustains geographic dominance through its regulated exchange-custody bundle, while Anchorage Digital differentiates via OCC national trust charter status and bank-grade compliance frameworks.
A crypto asset management platform comprises software systems that automate portfolio construction, risk quantification, regulatory reporting, and tax-loss harvesting across blockchain-based instruments, typically interfacing with on-chain data via RPC nodes and oracle feeds. The platform's primary commercial purpose is to reduce operational friction and counterparty exposure for holders of volatile, pseudonymous digital assets. Portfolio management and compliance monitoring command the deepest margin pools as fiduciary liability and audit trail requirements intensify. Hybrid cloud deployments gain traction among fund managers balancing latency sensitivity against data sovereignty mandates.
SEC registration under the Investment Advisers Act, MiCA licensing through EU national competent authorities, and Singapore MAS payment institution frameworks collectively determine market access and product permissibility across major jurisdictions. These regimes force platform operators to maintain segregated cold storage, real-time proof-of-reserves, and transaction surveillance or forfeit institutional clientele. Stakeholders must monitor how jurisdictional arbitrage between fragmented regulatory regimes reshapes custody location decisions and platform licensing strategies.
Market Dynamics
Multi-party computation infrastructure is fragmenting custody architectures and forcing platform operators to rebuild security stacks around distributed key management rather than centralized HSM vaults.
Growth Catalysts
- MiCA Licensing Deadlines:European asset managers face compressed compliance timelines that accelerate platform procurement for automated reporting and custody documentation.
- Institutional Fiduciary Standards:Pension funds and endowments now mandate segregated cold storage and real-time proof-of-reserves, driving demand for compliant infrastructure.
- Singapore MAS Frameworks:Payment institution licensing clarity attracts hedge funds and family offices to establish regional treasury operations.
Market Restraints
- Specialized Cryptography Talent Scarcity:Zero-knowledge proof engineers and MPC protocol developers command compensation premiums that inflate platform development costs.
- Cloud Infrastructure Concentration:AWS and Azure dominance in institutional data centers creates single-provider vulnerability for latency-sensitive trading operations.
- Cross-Border Regulatory Arbitrage Friction:Divergent SEC custody rules and EU MiCA definitions force platforms to maintain redundant compliance stacks.
Strategic Opportunities
- Tokenized Real-Asset Integration:Private equity and real estate fund administrators seek platforms capable of handling both crypto-native and security-token instruments.
- Tax-Loss Harvesting Automation:High-net-worth advisory channels demand embedded wash-sale monitoring and jurisdictional tax-optimization engines.
- Hybrid Cloud Deployments:Swiss and Liechtenstein fund managers pursue sovereign data residency with sub-millisecond exchange connectivity.
Industry Challenges
- Legacy Core Banking Integration:Mainframe reconciliation systems at traditional custodians resist API-native connectivity, extending implementation timelines.
- Audit Trail Standardization Gaps:Absence of uniform on-chain attestation formats complicates external verification and fiduciary liability management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Asset Management Platform Market |
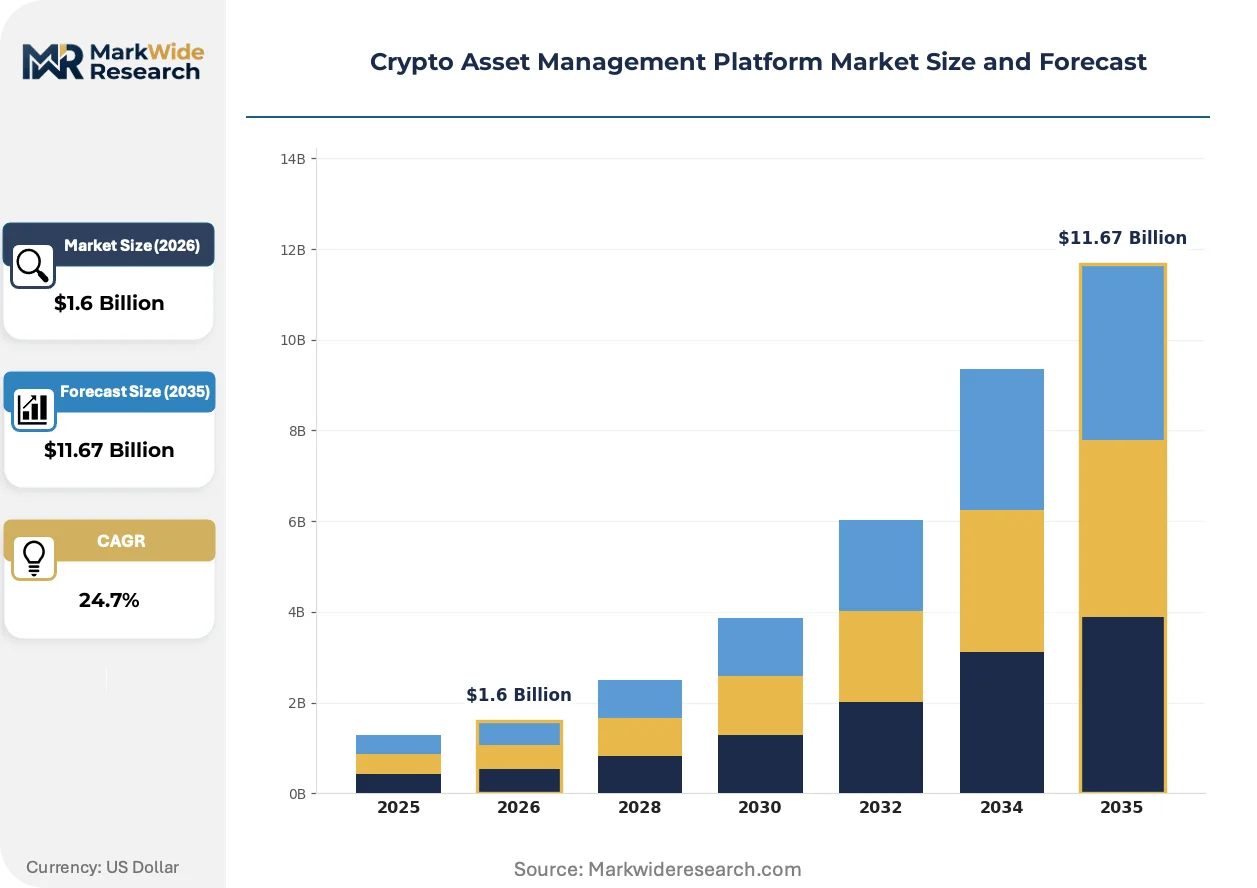
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $11.67 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Portfolio Management, Risk Assessment, Compliance Monitoring, Tax Optimization Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise End User: Institutional Investors, Retail Traders, Fund Managers, Wealth Advisors Integration Level: API Integration, Standalone, Multi-Channel, System Interoperability |
| Companies Covered | Coinbase, Binance, BitGo, Anchorage Digital, Gemini Trust Company, Fidelity Digital Assets, Bakkt, Fireblocks, Paxos Trust Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Asset Management Platform Market Strategic Shifts
Platform architectures are converging around programmable compliance and automated risk quantization, compressing the operational gap between traditional asset servicing and digital-native custody.
Multi-party computation with hardware security module hybrids is rendering obsolete single-signature cold storage and centralized key ceremonies. Institutional allocators now require distributed signing authority across three or more independent parties. This shift compresses counterparty exposure and eliminates single-point-of-failure liabilities that previously required expensive insurance overlays.
SEC registration under the Investment Advisers Act now mandates qualified custodian verification for all crypto advisory relationships. Fund administrators must demonstrate segregated wallet architectures and real-time reserve attestations or forfeit institutional mandates. US-registered investment advisers are responding by consolidating vendor relationships around OCC-chartered trust companies with federal banking compliance frameworks.
Family office direct indexing is displacing commingled fund structures for crypto exposure. Ultra-high-net-worth principals now demand bespoke portfolio construction with granular tax-lot control and custom ESG screening. This behavioral pivot concentrates in Singapore and Dubai, where private wealth infrastructure supports direct custody relationships alongside traditional banking arrangements.
Crypto Asset Management Platform Market Segmentation
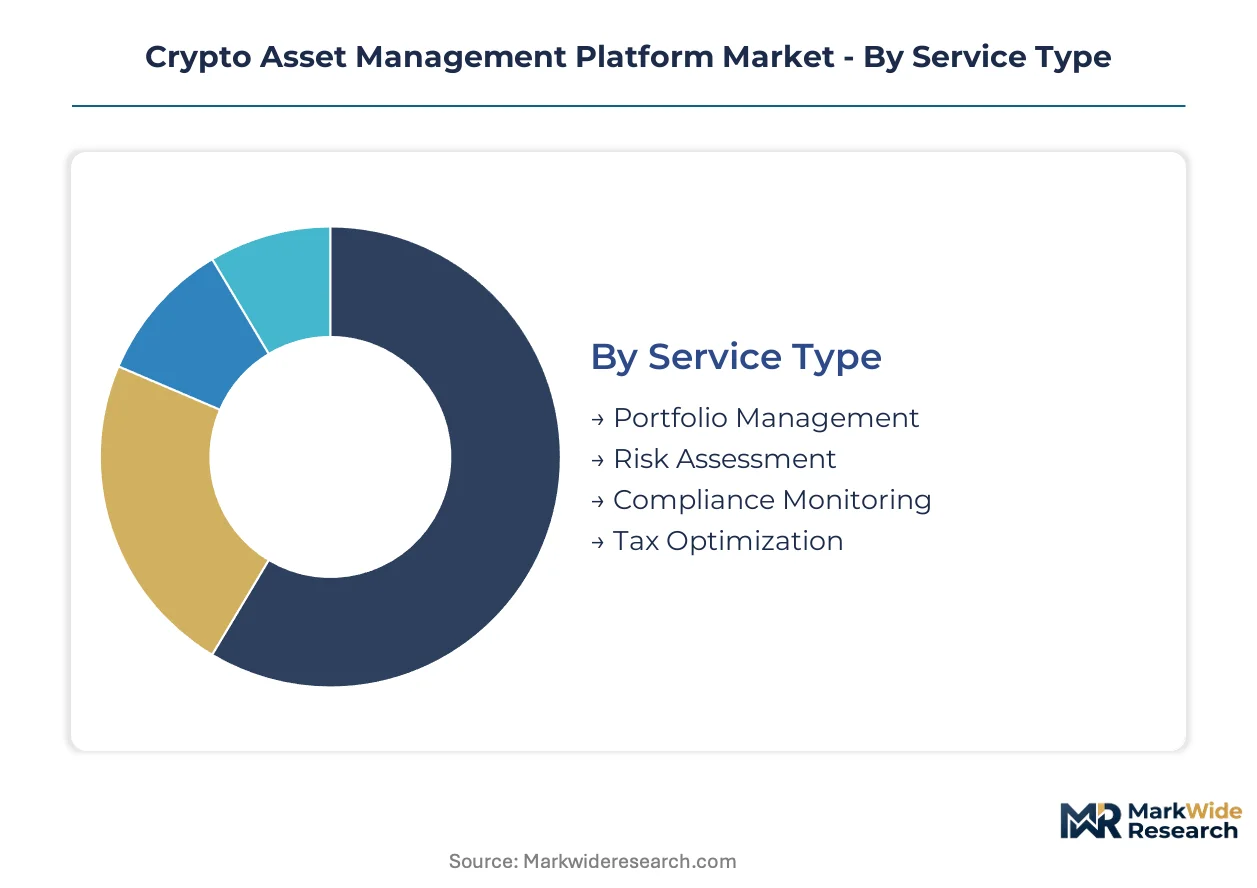
Platform providers configure service bundles and deployment architectures around divergent risk tolerances, regulatory footprints, and technical sophistication among crypto holders. Segmentation reveals where margin pools concentrate and which integration modes capture institutional procurement workflows.
Service Type:
Cost tier determines feature depth and automation sophistication across advisory workflows.
- Portfolio Management:Automated rebalancing engines execute cross-exchange position adjustments with sub-second latency. Institutional allocators in Singapore and the United States demand these capabilities for multi-billion-dollar mandates.
- Compliance Monitoring:Real-time surveillance against sanctions lists and transaction pattern analysis for AML triggers. MiCA licensing deadlines in Europe accelerate procurement of automated documentation suites.
- Risk Assessment:Value-at-risk calculations incorporating on-chain volatility surfaces and counterparty exposure metrics.
- Tax Optimization:Wash-sale detection across decentralized exchanges and jurisdictional loss-harvesting automation.
Portfolio Management holds installed capacity. Compliance Monitoring is rotating up the share rankings.
Deployment Model:
Application sensitivity to latency, data sovereignty, and counterparty risk drives architecture selection.
- Hybrid Cloud:Sensitive key material resides in sovereign data centers while compute-intensive analytics leverage public infrastructure. Swiss fund managers pursue this architecture for sub-millisecond exchange connectivity.
- Private Cloud:Dedicated infrastructure isolates client data from multi-tenant environments. Family offices in Dubai specify private deployments for direct custody relationships.
- Public Cloud:Elastic compute for backtesting and simulation workloads without capital-intensive infrastructure commitments.
- On-Premise:Air-gapped key generation and signing ceremonies for maximum isolation from internet-facing attack surfaces.
Private Cloud holds installed capacity. Hybrid Cloud is expanding most quickly among new implementations.
End User:
Customer type dictates contract structure, support intensity, and regulatory overlay requirements.
- Institutional Investors:Pension funds and endowments mandate segregated cold storage, real-time proof-of-reserves, and qualified custodian verification under SEC registration frameworks.
- Fund Managers:Hedge funds require API-native connectivity to prime brokerage arrangements and automated NAV calculation across commingled and segregated structures.
- Wealth Advisors:High-net-worth channels demand embedded tax-lot control and custom ESG screening for bespoke portfolio construction.
- Retail Traders:Mobile-first interfaces with simplified custody and automated dollar-cost averaging functionality.
Institutional Investors command the deepest margin pools. Fund Managers are climbing the fastest as hedge fund crypto allocations accelerate.
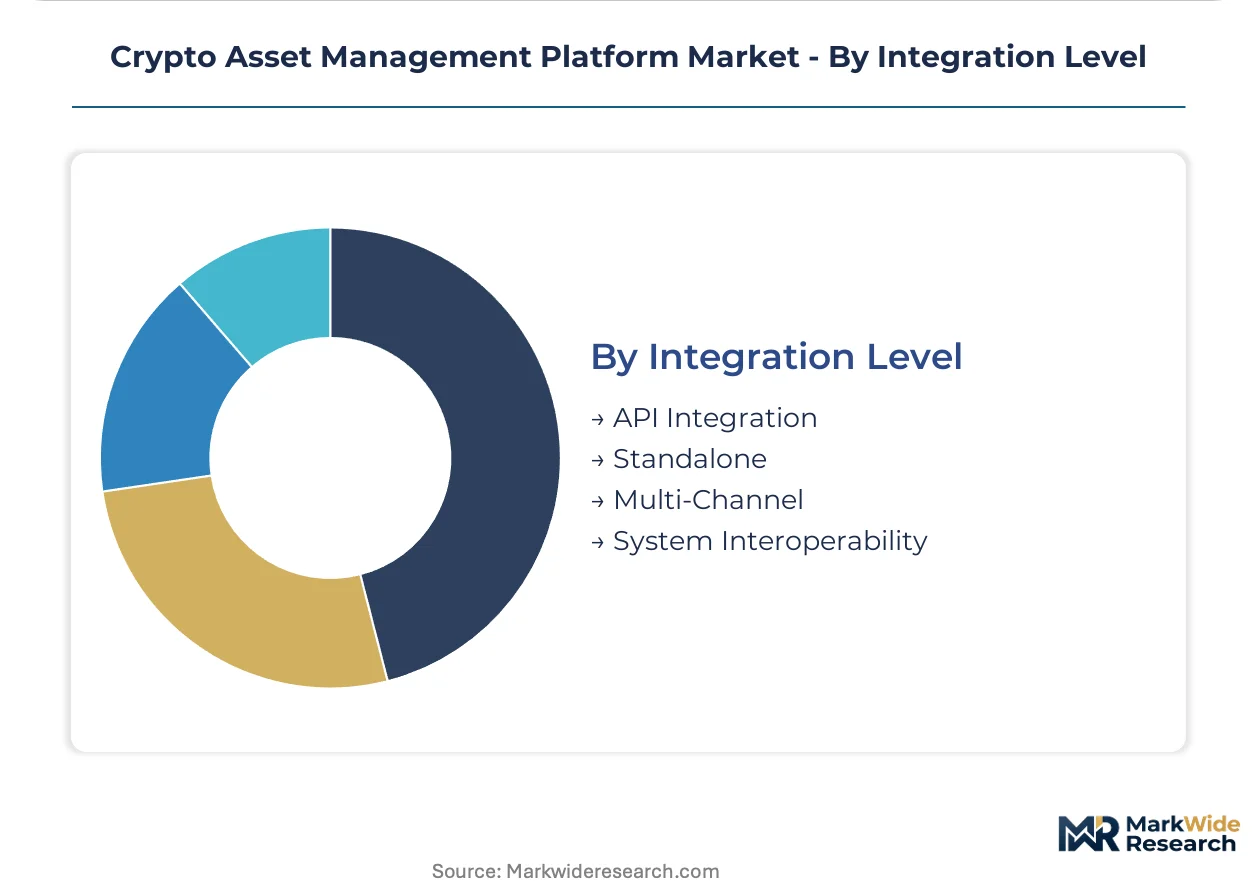
Integration Level:
Volume of external system touchpoints determines implementation complexity and switching costs.
- API Integration:Native connectivity to core banking systems, fund administration platforms, and on-chain data providers. Traditional custodians resist this mode due to legacy mainframe reconciliation constraints.
- System Interoperability:Bi-directional data flows between portfolio accounting, risk engines, and regulatory reporting infrastructure.
- Multi-Channel:Unified experience across desktop, mobile, and voice-activated interfaces for advisor-client interaction.
- Standalone:Self-contained platforms with manual data export for external system reconciliation.
API Integration holds installed capacity. System Interoperability is gaining share fastest as fund administrators consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional allocators concentrate procurement decisions in jurisdictions with qualified custodian frameworks and federal banking compliance infrastructure. Pension funds and endowments prioritize platforms with OCC charter status or equivalent national trust licensing. Regulatory clarity in specific markets is compressing vendor selection timelines and consolidating geographic vendor relationships.
United States
SEC registration under the Investment Advisers Act mandates qualified custodian verification for all crypto advisory relationships. OCC-chartered trust companies anchor institutional settlement workflows in New York and Chicago. Family offices in Miami and Austin are consolidating direct custody relationships with federally regulated platforms.
United Kingdom
FCA registration requirements for cryptoasset firms are accelerating platform procurement among hedge funds and wealth managers. Prudential standards for custodial operations force segregation of client assets in cold storage architectures. The City of London cluster concentrates compliance-technology vendors serving European asset managers.
Singapore
MAS payment institution licensing attracts regional treasury operations from family offices and commodity trading houses. Regulatory clarity on digital payment token services compresses vendor due diligence timelines. The Marina Bay financial district hosts concentrated platform operations serving Southeast Asian fund managers.
Switzerland
FINMA banking and securities dealer licensing enables integrated wealth management platforms for ultra-high-net-worth principals. Zug and Zurich clusters specialize in private banking infrastructure bridging traditional custody and digital assets. Swiss fund managers pursue hybrid cloud deployments balancing data sovereignty against exchange connectivity latency.
Germany
BaFin crypto custody licensing deadlines are accelerating procurement among Spezialfonds and institutional asset managers. HGB accounting standards require granular audit trails for blockchain-based instruments. Frankfurt's fund administration cluster is integrating MPC-based custody into legacy reconciliation systems.
Crypto Asset Management Platform Market Competitive Environment
Channel-controlling players compete with product-specialist players across custody infrastructure, exchange integration, and compliance automation layers. The market exhibits tiered concentration with federally chartered trust companies occupying premium institutional segments and technology infrastructure vendors capturing middleware workflows. Three archetypes dominate: exchange-custody bundles, standalone custody technology providers, and traditional financial institutions with digital asset subsidiaries. Competitive moves center on OCC charter acquisition and MPC protocol licensing to anchor institutional procurement decisions.
Within the federally chartered trust tier, Anchorage Digital and Gemini Trust Company exemplify bank-grade compliance frameworks that satisfy pension fund fiduciary requirements. Fireblocks occupies a position as infrastructure-specialist anchor for multi-party computation workflows across exchanges and custodians. Coinbase represents the exchange-integrated archetype combining regulated custody with liquidity access for institutional allocators.
| Leading Market Players |
|---|
| Coinbase |
| Binance |
| BitGo |
| Anchorage Digital |
| Gemini Trust Company |
| Fidelity Digital Assets |
| Bakkt |
| Fireblocks |
| Paxos Trust Company |
| Others |
Value Chain & Pricing Dynamics
MPC protocol developers in Israel and the United States command compensation premiums that compress margins for platform operators while concentrating value capture in specialized cryptography talent pools. This upstream concentration forces downstream pricing stratification between institutional-grade compliance bundles and retail-accessible SaaS tiers.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise procurement for institutional custody infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates OCC-chartered trust services from exchange-integrated bundles and API-native middleware. Price differentiation hinges on qualified custodian certification under SEC registration and real-time proof-of-reserves attestation capabilities. Pricing pressure stems from MiCA licensing deadlines accelerating procurement timelines for automated compliance documentation. Family offices exhibit highest price sensitivity due to direct indexing preferences, while pension funds prioritize fiduciary protection over cost minimization.
Supply Chain Analysis
Upstream cryptographic hardware feeds from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States. HSM component supply draws from NXP Semiconductors and Thales manufacturing footprints, while MPC software development clusters in Tel Aviv, New York, and Zurich. Single-source vulnerability pervades AWS and Azure dominance in institutional data centers serving latency-sensitive trading operations. Distribution runs through direct enterprise sales for institutional mandates and channel partnerships for wealth advisory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in crypto asset management are reaching an inflection as interoperability standards consolidate around API-native connectivity and cross-custodian settlement rails reshape vendor selection criteria.
For Market Incumbents: Pre-empt regulatory arbitrage fragmentation by consolidating OCC charter acquisition and MPC protocol licensing ahead of MiCA enforcement waves. Vertical integration into qualified custodian status eliminates counterparty exposure liabilities that erode institutional margins. Anchor procurement decisions through real-time proof-of-reserves infrastructure that satisfies pension fund fiduciary mandates. For New Entrants and Emerging Players: Mid-market fund administrators in Germany and Switzerland represent the most penetrable entry point for compliance-automation platforms lacking legacy mainframe integration burdens. Tax-loss harvesting engines for high-net-worth channels in Singapore and Dubai offer white-space expansion with lower regulatory capital requirements. Go-to-market execution should prioritize API-native connectivity demonstrations over custody infrastructure buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed custody technology providers facing compressed timelines to OCC charter conversion or MiCA licensing completion. Long-term viability centers on federal banking compliance frameworks rather than exchange-integrated liquidity access. Watch for consolidation signals when platform operators abandon standalone custody ambitions in favor of infrastructure-specialist positioning.| Strategic Initiative | Industry Significance |
|---|---|
| OCC Charter Acquisition | Federal banking status unlocks pension fund mandates requiring qualified custodian verification under SEC registration. |
| MPC Protocol Licensing | Distributed key management eliminates single-point-of-failure liabilities that previously required expensive insurance overlays. |
| Hybrid Cloud Deployment | Sovereign data residency satisfies Swiss and Liechtenstein fund manager requirements without sacrificing exchange connectivity latency. |
| Tax-Loss Harvesting Automation | Embedded wash-sale monitoring captures high-net-worth advisory channel demand for granular tax-lot control. |
| Cross-Custodian Settlement Integration | Interoperability with prime brokerage arrangements anchors hedge fund procurement decisions for NAV calculation automation. |
Study Parameters
A standing panel of chief technology officers at crypto custodians, compliance officers at OCC-chartered trust companies, fund administrators at institutional allocators, and MPC protocol engineers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC registration filings, MiCA regulatory notices, MAS licensing databases, and FINMA banking authorization records. Bottom-up platform deployment estimates triangulated against top-down institutional allocation surveys.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling service type segmentation by portfolio management depth, deployment architecture by latency sensitivity, and end-user category by regulatory overlay intensity. CAGRs derived from installed capacity buildout curves and procurement timeline compression effects. Forecast inputs incorporated MiCA licensing deadline schedules and qualified custodian verification mandate expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in institutional risk appetite, cryptocurrency price volatility, or regulatory enforcement intensity would shift the trajectory. Cross-checking against central bank digital currency development timelines and traditional asset manager crypto allocation surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market