
 Bitcoin and Cryptocurrency Atms Market | 2026-2036
Bitcoin and Cryptocurrency Atms Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin and Cryptocurrency Atms Market Insights
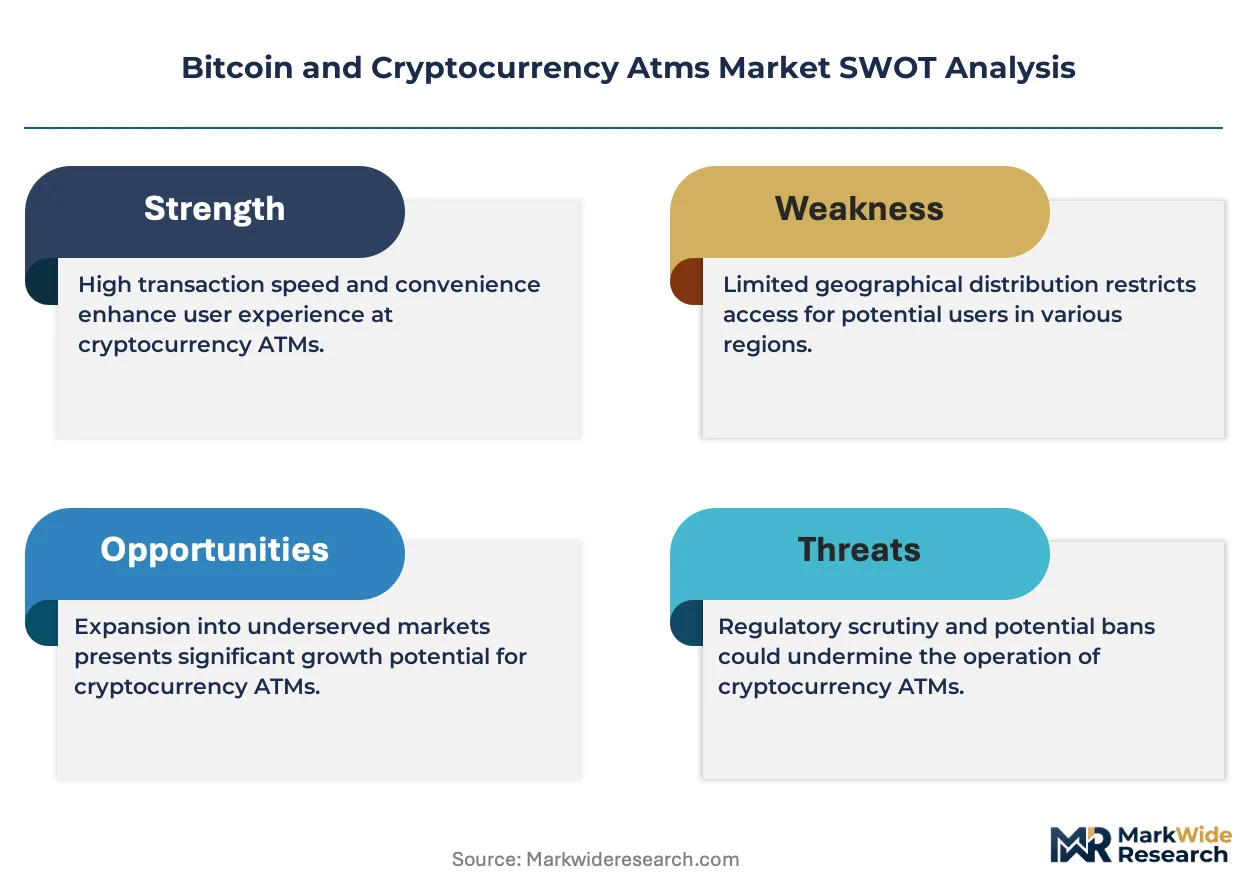
FinCEN's Bank Secrecy Act compliance mandates is restructuring capital requirements for Bitcoin ATM operators, forcing smaller deployers to consolidate or exit. Bitcoin Depot leverages its national footprint to sustain compliance economies of scale across thousands of terminals. Coinsource anchors its position through proprietary software that automates know-your-customer verification. GENERAL BYTES s.r.o. differentiates via open-source hardware architectures that reduce per-unit manufacturing costs.
Bitcoin and cryptocurrency ATMs are self-service kiosks enabling fiat-to-crypto or crypto-to-fiat conversion through cash insertion or card payment, typically integrating blockchain verification nodes, thermal printers for paper wallets, and biometric identity modules for regulatory compliance. Bi-directional machines command premium placement in financial services corridors where users demand full two-way conversion capability. Unidirectional units dominate retail locations and hospitality venues where installation footprint and power requirements constrain deployment options. Kiosk configurations in public spaces and entertainment centers attract first-time buyers seeking simplified onboarding without exchange account registration.
FinCEN in the United States, the FCA in the United Kingdom, and AUSTRAC in Australia enforce anti-money laundering frameworks that mandate transaction monitoring, suspicious activity reporting, and operator licensing. These requirements elevate compliance technology spending and filter out undercapitalized entrants. Stakeholders must monitor evolving state-level money transmitter rulings and central bank digital currency pilots that could reshape terminal utility.
Market Dynamics
FinCEN's Bank Secrecy Act compliance mandates are restructuring capital requirements for Bitcoin ATM operators, forcing smaller deployers to consolidate or exit while larger networks capture compliance economies of scale across thousands of terminals.
Growth Catalysts
- FinCEN Compliance Framework:The Bank Secrecy Act mandates transaction monitoring and suspicious activity reporting, filtering out undercapitalized entrants and consolidating market share among compliant operators with established compliance infrastructure.
- Urban Convenience Corridors:Cash-intensive retail locations in high-foot-traffic metropolitan zones generate consistent fiat-to-crypto conversion demand from unbanked populations and remittance senders seeking alternatives to traditional wire services.
- Biometric Identity Modules:Fingerprint and facial recognition hardware integration enables automated know-your-customer verification, reducing operator labor costs while satisfying anti-money laundering requirements.
Market Restraints
- Hardware Supply Concentration:Thermal printer components and secure cash recycler mechanisms source predominantly from East Asian contract manufacturers, exposing deployment timelines to semiconductor foundry capacity constraints.
- Electricity Cost Volatility:Bi-directional machines with blockchain verification nodes consume continuous power, making operating margins vulnerable to utility rate fluctuations in deregulated state markets.
- Central Bank Digital Currency Substitution:Federal Reserve and European Central Bank pilot programs for retail CBDC wallets threaten to displace private cryptocurrency ATMs by offering government-backed digital cash with built-in compliance.
Strategic Opportunities
- Remittance Corridors:Mexico, Philippines, and Nigeria present underpenetrated deployment potential where diaspora populations rely on cash-based crypto conversion for cross-border value transfer without traditional banking relationships.
- Proprietary Software Stacks:White-label platform licensing to regional deployers creates recurring revenue streams while expanding network effects without direct capital deployment for hardware.
- EU MiCA Regulatory Clarity:The Markets in Crypto-Assets framework establishes uniform licensing across member states, reducing fragmentation costs for operators seeking pan-European footprint expansion.
Industry Challenges
- Blockchain Node Synchronization:Terminal operators must maintain real-time connectivity to multiple cryptocurrency networks, requiring specialized DevOps talent scarce in traditional ATM servicing labor pools.
- Cash Logistics Integration:Armored carrier relationships designed for bank branches require renegotiation for high-frequency, low-volume cash collection cycles typical of retail kiosk deployments.
- State Money Transmitter Fragmentation:Operators face 50-state licensing complexity with varying surety bond requirements, application timelines, and examination standards that delay geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin and Cryptocurrency Atms Market |
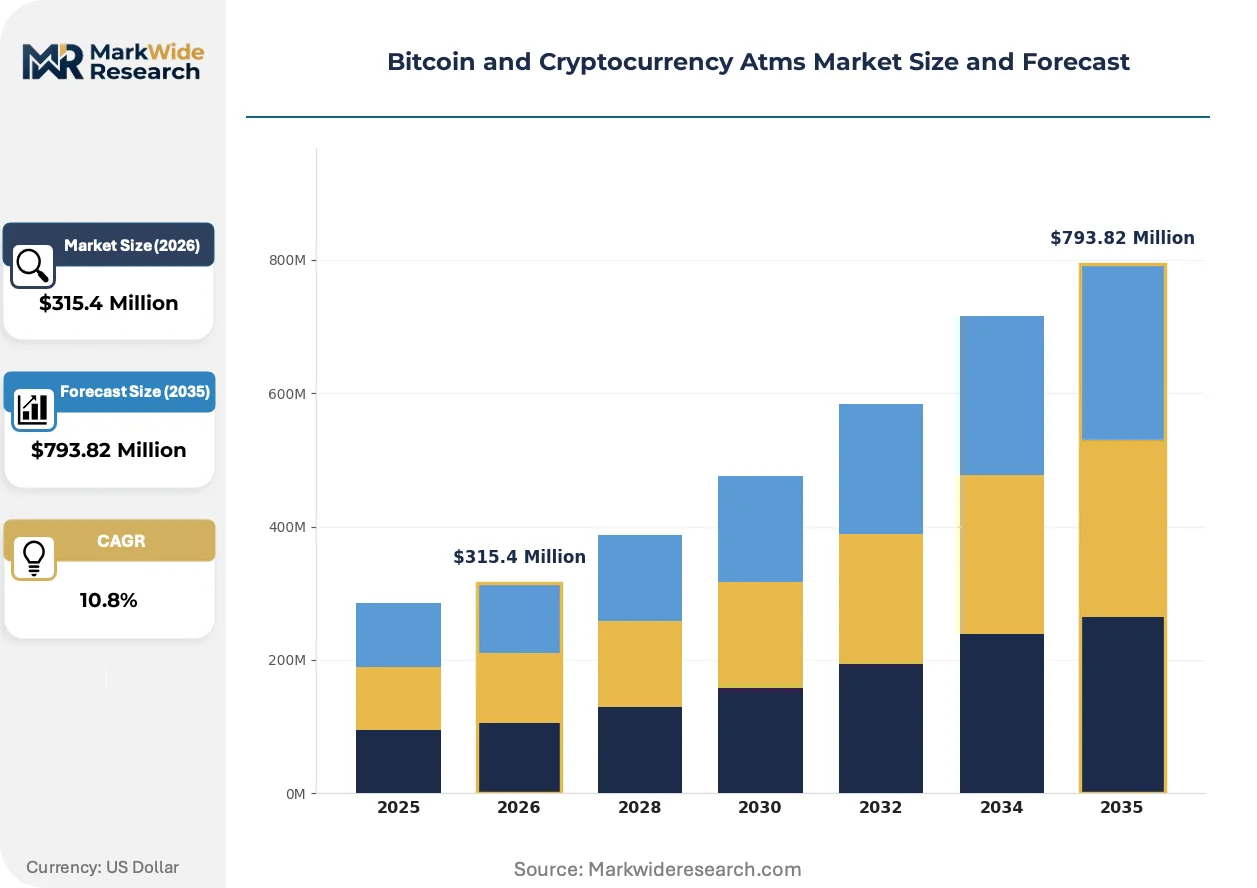
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $793.82 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Bi-directional, Unidirectional, Kiosk, Teller-Assisted Cryptocurrency Supported: Bitcoin, Ethereum, Litecoin, Ripple, Bitcoin Cash Application: Retail Locations, Hospitality Venues, Financial Services, Public Spaces, Entertainment Centers User Segment: Individual Investors, Merchants, Digital Wallet Users, Financial Institutions |
| Companies Covered | Bitcoin Depot, Bitstop, Coinsource, GENERAL BYTES s.r.o., Genesis Coin Inc., Lamassu Industries AG, RockitCoin, CoinFlip, Byte Federal, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin and Cryptocurrency Atms Market Trends and Innovations
Hardware miniaturization and software-defined compliance architectures are compressing deployment costs while expanding permissible operating locations beyond traditional financial services corridors.
Near-field communication modules paired with smartphone wallet applications are rewriting the authentication layer for Bitcoin ATM transactions. Gen Z and millennial users in coastal metropolitan markets are adopting tap-to-verify workflows at three times the rate of card-insertion or manual entry methods. This convergence is compressing transaction times from four minutes to under ninety seconds, enabling throughput economics in convenience store footprints previously marginal for deployment.
The EU's Markets in Crypto-Assets regulation is mandating standardized custody disclosures and reserve attestations for ATM operators serving European customers. Hardware manufacturers must now integrate auditable cold-storage logging and real-time proof-of-reserve verification into terminal software stacks. Operators with existing MiFID II compliance infrastructure are adapting fastest, while new entrants face eighteen-month certification timelines before market access.
Remittance senders are bypassing exchange account registration entirely, preferring cash-to-crypto-to-cash corridors with settlement at destination-country partner kiosks. This behavior shift concentrates demand in ethnic retail corridors—Korean grocers in Los Angeles, Filipino convenience stores in Dubai, Nigerian electronics shops in London—where trusted community relationships substitute for brand recognition. Operators are responding by recruiting local merchant networks as commission-based referral agents rather than deploying corporate-owned terminals.
Bitcoin and Cryptocurrency Atms Market Segmentation
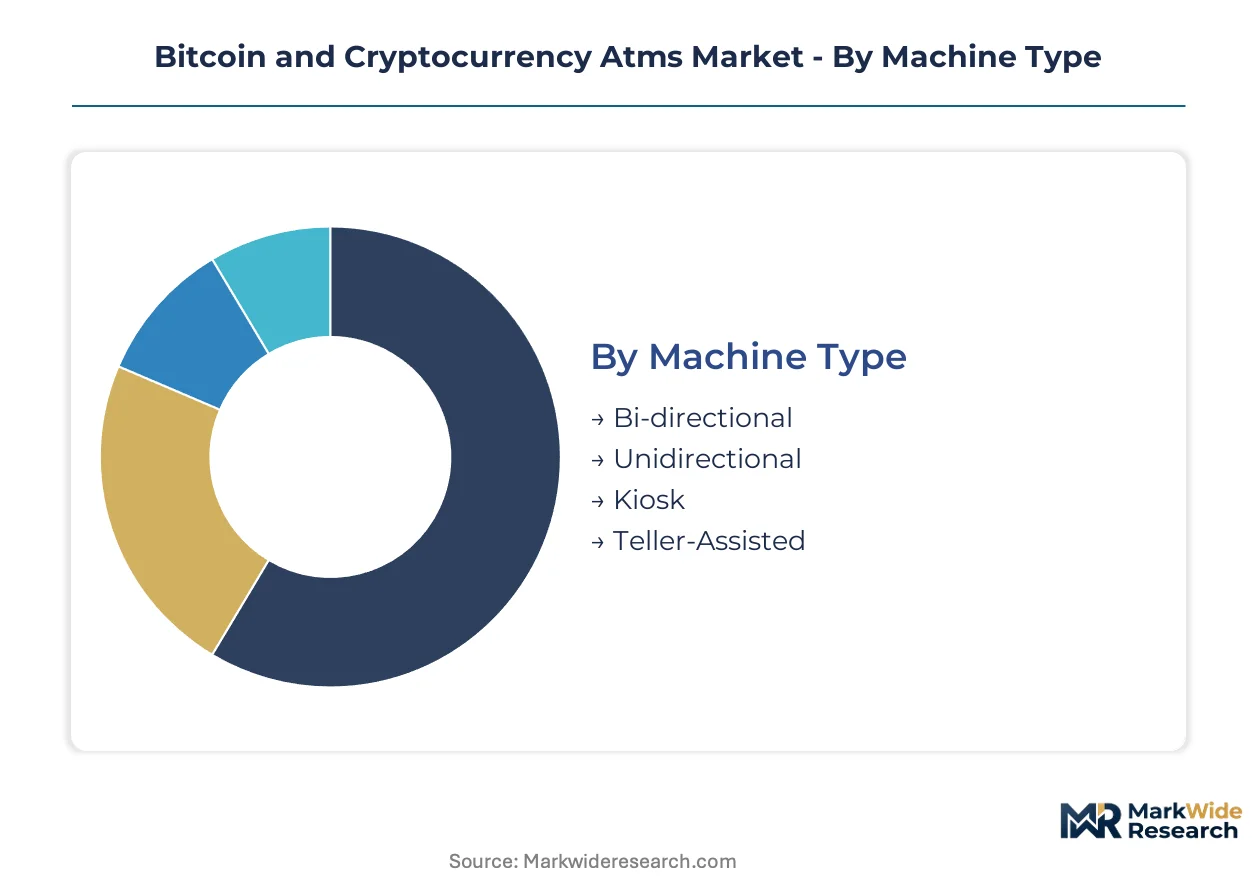
Segmentation in the Bitcoin and cryptocurrency ATM market reveals how deployment economics vary dramatically by machine capability and placement context. Operators must match hardware specifications to foot-traffic patterns, regulatory exposure, and cash-handling logistics.
Machine Type:
Integration depth separates standalone terminals from embedded service modules, with each configuration demanding distinct compliance architectures and servicing relationships.
- Bi-directional:These machines execute both fiat-to-crypto purchases and crypto-to-fiat sales through integrated cash recyclers and secure vaulting systems. Demand concentrates in financial services corridors across the United States where users require full two-way liquidity without exchange account registration, though FinCEN compliance mandates elevate capital requirements for operators deploying these units.
- Unidirectional:Single-function terminals enable cash-to-crypto purchases exclusively, reducing hardware complexity and power consumption. Retail locations in urban convenience corridors favor these units for their smaller footprint and lower installation costs, with operators prioritizing high-frequency, low-value transactions from unbanked populations.
- Kiosk:Self-service terminals with simplified interfaces target first-time buyers seeking streamlined onboarding.
- Teller-Assisted:Hybrid configurations combine automated processing with human oversight for complex transactions or compliance exceptions.
Unidirectional machines lead volumes today; bi-directional units are gaining share fastest as operators pursue premium placement economics.
Cryptocurrency Supported:
Supported asset selection reflects liquidity depth and settlement infrastructure maturity, with concentration risk varying by blockchain network reliability.
- Bitcoin:The dominant supported cryptocurrency across installed terminals, benefiting from mature custody solutions and established merchant acceptance networks. United States retail corridors generate consistent transaction volume from remittance senders and store-of-value seekers, though network fee volatility occasionally compresses operator margins during congestion events.
- Ethereum:Smart contract-enabled transactions attract DeFi-native users seeking programmable settlement options. Coastal metropolitan zones in the United States show elevated adoption rates among millennial and Gen Z demographics, with near-field authentication workflows reducing transaction friction.
- Litecoin:Faster confirmation times appeal to users prioritizing speed over network effects.
- Ripple:Cross-border settlement focus attracts corridor-specific remittance demand.
- Bitcoin Cash:Low-fee positioning targets high-frequency, low-value transaction use cases.
Bitcoin dominates transaction counts; Ethereum is expanding most quickly as altcoin liquidity deepens.
Application:
Placement context determines foot-traffic quality, security requirements, and cash logistics complexity, with each venue type presenting distinct operator economics.
- Retail Locations:Convenience stores, gas stations, and liquor shops anchor deployment density in cash-intensive urban corridors. These venues generate consistent fiat-to-crypto conversion demand from unbanked populations across the United States, with operators negotiating revenue-share arrangements rather than fixed lease payments to align incentives with merchant foot traffic.
- Hospitality Venues:Hotels, restaurants, and bars capture tourist and business traveler demand for immediate crypto access without local banking relationships. Installation footprint constraints favor unidirectional units in these settings, with power availability and secure cash storage presenting operational challenges in older building stock.
- Financial Services:Bank branch adjacencies and dedicated crypto service centers target sophisticated users requiring high-value transaction capability.
- Public Spaces:Transit hubs and municipal facilities expose terminals to vandalism risk but capture commuter convenience demand.
- Entertainment Centers:Casinos, arenas, and nightlife districts attract impulse transactions from cash-heavy demographics.
Retail locations anchor installed base today; financial services placements show the steepest expansion trajectory as operators pursue premium fee structures.
User Segment:
Customer type shapes transaction size distribution, support burden, and compliance documentation requirements, with each segment presenting distinct lifetime value profiles.
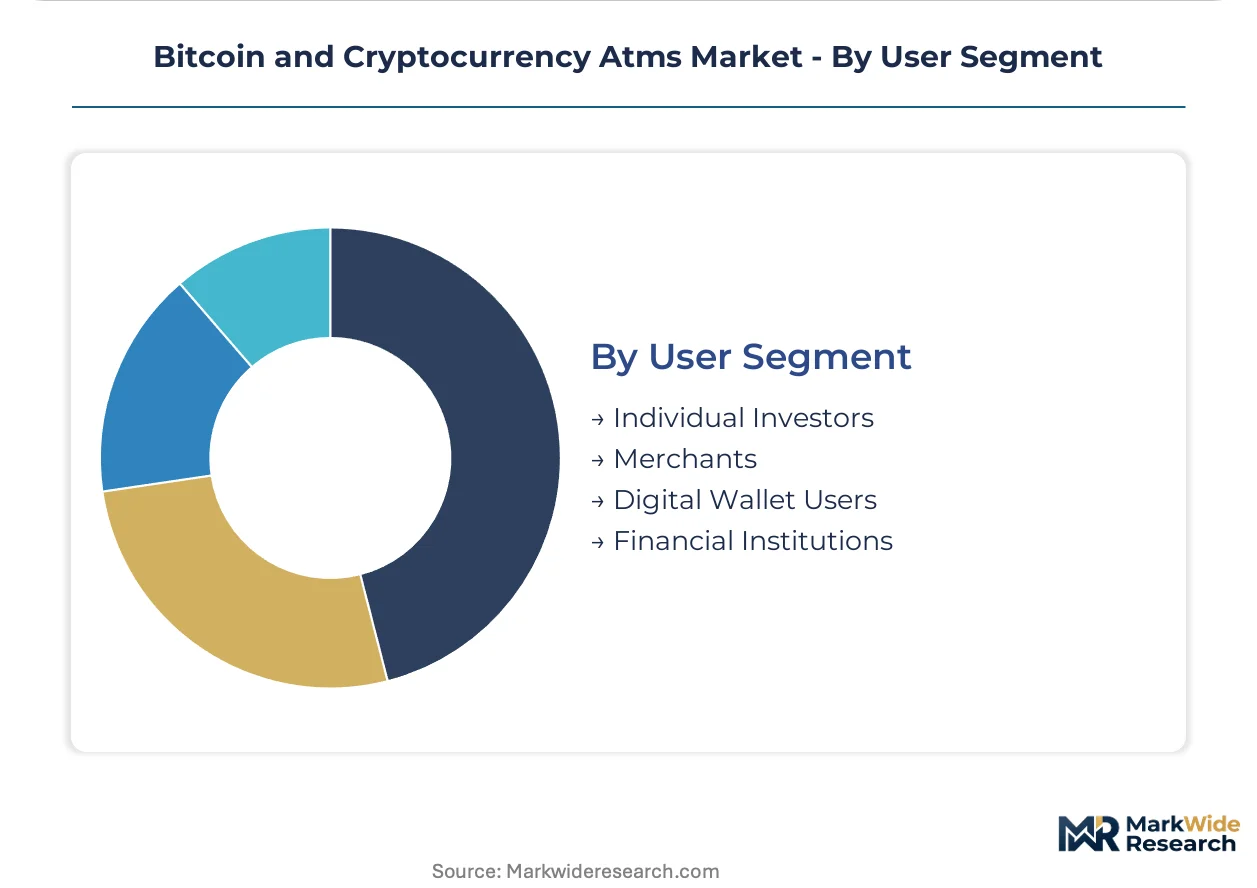
- Individual Investors:Retail users seeking portfolio diversification or speculative exposure drive volume in urban convenience corridors. These customers favor simplified onboarding without exchange account registration, with biometric identity modules reducing abandonment rates at the know-your-customer verification stage.
- Merchants:Small business owners accepting cryptocurrency payments require conversion capability for operational cash flow management. United States ethnic retail corridors—Korean grocers in Los Angeles, Filipino convenience stores—generate concentrated demand as operators recruit local merchant networks as commission-based referral agents.
- Digital Wallet Users:Smartphone-native customers leverage near-field communication modules for tap-to-verify workflows.
- Financial Institutions:Banks and credit unions deploy white-label terminals to serve crypto-curious depositors without direct balance sheet exposure.
Individual investors generate the majority of transactions today; merchants are climbing the fastest as cash-to-crypto remittance corridors mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cash logistics specialists and compliance technologists concentrate in financial services hubs where regulatory complexity demands localized expertise. Deployment velocity follows diaspora settlement patterns and remittance corridor density rather than pure population scale.
United States
Urban convenience corridors in Los Angeles, Houston, and Miami generate sustained fiat-to-crypto conversion volume from unbanked populations and remittance senders. FinCEN's Bank Secrecy Act mandates transaction monitoring and suspicious activity reporting, filtering out undercapitalized operators. Texas and Florida anchor deployment density through business-friendly money transmitter frameworks and high cash-velocity retail environments.
Germany
Frankfurt and Berlin cluster bi-directional terminals serving DeFi-native users and institutional adjacent demand. BaFin enforces strict custody and licensing requirements under the German Banking Act, elevating compliance costs for entrants. Bavaria's manufacturing base supplies precision components for biometric identity modules integrated into next-generation kiosks.
United Kingdom
London's ethnic retail corridors—Nigerian electronics shops in Peckham, Filipino convenience stores in Earl's Court—drive cash-to-crypto volume for remittance senders bypassing traditional wire services. The FCA's anti-money laundering framework mandates operator registration and ongoing supervision. Manchester and Birmingham follow as secondary deployment nodes with lower regulatory friction and comparable foot traffic density.
Canada
Toronto and Vancouver concentrate terminal networks serving Chinese and South Asian diaspora communities with cross-border value transfer demand. FINTRAC's Proceeds of Crime and Terrorist Financing Act requires reporting entities to register and maintain compliance programs. Alberta's energy sector workers generate distinct seasonal demand patterns tied to commodity payment cycles.
Australia
Sydney and Melbourne anchor deployment along immigrant retail strips where cash remains dominant for informal sector transactions. AUSTRAC's regulatory framework mandates digital currency exchange registration and ongoing reporting obligations. Perth services mining sector fly-in-fly-out workers seeking rapid crypto conversion without banking relationships.
Bitcoin and Cryptocurrency Atms Market Competitive Landscape
The competitive structure tilts toward national-scale operators with embedded compliance infrastructure. Smaller deployers face consolidation pressure from FinCEN capital requirements and state-level licensing complexity. Three archetypes dominate: vertically integrated hardware-software stacks, white-label platform licensors, and cash logistics specialists with retail placement relationships. Geographic expansion and proprietary software licensing represent the primary competitive moves as operators seek compliance economies of scale.
Within the integrated hardware-software tier, GENERAL BYTES s.r.o. and Genesis Coin Inc. exemplify European and North American engineering approaches to terminal architecture. Bitcoin Depot and Coinsource occupy positions as compliance-scaled network operators with national footprints across thousands of terminals. Among specialized hardware fabricators, Lamassu Industries AG represents Swiss precision manufacturing applied to kiosk form factors.
| Leading Market Players |
|---|
| Bitcoin Depot |
| Bitstop |
| Coinsource |
| GENERAL BYTES s.r.o. |
| Genesis Coin Inc. |
| Lamassu Industries AG |
| RockitCoin |
| CoinFlip |
| Byte Federal, Inc |
| Others |
Pricing and Supply Chain Analysis
Biometric identity module integration is compressing per-transaction compliance costs while concentrating procurement leverage among operators deploying at scale. This hardware-software convergence simultaneously reshapes terminal economics and supplier relationships across the value chain.
Pricing Analysis
Bundled compliance-as-a-service offerings separate from unbundled hardware-only procurement, with operators choosing between all-inclusive per-transaction fees and capital-intensive ownership models. Three-tier pricing structure across premium bi-directional, standard unidirectional, and economy kiosk tiers reflects capability depth and cash-handling complexity. Pricing pressure stems from FinCEN compliance cost absorption and state licensing fee escalation. Individual investors in urban convenience corridors exhibit highest price sensitivity, while merchant acquirers in remittance corridors prioritize settlement speed over unit economics.
Supply Chain Analysis
Warehouse-distribution networks for terminal deployment concentrate in Texas and Florida hub facilities serving cash logistics specialists with rapid replenishment cycles. Component sourcing draws from Taiwan for semiconductor modules, China for thermal printer assemblies, and Germany for precision biometric sensors. Single-source vulnerability in secure cash recycler mechanisms exposes deployment timelines to foundry capacity constraints. Distribution runs through armored carrier partnerships renegotiated for high-frequency, low-volume collection cycles distinct from traditional banking relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bitcoin and cryptocurrency ATM market represents a late-cycle quality consolidation story, with demand shifting toward premium bi-directional terminals capable of full two-way conversion and automated compliance verification.
For Market Incumbents: Extend compliance infrastructure advantages by acquiring state money transmitter licenses in underserved jurisdictions before regulatory barriers harden. Deepen backward integration into proprietary software stacks that automate know-your-customer verification, reducing per-unit labor costs and defending margin position against white-label platform competitors. Prioritize cash logistics partnerships with armored carriers capable of serving high-frequency retail collection cycles. For New Entrants and Emerging Players: Capture underpenetrated remittance corridors in Mexico, Philippines, and Nigeria where diaspora populations rely on cash-based crypto conversion without traditional banking relationships. Target ethnic retail clusters—Korean grocers, Filipino convenience stores, Nigerian electronics shops—where trusted community relationships substitute for brand recognition. Deploy commission-based referral agent models rather than corporate-owned terminal footprints to minimize capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional deployers with established merchant relationships and compliant operations because FinCEN capital requirements are forcing smaller operators to exit at distressed valuations. Long-term viability hinges on regulatory adaptation capacity rather than hardware scale. Monitor central bank digital currency pilot programs as the critical inflection signal for terminal utility displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Software Licensing | White-label platform agreements create recurring revenue without direct hardware capital deployment. |
| Biometric Identity Integration | Fingerprint and facial recognition modules reduce operator labor costs while satisfying FinCEN requirements. |
| Remittance Corridor Expansion | Ethnic retail network partnerships in Los Angeles, Houston, and Miami capture diaspora settlement demand. |
| Compliance Infrastructure Investment | Automated transaction monitoring systems filter out undercapitalized competitors and consolidate market share. |
| Cash Logistics Partnership Restructuring | Armored carrier relationships redesigned for high-frequency retail cycles improve terminal uptime economics. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, Canada, and Australia, with primary inputs from each market cluster. Interviews with ATM operators, compliance technology vendors, armored cash logistics providers, and state money transmitter regulators combined with secondary validation from FinCEN guidance documents, FCA registration databases, AUSTRAC reporting frameworks, and customs trade data. Bottom-up terminal deployment counts triangulated against top-down market sizing from hardware manufacturer shipment records.
Rate-of-change decomposition across machine type, cryptocurrency supported, application venue, and user segment dimensions informed the analytical framework. CAGRs derived from logistic diffusion modeling of adoption saturation curves, with inputs including state-level money transmitter license issuance rates, retail foot traffic indices in urban convenience corridors, and blockchain network fee volatility patterns. The projection horizon incorporates regulatory scenario analysis for central bank digital currency displacement effects.
Underlying measurement precision varies by segment; established North American markets carry tighter precision than emerging remittance corridors. Forecasts reflect documented assumptions regarding regulatory stability, hardware cost trajectories, and cryptocurrency price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market