
 Decentralized Finance Market | 2026-2036
Decentralized Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Decentralized Finance Market Intelligence
The divergence between institutional-grade DeFi infrastructure and retail-accessible commodity protocols is consolidating around compliance architecture and counterparty risk management. MakerDAO leverages overcollateralized stablecoin mechanics to anchor institutional trust. Aave sustains multi-chain lending pool architecture across Ethereum and Layer-2 networks. Uniswap competes through concentrated liquidity automation that reduces slippage for large-order execution.
Decentralized finance denotes a blockchain-based financial services ecosystem operating without centralized intermediaries, where smart contracts enforce lending, trading, and asset management logic through transparent, auditable code execution. Its primary purpose replaces traditional clearing and custody functions with programmable, permissionless settlement layers that reduce friction and counterparty dependency. Lending protocols currently capture the deepest liquidity pools and fee generation across the DeFi stack, while yield farming mechanisms attract speculative capital seeking optimized returns. Stablecoins function as the dominant settlement medium, with demand concentrating where dollar-denominated liquidity bridges on-chain and off-chain economies.
The SEC in the United States classifies certain DeFi tokens as securities, forcing protocol developers to restructure governance and disclosure practices. The EU MiCA framework establishes licensing requirements for crypto-asset service providers, directly shaping market access conditions for European users. Stakeholders must monitor how jurisdictional arbitrage between regulatory regimes influences protocol deployment decisions and user base migration patterns.
Market Dynamics
Institutional treasury departments are channeling capital into on-chain yield instruments, compressing the gap between traditional fixed-income infrastructure and permissionless lending protocols. This capital migration is restructuring liquidity depth and counterparty risk assessment across the DeFi stack.
Growth Catalysts
- MiCA Licensing Framework:The EU's Markets in Crypto-Assets regulation establishes clear authorization pathways for stablecoin issuers and lending protocol operators, reducing legal uncertainty for European institutional deployment.
- Singapore's MAS Licensing:The Monetary Authority of Singapore's digital payment token framework attracts hedge funds and family offices seeking regulated onshore DeFi access with statutory custody protections.
- Layer-2 Scaling:Rollup architectures on Ethereum reduce gas costs for institutional-sized transactions, enabling treasury operations to execute multi-million dollar trades without base-layer congestion penalties.
Market Restraints
- SEC Enforcement Uncertainty:The Securities and Exchange Commission's classification of governance tokens as unregistered securities creates legal exposure for US-based protocol developers and liquidity providers.
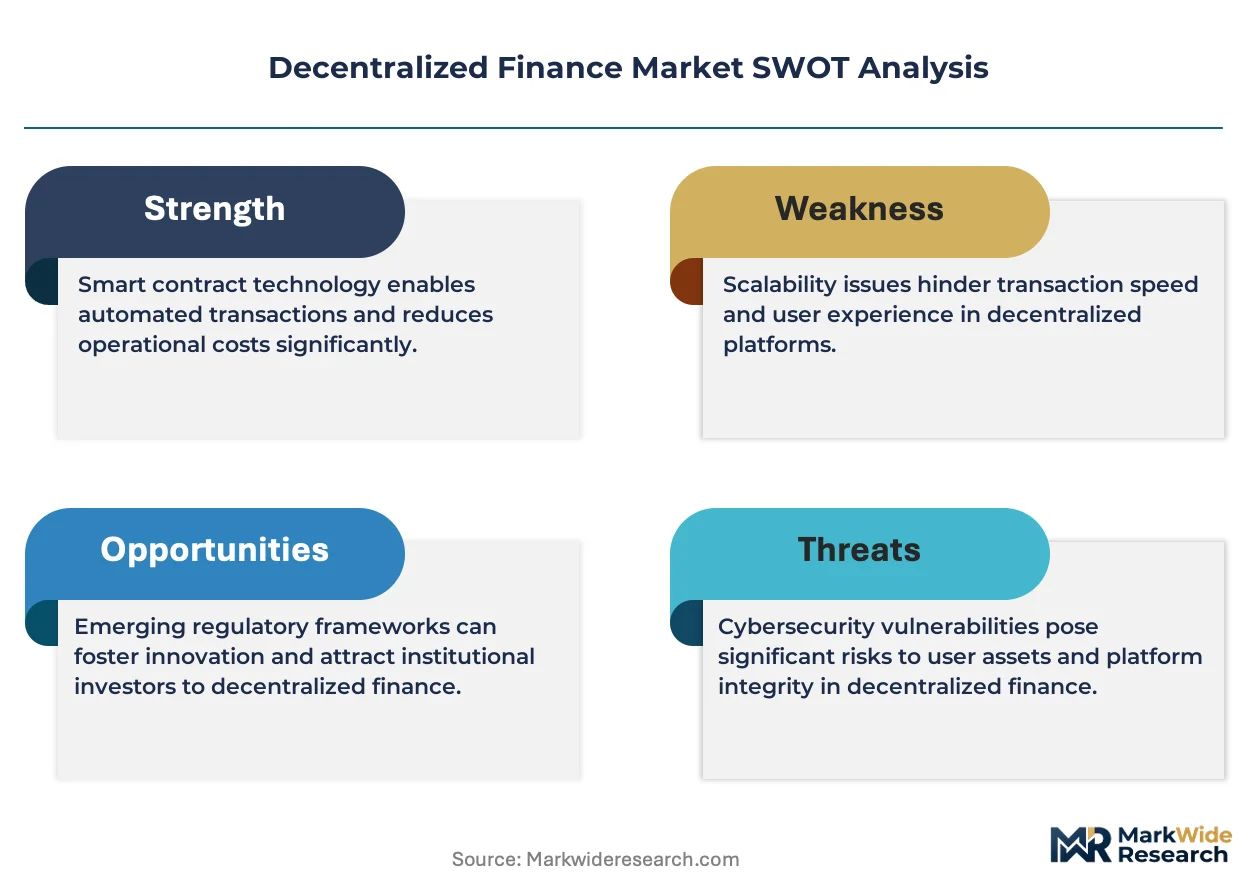
- Smart Contract Risk:Code vulnerabilities in automated market makers and lending pools expose capital to exploit-driven losses, requiring expensive audit cycles and insurance premiums.
- Stablecoin Reserve Transparency:Fiat-backed settlement tokens face recurring scrutiny over reserve composition, with Tether and Circle disclosures failing to match traditional money-market fund standards.
Strategic Opportunities
- Tokenized Real-World Assets:Private credit, real estate, and invoice financing instruments on public blockchains unlock yield sources disconnected from crypto-native volatility.
- Cross-Chain Interoperability:Messaging protocols like LayerZero and Axelar enable capital-efficient position management across Ethereum, Solana, and Cosmos ecosystems without fragmented liquidity.
- Regulatory Arbitrage Structuring:Protocols establishing legal entities in Switzerland and the Cayman Islands capture institutional flows blocked from unlicensed jurisdictions.
Industry Challenges
- Smart Contract Engineering Talent:Protocols compete for finite Solidity and Rust developer capacity, with compensation premiums exceeding traditional fintech engineering roles by substantial margins.
- Oracle Infrastructure Reliability:Price feed manipulation attacks on Chainlink and alternative oracle networks threaten collateral liquidation accuracy, requiring redundant data source architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decentralized Finance Market |
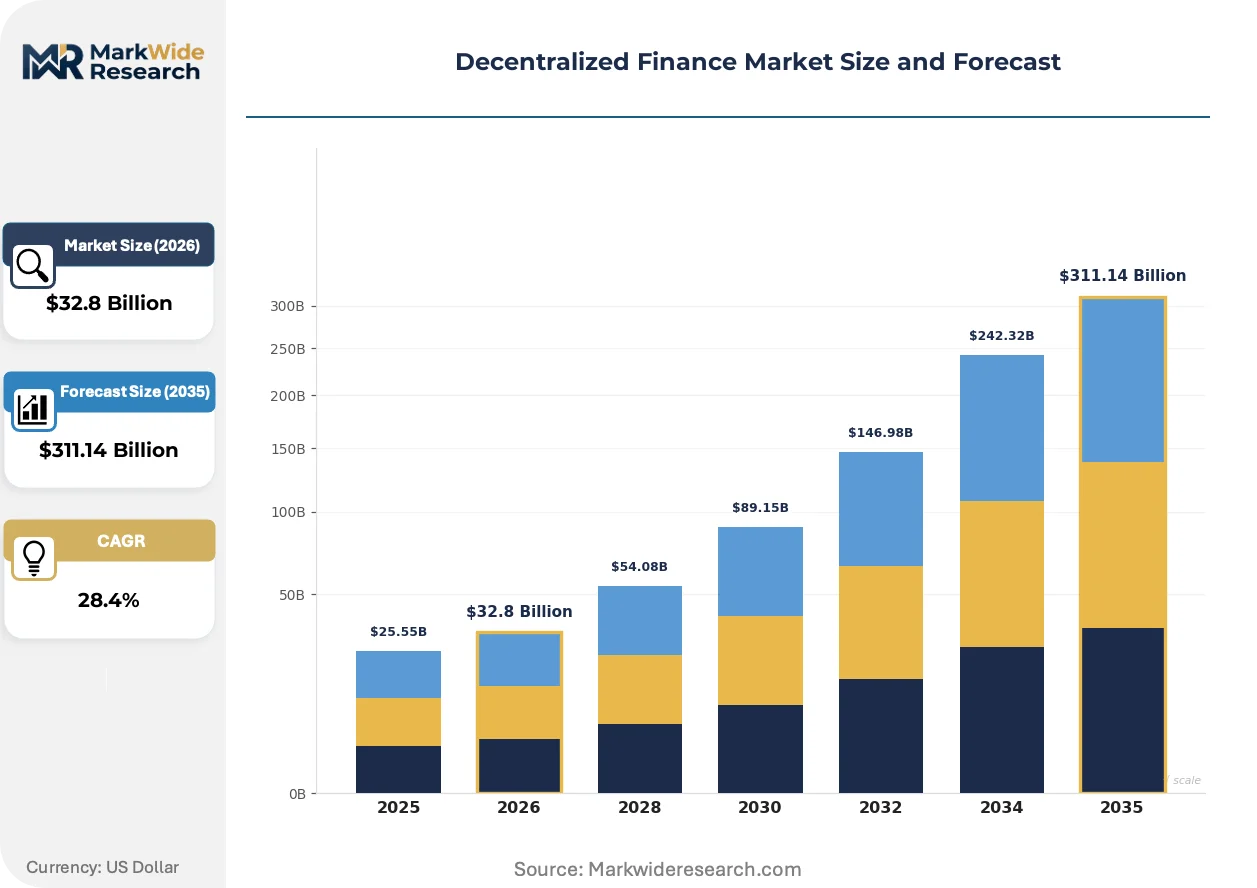
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $311.14 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decentralized Exchanges, Lending Protocols, Yield Farming, Stablecoins Technology: Blockchain, Smart Contracts, Tokenization, Interoperability User Type: Retail Investors, Institutional Traders, DeFi Developers, Liquidity Providers Service Type: Asset Management, Insurance Solutions, Payment Processing, Audit Services |
| Companies Covered | MakerDAO, Aave, Uniswap, Compound Labs, SushiSwap, Curve Finance, Synthetix, Balancer, Bancor Network, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decentralized Finance Market Strategic Shifts & Innovations
Automation of financial intermediation is compressing execution timelines from days to seconds, eliminating settlement layers that previously absorbed basis points in friction. This velocity shift demands recalibration of risk monitoring and compliance infrastructure.
Intent-based architectures are electrifying trade execution across decentralized exchanges. These systems allow users to specify desired outcomes rather than precise transaction paths, with solvers competing to fulfill orders through optimal routing. Sophisticated market makers at Wintermute and Jump Crypto are deploying capital to capture flow, compressing spreads for large-block trades that previously fragmented across multiple liquidity venues. The structural consequence is displacement of traditional request-for-quote workflows with programmatic, competitive fulfillment.
The EU's DORA regulation imposes operational resilience requirements on crypto-asset service providers, mandating incident reporting and stress testing protocols comparable to traditional financial infrastructure. Protocols serving European users must implement governance mechanisms and third-party risk management frameworks that mirror MiFID II standards. Decentralized autonomous organizations are responding by establishing Swiss foundation structures that assume liability for compliance execution.
Treasury management behavior is rotating from speculative yield farming to principal-protected instruments. Corporate finance teams at technology and real estate firms now prioritize overcollateralized lending positions and insured custody over leveraged liquidity mining. This preference shift is most visible in Singapore and Switzerland, where regulated digital asset banks offer segregated accounts with statutory deposit protections unavailable in unlicensed protocol interactions.
Decentralized Finance Market Segmentation
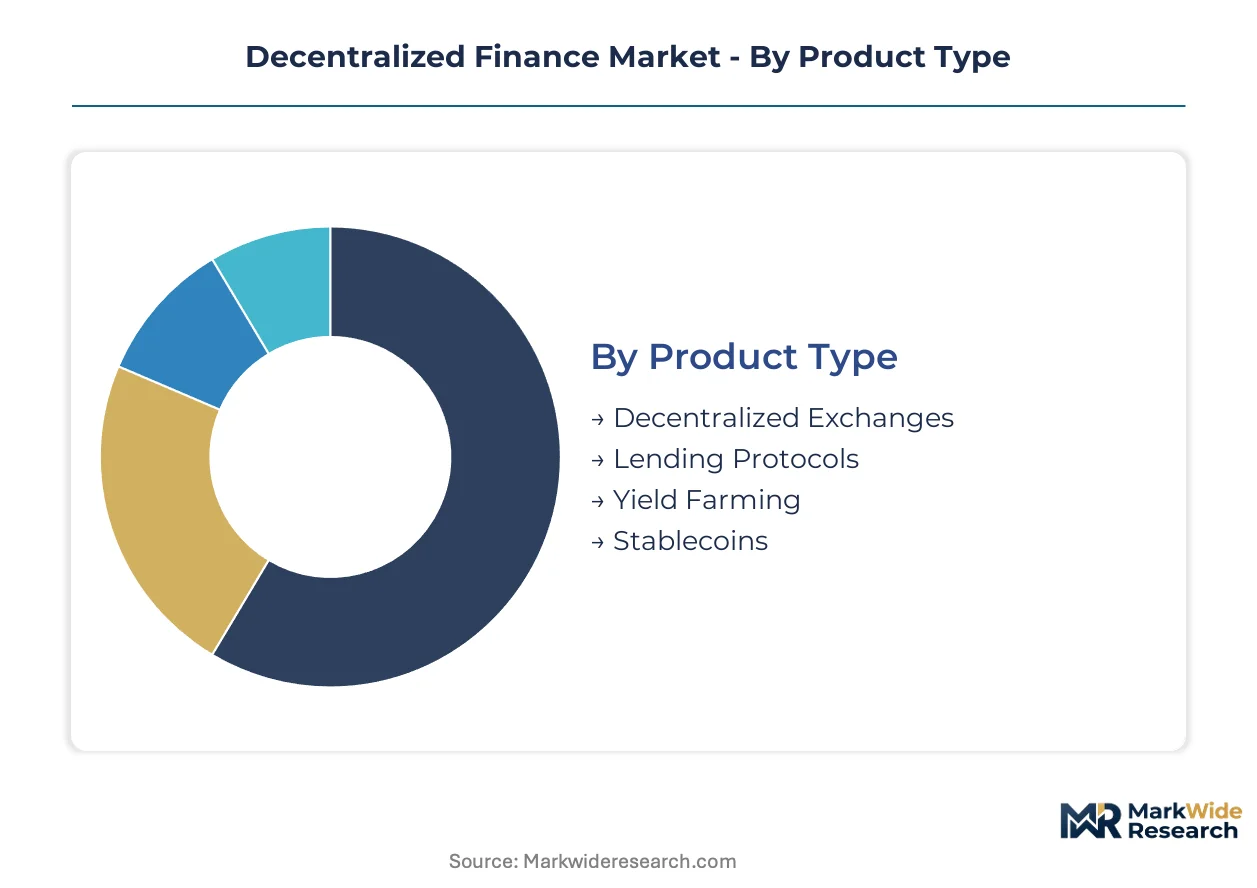
DeFi market segmentation reveals how infrastructure layers, participant profiles, and service architectures determine capital allocation patterns. Each axis exposes distinct risk tolerances, regulatory exposure, and technical requirements that shape protocol design and revenue models.
Product Type:
Protocol mechanics define liquidity depth, fee generation potential, and counterparty risk exposure across the DeFi stack.
- Decentralized Exchanges:Automated market makers and orderbook variants execute peer-to-contract trading without centralized custody. Singapore's licensed digital asset infrastructure attracts institutional-sized flow seeking reduced slippage through concentrated liquidity architectures.
- Lending Protocols:Collateralized debt positions and pooled lending markets generate yield through algorithmic interest rate curves. Institutional treasury departments in Switzerland and the Cayman Islands deploy capital here for principal-protected returns disconnected from crypto volatility.
- Yield Farming:Liquidity mining incentives reward protocol participation with governance tokens and fee shares. Retail capital concentrates where gas costs on Ethereum Layer-2 rollups compress entry thresholds.
- Stablecoins:Fiat-backed and algorithmic settlement tokens bridge on-chain and off-chain economies. Demand clusters where MiCA-licensed issuers provide statutory reserve transparency unavailable in unregulated alternatives.
Mature deployment sits with Lending Protocols. Newer deployment is concentrated in Yield Farming.
Technology:
Technical foundations determine settlement finality, composability boundaries, and cross-chain capital efficiency.
- Blockchain:Distributed ledger infrastructure provides immutable transaction records and consensus-driven state validation. Ethereum mainnet retains institutional preference for security guarantees despite higher gas costs.
- Smart Contracts:Self-executing code enforces lending, trading, and custody logic without intermediary intervention. Solidity engineering scarcity drives compensation premiums exceeding traditional fintech roles substantially.
- Tokenization:On-chain representation of real-world assets unlocks fractional ownership and programmable transfer mechanics. Private credit and real estate instruments in Singapore and Switzerland attract regulated institutional participation.
- Interoperability:Cross-chain messaging protocols enable capital-efficient position management across Ethereum, Solana, and Cosmos ecosystems. LayerZero and Axelar architectures reduce liquidity fragmentation for multi-chain treasuries.
Established infrastructure centers on Blockchain. Expanding most quickly is Interoperability.
User Type:
Participant sophistication dictates interface complexity, compliance requirements, and risk management tooling.
- Retail Investors:Individual participants access DeFi through wallet interfaces and aggregated yield platforms. European users migrate toward MiCA-licensed service providers reducing legal uncertainty.
- Institutional Traders:Hedge funds and proprietary desks execute block-sized transactions through segregated custody and insured settlement. Singapore's MAS licensing framework attracts family offices seeking statutory protections.
- DeFi Developers:Protocol engineers build and maintain smart contract systems across Solidity and Rust environments. Talent competition intensifies as audit costs and exploit risks escalate.
- Liquidity Providers:Capital suppliers earn fees from automated market makers and lending pools while bearing impermanent loss exposure. Sophisticated providers at Wintermute and Jump Crypto deploy inventory across intent-based execution venues.
Dominant participation flows through Institutional Traders. Steepest expansion trajectory belongs to DeFi Developers.
Service Type:
Ancillary infrastructure determines operational resilience, regulatory compliance, and institutional onboarding friction.
- Asset Management:On-chain portfolio allocation and automated rebalancing services optimize risk-adjusted returns. Swiss foundation structures assume liability for European DORA compliance execution.
- Insurance Solutions:Smart contract coverage and slashing protection mitigate exploit-driven capital losses. Premium pricing reflects audit quality and claims history across protocol categories.
- Payment Processing:Fiat on-ramps and merchant settlement bridges connect DeFi liquidity to traditional commerce. MiCA authorization requirements reshape European provider economics.
- Audit Services:Code review and formal verification reduce vulnerability exposure before protocol deployment. Demand concentrates where institutional capital requires third-party risk attestation.
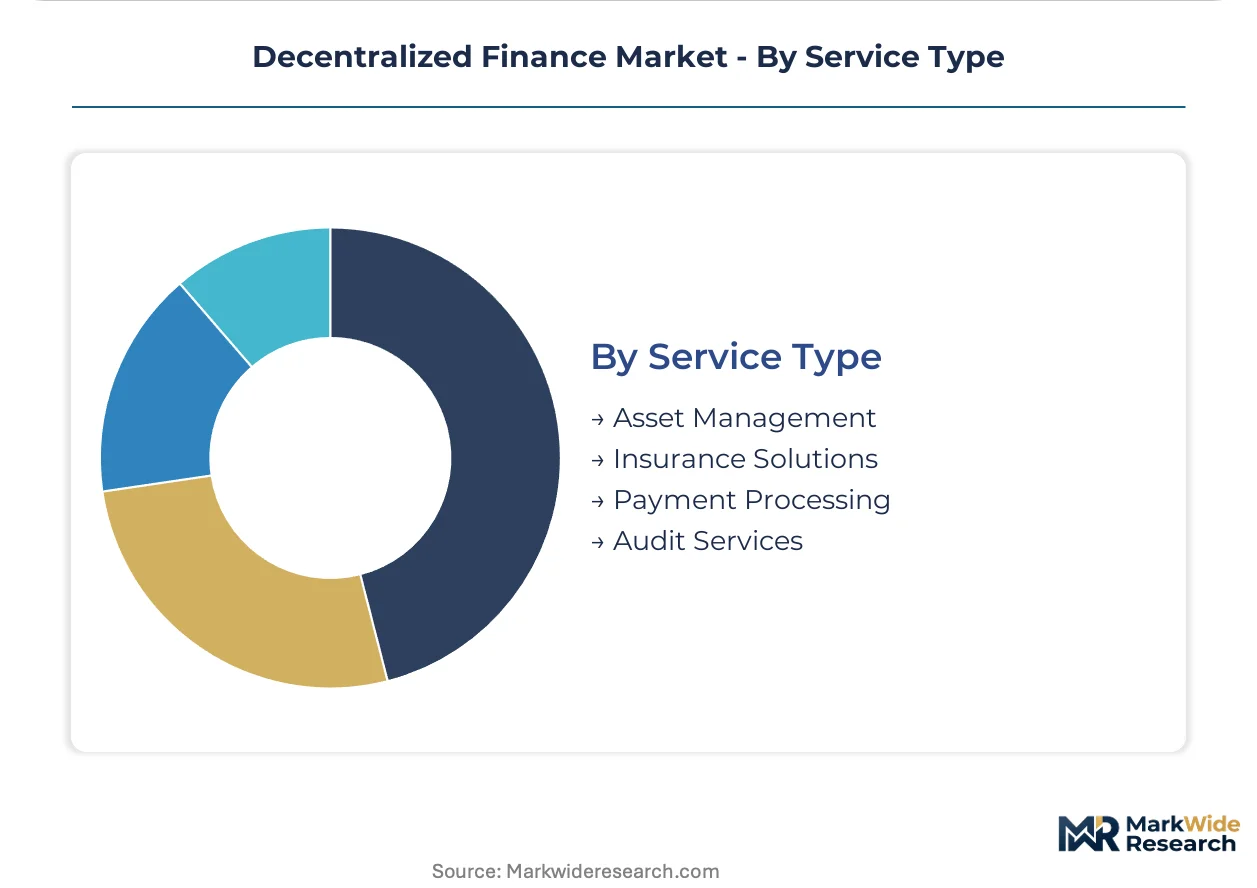
Regulatory pressure elevates Audit Services. Gaining share fastest is Insurance Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors institutional DeFi deployment, where licensed digital asset banks concentrate capital flows seeking regulatory clarity and statutory custody protections unavailable in offshore jurisdictions.
United States
Hedge funds and venture capital firms in New York and San Francisco drive protocol development and liquidity provision. The SEC classifies certain governance tokens as unregistered securities, forcing developers to restructure disclosure practices. Miami's emerging crypto corridor attracts firms seeking state-level regulatory experimentation outside federal enforcement zones.
Switzerland
Family offices and private banks in Zurich and Geneva channel capital into overcollateralized lending protocols for principal-protected yield. FINMA guidelines establish clear authorization pathways for crypto-asset service providers. The Crypto Valley cluster in Zug hosts foundation structures that assume liability for European DORA compliance execution.
Singapore
Treasury departments of technology and real estate firms deploy capital through MAS-licensed digital payment token frameworks. The Monetary Authority's statutory custody protections attract institutional flows blocked from unlicensed protocol interactions. The Marina Bay financial district concentrates licensed digital asset infrastructure with segregated account protections.
United Kingdom
Proprietary trading desks and fintech developers in London execute multi-chain position management through Layer-2 rollup architectures. The Financial Conduct Authority's evolving stablecoin regime shapes issuer reserve transparency requirements. The City of London cluster hosts audit and insurance providers serving institutional DeFi onboarding.
Germany
Corporate treasury units in Frankfurt and Berlin rotate from speculative yield farming to insured custody and regulated lending positions. BaFin licensing requirements for crypto custody businesses filter market access toward compliant infrastructure. The Frankfurt financial center attracts MiCA-authorized service providers seeking EU passporting rights.
Decentralized Finance Market Key Industry Players
Premium-margin players sit above commodity-margin players across compliance architecture and counterparty risk management capabilities. The market structure consolidates around protocols with institutional-grade audit histories and licensed legal entities. Three archetypes dominate: overcollateralized stablecoin issuers anchoring trust, multi-chain lending pool operators capturing liquidity depth, and automated market makers optimizing execution for large-order flow. Competitive moves concentrate on Swiss foundation restructuring for European regulatory compliance and Layer-2 deployment for gas cost reduction.
Within the protocol governance tier, MakerDAO exemplifies overcollateralized mechanics that anchor institutional capital deployment. Aave occupies a position representing multi-chain lending architecture across Ethereum and scaling networks. Uniswap sits within the automated market maker archetype, its concentrated liquidity design reducing slippage for block-sized transactions that previously fragmented across venues.
| Leading Market Players |
|---|
| MakerDAO |
| Aave |
| Uniswap |
| Compound Labs |
| SushiSwap |
| Curve Finance |
| Synthetix |
| Balancer |
| Bancor Network |
| Others |
Cost & Logistics Intelligence
Smart contract audit costs flow from specialized engineering labor through protocol deployment tiers, compressing margins for retail-accessible platforms while premium-grade infrastructure commands validation premiums in Singapore and Switzerland.
Pricing Analysis
Yield-based pricing anchors protocol revenue models, with lending pools extracting performance fees tied to realized returns rather than fixed subscriptions. Three-tier pricing structure across institutional custody, insured retail access, and permissionless self-custody separates compliance-bundled services from bare protocol interaction. Pricing pressure stems from Layer-2 gas compression reducing execution friction and compressing fee capture for base-layer settlement. Institutional traders exhibit lowest price sensitivity, absorbing custody and insurance premiums for statutory protections, while retail participants migrate toward lowest-cost rollup venues.
Supply Chain Analysis
Single-source vulnerability sits with Ethereum validator concentration, where staking derivatives and liquid staking protocols anchor collateral flows through a narrow base-layer consensus. Smart contract engineering talent draws from the United States, Switzerland, and Singapore, with Solidity and Rust expertise commanding compensation premiums exceeding traditional fintech roles. Oracle infrastructure dependencies create systemic risk exposure through price feed manipulation vectors. Distribution runs through wallet interfaces and institutional prime brokerage layers that abstract protocol complexity for end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DeFi infrastructure is becoming a vertical-integration race, with protocols pursuing captive audit capabilities and proprietary oracle networks to capture margin pools currently leaking to third-party service providers.
For Market Incumbents: Anticipate regulatory arbitrage fragmentation by securing MiCA licensing in Germany and MAS authorization in Singapore before enforcement thresholds harden. Consolidate around overcollateralized mechanics and segregated custody structures that anchor institutional trust. Acquire specialized audit firms to internalize security validation and reduce external dependency premiums. For New Entrants and Emerging Players: Intent-based execution architectures offer a technology-first wedge into institutional flow capture currently dominated by Wintermute and Jump Crypto. Target cross-chain messaging infrastructure as the most penetrable layer, where interoperability protocols remain undersupplied relative to multi-chain treasury demand. Pursue white-label deployment through Swiss foundation structures to bypass direct regulatory liability. For Investors and Strategic Acquirers: MAS licensing announcements from Singapore-based protocols are the leading indicator that institutional capital rotation into regulated onshore DeFi is accelerating. Position for long-term viability by targeting protocols with established Swiss foundation governance and Layer-2 deployment momentum. Monitor SEC enforcement actions against unregistered token issuances as the primary signal for jurisdictional capital migration patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Swiss Foundation Restructuring | Enables European DORA compliance execution through liability-shielded governance entities in Zug. |
| Layer-2 Deployment Expansion | Reduces gas costs for institutional-sized transactions on Ethereum rollup architectures. |
| Proprietary Oracle Network Development | Captures price feed infrastructure margin currently extracted by Chainlink and alternatives. |
| Tokenized Real-World Asset Integration | Unlocks private credit and real estate yield sources disconnected from crypto-native volatility. |
| Cross-Chain Messaging Protocol Launch | Enables capital-efficient position management across Ethereum, Solana, and Cosmos ecosystems. |
Research Approach
Document review covered protocol whitepapers, SEC enforcement filings, EU MiCA regulatory texts, and MAS licensing announcements, complemented by interviews with DeFi protocol developers, institutional treasury managers at technology firms, smart contract auditors, and digital asset custody providers. Secondary validation drew from on-chain analytics platforms, DEX volume aggregators, and lending protocol transparency reports. Bottom-up transaction flow analysis triangulated against top-down regulatory impact assessment.
Market sizing outputs reflect protocol revenue aggregation across lending interest spreads, DEX trading fees, and stablecoin issuance yields, segmented by infrastructure layer, participant sophistication, and jurisdictional regulatory framework. CAGRs were derived from institutional capital deployment velocity and compliance-driven market access expansion. Forecast inputs incorporated Layer-2 adoption curves and MiCA implementation timelines.
Several conditions sit outside the modeled scope, including extreme smart contract exploit events, coordinated regulatory bans across multiple jurisdictions, and fundamental Layer-1 consensus failures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market