
 Digital Asset Management (DAM) Market | 2026-2036
Digital Asset Management (DAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Asset Management (DAM) Market Intelligence
Multi-source vendor strategies is realigning how enterprises procure DAM capabilities, shifting from single-suite dependencies to best-of-breed integrations. Bynder leverages API-first architecture to sustain interoperability across marketing technology stacks. Canto anchors its position through intuitive user experience design that reduces onboarding friction for mid-market creative teams. Frontify differentiates by occupying the brand operations niche, extending beyond asset storage into governance and templating workflows.
Digital Asset Management encompasses software platforms that ingest, store, organize, retrieve, and distribute rich media files through metadata tagging, version control, and rights-management protocols, serving primarily to accelerate content velocity and ensure brand consistency across distributed marketing operations. Cloud-based deployment leads solution uptake as organizations prioritize elastic scalability and reduced infrastructure overhead, while hybrid configurations retain relevance among financial services and healthcare entities with strict data residency requirements. Enterprise DAM solutions command the largest revenue pool due to complex permission hierarchies and integration demands, though open-source alternatives attract digitally mature organizations seeking customization control.
FDA 21 CFR Part 11 compliance requirements shape DAM specifications for pharmaceutical marketing materials, while GDPR and the EU AI Act impose audit trails and automated consent tracking that vendors must embed by design. ISO 27001 certification has become a baseline threshold for vendor selection in regulated sectors, with procurement teams rejecting uncertified platforms outright. Stakeholders should evaluate metadata interoperability standards and emerging AI-generated content provenance protocols before committing to long-term platform contracts.
Market Dynamics
Cloud migration mandates under GDPR and the EU AI Act are forcing pharmaceutical, retail, and financial services enterprises to replace on-premise DAM infrastructure with auditable, elastic platforms that embed automated consent tracking and data lineage by design.
Growth Catalysts
- Omnichannel content velocity:Retail and consumer goods enterprises require unified asset distribution across e-commerce, social, and physical touchpoints. DAM platforms reduce creative production cycles through templating and automated variant generation.
- GDPR Article 30 compliance:European enterprises must maintain records of processing activities for all personal data in marketing assets. DAM vendors embedding automated metadata tagging and retention policies capture procurement preference.
- AI-generated content provenance:Marketing teams deploying synthetic media need immutable audit trails establishing authenticity and rights clearance. DAM platforms with blockchain-anchored provenance protocols address this emerging requirement.
Market Restraints
- Enterprise integration complexity:Legacy marketing technology stacks in financial services and healthcare require extensive API customization. Implementation timelines stretch 12-18 months, delaying revenue recognition for vendors.
- Specialized talent scarcity:DAM administrators with expertise in metadata taxonomy design, rights management, and marketing operations command premium compensation. Mid-market enterprises struggle to retain this capability.
- Data residency fragmentation:National data localization laws in Germany, France, and Switzerland mandate sovereign cloud deployment. Vendors lacking regional infrastructure partnerships face exclusion from public sector and regulated industry procurement.
Strategic Opportunities
- Mid-market creative team penetration:Agencies and boutique brands in Spain, Italy, and Poland currently rely on shared drives and manual versioning. SaaS DAM solutions with intuitive onboarding capture this underserved segment.
- Pharmaceutical marketing compliance:FDA 21 CFR Part 11 validation requirements for electronic records create demand for DAM platforms with built-in electronic signatures, audit trails, and archival integrity. Vendors with pre-validated configurations accelerate sales cycles.
- Brand governance convergence:Enterprises seek unified platforms combining asset storage, brand guidelines, and template libraries. DAM vendors extending into brand operations workflows displace point solutions and capture expanded contract value.
Industry Challenges
- Metadata standardization gaps:Interoperability between DAM platforms and adjacent marketing technologies requires consistent schema definitions. Industry consortia have failed to establish dominant standards, forcing costly custom mapping projects.
- Rights management complexity:Multi-territory licensing agreements for stock photography, music, and talent releases create compliance exposure. Automated expiration tracking and territory-based access controls remain technically immature.
- Legacy system coexistence:Enterprises with substantial investments in on-premise content repositories face difficult migration decisions. Hybrid deployment architectures introduce synchronization latency and version control conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Asset Management (DAM) Market |
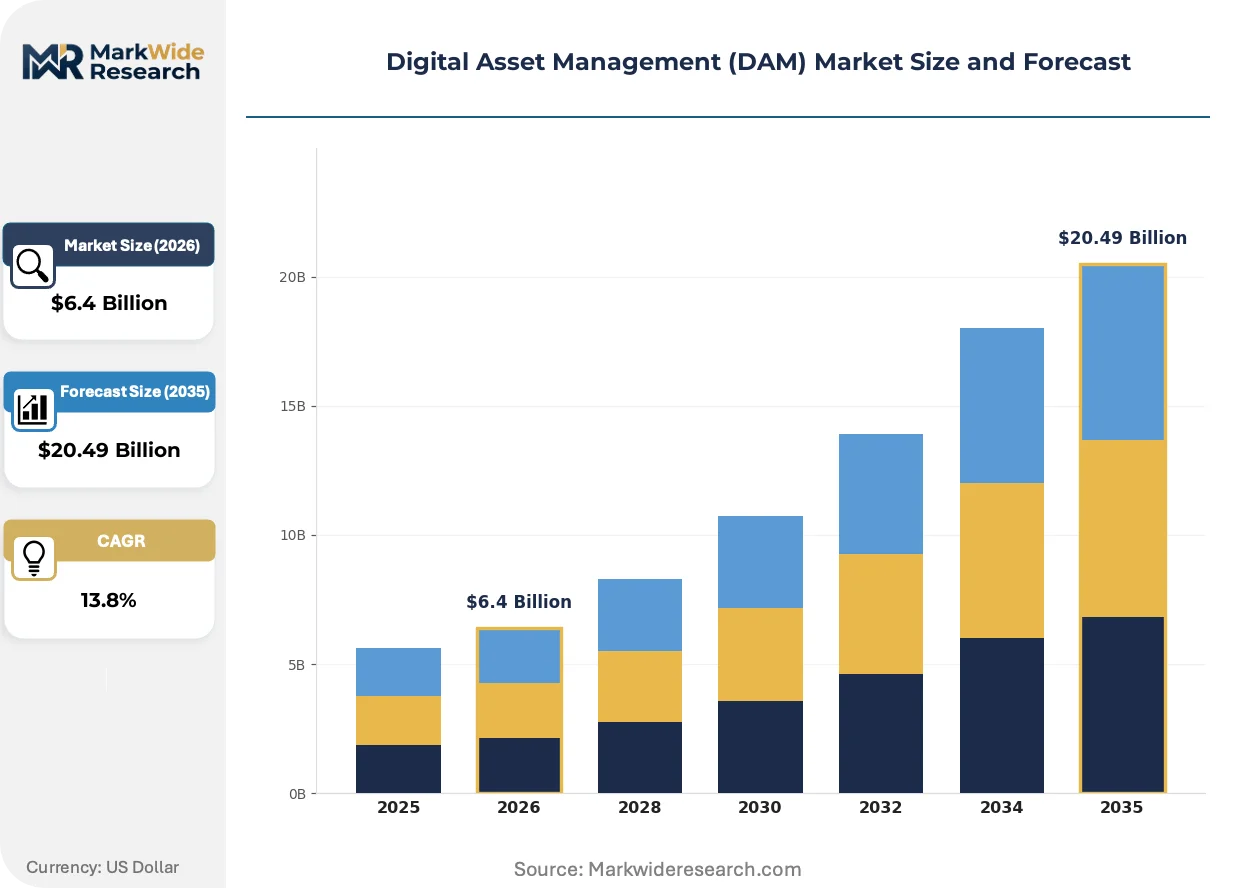
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $20.49 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Private Cloud Solution Type: Enterprise DAM, Cloud DAM, Open Source DAM, On-Premise DAM Application: Content Management, Brand Management, Media Management, Workflow Automation, Archiving End User: Advertising Agencies, Media Publishers, Marketing Firms, Educational Institutions |
| Companies Covered | Brandfolder, Canto, contentcloud, Air, Aprimo, MediaValet, Acquia DAM, Frontify, Bynder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Asset Management (DAM) Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how marketing organizations create, manage, and distribute visual assets. Three developments are compressing traditional workflows and redefining platform requirements.
Generative AI integration is decentralizing creative production authority from centralized agencies to distributed marketing teams. Mid-market enterprises in retail and consumer goods are deploying text-to-image and text-to-video capabilities at scale. This technology is decentralizing asset creation timelines from weeks to hours, compressing demand for traditional creative services and elevating governance requirements within DAM platforms.
The EU AI Act's transparency obligations for synthetic media are mandating technical documentation and labeling standards that reshape platform architecture. Marketing materials containing AI-generated elements must carry machine-readable provenance markers. Pharmaceutical and financial services segments in Germany and France are prioritizing DAM vendors with embedded compliance modules over generalist alternatives.
Self-service procurement models are displacing traditional enterprise sales cycles in the DAM sector. Marketing operations leaders in technology and professional services verticals now expect transparent pricing, instant provisioning, and usage-based scaling. This pattern is most pronounced in the United States, where procurement autonomy has shifted to departmental buyers who reject lengthy vendor negotiation processes.
Digital Asset Management (DAM) Market Segmentation
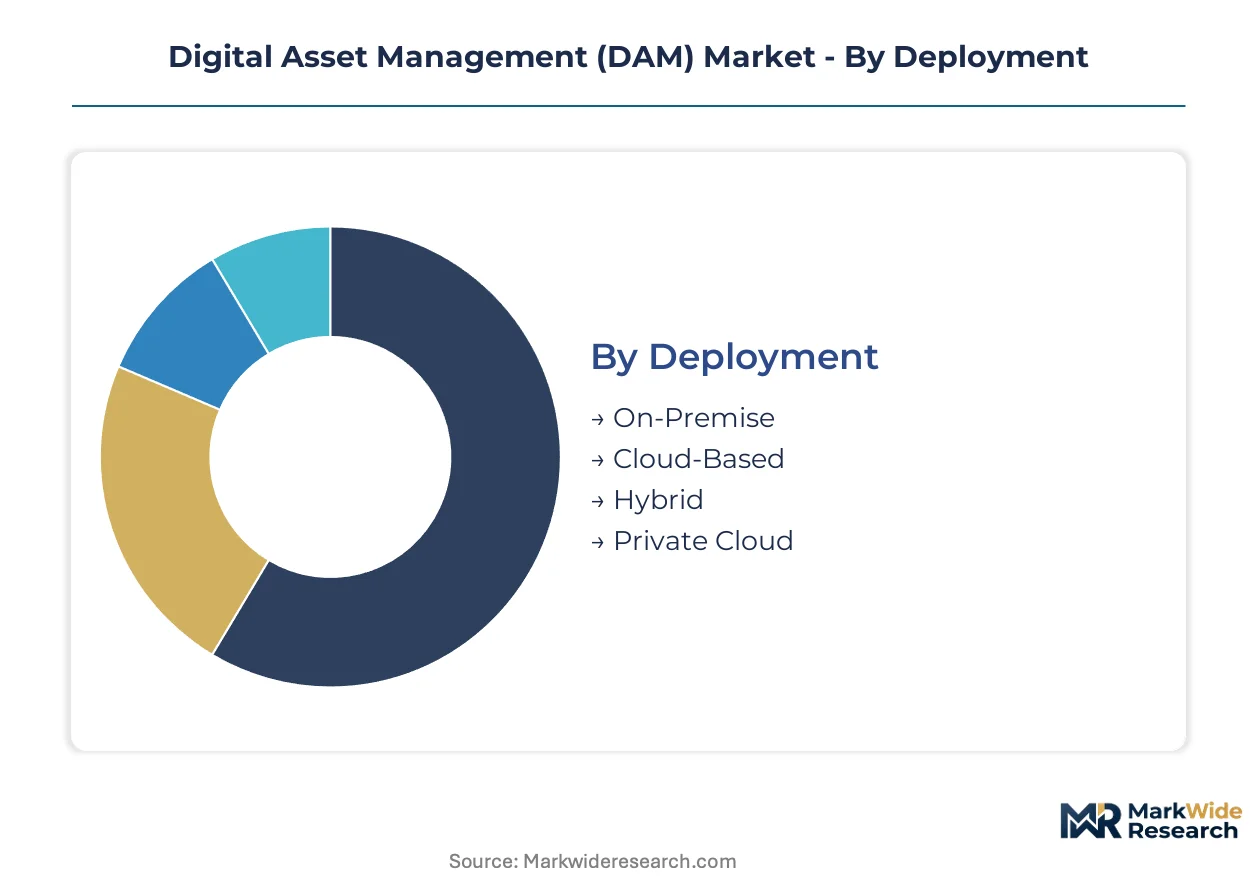
Deployment architecture determines total cost of ownership and compliance posture for DAM procurement. Solution type reflects organizational maturity and customization requirements. Application focus and end-user profile shape feature prioritization and integration complexity.
Deployment:
Buyers weigh elastic scalability against data sovereignty mandates when selecting infrastructure models.
- Cloud-Based:Multi-tenant SaaS platforms deliver automatic updates and usage-based scaling without capital expenditure. Retail and consumer goods enterprises in the United States prioritize this model to support seasonal traffic spikes and distributed creative teams.
- Hybrid:Split architectures maintain sensitive assets on-premise while pushing distribution workloads to cloud edge nodes. Financial services and healthcare entities in Germany and Switzerland adopt this configuration to satisfy GDPR data residency requirements while enabling external collaboration.
- On-Premise:Self-managed infrastructure retains full operational control over hardware and network security.
- Private Cloud:Single-tenant hosted environments dedicate physical resources to individual organizations.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution Type:
Organizational scale and IT governance maturity drive selection between packaged and customizable platforms.
- Enterprise DAM:Comprehensive platforms support complex permission hierarchies, federated search across multiple repositories, and deep ERP integration. Large marketing operations in Japan demand these capabilities for coordinating content across dozens of brand portfolios and regional subsidiaries.
- Open Source DAM:Community-developed codebases enable unrestricted modification and avoid vendor lock-in. Digitally mature organizations with internal development resources leverage these tools to build proprietary metadata schemas and workflow automations.
- Cloud DAM:SaaS-native solutions emphasize rapid deployment and minimal IT involvement.
- On-Premise DAM:Perpetual-license software installed within organizational data centers.
Enterprise DAM dominates contract value; Open Source DAM climbs fastest among technology-forward adopters.
Application:
Functional scope determines integration touchpoints and user training requirements.
- Brand Management:Unified platforms combine asset libraries with guideline documentation, template systems, and approval workflows. Consumer goods manufacturers deploy these tools to enforce visual consistency across franchisee networks and co-branded partnerships.
- Workflow Automation:Embedded orchestration engines route assets through creative review, legal clearance, and localization pipelines. Advertising agencies in France implement these capabilities to compress campaign production cycles and reduce manual handoff errors.
- Content Management:Core repository functions for ingestion, storage, and retrieval.
- Media Management:Specialized handling for broadcast video, streaming formats, and high-resolution imagery.
- Archiving:Long-term preservation with format migration and retrieval optimization.
Brand Management captures the largest deal sizes; Workflow Automation shows the steepest expansion trajectory.
End User:
Organizational purpose shapes collaboration patterns and rights management complexity.
- Advertising Agencies:Project-based workflows demand rapid client onboarding, external sharing controls, and usage tracking for billable hours. Multi-office networks require synchronized asset access across time zones.
- Marketing Firms:In-house corporate teams prioritize brand governance and integration with marketing automation stacks.
- Media Publishers:High-volume production environments need broadcast-grade transcoding and multi-channel distribution.
- Educational Institutions:Budget-constrained buyers favor lightweight solutions with academic pricing and limited administrative overhead.
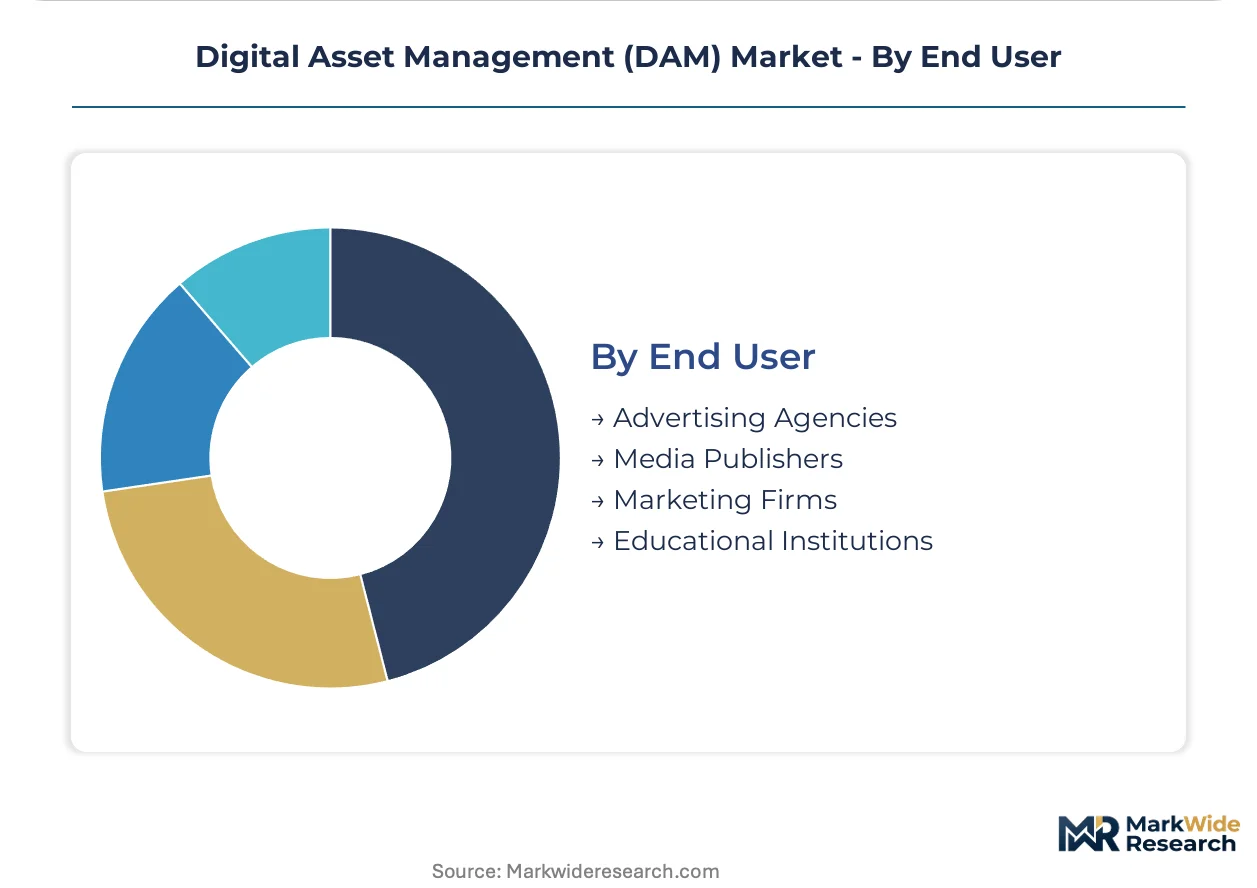
Advertising Agencies lead on user count; Marketing Firms lead on per-seat value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping DAM procurement as enterprises migrate cloud infrastructure toward jurisdictions with clearer data sovereignty frameworks and streamlined compliance costs.
United States
Technology and professional services firms drive SaaS DAM adoption through departmental procurement autonomy. HIPAA compliance requirements shape healthcare marketing asset workflows. Silicon Valley and New York City clusters concentrate demand for API-first platforms with instant provisioning capabilities.
Germany
Automotive and industrial manufacturers require federated search across distributed brand portfolios. GDPR Article 30 mandates automated metadata tagging for personal data in marketing materials. Bavaria's manufacturing corridor and Berlin's startup ecosystem generate dual demand for enterprise-grade and mid-market solutions.
Japan
Consumer goods conglomerates coordinate content operations across dozens of regional subsidiaries and franchise networks. METI guidelines on digital transformation accelerate platform modernization. Tokyo and Osaka metropolitan areas anchor procurement for complex permission hierarchies and multi-language localization.
United Kingdom
Advertising agencies and media publishers prioritize workflow automation to compress campaign production cycles. CSRD disclosure requirements extend to marketing supply chain transparency. London's creative district and Manchester's media cluster sustain demand for rapid client onboarding and external sharing controls.
France
Luxury goods houses and pharmaceutical marketers seek immutable audit trails for AI-generated content provenance. CNIL enforcement of GDPR data retention policies drives automated consent tracking adoption. Paris and Lyon concentrate brand governance platform deployments with embedded compliance modules.
Digital Asset Management (DAM) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized vertical applications and API-native architectures. The vendor landscape segments across three maturity tiers: legacy suite providers with deep enterprise integration, cloud-native challengers emphasizing rapid deployment, and open-source alternatives targeting customization control. Competitive intensity concentrates on M&A activity consolidating adjacent marketing technology capabilities and strategic partnerships embedding DAM into broader content orchestration platforms.
Within the API-first tier, Bynder and Brandfolder exemplify architecture strategies prioritizing interoperability across marketing technology stacks. Canto anchors the mid-market creative segment through user experience design reducing onboarding friction. Frontify occupies a distinct position extending beyond asset storage into brand governance and templating workflows, representing the convergence archetype combining DAM with adjacent brand operations functionality.
| Leading Market Players |
|---|
| Brandfolder |
| Canto |
| contentcloud |
| Air |
| Aprimo |
| MediaValet |
| Acquia DAM |
| Frontify |
| Bynder |
| Others |
Cost & Logistics Intelligence
Enterprise marketing operations teams in pharmaceutical and financial services verticals concentrate procurement authority for DAM platforms, driving adoption of subscription-based SaaS tiers with embedded compliance modules that command premium positioning against self-serve alternatives.
Pricing Analysis
Direct-to-enterprise sales cycles capture the highest contract values through multi-year agreements with customized implementation services, while self-service channels penetrate mid-market segments through transparent per-seat tiers. Price differentiation hinges on ISO 27001 certification status and GDPR compliance automation depth. Pricing pressure stems from open-source alternatives attracting digitally mature buyers with internal development resources. Mid-market creative agencies exhibit the greatest price sensitivity, whereas regulated enterprises prioritize compliance assurance over cost minimization.
Supply Chain Analysis
ISO 27001 certification and GDPR Article 30 compliance documentation serve as mandatory qualification gates for vendor participation in European and North American procurement. Cloud infrastructure concentrates in the United States, Germany, and Japan, with sovereign cloud partnerships required for German and Swiss public sector access. Platform development draws from specialized talent pools in metadata taxonomy design, API engineering, and rights management protocol implementation. Single-source vulnerability in AI model training data licensing creates supply risk. Distribution runs through direct enterprise sales, self-service digital channels, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DAM market functions as a regulatory compounder where GDPR and EU AI Act compliance milestones create sustained platform replacement cycles across European enterprise installed bases.
For Market Incumbents: Acquire specialized workflow automation capabilities to extend platform functionality beyond asset storage into brand governance and templating operations. Consolidate API-first architecture investments to defend against cloud-native challengers exploiting integration complexity in legacy marketing technology stacks. Deepen vertical integration into sovereign cloud infrastructure partnerships for German and Swiss data residency requirements. For New Entrants and Emerging Players: Creative agency networks in Spain, Italy, and Poland represent the most penetrable channel partner type for SaaS DAM solutions displacing shared drive workflows. Target mid-market pharmaceutical marketers seeking pre-validated FDA 21 CFR Part 11 configurations without enterprise implementation timelines. Pursue white-label embedding partnerships with marketing automation platforms to bypass direct sales cycle friction. For Investors and Strategic Acquirers: Private equity firms with marketing technology portfolio holdings are the most active acquirer in this space, consolidating adjacent brand operations and content orchestration capabilities. Long-term viability favors vendors with proven metadata interoperability standards and AI-generated content provenance protocols. Monitor CNIL and German data protection authority enforcement patterns as inflection indicators for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables interoperability with Adobe, Salesforce, and SAP marketing stacks. |
| Acquisition of Specialist Firm | Workflow automation targets compress creative production cycles for advertising agency clients. |
| Geographic Expansion | Sovereign cloud deployment satisfies GDPR data residency mandates in Germany and Switzerland. |
| Product Launch | AI-generated content provenance modules address EU AI Act transparency obligations for synthetic media. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise implementation timelines for complex permission hierarchies. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with DAM vendor product managers, enterprise marketing operations directors, and creative agency technology leads. Secondary validation draws from SEC filings of publicly traded marketing technology companies, EU regulatory implementation guidance documents, and ISO certification registry databases. Bottom-up demand modeling triangulates against top-down market sizing from technology expenditure surveys.
Granularity-level modeling addresses deployment architecture, solution type, application focus, and end-user profile dimensions across the projection horizon. CAGRs derive from segment-specific growth trajectories weighted by regional adoption patterns. Forecast inputs incorporate GDPR enforcement intensity indices, pharmaceutical marketing compliance audit frequencies, and cloud infrastructure expansion announcements from hyperscale providers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementation timelines and generative AI content provenance standardization. Forecasts reflect assumptions regarding regulatory enforcement consistency, enterprise cloud migration velocity, and metadata interoperability consortium progress. A model refresh is warranted upon material change in CNIL or German data protection authority penalty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market