
 Online Microtransaction Market | 2026-2036
Online Microtransaction Market Size, Share, and Industry Trends Forecast 2026-2036
Online Microtransaction Market Analysis
Casual mobile players is reorganizing revenue flows away from hardcore console audiences in the Online Microtransaction Market. Tencent Holdings Ltd. leverages its WeChat Pay integration to dominate in-game purchase rails across Asia. Valve Corporation sustains Steam Wallet adoption through tight channel control over PC distribution. Electronic Arts Inc. competes via FIFA Ultimate Team mechanics that anchor recurring virtual goods spend.
Online microtransactions denote sub-dollar to low-double-digit digital payments executed within software ecosystems, typically processed through tokenized wallet systems or direct carrier billing with sub-second authorization latencies below 300 milliseconds. These friction-minimized exchanges primarily monetize engagement loops in interactive entertainment and creator platforms. In-game purchases within the transaction purpose dimension generate the deepest margin pools, while mobile wallet penetration across the payment method category is expanding fastest in emerging markets. Gaming consoles in the platform type segment remain mature with slower growth but higher average transaction values per user session.
The Federal Trade Commission in the United States scrutinizes loot-box mechanics as potential gambling-adjacent products, pressuring publishers to disclose odds and restrict minors. The European Commission's Digital Services Act imposes transparency obligations on platform operators regarding algorithmic amplification of purchasable virtual content. China's National Press and Publication Administration enforces strict spending caps for underage gamers, reshaping product design priorities for studios serving that geography. Stakeholders must monitor how fragmented regulatory frameworks across Washington, Brussels, and Beijing will force divergent monetization architectures rather than unified global product strategies.
Market Dynamics
Frictionless payment rails and algorithmic personalization engines are compressing purchase decision cycles, converting casual engagement into monetizable moments faster than legacy checkout architectures permit.
Growth Catalysts
- UPI infrastructure proliferation:India's unified payments interface enables sub-300 millisecond authorization latencies, removing the final conversion barrier for mobile-first gamer populations.
- WeChat Pay ecosystem lock-in:Super-app wallet integration across social, commerce, and gaming verticals creates captive purchase funnels with minimal user friction.
- Freemium model maturation:Southeast Asian studios deploy engagement-loop analytics to optimize whale-to-minnow conversion ratios without upfront content paywalls.
Market Restraints
- Input cost volatility:Cloud compute and bandwidth expenses for real-time transaction processing fluctuate with energy market instability, pressuring margin structures.
- Regulatory fragmentation:Divergent youth protection mandates across Washington, Brussels, and Beijing force redundant compliance architectures rather than unified product builds.
- Platform gatekeeper concentration:Apple and Google app store monopolies extract 30% transaction taxes, constraining publisher profitability and pricing flexibility.
Strategic Opportunities
- Creator economy convergence:Twitch and YouTube tipping mechanics merge with in-game purchase systems, enabling cross-platform virtual goods portability.
- Blockchain-based asset ownership:Non-fungible token interoperability standards allow secondary market royalties, unlocking persistent value beyond single-game lifecycles.
- Carrier billing penetration:Direct-to-bill payment rails in underbanked African and Latin American markets bypass traditional banking infrastructure entirely.
Industry Challenges
- Live-service talent scarcity:Economists and behavioral psychologists capable of designing ethical engagement mechanics command premium compensation, constraining studio expansion.
- Anti-addiction compliance timelines:China's NPPA mandates real-name verification and spending cap enforcement within 72-hour windows, requiring costly infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Microtransaction Market |
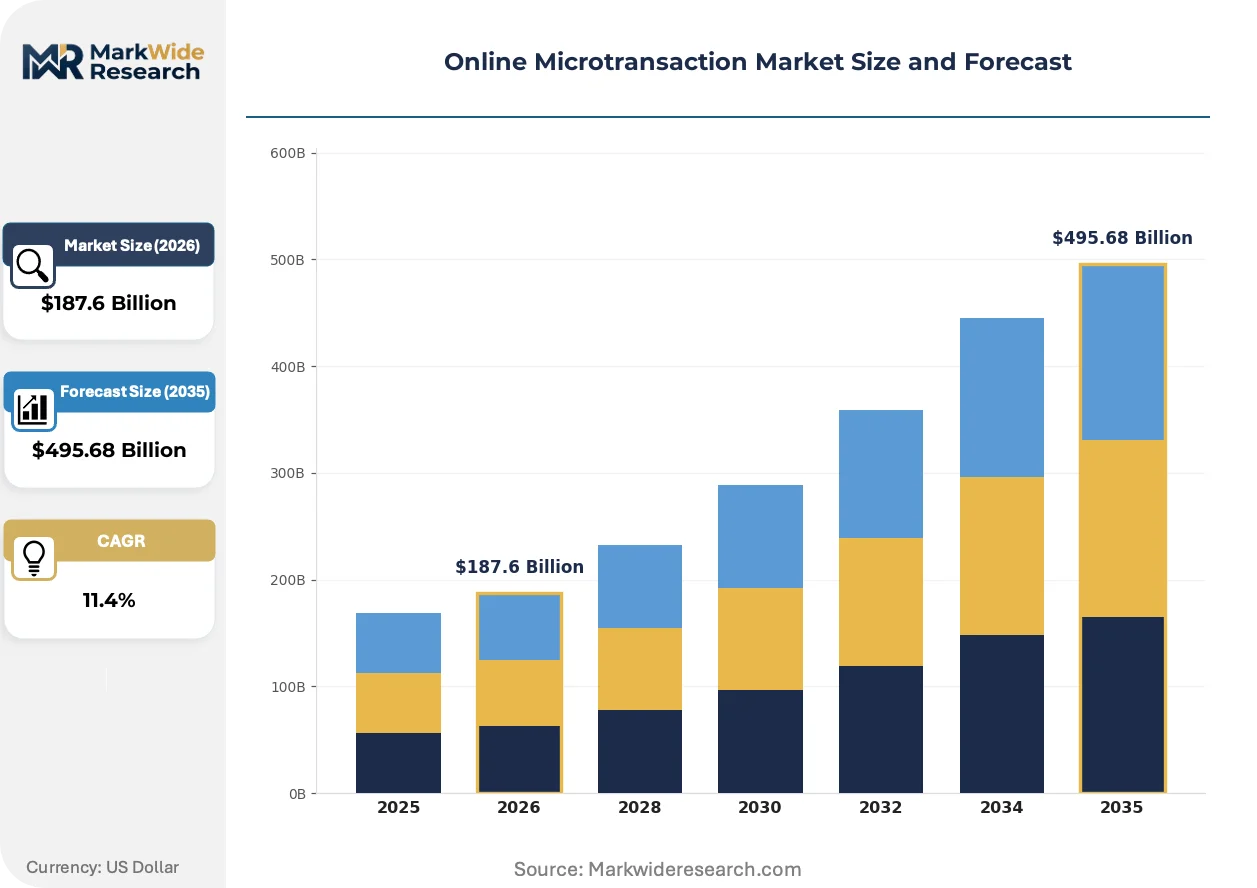
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, PayPal, Bitcoin, Mobile Wallet Platform Type: Mobile Apps, Web Browsers, Gaming Consoles, Desktop Applications Transaction Purpose: In-Game Purchases, Subscription Services, Virtual Goods, Unlockable Content End User Segment: Casual Gamers, Hardcore Gamers, Content Creators, Enterprises |
| Companies Covered | Activision Blizzard, Nexon Co., Ltd., Tencent Holdings Ltd., Valve Corporation, NetEase Inc., Microsoft Corporation, Electronic Arts Inc., Riot Games, Sony Interactive Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Microtransaction Market Emerging Trajectories
Algorithmic recommendation engines and biometric authentication protocols are collapsing the distance between intent and transaction, embedding commerce directly into interactive experiences without discrete purchase interruptions.
Tokenized wallet architectures are displacing traditional card-on-file systems by enabling one-tap authorization through biometric verification. Mobile-first publishers in India and Southeast Asia deploy these rails to capture impulse purchases during peak engagement moments. The structural consequence is a compression of checkout abandonment rates and an expansion of microtransaction frequency among previously cash-constrained demographics.
The European Commission's Digital Services Act imposes algorithmic transparency obligations on platforms amplifying purchasable virtual content. Publishers must now disclose recommendation logic and provide user controls over personalized purchase prompts. Gaming and creator platforms serving EU audiences are rebuilding content discovery layers to satisfy audit requirements while preserving conversion efficiency.
Subscription bundling is fragmenting standalone purchase behavior as consumers consolidate entertainment spend into all-access passes. Platform operators respond by tiering virtual goods exclusivity, reserving premium cosmetics and progression accelerators for direct microtransaction channels. This tension between flat-rate and à-la-carte monetization is most acute in North American and Western European markets where subscription fatigue has set in.
Online Microtransaction Market Segmentation
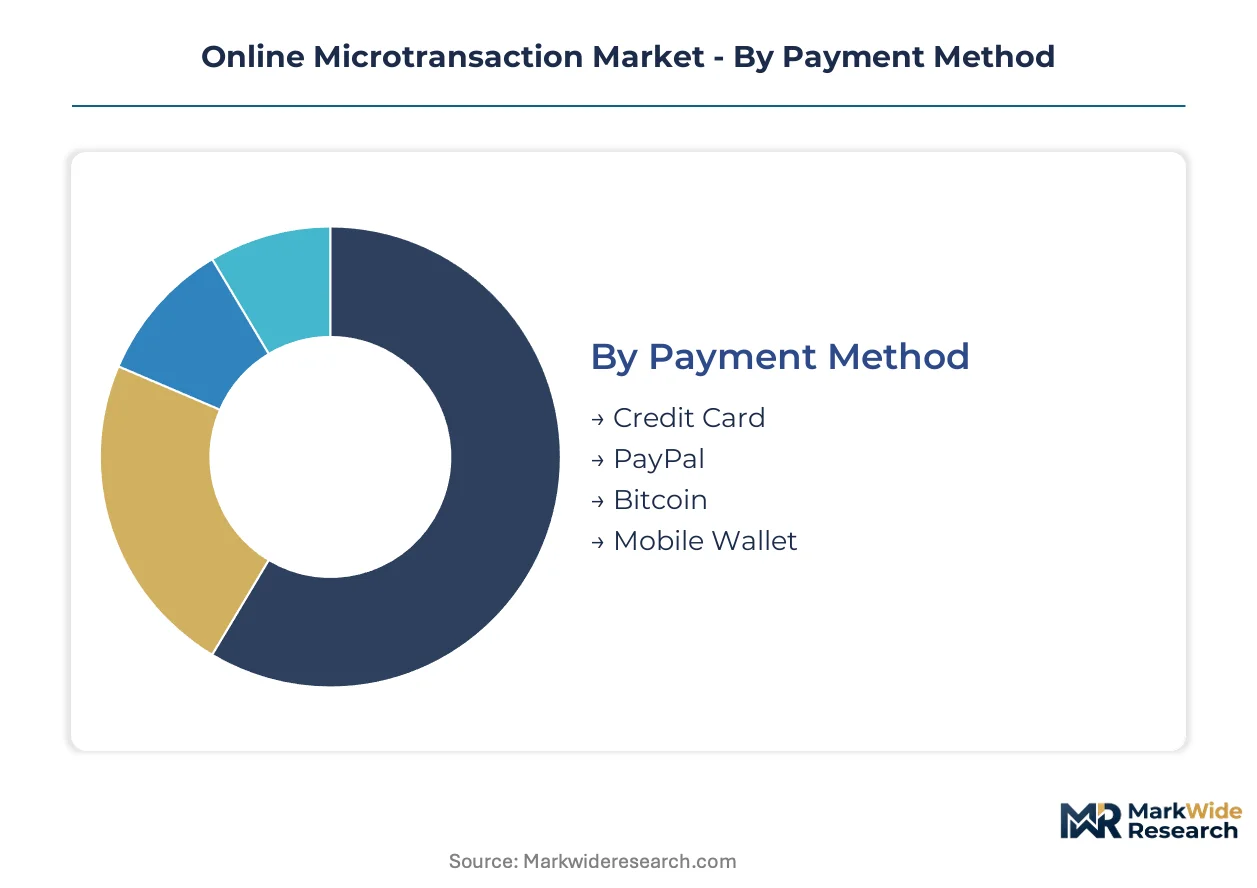
Payment rails and platform architectures fragment the Online Microtransaction Market into distinct monetization ecosystems. Each segment category carries divergent margin profiles, regulatory exposure, and geographic concentration patterns that shape competitive positioning.
Payment Method:
Mobile wallets dominate emerging market volumes while credit cards anchor developed economy spend. Geographic spread determines infrastructure investment priorities across payment rails.
- Credit Card:Traditional card-on-file systems process higher average transaction values with established chargeback protections. Demand concentrates in North America and Western Europe where revolving credit penetration exceeds 70% of adult populations. PCI-DSS compliance costs constrain entry for smaller publishers.
- Mobile Wallet:Tokenized biometric authorization enables sub-300 millisecond purchase completion, collapsing abandonment rates. India's UPI rails and China's WeChat Pay ecosystem drive fastest volume expansion among previously unbanked demographics. Interoperability standards remain fragmented across national boundaries.
- PayPal:Buyer protection policies and established trust metrics sustain adoption among risk-averse consumer segments. Merchant fees compress margins relative to direct carrier billing alternatives.
- Bitcoin:Pseudonymous settlement appeals to privacy-conscious users and cross-border remittance scenarios. Volatility exposure and regulatory uncertainty limit mainstream publisher integration.
Mobile wallets hold the largest share; momentum sits with credit card tokenization architectures.
Platform Type:
Development cost tiers separate premium console experiences from high-frequency mobile monetization loops. Application maturity determines customer acquisition economics across platforms.
- Mobile Apps:Touch-native interfaces and always-on connectivity enable impulse purchase capture during commute and leisure micro-moments. Southeast Asian studios optimize whale-to-minnow conversion ratios through engagement-loop analytics without upfront paywalls. Apple's 30% App Store tax constrains publisher profitability.
- Gaming Consoles:Closed hardware ecosystems sustain higher average transaction values per session through immersive experience design. Sony and Microsoft platform fees extract comparable revenue shares to mobile gatekeepers. Mature demographics in Japan and the United States generate recurring virtual goods spend.
- Web Browsers:HTML5-based experiences bypass native store taxation but sacrifice push notification re-engagement capabilities. Progressive web apps narrow the functionality gap with reduced distribution friction.
- Desktop Applications:Steam and Epic Games Store distribution channels anchor PC gaming monetization with integrated wallet systems. Valve's tight channel control sustains Steam Wallet adoption through exclusive title access.
Gaming consoles command premium pricing power; mobile apps are climbing the fastest on volume metrics.
Transaction Purpose:
Margin structure varies sharply between recurring subscription commitments and one-time unlockable content purchases. Customer lifetime value calculations diverge across purpose categories.
- In-Game Purchases:Cosmetic skins, battle passes, and progression accelerators generate the deepest margin pools through artificial scarcity mechanics. Electronic Arts deploys FIFA Ultimate Team card packs to anchor recurring spend in competitive sports titles. China's NPPA spending caps for minors force redesign of gacha-style monetization.
- Subscription Services:Predictable revenue streams reduce customer acquisition cost volatility but require continuous content refresh investments. Subscription fatigue in North American markets drives tiering strategies that reserve premium features for microtransaction channels.
- Virtual Goods:Persistent avatar customization and social signaling assets sustain secondary market interest. Blockchain interoperability standards enable cross-platform portability with royalty capture on resales.
- Unlockable Content:One-time expansion purchases deliver higher immediate revenue per transaction but lower repeat engagement frequency. Day-one DLC strategies face consumer backlash and regulatory scrutiny in European markets.
In-game purchases hold the largest share; momentum sits with subscription bundling convergence.
End User Segment:
Behavioral economics expertise separates whale-extraction models from mass-market conversion optimization. Psychographic segmentation determines engagement mechanic design priorities.
- Casual Gamers:Short session lengths and low skill barriers require friction-minimized purchase flows with immediate gratification rewards. Hyper-casual studios in India deploy rewarded video integration to monetize non-paying users.
- Hardcore Gamers:Competitive ranking systems and social status signaling drive willingness to pay for performance-adjacent advantages. Esports ecosystem integration amplifies virtual goods value perception.
- Content Creators:Twitch and YouTube tipping mechanics merge with platform-native purchase systems for audience engagement. Cross-platform virtual goods portability enables persistent identity investment.
- Enterprises:B2B software licensing microtransactions remain nascent relative to consumer gaming volumes. SaaS consumption-based billing models adopt gaming-industry authorization latency standards.
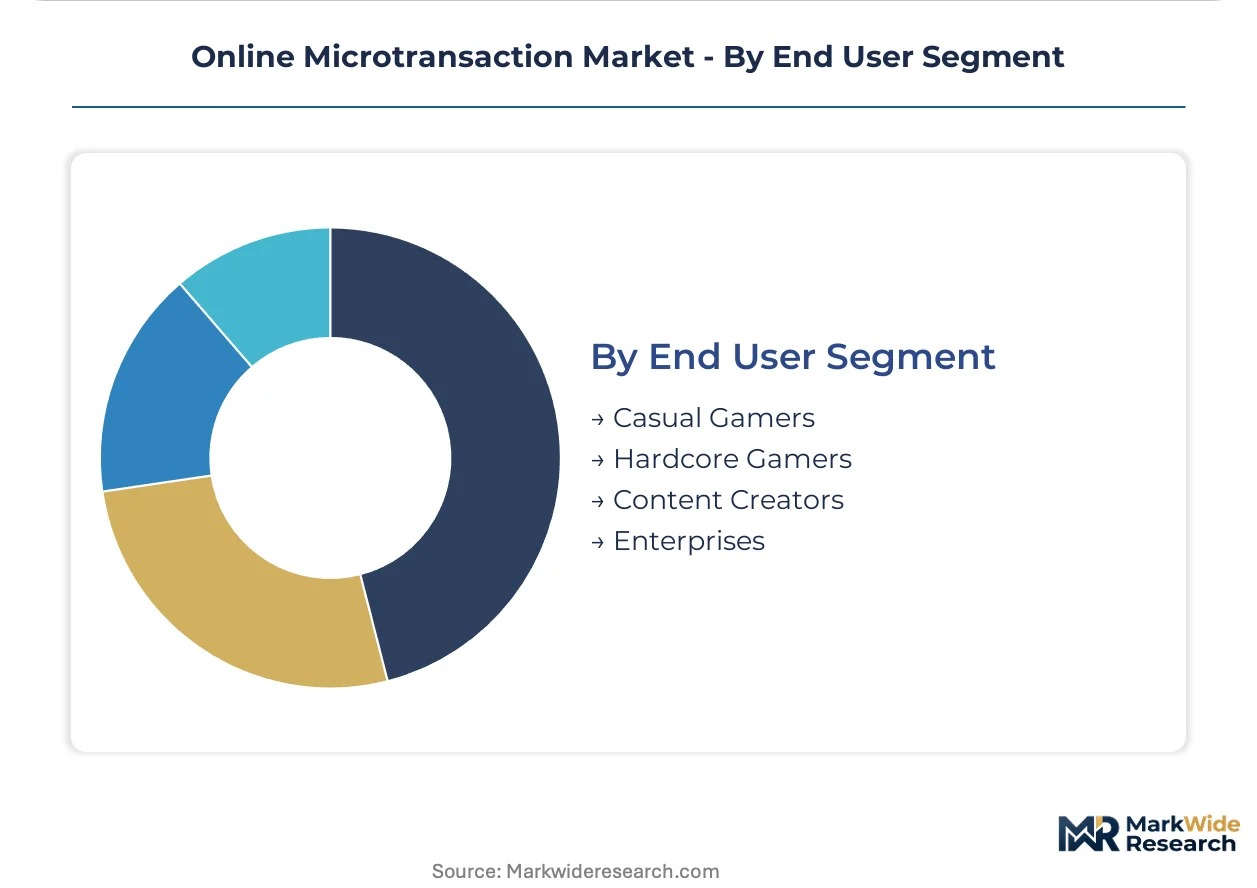
Casual gamers hold the largest share; content creators are expanding most quickly through platform economy convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Pacific fiber cable landing stations and India's UPI payment grid interconnects are underwriting divergent microtransaction infrastructure trajectories across major economies.
United States
Credit card tokenization architectures and console gaming ecosystems anchor transaction volume. The FTC scrutinizes loot-box mechanics under consumer protection statutes. Seattle and Los Angeles clusters host platform operators redesigning disclosure frameworks.
China
Super-app wallet integration and youth gamer population density sustain market scale. The National Press and Publication Administration enforces spending caps and real-name verification mandates. Shenzhen and Beijing studios are restructuring gacha monetization architectures.
India
UPI rail penetration and mobile-first gamer demographics compress purchase friction. The Reserve Bank of India governs payment aggregator licensing and data localization. Bangalore and Hyderabad development clusters optimize whale-to-minnow conversion analytics.
Japan
Gacha monetization heritage and aging console user bases sustain premium transaction values. The Consumer Affairs Agency regulates complete gacha mechanics under prize labeling laws. Tokyo and Osaka publisher headquarters refine live-service engagement loops.
South Korea
Esports ecosystem integration and PC bang culture drive competitive virtual goods demand. The Game Rating and Administration Committee mandates probability disclosures for randomized items. Seoul's Pangyo Techno Valley clusters host behavioral economics talent pools.
Online Microtransaction Market Vendor Landscape
Listed leaders compete with private specialists across platform control and payment rail integration. The market structures around three tiers: super-app operators with captive wallet ecosystems, dedicated gaming publishers with live-service expertise, and hardware platform holders extracting distribution taxes. Strategic archetypes include engagement-loop optimizers, channel gatekeepers, and cross-platform infrastructure providers. Dominant competitive moves center on vertical integration into payment processing and geographic expansion through localized content licensing.
Within the super-app operator tier, Tencent Holdings Ltd. and NetEase Inc. exemplify wallet-ecosystem monetization models. Among dedicated gaming publishers, Electronic Arts Inc. and Activision Blizzard occupy positions emphasizing recurring virtual goods mechanics. At the infrastructure-provider end, Valve Corporation and Sony Interactive Entertainment anchor platform-control strategies through proprietary distribution channels and integrated wallet systems.
| Leading Market Players |
|---|
| Activision Blizzard |
| Nexon Co., Ltd. |
| Tencent Holdings Ltd. |
| Valve Corporation |
| NetEase Inc. |
| Microsoft Corporation |
| Electronic Arts Inc. |
| Riot Games |
| Sony Interactive Entertainment |
| Others |
Supply Flow & Price Mechanics
China's NPPA spending caps and real-name verification mandates gate both publisher qualification and price differentiation simultaneously, forcing studios to redesign monetization architectures that separate compliant youth-accessible tiers from premium adult-targeted offerings.
Pricing Analysis
Volume-discount tiering structures anchor monetization across whale-to-minnow conversion funnels. Pricing stratifies across premium cosmetic tiers, standard progression accelerators, and economy-level rewarded video integrations. Cost compression in the economy tier is intensifying because Apple's 30% App Store tax constrains publisher margin structures. Casual mobile gamers exhibit highest price sensitivity, while hardcore competitive players demonstrate lowest sensitivity due to social status signaling value.
Supply Chain Analysis
Inventory lead times for live-service content pipelines compress to 72-hour windows under China's NPPA mandates. Cloud compute provisioning concentrates in the United States, Ireland, and Singapore. Raw material dependencies span server hardware, bandwidth capacity, and behavioral analytics talent pools. Single-source vulnerability sits with hyperscaler infrastructure concentration. Distribution runs through platform-native wallet systems and carrier billing rails.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Online Microtransaction Market represents high-growth disruption as UPI rail proliferation and biometric authorization collapse purchase friction below 300 milliseconds.
For Market Incumbents: Shield core revenue streams by accelerating backward integration into proprietary payment processing to bypass platform gatekeeper taxes. Fortify live-service talent pools through captive behavioral economics hiring in Seoul and Bangalore clusters. The regulatory fragmentation across Washington, Brussels, and Beijing threatens unified product architectures.
For New Entrants and Emerging Players: Lead with carrier billing penetration in underbanked African and Latin American markets where traditional banking infrastructure remains sparse. Target India's mobile-first gamer population through UPI-native purchase flows. Deploy HTML5 progressive web apps to circumvent native store taxation entirely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across blockchain-based asset ownership infrastructure as interoperability standards mature. Long-term viability favors publishers with cross-platform virtual goods portability capabilities. Acquisition targets should demonstrate live-service engagement-loop expertise. Watch China's NPPA enforcement intensity as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Wallet Development | Valve's Steam Wallet demonstrates channel control reduces platform tax exposure. |
| Biometric Authorization Integration | WeChat Pay's fingerprint verification collapses purchase abandonment rates. |
| Carrier Billing Expansion | Direct-to-bill rails bypass banking infrastructure in underbanked markets. |
| Live-Service Talent Acquisition | Behavioral economists command premium compensation in Seoul's Pangyo cluster. |
| Cross-Platform Asset Portability | Blockchain interoperability enables secondary market royalty capture. |
Methodological Framework
A standing panel of live-service product managers, payment rail engineers, regulatory compliance officers, and behavioral economists provided ongoing calibration throughout the study. Primary interviews with platform operators and secondary validation against SEC filings, App Annie mobile revenue data, and central bank payment system disclosures anchored the analysis. Bottom-up transaction volume modeling and top-down market sizing triangulated across the projection horizon.
Consistency checks validated outputs against external benchmarks including hyperscaler capex disclosures and carrier billing volume reports. The analytical framework segmented by payment method, platform type, transaction purpose, and end-user psychographic across the modeling period. CAGRs derived from longitudinal engagement-loop analytics and wallet penetration trajectories. Forecast inputs incorporated UPI transaction velocity and real-name verification compliance rates.
Forecasts assume regulatory continuity in China's NPPA regime, India's RBI data localization rules, and the European Commission's Digital Services Act; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market