
 Cryptocurrency Atms Market | 2026-2036
Cryptocurrency Atms Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency Atms Market Analysis
Tier-one compliance certification is collapsing the competitive set to operators with mature anti-money laundering programs and state-level licensing breadth. Bitcoin Depot leverages its retail partnership density across thousands of convenience locations to sustain network effects in high-traffic corridors. Genesis Coin Inc. anchors the hardware supply layer through its dominance of software-agnostic ATM platforms deployed by multiple operator brands. GENERAL BYTES s.r.o. competes on manufacturing flexibility, offering modular kiosks that operators customize for local regulatory environments.
Cryptocurrency ATMs are self-service terminals enabling cash-to-crypto and crypto-to-cash transactions through blockchain wallet integration, typically supporting Bitcoin and Ethereum with transaction limits set by know-your-customer thresholds. These machines serve commercial purposes by bridging fiat banking exclusion and digital asset access for retail customers and merchants without traditional exchange accounts. Two-way ATM configurations command premium positioning as they enable both purchase and sale functionality, whereas one-way units dominate unit volume in cost-constrained deployments. Software integration represents the fastest-evolving segment as operators differentiate through mobile wallet pairing and real-time blockchain settlement rather than hardware specifications alone.
FinCEN enforces Bank Secrecy Act compliance on cryptocurrency ATM operators, mandating suspicious activity reporting and customer identification programs that elevate operational costs for smaller deployers. State banking regulators in New York, Texas, and California impose additional money transmitter licensing requirements that fragment market access across jurisdictional boundaries. The EU's Markets in Crypto-Assets framework and forthcoming Travel Rule implementation will reshape compliance architecture for any operator seeking European expansion. Stakeholders must monitor how fragmented state-level enforcement in the United States converges with federal rulemaking to determine whether compliance scale becomes the decisive competitive barrier.
Market Dynamics
FinCEN's Bank Secrecy Act enforcement is compressing operator margins while simultaneously erecting compliance barriers that favor scaled deployers with mature anti-money laundering infrastructure over fragmented local networks.
Growth Catalysts
- FinCEN Compliance Architecture:Federal suspicious activity reporting mandates force consolidation toward operators with dedicated compliance teams, accelerating professionalization of the sector.
- Unbanked Population Access:Cash-to-crypto conversion points serve underbanked communities in urban corridors where traditional banking penetration remains below national averages.
- Two-Way Functionality:Machines enabling both purchase and sale transactions command premium placement in high-traffic retail environments, expanding revenue per unit.
Market Restraints
- State Licensing Fragmentation:Money transmitter requirements in New York, Texas, and California create jurisdictional friction that multiplies compliance costs for multi-state operators.
- Hardware Supply Concentration:Genesis Coin's dominance of software-agnostic ATM platforms creates dependency risk for operator brands lacking captive manufacturing.
- Cash Handling Logistics:Armored courier services and vault cash partnerships impose recurring operational expenses that scale with transaction volume.
Strategic Opportunities
- EU MiCA Framework:Markets in Crypto-Assets regulation creates a harmonized compliance pathway for operators seeking European market entry.
- Mobile Wallet Convergence:Real-time blockchain settlement paired with smartphone custody solutions enables seamless fiat-to-digital asset bridging.
- Convenience Store Channel Density:Gas station and retail partnerships in secondary metropolitan areas remain underpenetrated relative to primary urban corridors.
Industry Challenges
- Compliance Talent Scarcity:Anti-money laundering specialists with cryptocurrency transaction monitoring experience command premium compensation in competitive labor markets.
- Blockchain Settlement Latency:Network congestion during peak demand periods degrades user experience and increases customer service burden.
- Legacy Banking Relationships:De-risking by correspondent banks limits access to fiat liquidity for operators without established institutional partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency Atms Market |
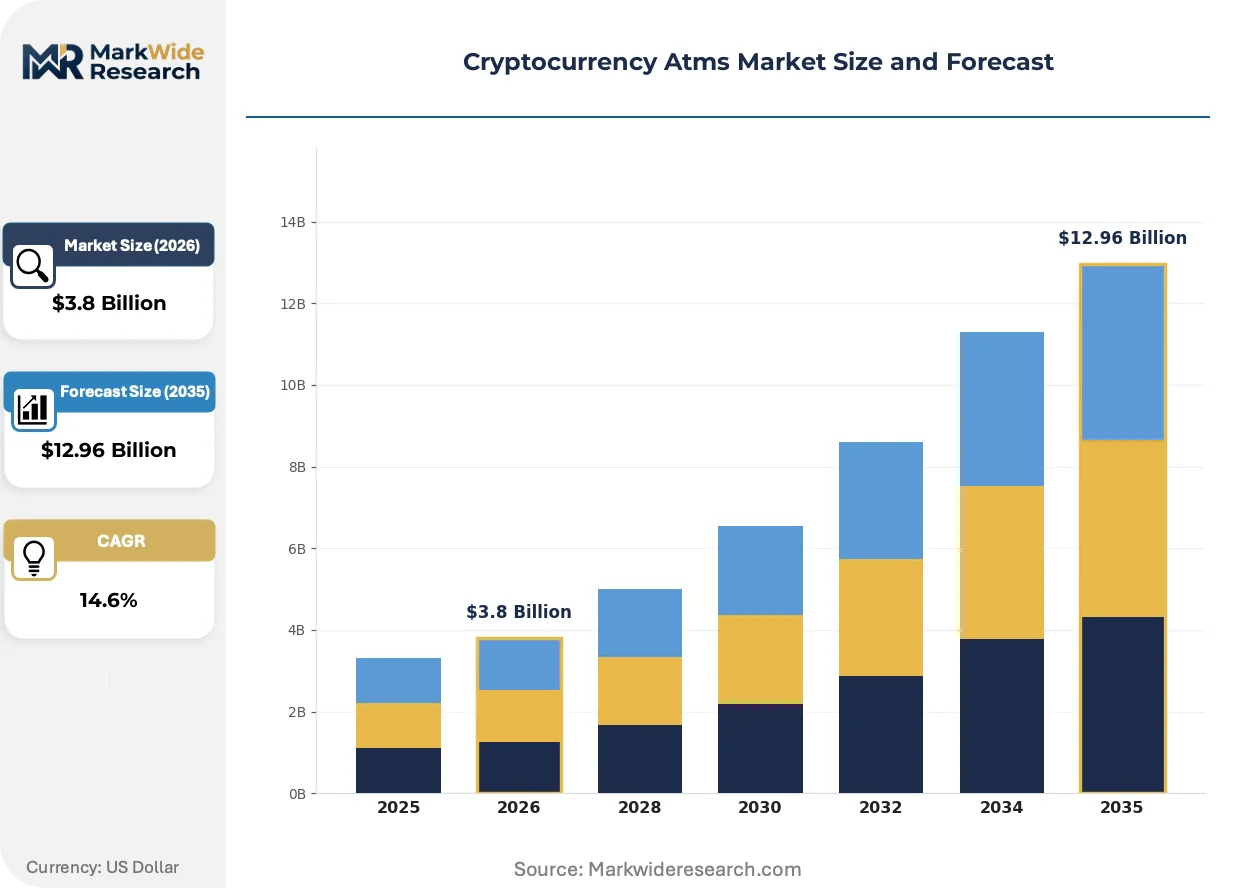
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Two-Way ATMs, One-Way ATMs, Kiosks, Mobile ATMs Transaction Volume: High, Medium, Low, Peer-to-Peer Integration Level: Software Integration, Hardware Integration, External Wallets, Blockchain Integration End User: Retail Customers, Investors, Merchants, Financial Institutions |
| Companies Covered | Bitcoin Depot, Genesis Coin Inc., GENERAL BYTES s.r.o., Bitstop, RockItCoin, Byte Federal, Inc., CoinFlip, Coinsource, Lamassu Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency Atms Market Emerging Trajectories
Software differentiation is displacing hardware specifications as the primary competitive vector, with operators investing in mobile integration and real-time settlement capabilities rather than kiosk industrial design.
Biometric identity verification is displacing document-based KYC workflows at high-volume machines, reducing transaction friction for repeat users. Retail operators in the United States are deploying palm-vein and facial recognition systems to accelerate customer throughput during peak hours. This shift is compressing average transaction times while elevating compliance confidence for regulators scrutinizing customer identification programs.
The EU's forthcoming Travel Rule implementation is mandating enhanced beneficiary data collection for cross-border transfers, forcing operators to rearchitect transaction pipelines. Hardware manufacturers serving European markets must embed additional data fields into settlement protocols. MiCA-aligned operators are responding by pre-positioning compliance infrastructure ahead of enforcement deadlines.
Merchant-acquired transaction flows are shifting toward revenue-sharing models that align operator incentives with retail host performance. Convenience store chains now negotiate percentage-based arrangements rather than flat monthly rental fees. This restructuring is most visible in Texas and Florida corridors where Bitcoin Depot and CoinFlip compete aggressively for exclusive placement rights.
Cryptocurrency Atms Market Segmentation
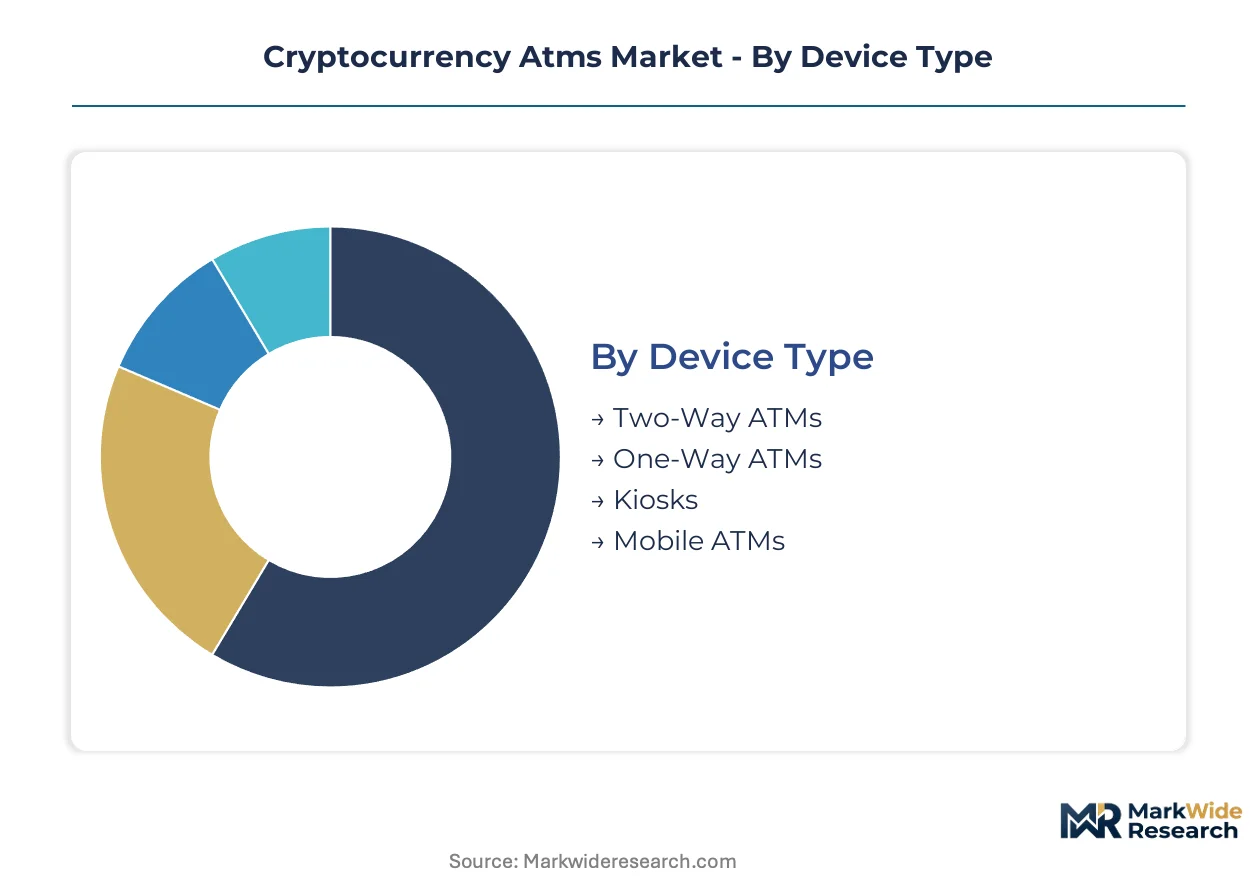
Segmentation in cryptocurrency ATMs reveals how regulatory thresholds, transaction economics, and custody architectures reshape deployment priorities across operator networks. Each dimension carries distinct compliance burdens and capital intensity that determine viable market entry points.
Device Type:
FinCEN's suspicious activity reporting thresholds and state money transmitter mandates create divergent compliance costs across physical form factors, with two-way configurations triggering enhanced oversight.
- Two-Way ATMs:Machines enabling both fiat-to-crypto purchases and crypto-to-cash redemptions embed dual cash handling infrastructure. Demand concentrates in high-traffic retail corridors across Texas and Florida where Bitcoin Depot and CoinFlip negotiate exclusive placement. Regulatory complexity elevates operational costs but sustains premium positioning through complete transaction cycles.
- One-Way ATMs:Purchase-only terminals dominate unit volume through lower capital requirements and simplified cash logistics. Deployment clusters in secondary metropolitan areas where armored courier density remains thin. Operators favor these units for rapid network expansion without vault cash partnerships.
- Kiosks:Compact footprint terminals integrate with existing point-of-sale infrastructure in convenience store chains.
- Mobile ATMs:Portable units serve temporary event deployments and seasonal demand spikes in festival corridors.
Established volume favors one-way configurations; emerging adoption favors two-way functionality.
Transaction Volume:
Know-your-customer tiering structures segment operators by compliance automation maturity, with high-volume thresholds demanding real-time identity verification infrastructure.
- High:Transactions exceeding federal reporting limits require biometric identity verification and enhanced due diligence protocols. Demand concentrates in urban corridors with unbanked populations seeking large-denomination conversion. Palm-vein and facial recognition systems reduce friction for repeat users.
- Medium:Mid-tier thresholds balance transaction velocity with document-based KYC workflows. Deployment favors suburban retail clusters where customer acquisition costs moderate. Operators optimize here for throughput without premium biometric hardware.
- Low:Minimal-threshold transactions serve casual users through simplified registration.
- Peer-to-Peer:Direct wallet transfers bypass traditional ATM infrastructure entirely.
Revenue concentration sits with high-volume tiers; network expansion economics favor medium thresholds.
Integration Level:
Software architecture differentiation determines operator competitive positioning as hardware commoditization accelerates across Genesis Coin and GENERAL BYTES supply bases.
- Software Integration:Proprietary transaction platforms enable mobile wallet pairing and real-time settlement differentiation. Demand concentrates among crypto-native consumers seeking seamless fiat bridging without exchange accounts. Operators invest here to escape hardware supplier dependency.
- Hardware Integration:Captive manufacturing or exclusive supplier relationships control unit economics and customization flexibility. Deployment favors operators with capital depth for vertical integration into kiosk production.
- External Wallets:Third-party custody integration reduces operator security burden.
- Blockchain Integration:Direct settlement protocols minimize counterparty exposure.
Mature deployments emphasize software integration; capital-constrained entrants prioritize external wallet partnerships.
End User:
Customer archetypes segment by banking exclusion severity, investment sophistication, and merchant acceptance requirements, each demanding distinct interface design and compliance workflows.
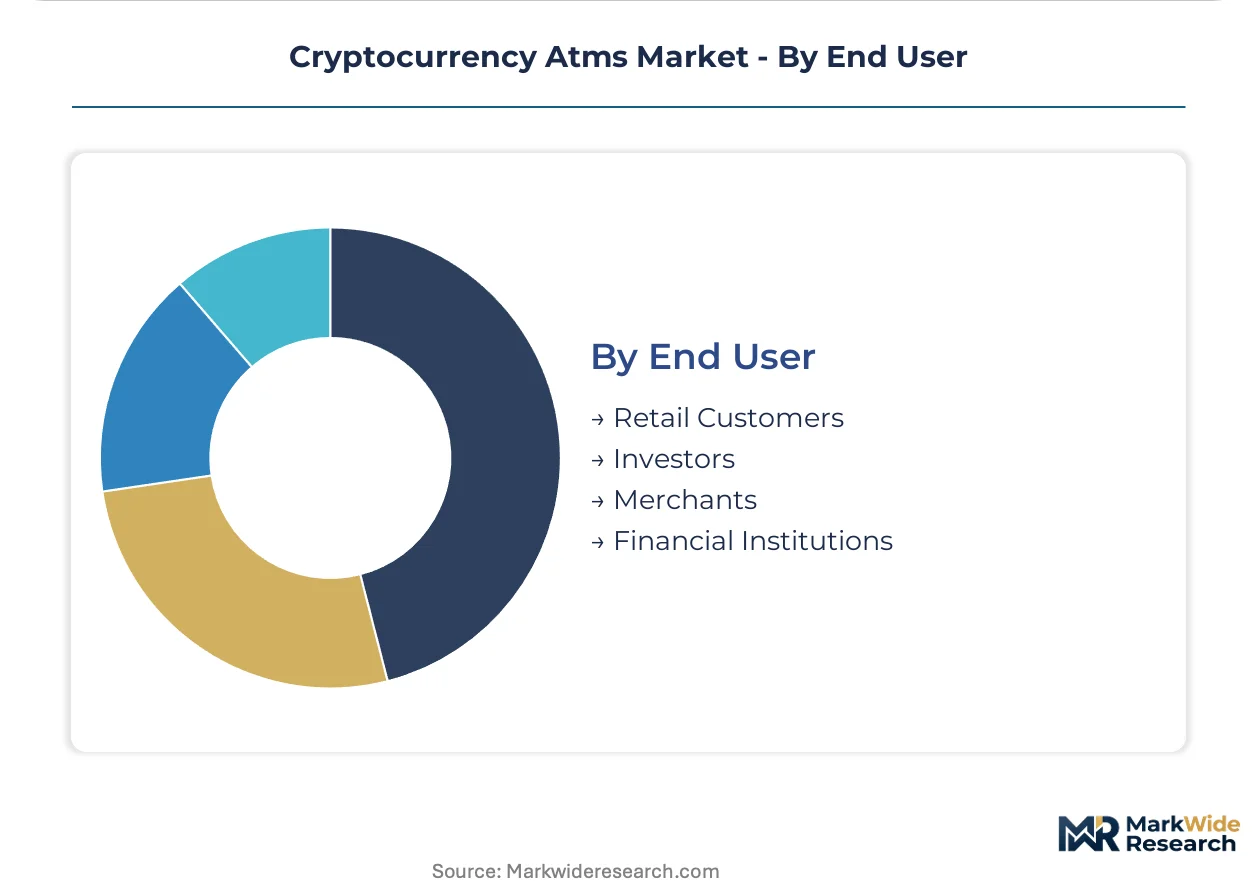
- Retail Customers:Unbanked and underbanked individuals seeking cash-to-crypto conversion without traditional exchange accounts. Demand concentrates in urban corridors where banking penetration lags national averages. This segment is expanding most quickly as financial exclusion persists.
- Investors:Sophisticated users executing large transactions with portfolio diversification intent. Deployment favors high-security two-way machines in affluent metropolitan clusters. Operators customize for privacy preferences and settlement speed.
- Merchants:Businesses accepting crypto payments requiring liquidation infrastructure.
- Financial Institutions:Banks and credit unions exploring digital asset custody partnerships.
Transaction frequency favors retail customers; margin per transaction favors investors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing clusters concentrate in the Czech Republic and Switzerland, while operator networks expand fastest across the United States, Canada, and select European corridors. Jurisdictional licensing regimes fragment deployment economics, rewarding operators with multi-state or multi-country compliance infrastructure.
United States
Retail partnership density with convenience store chains and gas station operators sustains network effects across high-traffic corridors. FinCEN's Bank Secrecy Act enforcement and state-level money transmitter requirements in Texas, New York, and California elevate compliance costs. Deployment concentrates in Texas and Florida corridors where Bitcoin Depot and CoinFlip negotiate exclusive placement rights.
Canada
Regulatory clarity from FINTRAC's anti-money laundering framework attracts operators seeking stable compliance architecture. Provincial oversight varies, with British Columbia and Ontario imposing distinct registration requirements on virtual currency dealers. Vancouver and Toronto anchor deployment clusters serving cross-border demand from Pacific Northwest and Great Lakes corridors.
Germany
BaFin's cryptocurrency custody licensing creates a structured entry pathway for ATM operators seeking European market access. The EU's Markets in Crypto-Assets framework harmonizes compliance standards across member states. Berlin and Frankfurt host operator headquarters coordinating Central European network expansion.
Switzerland
FINMA's blockchain-friendly regulatory posture attracts operators seeking jurisdictional credibility for international expansion. The Travel Rule implementation mandates enhanced beneficiary data collection for cross-border transfers. Zug's Crypto Valley anchors software development and compliance infrastructure serving European operator networks.
United Kingdom
FCA registration requirements for cryptoasset firms filter market entry toward compliant operators with mature anti-money laundering programs. Post-Brexit regulatory divergence from EU frameworks creates distinct compliance obligations. London concentrates fintech partnerships linking ATM networks to digital banking infrastructure.
Cryptocurrency Atms Market Vendor Landscape
Concentration sits with operators possessing multi-jurisdictional licensing breadth and retail channel density. The competitive set compresses toward scaled deployers with dedicated compliance teams, while hardware supply remains concentrated among specialized manufacturers. Three archetypes dominate: retail-network operators, hardware-agnostic platform providers, and vertically integrated kiosk manufacturers. Consolidation accelerates through state licensing acquisitions and exclusive retail partnerships.
Among retail-network operators, Bitcoin Depot and CoinFlip exemplify the scale-driven archetype, occupying positions sustained by convenience store partnership density across thousands of locations. Genesis Coin Inc. anchors the hardware-agnostic platform tier, supplying software infrastructure deployed under multiple operator brands. GENERAL BYTES s.r.o. represents European manufacturing specialization, offering modular kiosks customizable for local regulatory environments.
| Leading Market Players |
|---|
| Bitcoin Depot |
| Genesis Coin Inc. |
| GENERAL BYTES s.r.o. |
| Bitstop |
| RockItCoin |
| Byte Federal, Inc. |
| CoinFlip |
| Coinsource |
| Lamassu Industries AG |
| Others |
Supply Flow & Price Mechanics
Genesis Coin's manufacturing scale in the Czech Republic and GENERAL BYTES's modular production capacity create asymmetric cost structures that compress price floors for hardware-agnostic operators while elevating premiums for vertically integrated deployers with captive compliance infrastructure.
Pricing Analysis
FinCEN's Bank Secrecy Act dictates the pricing tier structure across the cryptocurrency ATM landscape, segmenting operators by compliance automation maturity. Three-tier pricing structure across premium, standard, and economy levels reflects state licensing breadth, with Bitcoin Depot and CoinFlip commanding placement premiums through multi-jurisdictional coverage while smaller deployers compete on transaction fee compression. Price differentiation hinges on biometric KYC integration and real-time settlement speed. Cost compression in the hardware tier is intensifying because Genesis Coin's platform dominance limits supplier bargaining power. Retail customers exhibit highest price sensitivity, while institutional merchants prioritize compliance certification over per-transaction economics.
Supply Chain Analysis
Inventory lead times for cash handling modules and biometric sensors extend deployment cycles, constraining rapid network expansion for operators lacking advance procurement commitments. Hardware manufacturing concentrates in the Czech Republic, Switzerland, and select East Asian electronics clusters. Component sourcing draws from semiconductor foundries in Taiwan, precision optics suppliers in Germany, and vault cash logistics providers in North America. Single-source vulnerability sits with Genesis Coin's software-agnostic platform dominance, which feeds from proprietary firmware architectures that resist rapid supplier switching. Distribution runs through direct operator procurement for scaled deployers and distributor networks for emerging entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryptocurrency ATM market represents high-growth financial infrastructure disruption, with the EU's MiCA framework and Travel Rule implementation creating regulatory clarity that will accelerate cross-border operator consolidation and compliance investment cycles.
For Market Incumbents: Secure exclusive retail channel density in secondary metropolitan corridors before state licensing barriers harden, and acquire compliant operators in Texas and California to preempt jurisdictional fragmentation. The threat of biometric-enabled KYC commoditization demands investment in proprietary settlement speed rather than hardware differentiation.
For New Entrants and Emerging Players: Anchor in convenience store partnerships across Florida and Georgia corridors where Bitcoin Depot and CoinFlip placement saturation remains incomplete. The most penetrable segment sits with one-way ATM deployments in cash-heavy urban communities lacking banking infrastructure. A white-label software integration play with existing kiosk hardware avoids capital-intensive manufacturing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with multi-state money transmitter licenses and established armored courier relationships. Long-term viability across a 5-10 year window favors deployers with compliance automation infrastructure rather than transaction volume scale alone. The acquisition target archetype combines software-agnostic platform flexibility with biometric KYC deployment. The signal to watch is FinCEN enforcement intensity against unlicensed operators as a precursor to consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Licensing Acquisition | Preemptive compliance coverage in Texas and California accelerates network expansion without regulatory friction. |
| Biometric KYC Integration | Palm-vein and facial recognition deployment reduces transaction friction for repeat retail customers. |
| Mobile Wallet Convergence | Real-time blockchain settlement paired with smartphone custody eliminates exchange account dependency. |
| Revenue-Sharing Retail Partnerships | Percentage-based arrangements with convenience store chains align operator incentives with host performance. |
| EU MiCA Compliance Pre-Positioning | Harmonized regulatory architecture in Germany and Switzerland enables scalable European market entry. |
Methodological Framework
Initial hypotheses were tested against primary input from ATM operators, compliance officers at money services businesses, convenience store chain procurement directors, and armored courier logistics managers, and refined through secondary validation against FinCEN enforcement actions, state banking regulator licensing databases, EU MiCA regulatory filings, and SEC disclosures from publicly traded crypto infrastructure firms. Bottom-up unit deployment counts triangulated with top-down transaction volume estimates derived from blockchain analytics.
Variance decomposition across the modeling period isolates regulatory enforcement intensity, hardware cost curves, and retail channel saturation as primary forecast drivers. Segmentation dimensions include device type, transaction volume tier, integration level, and end-user archetype, with geographic regulatory clusters modeled separately. CAGRs were derived from installed base expansion rates and revenue-per-machine trajectories, incorporating cash handling logistics costs and compliance automation investment cycles as industry-specific inputs.
Material uncertainties — abrupt FinCEN enforcement escalation, correspondent banking de-risking waves, and blockchain network congestion episodes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and hardware supply stability. Revision becomes warranted when state-level licensing rejection rates for new operators cross thresholds that materially constrain market entry velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market