
 Cryptocurrency Exchange Platform Market | 2026-2036
Cryptocurrency Exchange Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency Exchange Platform Market Intelligence
MiCA licensing is decoupling European market access from legacy passporting arrangements. Binance leverages its compliance infrastructure to sustain operations across multiple jurisdictions. Coinbase Exchange anchors its position through regulatory-first expansion into selective markets. Kraken differentiates via specialized institutional onboarding workflows that reduce counterparty friction.
A cryptocurrency exchange platform constitutes a digital marketplace architecture enabling order matching, custody, and settlement for virtual asset transactions, typically processing throughput exceeding one hundred thousand trades per second during peak load. The system serves commercial and industrial purposes by converting fiat liquidity into tokenized instruments and providing price discovery infrastructure for portfolio rebalancing. Spot trading occupies the largest transaction volume share while derivatives trading captures the fastest growth trajectory among service type segments. Institutional investors command the deepest margin pools within customer type segments due to bespoke custody and execution requirements.
The SEC enforces registration mandates for platforms serving United States participants while Singapore's Monetary Authority administers payment licensing frameworks that determine operational legality. The EU's MiCA regime establishes uniform reserve and disclosure standards across member states, compressing timelines for market entry approvals. Stakeholders must monitor how jurisdictional arbitrage between frameworks affects platform licensing costs and user migration patterns.
Market Dynamics
MiCA licensing requirements in Europe are compressing market entry timelines while simultaneously elevating compliance infrastructure costs, forcing platforms to consolidate multi-jurisdictional operations or exit selective markets entirely.
Growth Catalysts
- Institutional custody demand:Pension funds and asset managers require segregated cold storage and insurance-backed wallets, driving platform investment in qualified custodian frameworks.
- Payment licensing in Singapore:The Monetary Authority of Singapore's clear digital payment token licensing pathway attracts capital deployment from firms seeking regulatory certainty.
- Derivatives infrastructure:Perpetual futures and options protocols expand revenue per user beyond spot trading margins, capturing sophisticated trader segments.
Market Restraints
- Reserve requirement compression:MiCA mandates stablecoin issuers maintain 30% reserves in bank deposits and low-risk assets, constraining yield generation and capital efficiency.
- Banking access concentration:Fiat on-ramp relationships cluster with a limited number of payment processors in the United States and Switzerland, creating single-point-of-failure risk.
- Cross-chain settlement latency:Finality guarantees across Layer-1 and Layer-2 networks remain inconsistent, limiting high-frequency trading strategies.
Strategic Opportunities
- United Arab Emirates regulatory arbitrage:Dubai's Virtual Assets Regulatory Authority offers accelerated licensing timelines compared to European or American frameworks, attracting platform relocations.
- Tokenized securities integration:Convergence of traditional equity settlement rails with blockchain infrastructure enables 24/7 trading of real-world assets.
- Embedded finance distribution:Neobanks and fintech applications integrate white-label exchange APIs, expanding user acquisition beyond direct-to-consumer marketing.
Industry Challenges
- Smart contract auditing capacity:Qualified blockchain security firms face 6-12 month backlogs, delaying product launches and protocol upgrades.
- Travel Rule implementation:FATF compliance requires real-time counterparty identification across jurisdictions with incompatible technical standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency Exchange Platform Market |
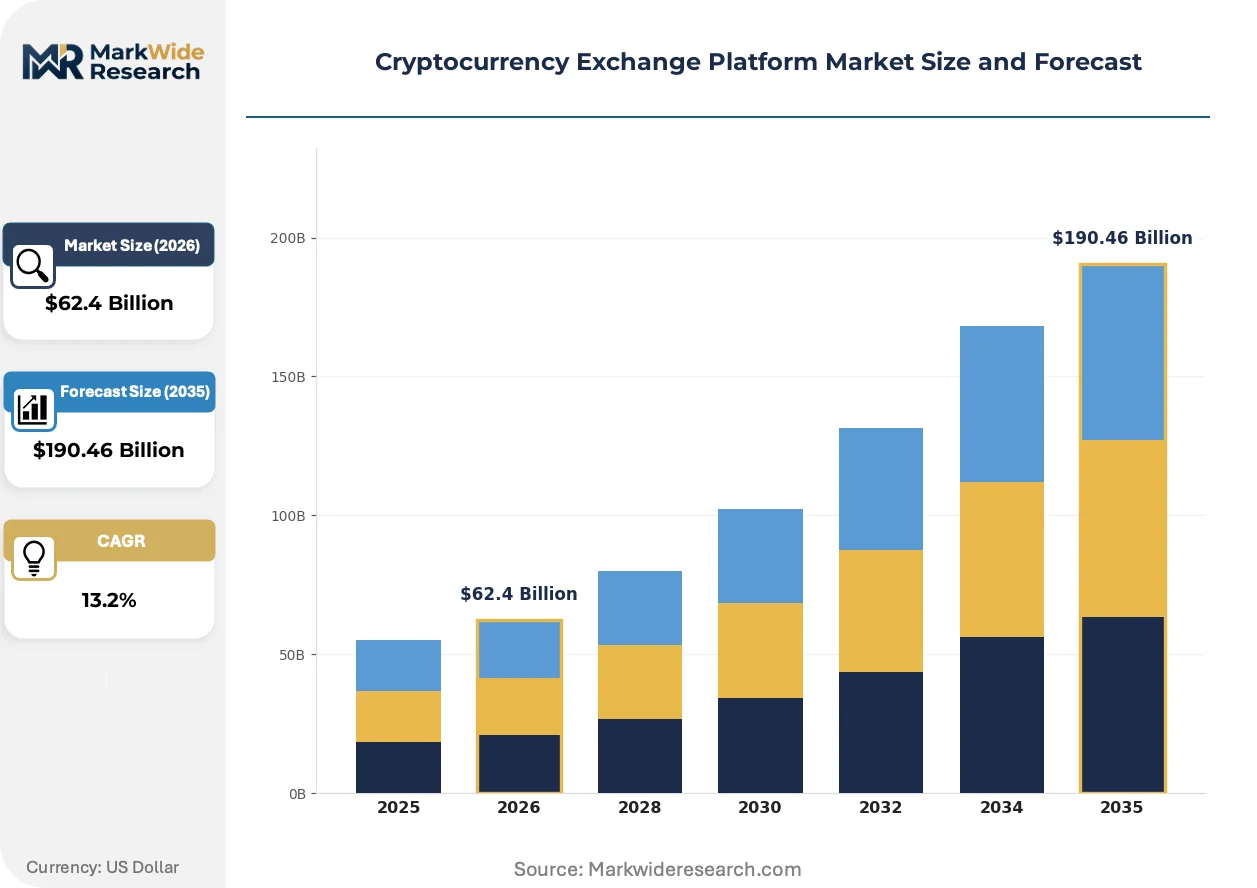
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $190.46 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spot Trading, Margin Trading, Derivatives Trading, OTC Services Customer Type: Retail Traders, Institutional Investors, High-Net-Worth Individuals, Corporate Accounts Security Features: Two-Factor Authentication, Cold Wallet Storage, Insurance Coverage, DDoS Protection Payment Method: Fiat Currency, Credit Cards, Bank Transfers, Digital Wallets |
| Companies Covered | Binance, Coinbase Exchange, OKX, Upbit, HTX, Kraken, Bitfinex, Huobi, Gate.io, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency Exchange Platform Market Strategic Shifts & Innovations
Execution infrastructure is fragmenting across centralized order books, automated market makers, and hybrid architectures as latency requirements and custody preferences diverge across user segments.
Layer-2 rollups utilizing zero-knowledge proofs are overtaking optimistic rollup architectures for exchange settlement layers. Institutional platforms prioritize zk-SNARK-based validity proofs for sub-second finality and reduced data availability costs. This compression of settlement latency is overtaking traditional batch-based clearing models in derivatives markets.
REACH chemical substance registration requirements indirectly shape hardware wallet manufacturing supply chains in Europe. Component suppliers must disclose material compositions for custody device enclosures and secure element packaging. Hardware manufacturers in Germany and France are responding by qualifying alternative substrate materials ahead of 2025 disclosure deadlines.
Aggregated liquidity sourcing is displacing single-venue execution for large-block cryptocurrency transactions. Family offices and hedge funds now route orders through smart order routers accessing multiple exchanges and dark pools simultaneously. This behavior is most visible in Singapore and the United States where regulatory clarity supports multi-custodian arrangements.
Cryptocurrency Exchange Platform Market Segmentation
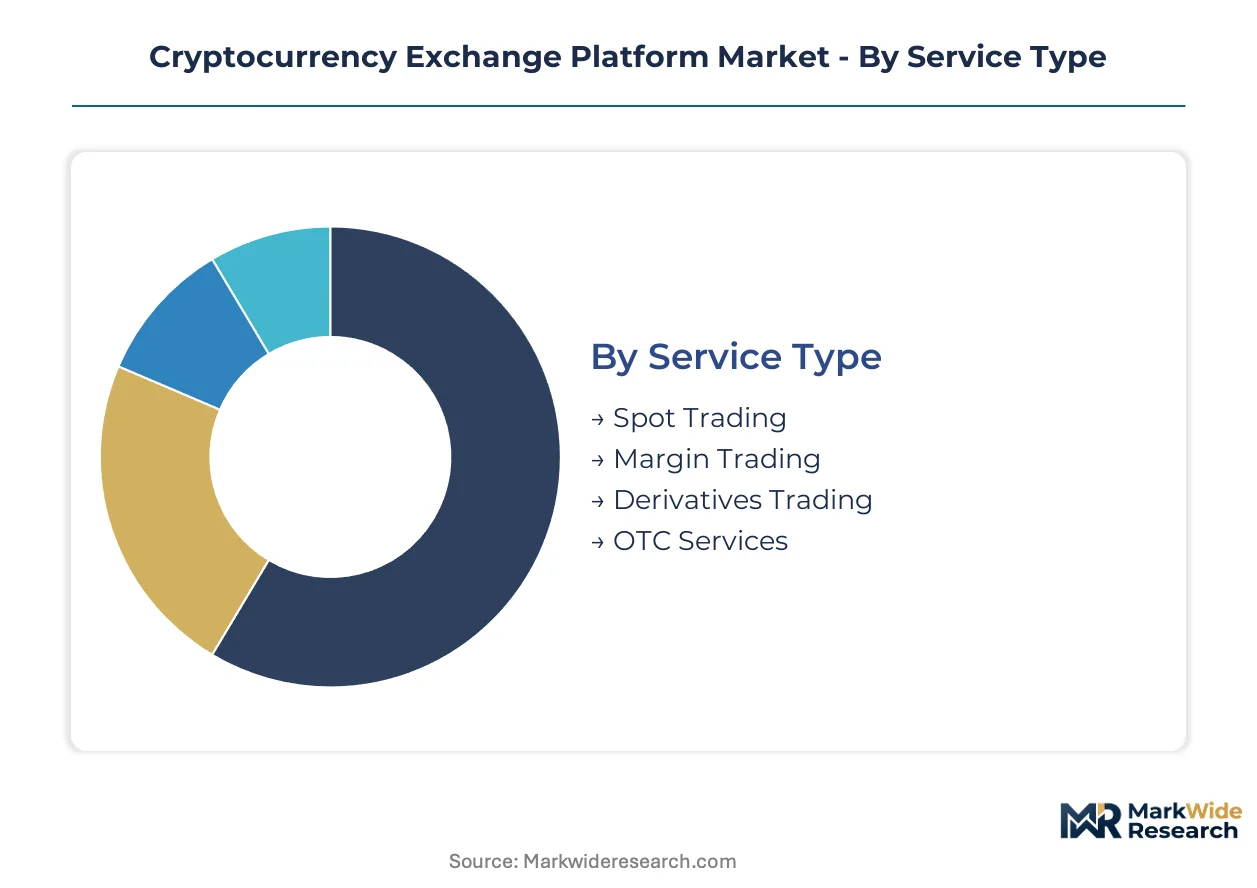
Exchange platforms segment their infrastructure to capture divergent margin profiles across execution speeds, custody requirements, and counterparty risk tolerances. Service architecture must reconcile retail accessibility with institutional compliance without fragmenting liquidity pools.
Service Type:
Platform operators redesign matching engines and settlement rails as traders migrate between execution modes, compressing upgrade cycles from annual to quarterly releases.
- Spot Trading:Immediate delivery of underlying assets against fiat or stablecoin settlement. Retail concentration in the United States and Singapore drives throughput optimization for sub-100 millisecond execution.
- Derivatives Trading:Perpetual swaps and dated futures with leveraged notional exposure. Institutional desks in Dubai and Chicago generate the deepest order book liquidity through 24-hour rolling settlement.
- Margin Trading:Collateralized borrowing against posted cryptocurrency positions. Demand clusters among sophisticated retail cohorts seeking amplified beta exposure.
- OTC Services:Bilateral negotiation for large-block transactions outside public order books. Family offices in Switzerland and the United Arab Emirates prefer direct relationship pricing for seven-figure trades.
Volume placements concentrate in Spot Trading; the faster expansion belongs to Derivatives Trading.
Customer Type:
Revenue per user varies by an order of magnitude across customer tiers, forcing platforms to maintain parallel onboarding workflows with divergent KYC intensity.
- Institutional Investors:Pension funds, hedge funds, and asset managers requiring segregated custody and regulatory reporting. MiCA compliance in Europe and SEC registration in the United States mandate dedicated relationship management.
- Retail Traders:Individual participants executing through mobile-optimized interfaces. Volume surges correlate with volatility events in Bitcoin and Ethereum spot markets.
- High-Net-Worth Individuals:Private wealth deploying through specialized desks with personalized custody arrangements. Singapore's payment licensing framework attracts this cohort seeking jurisdictional certainty.
- Corporate Accounts:Treasury departments managing cryptocurrency holdings as balance sheet assets. Treasury deployment concentrates among technology firms with dollar-denominated liabilities.
Institutional Investors command the steepest margin expansion; Retail Traders deliver the highest transaction velocity.
Security Features:
Insurance-backed custody and authentication protocols differentiate platform positioning as breach incidents reshape user trust hierarchies.
- Cold Wallet Storage:Air-gapped private key management with multi-signature authorization. Institutional mandates in Germany and the United States require qualified custodian certification.
- Insurance Coverage:Underwritten policies against theft, hacking, and operational failure. Lloyd's of London syndicates and Bermuda carriers dominate underwriting capacity for large platforms.
- Two-Factor Authentication:TOTP and hardware key verification for account access. Regulatory guidance from Singapore's Monetary Authority treats this as baseline compliance.
- DDoS Protection:Traffic scrubbing and geographic distribution against volumetric attacks. Exchange infrastructure providers maintain scrubbing centers across Frankfurt, Singapore, and Virginia.
Deployment concentrates in Cold Wallet Storage; Insurance Coverage is climbing fastest as institutional participation deepens.
Payment Method:
Fiat on-ramp architecture determines geographic accessibility and regulatory exposure for platform operators.
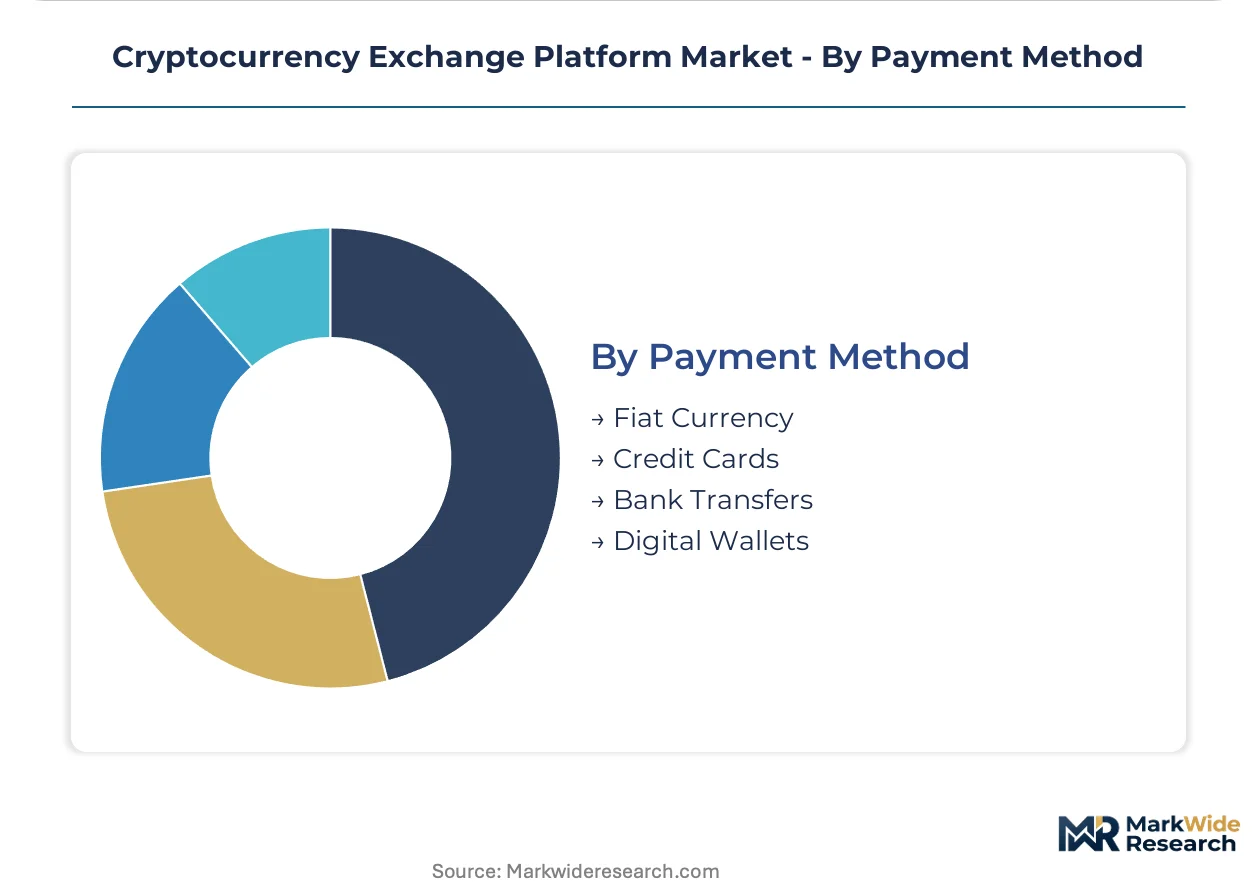
- Bank Transfers:ACH, SEPA, and SWIFT rails for high-value deposits. United States correspondent banking relationships cluster with select payment processors in New York and California.
- Digital Wallets:Integration with PayPal, Apple Pay, and regional alternatives. Southeast Asian markets demonstrate highest adoption velocity for mobile-first funding.
- Fiat Currency:Direct currency pairs against USD, EUR, GBP, and JPY. Reserve requirements under MiCA constrain stablecoin issuance economics.
- Credit Cards:Card network settlement with chargeback risk absorption. Issuer restrictions in the United Kingdom and Australia limit availability for cryptocurrency purchases.
Transaction value concentrates in Bank Transfers; Digital Wallets are expanding most quickly in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Virtual Assets Regulatory Authority has compressed licensing timelines to 90 days, drawing platform relocations from slower jurisdictions. Singapore's payment licensing framework and Switzerland's FINMA guidelines create parallel regulatory gravity wells. MiCA implementation across European Union member states forces reserve restructuring for stablecoin issuers.
United States
Institutional custody demand from pension funds and asset managers drives platform investment in qualified custodian frameworks. SEC registration mandates enforce segregation of customer assets and real-time reporting for exchanges serving domestic participants. New York and California host the densest concentration of fiat on-ramp banking relationships, with correspondent ties clustering among select payment processors.
Singapore
The Monetary Authority of Singapore's digital payment token licensing pathway attracts capital deployment from firms seeking regulatory certainty. Clear frameworks for stablecoin issuance and custody services reduce compliance ambiguity for platform operators. The city-state's financial district anchors regional headquarters for exchanges targeting Southeast Asian market expansion.
United Arab Emirates
Dubai's VARA licensing offers accelerated approval timelines compared to European or American frameworks, attracting platform relocations and regional headquarters establishment. The regulatory regime permits derivatives trading and staking services under unified supervision. Abu Dhabi's financial free zones complement Dubai with institutional-focused custody licensing for family offices and sovereign wealth vehicles.
Switzerland
FINMA guidelines for blockchain service providers create a banking-integrated licensing pathway with crypto-specific carve-outs. The country's private banking heritage supports institutional onboarding workflows for high-net-worth individuals and corporate treasuries. Zurich and Zug host the highest density of custody infrastructure providers and blockchain security auditing firms.
Germany
BaFin's crypto custody licensing requirements mandate qualified custodian certification for institutional-facing platforms. The 30% reserve requirements under EU MiCA constrain stablecoin issuance economics for Germany-based issuers. Frankfurt's financial infrastructure providers and Berlin's technology clusters split operational gravity between traditional finance integration and protocol development.
Cryptocurrency Exchange Platform Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across custody, execution, and compliance infrastructure layers. Market structure exhibits tiered consolidation where vertically integrated platforms with multi-jurisdictional licensing command premium positioning against regional specialists. Three archetypes dominate: global full-service exchanges with proprietary custody, derivatives-focused platforms with institutional workflow specialization, and white-label infrastructure providers enabling embedded finance distribution. Competitive moves concentrate on regulatory-first geographic expansion and strategic partnerships with traditional financial institutions for fiat on-ramp access.
Among globally diversified exchange operators, Binance and Coinbase Exchange exemplify contrasting archetypes of multi-jurisdictional scale versus regulatory-first selective market entry. Kraken occupies a specialist position within the institutional-tier segment, differentiated by onboarding workflow design for counterparty friction reduction. These three entities anchor the competitive landscape through divergent responses to MiCA compliance costs, SEC registration requirements, and Singapore payment licensing frameworks.
| Leading Market Players |
|---|
| Binance |
| Coinbase Exchange |
| OKX |
| Upbit |
| HTX |
| Kraken |
| Bitfinex |
| Huobi |
| Gate.io |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up custody infrastructure specialists anchor supply-side consolidation, compressing vendor margins while extracting pricing premiums through qualified custodian certification and insurance-backed wallet guarantees. This ownership pattern concentrates cold storage hardware procurement and banking relationship negotiations, forcing platforms to absorb cost pass-throughs or sacrifice compliance tier positioning.
Pricing Analysis
Short lead-time deployment commands premium pricing as exchanges race MiCA licensing deadlines in Europe and VARA approvals in Dubai. The dominant structure stratifies across premium, standard, and economy tiers tied to custody certification grade and insurance coverage depth. Price differentiation centers on qualified custodian status and segregated cold storage architecture. Pricing pressure stems from reserve requirement compression under MiCA, which constrains yield generation and squeezes platform economics. Retail traders exhibit highest price sensitivity, while institutional investors absorb premium tiers for bespoke onboarding workflows and regulatory reporting automation.
Supply Chain Analysis
Freight costs for hardware wallet components and secure element shipments from Germany and Taiwan amplify working capital requirements for custody device manufacturers. Supply concentrates in Germany for qualified custodian certification infrastructure, Switzerland for private banking-integrated onboarding systems, and Singapore for payment licensing-aligned fiat on-ramp technology. Component dependencies include HSM modules, air-gapped storage enclosures, and biometric authentication sensors. Single-source vulnerability in secure element fabrication creates chokepoint exposure. Distribution runs through direct platform procurement for institutional-grade infrastructure and white-label API licensing for embedded finance distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated platforms with multi-jurisdictional licensing, as MiCA compliance costs and SEC registration mandates force sub-scale operators toward exit or acquisition.
For Market Incumbents: To counter regulatory arbitrage from Dubai VARA and Singapore MAS licensing pathways, anchor market position through accelerated multi-jurisdictional compliance infrastructure and captive custody technology development. Prioritize backward integration into cold storage hardware manufacturing to reduce vendor concentration in German and Taiwanese component suppliers. Deepen banking relationship diversification beyond New York and California correspondent networks to mitigate single-point-of-failure in fiat on-ramp access. For New Entrants and Emerging Players: White-label API distribution through neobanks and fintech applications offers the most penetrable entry vector, bypassing direct customer acquisition costs against entrenched exchanges. Target embedded finance integration in Southeast Asian markets where mobile-first digital wallet adoption outpaces traditional banking penetration. Pursue regulatory sandbox participation in Abu Dhabi Global Market to validate institutional custody workflows before scaling. For Investors and Strategic Acquirers: MiCA license issuance velocity in Europe is the leading indicator that regulatory-first platforms will command valuation premiums over technology-only specialists. Frame long-term viability around 5-10 year compliance infrastructure amortization and jurisdictional licensing portfolio breadth. Target acquisition profiles emphasizing VARA-licensed entities with derivatives trading permissions and staking service capabilities. Watch stablecoin reserve restructuring announcements as signals of issuer capital efficiency stress.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Licensing Expansion | MiCA compliance in Europe and VARA approval in Dubai create defensible geographic moats against regulatory fragmentation. |
| Custody Infrastructure Backward Integration | In-house HSM module development and secure element sourcing reduce vendor lock-in with German and Taiwanese suppliers. |
| Derivatives Protocol Development | Perpetual futures and options infrastructure capture institutional order flow from Chicago and Dubai trading desks. |
| Embedded Finance API Licensing | White-label exchange integration with Southeast Asian neobanks expands user acquisition beyond direct marketing spend. |
| Stablecoin Reserve Restructuring | 30% bank deposit compliance under MiCA mandates liquidity transformation for European-issued fiat-backed tokens. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining structured interviews with exchange compliance officers, custody infrastructure procurement leads, and neobank partnership directors with validation against MiCA implementation guidance, SEC registration disclosures, and MAS licensing determinations. Bottom-up platform volume estimates and top-down market sizing triangulated through banking relationship mapping and fiat on-ramp processor concentration analysis.
Data-stream reconciliation across spot trading volume, derivatives open interest, and custody asset under administration enabled segmentation modeling by service type, customer tier, and security feature deployment. The analytical framework projected growth across the analysis window using institutional onboarding velocity, regulatory licensing timeline compression, and embedded finance API penetration as core demand drivers. CAGRs derived from quarterly platform disclosure patterns and banking relationship expansion trajectories.
The model holds under stable regulatory enforcement intensity; deviation in SEC registration mandate timing or MiCA reserve requirement calibration would shift platform economics and geographic relocation incentives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market