
 Digital Asset Trading Platform Market | 2026-2036
Digital Asset Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Asset Trading Platform Market Analysis
Multi-source liquidity provisioning is shifting from centralized exchange dominance toward hybrid models blending custodial and non-custodial infrastructure. Binance leverages its global matching engine footprint to sustain volume leadership across spot and derivatives markets. Coinbase anchors its competitive position through regulatory licensing depth in multiple jurisdictions. Kraken differentiates via specialized staking and institutional custody services.
A digital asset trading platform constitutes software infrastructure enabling order matching, settlement, and custody for blockchain-based instruments, typically processing throughput exceeding 100,000 transactions per second at leading operators. Its primary commercial purpose centers on reducing counterparty risk while providing price discovery mechanisms for programmable assets. Exchange platforms capture the dominant margin pool given network effects in liquidity aggregation, while custody services exhibit accelerated expansion as institutional mandates require segregated cold-storage architectures. Cloud-based deployment models lead adoption among newer entrants seeking elastic compute scaling without capital-intensive data center buildouts.
SEC registration requirements under evolving securities frameworks, EU MiCA licensing standards, and Singapore MAS payment institution rules collectively determine market access thresholds for platform operators. These regulatory structures shape demand by mandating capital reserves, audit transparency, and consumer protection protocols that favor compliant incumbents. Stakeholders must monitor jurisdictional arbitrage dynamics as regulatory fragmentation creates divergent compliance cost structures across operating regions.
Market Dynamics
Hybrid infrastructure architectures are compressing the dominance of pure centralized exchanges as institutional mandates force reconciliation between self-custody assurances and regulatory audit trails. Platform operators now engineer modular stacks separating execution, clearing, and settlement functions across jurisdictional boundaries.
Growth Catalysts
- MiCA Licensing Framework:The European Union's Markets in Crypto-Assets regulation creates uniform passporting rights across member states, reducing fragmentation costs for compliant operators seeking cross-border scale.
- Singapore MAS Payment Institution Rules:Singapore's licensing clarity attracts platform headquarters relocation from less certain jurisdictions, concentrating APAC operational talent in the city-state.
- Institutional Custody Mandates:Pension funds and asset managers now require segregated cold-storage architectures with third-party audit trails, accelerating demand for licensed custody infrastructure.
Market Restraints
- SEC Registration Uncertainty:Evolving securities classification frameworks in the United States create compliance cost volatility as platforms maintain dual-state legal structures pending definitive rulemaking.
- Cloud Concentration Risk:Elastic compute scaling depends on hyperscaler infrastructure concentrated among three dominant providers, creating single-point-of-failure exposure for newer exchange entrants.
- Cross-Chain Settlement Latency:Interoperability protocols between Layer-1 networks exhibit finality delays exceeding institutional risk tolerance for large-value transactions.
Strategic Opportunities
- Tokenized Securities Infrastructure:Convergence of traditional settlement rails with blockchain-based registry systems enables platforms to capture equity and debt issuance flows currently processed by legacy clearinghouses.
- United Arab Emirates Regulatory Sandbox:Dubai's VARA framework permits controlled experimentation with novel trading mechanisms, attracting operators seeking to test derivatives and structured products ahead of broader licensing.
- Embedded Finance Distribution:Banking-as-a-Service integrations allow retail brokerages to offer digital asset exposure without building proprietary custody stacks, expanding addressable channel partnerships.
Industry Challenges
- Smart Contract Security Engineering:Platform operators face acute scarcity of formal verification specialists capable of auditing self-executing settlement logic at institutional deployment scale.
- Legacy Core Banking Integration:Corporate treasury clients demand API connectivity with existing ERP and treasury management systems, requiring expensive middleware development for each major software vendor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Asset Trading Platform Market |
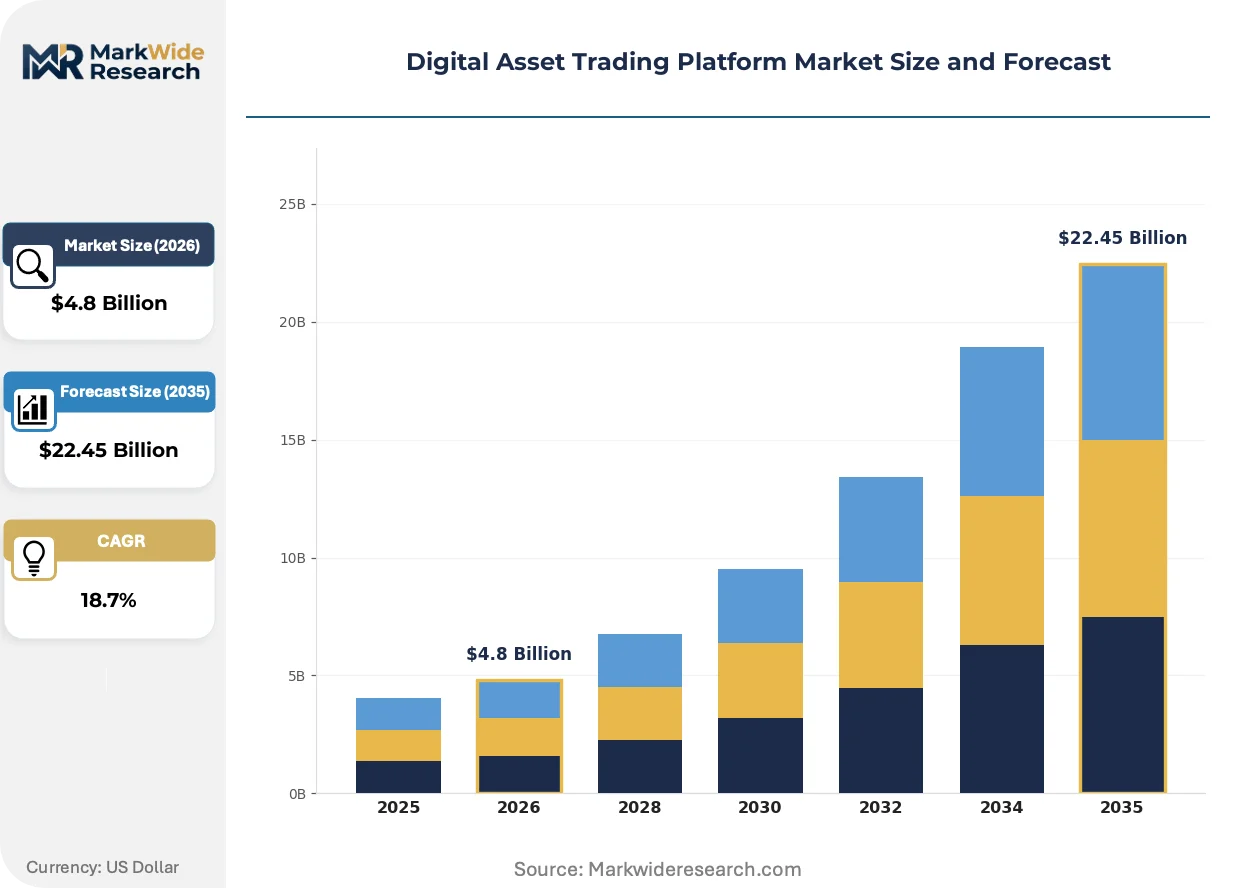
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exchange Platforms, Custody Services, Brokerage Services, Wallet Solutions End User: Retail Investors, Institutional Investors, Traders, Asset Managers Product Type: Cryptocurrencies, Tokens, Stablecoins, Derivatives Deployment Model: On-Premises, Cloud-Based, Hybrid, Multitenant |
| Companies Covered | OKX, Bitfinex, Binance, Bitstamp, Huobi, Coinbase, Kraken, KuCoin, Bybit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Asset Trading Platform Market Emerging Trajectories
Execution infrastructure is fragmenting across specialized layers as regulatory jurisdiction becomes the primary segmentation variable for platform architecture decisions. Operators now optimize for compliance portability rather than pure throughput metrics.
Zero-knowledge proof technology is integrating into trade confirmation workflows to satisfy privacy requirements without sacrificing regulatory transparency. Institutional desks in Switzerland and Liechtenstein are adopting these cryptographic methods for pre-trade position verification. The structural compression enables cross-platform netting agreements that were previously impossible under information-asymmetry constraints.
EU MiCA's stablecoin reserve requirements are forcing issuers to restructure collateral frameworks ahead of full implementation deadlines. Circle and Tether competitors must now maintain segregated accounts with EU-credit-institution custodians. Custody-dependent segments including euro-denominated trading pairs face the most acute reconfiguration timelines as grandfathering provisions expire.
Buy-side due diligence is extending beyond technical security audits to encompass jurisdictional risk assessments of platform operator licensing depth. Family offices and hedge funds now retain specialized legal counsel for multi-jurisdictional counterparty mapping before committing capital. This behavioral shift is most visible in Switzerland and Singapore where private banking relationships traditionally dominated allocator decisions.
Digital Asset Trading Platform Market Segmentation
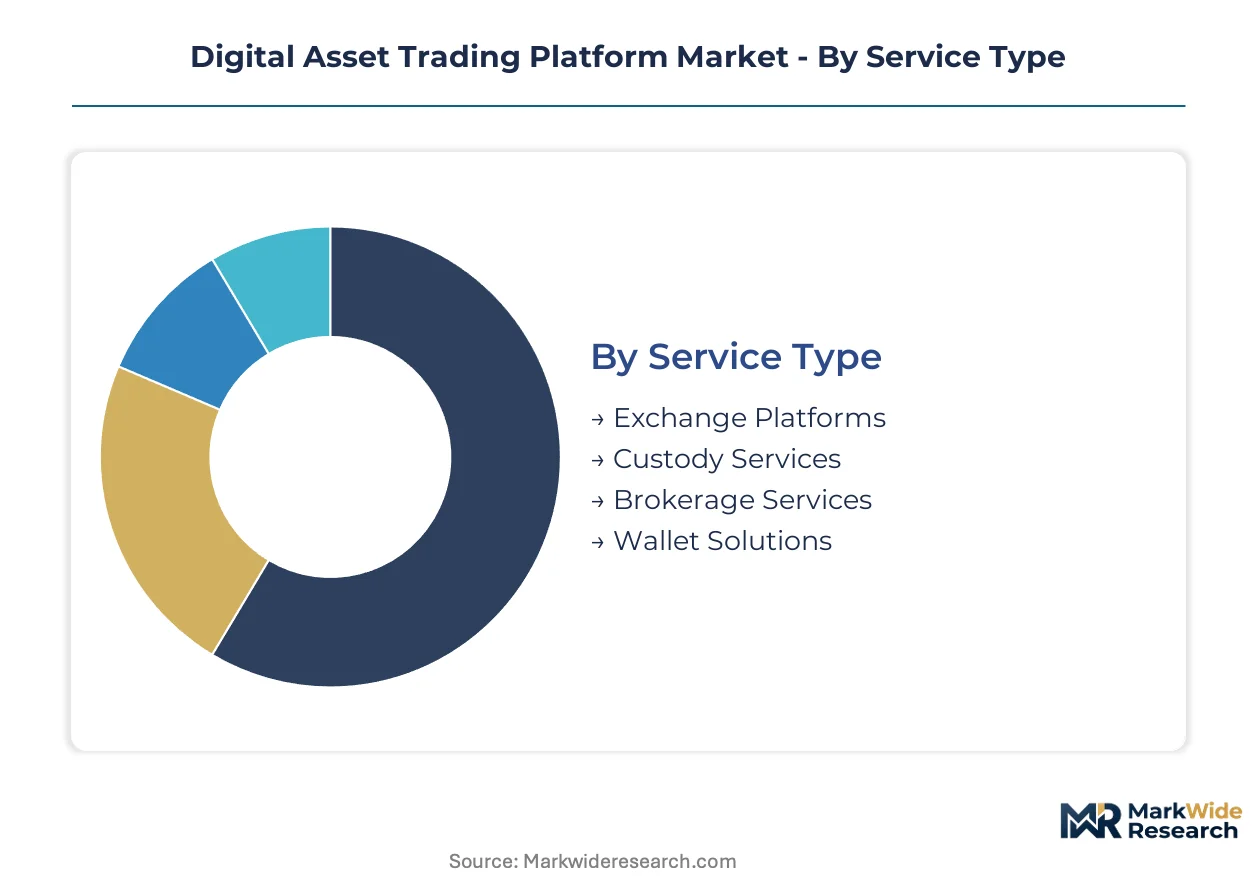
Platform operators configure service architectures around distinct capital requirements and regulatory exposure profiles. Segmentation reveals where infrastructure investments concentrate and which user categories drive margin expansion.
Service Type:
Exchange platforms demand the heaviest upfront investment in matching engine technology and regulatory licensing across multiple jurisdictions.
- Exchange Platforms:Centralized order-matching infrastructure processes throughput exceeding 100,000 transactions per second at leading operators. Singapore and the United States concentrate demand as institutional mandates force reconciliation between execution speed and audit transparency.
- Custody Services:Segregated cold-storage architectures with third-party audit trails satisfy pension fund and asset manager mandates. Licensed custody infrastructure accelerates fastest in Switzerland and Liechtenstein where private banking relationships dominate allocator decisions.
- Brokerage Services:Agency execution models aggregate liquidity across multiple venues without taking proprietary risk.
- Wallet Solutions:Non-custodial key management tools serve retail self-custody preferences with lower regulatory overhead.
Exchange platforms absorb the bulk of installed capacity; custody services are expanding most quickly.
End User:
Customer type determines compliance architecture depth and average revenue per user.
- Institutional Investors:Pension funds and asset managers require segregated account structures with formal verification of smart contract security. Demand concentrates in Singapore where the Monetary Authority of Singapore licensing framework provides regulatory clarity unavailable in less certain jurisdictions.
- Asset Managers:Hedge funds and family offices conduct multi-jurisdictional counterparty mapping before committing capital. Switzerland and Singapore show the most visible behavioral shift toward specialized legal counsel for platform due diligence.
- Retail Investors:Individual account holders drive volume through mobile-first interfaces with simplified onboarding.
- Traders:Proprietary desks and algorithmic operators prioritize latency-sensitive co-location and advanced order types.
Retail investors generate the highest transaction volumes; institutional investors command the steepest expansion trajectory in revenue per account.
Product Type:
Instrument classification shapes settlement infrastructure requirements and collateral frameworks.
- Derivatives:Perpetual swaps and options contracts require sophisticated margin calculation engines and cross-platform netting agreements. Dubai's VARA regulatory sandbox attracts operators testing structured products ahead of broader licensing.
- Stablecoins:Fiat-pegged instruments face acute reconfiguration timelines as EU MiCA reserve requirements force collateral restructuring with EU-credit-institution custodians.
- Cryptocurrencies:Native Layer-1 assets settle on their respective blockchains with varying finality guarantees.
- Tokens:Programmable assets span utility, governance, and security classifications with divergent regulatory treatment.
Cryptocurrencies dominate spot trading volume; derivatives are climbing the fastest in notional value terms.
Deployment Model:
Infrastructure location decisions trade capital efficiency against operational control and jurisdictional compliance.
- Cloud-Based:Elastic compute scaling without data center buildouts attracts newer entrants. Concentration risk emerges from dependence on three dominant hyperscaler providers.
- Hybrid:Modular stacks separate execution, clearing, and settlement across jurisdictional boundaries to optimize for compliance portability.
- On-Premises:Dedicated hardware installations serve operators with strict data sovereignty requirements.
- Multitenant:Shared infrastructure instances reduce unit economics for smaller platforms with correlated security exposure.
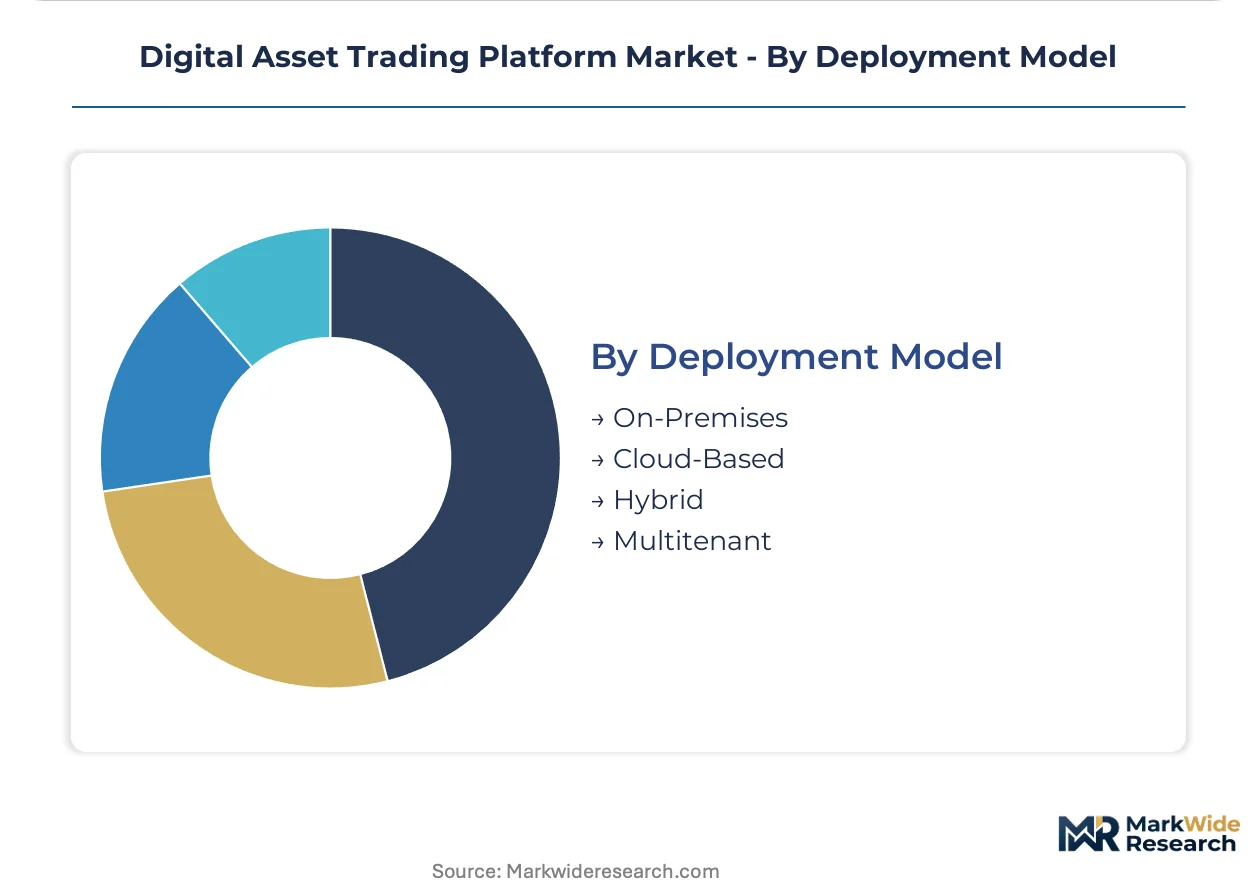
Cloud-based deployments capture the majority of new entrants; hybrid architectures are gaining share fastest among institutional-facing operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's regulatory sandbox anchors Asia-Pacific platform development as institutional capital flows concentrate in jurisdictions with licensing clarity. The United States and European Union compete for operational headquarters through divergent securities frameworks. Dubai and Switzerland carve specialized niches in derivatives and private banking integration respectively.
United States
Institutional custody mandates from pension funds and asset managers drive demand for segregated cold-storage architectures. SEC registration requirements under evolving securities frameworks create compliance cost volatility for platform operators. New York and Chicago concentrate exchange infrastructure development as regulatory clarity lags behind institutional capital deployment timelines.
Singapore
The Monetary Authority of Singapore's payment institution licensing framework attracts platform headquarters relocation from less certain jurisdictions. MAS rules mandate capital reserves and audit transparency that favor compliant incumbents seeking cross-border scale. The city-state concentrates APAC operational talent as family offices and hedge funds conduct multi-jurisdictional counterparty mapping before committing capital.
Germany
EU MiCA's uniform passporting rights reduce fragmentation costs for compliant operators seeking cross-border scale across member states. BaFin licensing standards enforce consumer protection protocols that accelerate demand for licensed custody infrastructure. Frankfurt anchors euro-denominated trading pair development as stablecoin issuers restructure collateral frameworks with EU-credit-institution custodians.
United Arab Emirates
Dubai's VARA regulatory sandbox permits controlled experimentation with novel trading mechanisms ahead of broader licensing. The framework attracts operators testing derivatives and structured products for institutional deployment. Abu Dhabi complements Dubai's experimentation hub with sovereign wealth capital allocation to compliant platform infrastructure.
Switzerland
Private banking relationships dominate allocator decisions as family offices retain specialized legal counsel for platform due diligence. FINMA licensing depth enables zero-knowledge proof integration into trade confirmation workflows for pre-trade position verification. Zurich and Zug concentrate institutional custody services with segregated account structures and formal verification of smart contract security.
Digital Asset Trading Platform Market Vendor Landscape
Global majors compete with regional champions across regulatory licensing depth and institutional custody specialization. The vendor base separates into three tiers: volume leaders with matching engine scale, compliance-heavy incumbents with multi-jurisdictional licensing, and derivatives specialists with structured product capabilities. Strategic moves concentrate on modular stack development separating execution, clearing, and settlement functions, plus embedded finance partnerships with retail brokerages.
Within the volume-leader tier, Binance and Coinbase exemplify divergent geographic risk management strategies. Binance occupies a position emphasizing global matching engine footprint across spot and derivatives markets. Coinbase anchors the compliance-first archetype through regulatory licensing accumulation. Kraken sits within the specialized services tier, representing institutional custody and staking differentiation. OKX and Bybit exemplify derivatives-focused operators testing structured products in permissive regulatory sandboxes.
| Leading Market Players |
|---|
| OKX |
| Bitfinex |
| Binance |
| Bitstamp |
| Huobi |
| Coinbase |
| Kraken |
| KuCoin |
| Bybit |
| Others |
Supply Flow & Price Mechanics
Institutional-grade platform tiers diverge sharply from retail-facing infrastructure on both cost structures and supplier ecosystems. Premium custody stacks command threefold unit economics over standardized exchange modules due to segregated cold-storage requirements and third-party audit trails mandated by Singapore MAS and EU MiCA frameworks, while commodity matching engines compete on hyperscaler compute pricing alone.
Pricing Analysis
Service bundling separates licensed custody packages from bare-metal execution rentals. Three-tier pricing structure across premium, standard, and economy levels maps to regulatory certification depth: MiCA-compliant operators with EU-credit-institution custodian relationships price at premiums, unlicensed offshore venues compete on transaction fee minimization, and hybrid brokerage APIs occupy mid-market positioning. Cost compression in retail execution tiers is intensifying because hyperscaler volume discounts favor scale leaders. Proprietary traders exhibit least price sensitivity due to latency co-location requirements, while emerging market retail aggregators face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates in data sovereignty regimes are reshaping sourcing toward jurisdictional compute clusters. Hardware concentration centers on Taiwan for advanced semiconductors, South Korea for memory modules, and the United States for specialized ASIC fabrication. Cloud infrastructure draws from Nvidia GPUs, Arista network switches, and Samsung solid-state storage arrays. Single-source vulnerability persists in EU-certified hardware security modules required for MiCA compliance. Distribution runs through direct hyperscaler partnerships for newer entrants and captive data center builds for sovereign-compliant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MiCA licensing standards erect barrier-to-entry moats favoring capitalized incumbents over undercapitalized challengers.
For Market Incumbents: Extend jurisdictional licensing depth ahead of MiCA grandfathering deadlines to capture cross-border passporting rights. Deepen backward integration into proprietary custody hardware to reduce dependence on EU-certified security module suppliers facing allocation constraints. Threat substitution from decentralized exchange protocols intensifies margin pressure on spot trading fees. For New Entrants and Emerging Players: Begin with Dubai VARA sandbox participation to test structured derivatives products ahead of broader institutional licensing. White-space concentration sits with embedded finance distribution partnerships enabling retail brokerages to offer digital asset exposure without proprietary custody builds. Go-to-market leverage rests on Banking-as-a-Service API integrations with established neobank channels. For Investors and Strategic Acquirers: Re-rating potential sits with MiCA-licensed custody specialists given passporting rights expansion across euro-denominated institutional mandates. Long-term viability favors operators with segregated account architectures and formal verification capabilities for smart contract security. Signal to watch: Singapore MAS licensing queue velocity as proxy for APAC operational talent concentration.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Acquisition | EU passporting rights reduce fragmentation costs for cross-border custody operations. |
| Hybrid Infrastructure Deployment | Modular stacks separating execution and settlement optimize compliance portability across jurisdictions. |
| Zero-Knowledge Proof Integration | Switzerland FINMA guidance enables privacy-preserving trade confirmation for institutional desks. |
| Embedded Finance Partnership | Banking-as-a-Service APIs expand retail distribution without proprietary custody capital requirements. |
| VARA Sandbox Participation | Dubai's controlled experimentation framework permits derivatives testing ahead of broader licensing. |
Methodological Framework
Document review covered SEC registration filings, EU MiCA regulatory texts, Singapore MAS licensing guidelines, and hyperscaler infrastructure disclosures, complemented by interviews with exchange platform CTOs, custody infrastructure engineers, regulatory compliance officers at licensed operators, and institutional trading desk heads at asset managers. Secondary validation drew from blockchain analytics providers, cloud service provider capex reports, and jurisdictional trade association publications. Bottom-up transaction volume estimates triangulated against top-down regulatory licensing counts.
Model outputs project market evolution across service type, end-user category, deployment architecture, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from licensing velocity assumptions, institutional capital deployment timelines, and infrastructure cost curves. Industry-specific inputs encompass MiCA implementation phase transitions, MAS application queue dynamics, and cross-chain settlement finality improvements.
Underlying measurement precision varies by segment; exchange platform transaction volumes carry tighter precision than custody service revenue allocations due to blockchain transparency. Forecasts reflect documented assumptions on regulatory implementation schedules and institutional adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Crypto Wallet Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Global Digital Vault Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market