
 Insurance Third Party Administrators Market | 2026-2036
Insurance Third Party Administrators Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Third Party Administrators Market Foresight
Licensed claims adjuster availability is rotating toward digital-first skill profiles, tightening traditional talent pipelines while unlocking automation-led scale. Sedgwick Claims Management Services Inc anchors its market position through vertical integration across workers' compensation and liability verticals. Gallagher Bassett Services Inc differentiates via technology leadership in predictive analytics for claim duration forecasting. Crawford & Company extends its geographic dominance through specialized catastrophe response networks spanning multiple continents.
Insurance third party administrators are outsourced entities that manage operational functions—including claims adjudication, benefit administration, and compliance reporting—on behalf of insurers, self-funded employers, and government programs, typically operating under service-level agreements with defined turnaround times and accuracy benchmarks. Their primary commercial purpose is to reduce per-claim processing costs while maintaining regulatory adherence and beneficiary satisfaction. Claims processing services occupy the largest revenue pool within service type segmentation due to volume density in health and property lines. Cloud-based solutions represent the fastest-expanding technology category as administrators migrate legacy on-premises infrastructure to scalable architectures. Self-insured entities within client type segmentation command premium pricing due to customized plan design complexity and fiduciary liability transfer requirements.
The US Department of Labor enforces ERISA standards that dictate fiduciary conduct and fee disclosure for administrator engagements, while HIPAA governs protected health information handling across claims workflows. State insurance commissioners maintain solvency oversight and licensing requirements that create barriers to unauthorized market entry. The EU AI Act introduces algorithmic transparency mandates affecting automated claims decisioning systems deployed in European operations. Stakeholders must monitor evolving state-level surprise billing regulations and federal price transparency rules that reshape data infrastructure investments and contractual risk allocations.
Market Dynamics
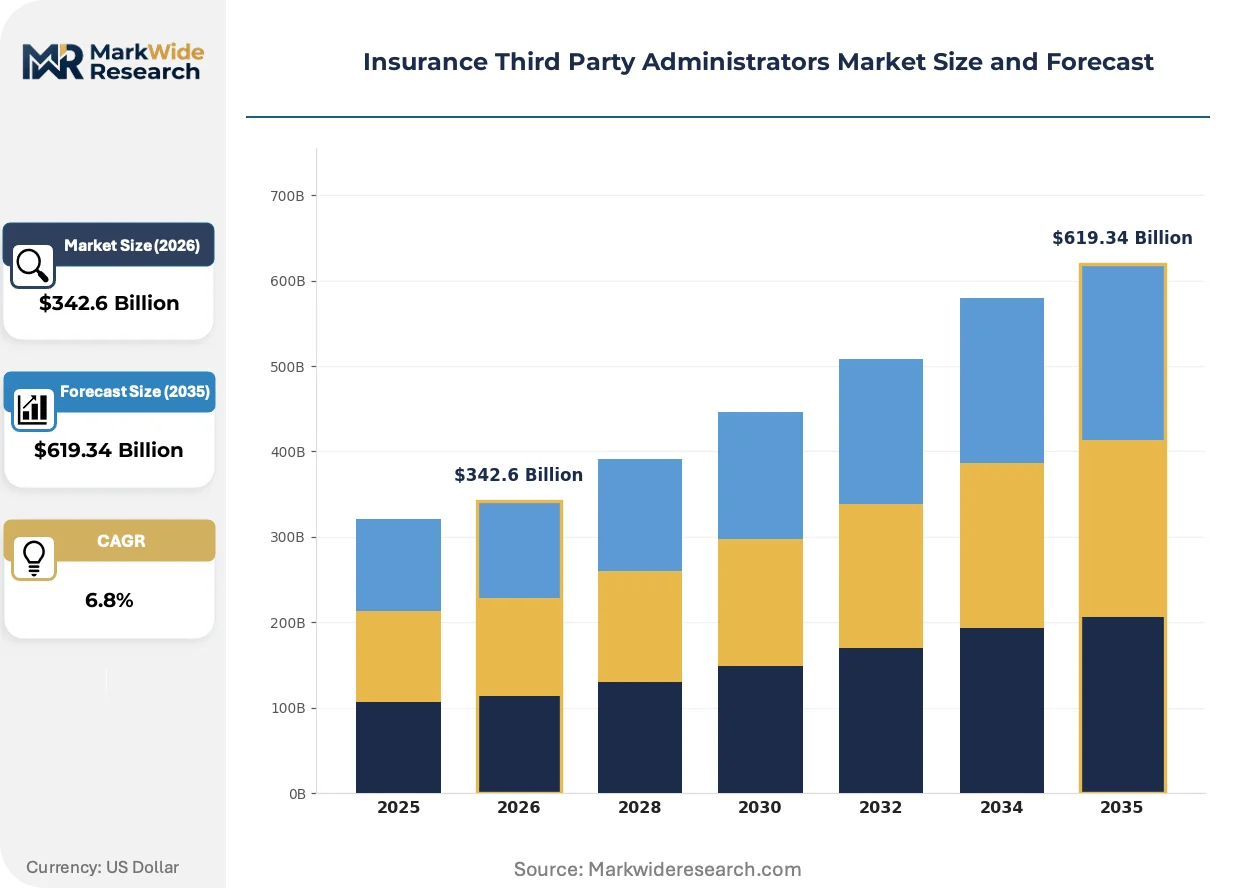
Self-insured employers are accelerating administrator outsourcing as fiduciary liability transfer and ERISA compliance complexity reshape contract economics, with cloud infrastructure investments compressing per-claim processing costs below legacy on-premises thresholds.
Growth Catalysts
- ERISA Fiduciary Standards:US Department of Labor enforcement of fee disclosure and conduct rules drives employer demand for administrator partnerships that transfer fiduciary risk and document compliance rigor.
- Cloud Infrastructure Migration:Scalable architecture adoption enables real-time claims processing at lower unit economics, attracting mid-market self-funded plans previously served by in-house operations.
- Workers' Compensation Volume Concentration:Manufacturing and logistics employers in industrial US states generate sustained claims density that rewards specialized administrator scale.
Market Restraints
- Licensed Adjuster Supply Bottleneck:Digital-first skill requirements in claims processing have tightened traditional talent pipelines, extending hiring cycles and inflating compensation for hybrid technical-adjusters.
- State Licensing Fragmentation:Solvency oversight and admission requirements vary across US state insurance commissioners, creating compliance overhead that slows multi-state expansion for regional administrators.
- Legacy System Technical Debt:Core policy administration platforms built on 1990s architectures impose integration friction with modern APIs, delaying automation deployment and elevating maintenance spend.
Strategic Opportunities
- Surprise Billing Regulatory Tailwind:Federal No Surprises Act implementation creates demand for administrator infrastructure that reconciles out-of-network pricing and dispute resolution workflows.
- AI-Enabled Decisioning Convergence:Machine learning classification layered on optical character recognition is compressing manual document review, opening automation-led scale in property and casualty lines.
- Self-Insured Municipal Expansion:School districts and county governments represent underpenetrated plan sponsors seeking claims administration expertise without building captive operations.
Industry Challenges
- HIPAA Technical Safeguard Implementation:Protected health information handling across distributed cloud environments demands continuous security architecture investment and staff certification maintenance.
- API Integration Complexity:Real-time data exchange with employer HRIS platforms and payer networks requires bespoke middleware development that strains implementation timelines and margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Third Party Administrators Market |
| Market Size in 2026 | $342.6 Billion |
| Market Size in 2035 | $619.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Customer Support, Risk Management, Compliance Services Client Type: Insurance Companies, Self-Insured Entities, Corporations, Government Agencies Technology: Cloud-Based Solutions, On-Premises Systems, Mobile Platforms, Data Analytics Tools End User: Small Businesses, Large Enterprises, Individuals, Non-Profit Organizations |
| Companies Covered | CorVel Corporation, Alight Solutions LLC, Sedgwick Claims Management Services Inc, Conduent State Healthcare LLC, Meritain Health Inc, Gallagher Bassett Services Inc, ESIS Inc, HealthSmart Holdings Inc, Crawford & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Third Party Administrators Market Shifts & Advancements
Automation architectures and regulatory data mandates are restructuring how administrators invest in technology infrastructure and talent composition, with competitive advantage accruing to firms that operationalize compliance as a service layer.
Robotic process automation paired with natural language processing is fragmenting the traditional claims examiner role into discrete task categories—triage, documentation verification, and reserve setting—that machine learning handles at scale. Large self-insured employers and commercial insurers are deploying these tools aggressively in workers' compensation and auto liability lines. The technology is fragmenting labor cost structures, compressing headcount per thousand claims while elevating demand for exception-handling specialists.
The EU AI Act introduces algorithmic transparency mandates affecting automated claims decisioning systems deployed in European operations, requiring documentation of training data provenance and human oversight protocols. Administrators with cross-border footprints must retrofit European workflows with explainability features and audit trails that satisfy national competent authorities. Property and casualty lines with high-frequency, low-severity claims are most affected, with carriers accelerating procurement of compliant decisioning platforms ahead of enforcement timelines.
Employer procurement of administrator services is consolidating around performance-based fee structures that tie compensation to claim closure velocity and beneficiary satisfaction scores, displacing traditional per-employee-per-month arrangements. Third-party administrators and brokers are restructuring contracts to absorb outcome risk, with fiduciary liability transfer becoming a priced service component. This shift is most visible among Fortune 500 self-insured plans in the United States, where procurement teams mandate annual service level agreement renegotiation tied to measurable cost containment results.
Insurance Third Party Administrators Market Segmentation
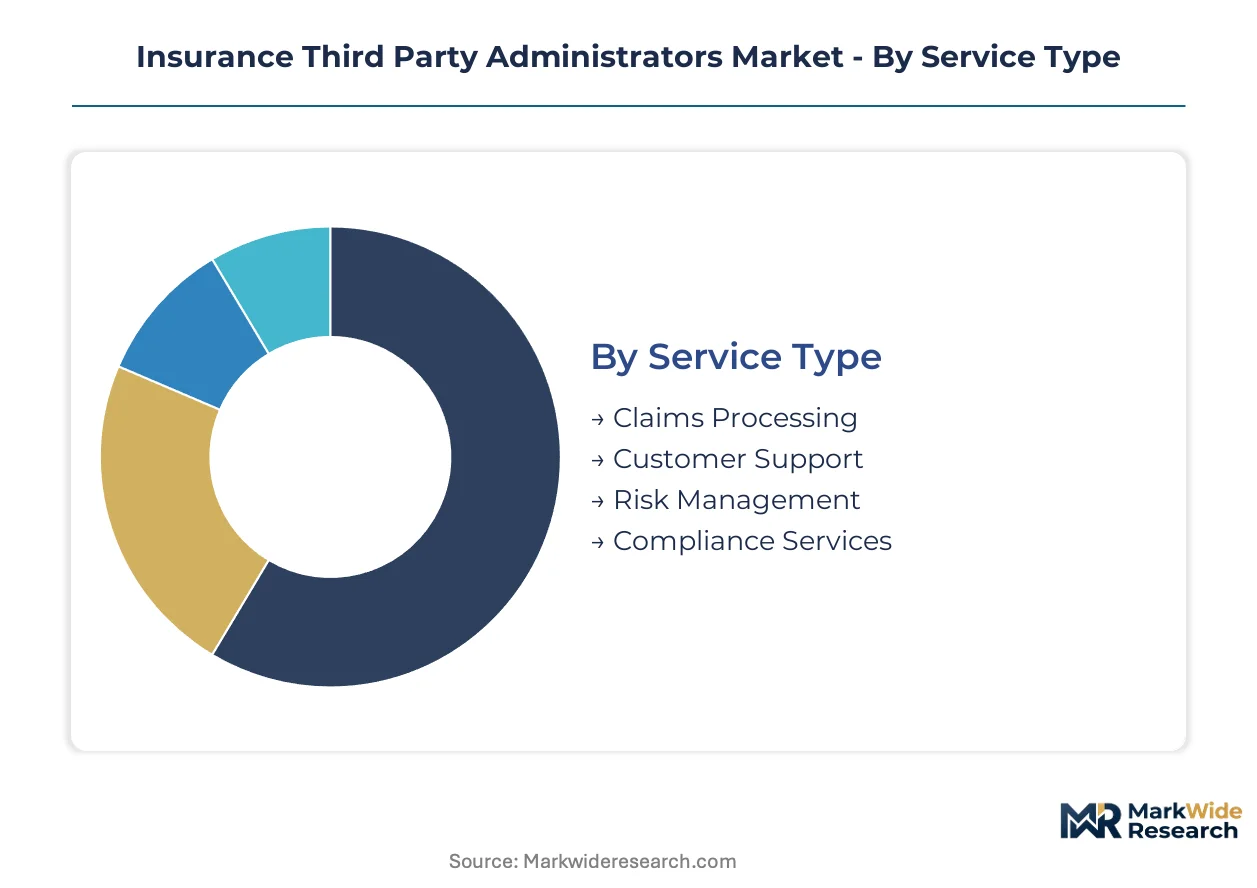
Administrators configure service portfolios around liability transfer intensity and technology modernization readiness. Segment boundaries reflect divergent compliance burdens across ERISA-governed employer plans and state-regulated commercial carriers. Procurement patterns differ materially between self-insured sponsors seeking fiduciary coverage and insurers outsourcing operational scale.
Service Type:
Domestic demand concentrates in claims adjudication and compliance functions tied to US regulatory mandates, while risk management services follow multinational corporations into European and Asia-Pacific operations.
- Claims Processing:Core adjudication workflows span health, property, and casualty lines with defined turnaround benchmarks. Large self-insured employers in industrial US states drive volume concentration as manufacturing and logistics sectors generate sustained claims density. HIPAA technical safeguards and ERISA fiduciary documentation requirements elevate infrastructure investment thresholds.
- Compliance Services:Regulatory reporting automation addresses Affordable Care Act employer mandates and state-level surprise billing reconciliation. Demand clusters among Fortune 500 plans facing Department of Labor audit scrutiny and multi-state licensing complexity.
- Customer Support:Beneficiary inquiry handling and appeals navigation support retention metrics for administrator contracts. Call center operations with licensed adjuster staffing serve mid-market employers lacking captive member services teams.
- Risk Management:Loss control consulting and reserve optimization support workers' compensation and liability verticals. Cross-border deployment follows multinational corporations into jurisdictions with divergent occupational safety regimes.
Claims Processing commands the established base. The steepest expansion runs through Compliance Services.
Client Type:
Pricing tiers separate fiduciary-heavy engagements with customized plan design from standardized administrative contracts with defined scope boundaries.
- Self-Insured Entities:Employer-sponsored plans transfer fiduciary liability and ERISA compliance burden through administrator partnerships. Premium pricing reflects customized benefit structures, stop-loss coordination, and member-specific reporting requirements.
- Insurance Companies:Commercial carriers outsource operational scale for specific lines or geographies without captive infrastructure investment. Contracts emphasize per-claim unit economics and service-level agreement enforcement.
- Corporations:Captive insurance arrangements and risk retention groups seek administrative support for self-funded workers' compensation and liability programs. Manufacturing and logistics employers in industrial states represent concentrated demand.
- Government Agencies:Medicaid managed care and public employee benefit plans require administrator expertise in federal program compliance and beneficiary eligibility verification.
Self-Insured Entities anchor revenue concentration. Government Agencies are climbing the fastest as municipal expansion accelerates.
Technology:
Deployment models stratify by IT modernization trajectory, with cloud migration compressing per-claim costs below legacy on-premises maintenance thresholds.
- Cloud-Based Solutions:Scalable architectures enable real-time claims processing and distributed workforce coordination. Mid-market self-funded plans previously served by in-house operations represent expanding adoption as unit economics improve.
- On-Premises Systems:Legacy policy administration platforms persist among administrators serving HIPAA-sensitive health lines with stringent data localization requirements. Technical debt from 1990s architectures delays API integration with modern employer HRIS platforms.
- Data Analytics Tools:Predictive modeling for claim duration forecasting and reserve optimization supports outcome-based fee structures. Machine learning classification layered on document processing compresses manual review cycles.
- Mobile Platforms:Member-facing applications for claim submission and status inquiry elevate beneficiary satisfaction scores tied to contract renewal.
On-Premises Systems retain the incumbent installed base. Cloud-Based Solutions gain share fastest as infrastructure migration accelerates.
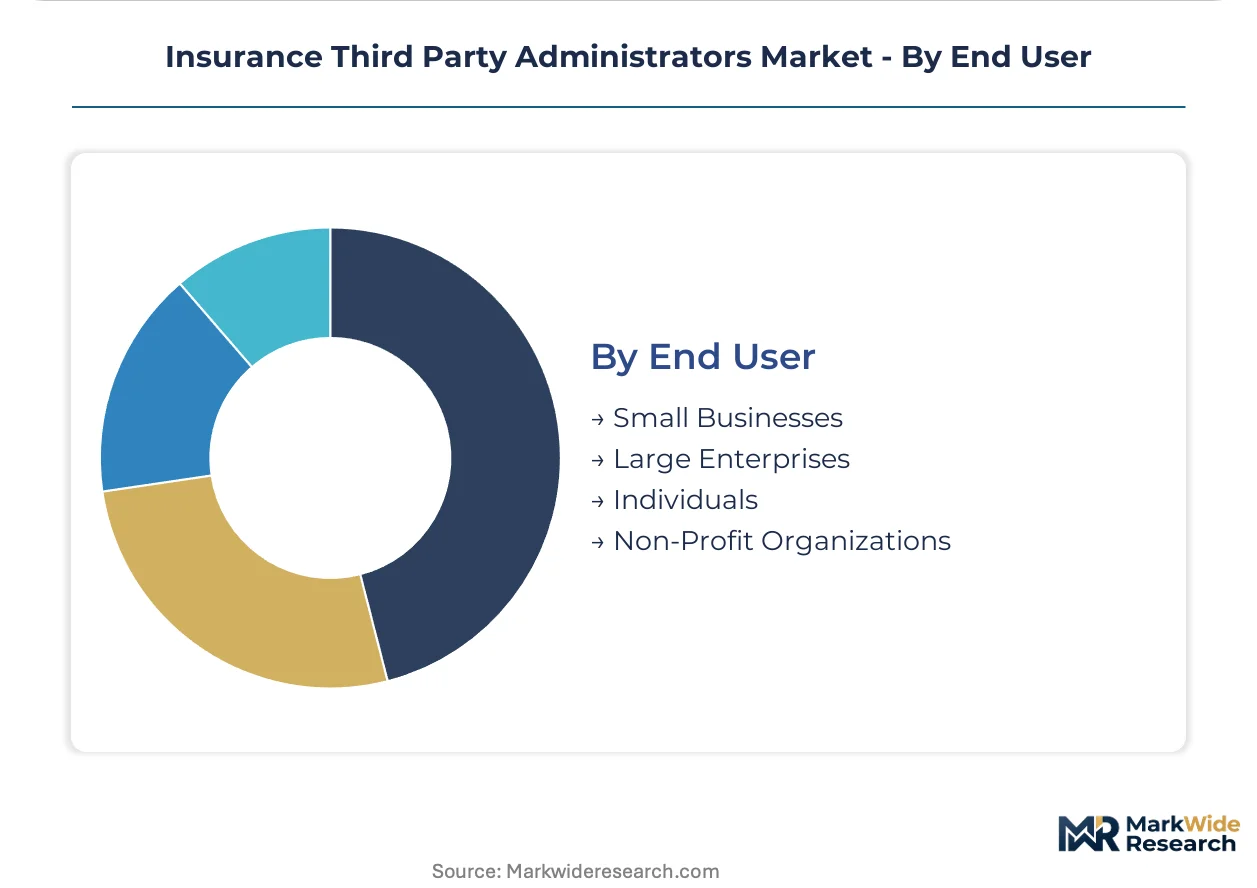
End User:
Scale requirements separate enterprise-grade fiduciary transfers from standardized administrative packages serving fragmented small-group markets.
- Large Enterprises:Fortune 500 self-insured plans mandate annual service level agreement renegotiation tied to measurable cost containment and closure velocity metrics. Procurement teams absorb outcome risk through performance-based fee structures.
- Small Businesses:Fully insured and level-funded arrangements access administrator services through broker intermediaries with limited customization scope. Price sensitivity constrains technology investment and dedicated account management.
- Individuals:Direct-to-consumer channels remain marginal, concentrated in Medicare supplemental and individual disability lines with simplified claim workflows.
- Non-Profit Organizations:Religious institutions and charitable entities seek claims administration without building captive operations, often through association purchasing cooperatives.
Large Enterprises dominate contract value. Non-Profit Organizations show the steepest expansion trajectory as underpenetrated segments access outsourced expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-insured employers in the United States consume administrator services at substantially higher fiduciary intensity than counterparts elsewhere, while European demand clusters around compliance automation for cross-border regulatory frameworks.
United States
Fortune 500 manufacturers and logistics operators in industrial states generate sustained claims density for workers' compensation administration. The US Department of Labor enforces ERISA fiduciary standards that mandate fee disclosure and conduct documentation. Texas and California anchor administrator concentration, with Dallas-Fort Worth and Los Angeles hosting specialized catastrophe response networks.
Germany
Industrial employers in automotive and machinery sectors seek administrator partnerships for occupational health compliance. The EU AI Act introduces algorithmic transparency mandates affecting automated claims decisioning systems. Bavaria and Baden-Württemberg concentrate administrator operations, with Munich serving as a hub for predictive analytics platform development.
United Kingdom
Commercial insurers outsource operational scale for liability lines without captive infrastructure investment. GDPR governs protected health information handling across distributed cloud environments. London anchors administrator presence, with Birmingham and Manchester emerging as secondary centers for mid-market self-funded plan services.
Canada
Provincial workers' compensation boards and private employers generate parallel demand streams for claims adjudication expertise. Health Canada maintains oversight of medical device and pharmaceutical benefit administration. Ontario and Quebec concentrate administrator activity, with Toronto hosting regional headquarters for cross-border fiduciary services.
Australia
Self-insured corporations and government agencies seek administrator expertise for workers' compensation and liability programs. The Therapeutic Goods Administration (TGA) influences pharmaceutical claims processing standards. New South Wales and Victoria anchor demand concentration, with Sydney and Melbourne hosting specialized compliance reporting operations.
Insurance Third Party Administrators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium pricing through fiduciary liability transfer capabilities and multi-line scale. The middle tier fragments across regional geographies and single-vertical specializations. Two archetypes dominate: diversified administrators spanning health, property, and casualty lines; and focused players capturing density in workers' compensation or liability niches. Competitive moves concentrate on cloud infrastructure migration and outcome-based contract restructuring that absorbs employer risk.
Within the integrated tier, Sedgwick Claims Management Services Inc and Gallagher Bassett Services Inc exemplify scale-driven positioning across multiple verticals. Crawford & Company anchors geographic breadth through catastrophe response networks. These three represent the archetype of administrators that transfer fiduciary liability while delivering compliance documentation rigor demanded by large self-insured sponsors.
| Leading Market Players |
|---|
| CorVel Corporation |
| Alight Solutions LLC |
| Sedgwick Claims Management Services Inc |
| Conduent State Healthcare LLC |
| Meritain Health Inc |
| Gallagher Bassett Services Inc |
| ESIS Inc |
| HealthSmart Holdings Inc |
| Crawford & Company |
| Others |
Supply & Pricing Matrix
Claims examiner density in industrial US states anchors administrator scale economies, compressing per-unit processing costs below thresholds achievable by fragmented regional competitors while simultaneously elevating price floors for fiduciary-heavy engagements that transfer ERISA liability.
Pricing Analysis
Long-term service-level agreements dominate administrator contracting, with Fortune 500 self-insured employers locking in multi-year arrangements that embed performance-based fee components tied to claim closure velocity. Premium-mid-economy pricing differentiation separates fiduciary liability transfer engagements from standardized administrative packages, with cloud infrastructure investments enabling mid-market penetration at compressed margins. Pricing pressure stems from outcome-based contract restructuring that absorbs employer risk, while small businesses served through broker intermediaries exhibit the highest price sensitivity.
Supply Chain Analysis
Licensed adjuster certification bottlenecks in the United States tether administrator capacity expansion to hybrid technical talent pipelines that remain constrained despite automation deployment. Cloud infrastructure provisioning draws from hyperscaler data center concentrations in Virginia, Oregon, and Ohio, while legacy system maintenance feeds from specialized mainframe expertise concentrated in Texas and California. Single-source vulnerability in digital claims platforms elevates operational risk, with distribution running through direct enterprise sales teams and broker intermediaries serving fragmented small-group markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of ERISA-certified claims professionals capable of navigating fiduciary documentation requirements simultaneously constrains incumbent expansion and creates entry pathways for specialists who can operationalize compliance as a service layer.
For Market Incumbents: Shield core Fortune 500 relationships by embedding outcome-based fee structures that absorb closure velocity risk, while accelerating cloud migration to compress per-claim economics below mid-market competitor reach. Invest in licensed adjuster apprenticeship pipelines to offset digital-first talent bottlenecks threatening scale deployment.
For New Entrants and Emerging Players: Municipal government and school district segments represent underpenetrated plan sponsors lacking captive claims operations, offering white-space entry with lower fiduciary intensity than corporate engagements. Pursue association purchasing cooperatives as channel partners to aggregate fragmented non-profit demand without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors administrators with cloud-native architectures and proven API integration capabilities that can capture mid-market self-funded plans migrating from in-house operations. Monitor state-level surprise billing regulation implementation as inflection indicator for compliance services demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Migration | Scalable architectures enable real-time claims processing at unit economics below legacy on-premises thresholds. |
| Outcome-Based Contract Restructuring | Performance-linked fee arrangements absorb employer risk while differentiating against per-employee-per-month competitors. |
| Licensed Adjuster Pipeline Development | Hybrid technical talent apprenticeships address digital-first skill shortages constraining automation deployment scale. |
| API Integration Investment | Real-time data exchange with employer HRIS platforms reduces implementation friction and accelerates deployment timelines. |
| Municipal Expansion Program | School districts and county governments represent underpenetrated sponsors seeking claims expertise without captive operations. |
Research Methodology
A spread of perspectives from self-insured employer benefits directors, ERISA compliance officers, licensed claims adjusters, and broker intermediaries converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, state insurance commissioner licensing databases, Department of Labor enforcement records, and healthcare GPO contract disclosures. Bottom-up service line enumeration and top-down macroeconomic triangulation anchored value estimates across the projection horizon.
Segmentation dimensions modeled encompass service type intensity, client fiduciary exposure, technology deployment architecture, and end-user scale tier throughout the forecast period. CAGRs derive from regression analysis against historical claims volume trends, regulatory implementation timelines, and cloud adoption elasticity coefficients specific to healthcare administrative services. Inputs include workers' compensation claim frequency by industrial state concentration and self-insured plan sponsor growth trajectories.
Forecasts assume regulatory continuity in ERISA enforcement standards and HIPAA technical safeguard requirements; material policy shifts would require re-modeling of fiduciary liability transfer pricing and compliance infrastructure investment levels. Practitioners should keep alternative scenarios live as state-level surprise billing regulations and federal price transparency mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Reinsurance Market
Insurance
Business Travel Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Reinsurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Japan Parametric Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
UK Commercial Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
China Online Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Estonia Property and Casualty Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
US Insurance Third-Party Administrator Market