
 Digital Collectibles Platform Market | 2026-2036
Digital Collectibles Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Collectibles Platform Market Insights
Carbon offset verification layers are replacing energy-intensive proof-of-work validation on legacy chains and is realigning platform operating economics toward lower marginal costs per transaction. Dapper Labs leverages proprietary blockchain infrastructure to sustain fee advantages for sports-licensed collectible drops. OpenSea anchors liquidity across secondary markets through broad multi-chain listing support. Venly competes by embedding wallet and minting tools directly into enterprise partner applications.
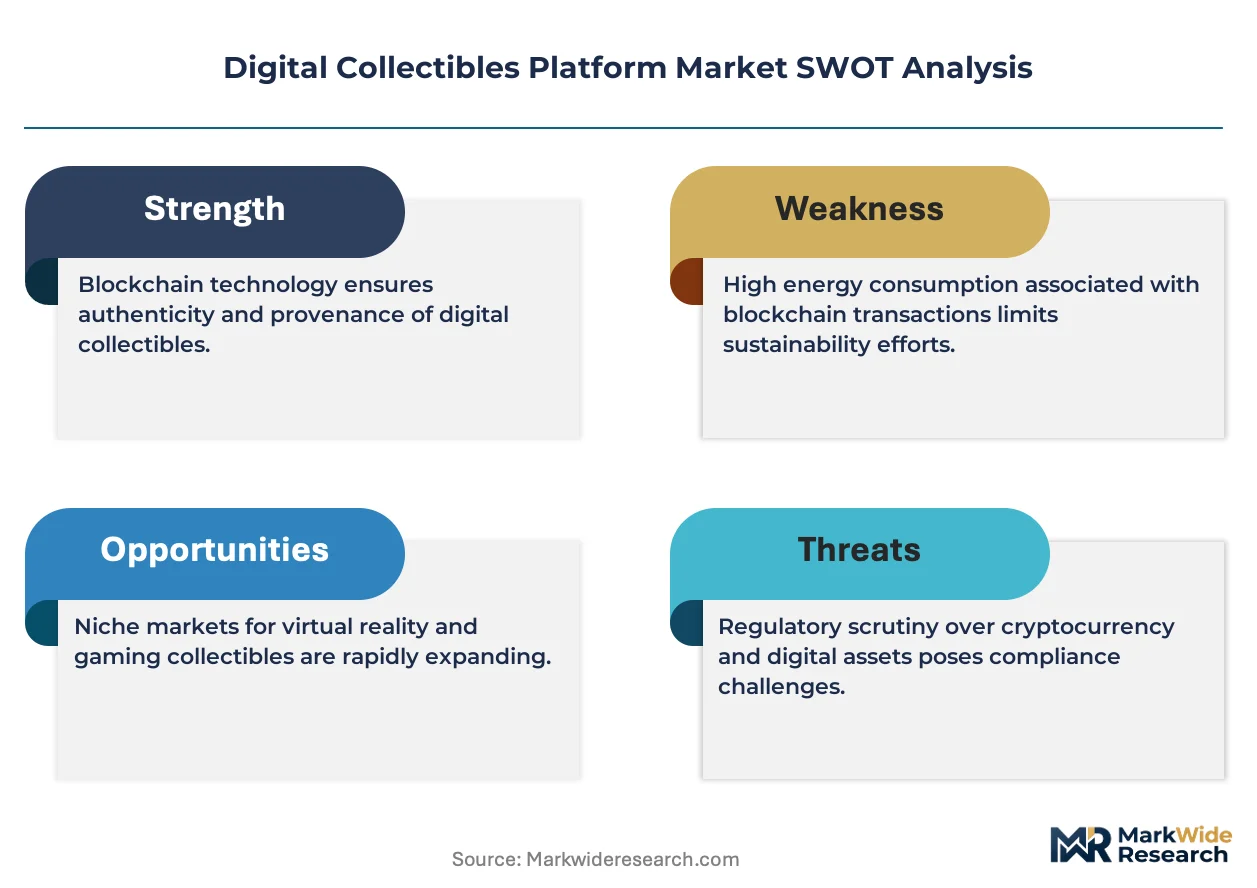
A digital collectibles platform is a software infrastructure that uses distributed ledger technology to mint, authenticate, and transfer unique or limited-run digital assets, typically employing ERC-721 or ERC-1155 token standards with cryptographic hashing to verify provenance and ownership. These platforms serve commercial purposes ranging from creator monetization and fan engagement to speculative investment and virtual world asset management. Art and virtual real estate segments command premium transaction values due to scarcity mechanics and metaverse land utility, while music and video categories are expanding fastest as streaming-era artists adopt tokenized royalty structures. Blockchain and smart contract layers form the technical backbone where margin pools concentrate, since infrastructure providers capture recurring gas and protocol fees regardless of secondary price performance.
SEC enforcement actions against unregistered token offerings shape platform compliance architectures in the United States, while EU MiCA framework provisions are forcing custody and disclosure upgrades for European-accessible marketplaces. ISO standards for blockchain interoperability are gaining traction among enterprise-grade platforms seeking cross-chain liquidity. Stakeholders must monitor whether jurisdictional licensing requirements fragment platform operating models or consolidate activity in regulatory safe harbors.
Market Dynamics
Ethereum's proof-of-stake migration has fundamentally altered platform economics, collapsing energy costs per transaction and triggering institutional capital reallocation toward ESG-compliant infrastructure providers.
Growth Catalysts
- EU MiCA Framework:Standardized licensing requirements across European marketplaces reduce compliance fragmentation and accelerate cross-border platform expansion.
- Tokenized Royalty Structures:Streaming-era musicians adopt programmable revenue splits, driving music segment volume faster than legacy art categories.
- Metaverse Land Utility:Virtual real estate scarcity mechanics anchor premium transaction values and sustain secondary market liquidity depth.
Market Restraints
- SEC Enforcement Uncertainty:Active review of digital asset classification creates compliance architecture delays for US-accessible platforms.
- Layer-1 Gas Volatility:Network congestion on Ethereum mainnet unpredictably elevates minting costs during high-demand drops.
- Wallet Onboarding Friction:Self-custody key management complexity limits mainstream consumer conversion rates.
Strategic Opportunities
- Embedded Enterprise Wallets:White-label minting tools integrated directly into sports franchise mobile applications bypass standalone marketplace competition.
- Carbon Offset Verification Layers:Real-time emissions tracking attracts institutional buyers with net-zero mandates.
- India's PLI Scheme:Domestic blockchain infrastructure incentives position the country as a low-cost minting alternative to Western layer-1 congestion.
Industry Challenges
- Smart Contract Audit Bottlenecks:Certified security review capacity constraints delay platform launch timelines.
- Cross-Chain Interoperability:ISO standard adoption gaps fragment liquidity across competing blockchain ecosystems.
- Creator IP Licensing Complexity:Entertainment studio rights clearance processes extend time-to-market for licensed collectible drops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Collectibles Platform Market |
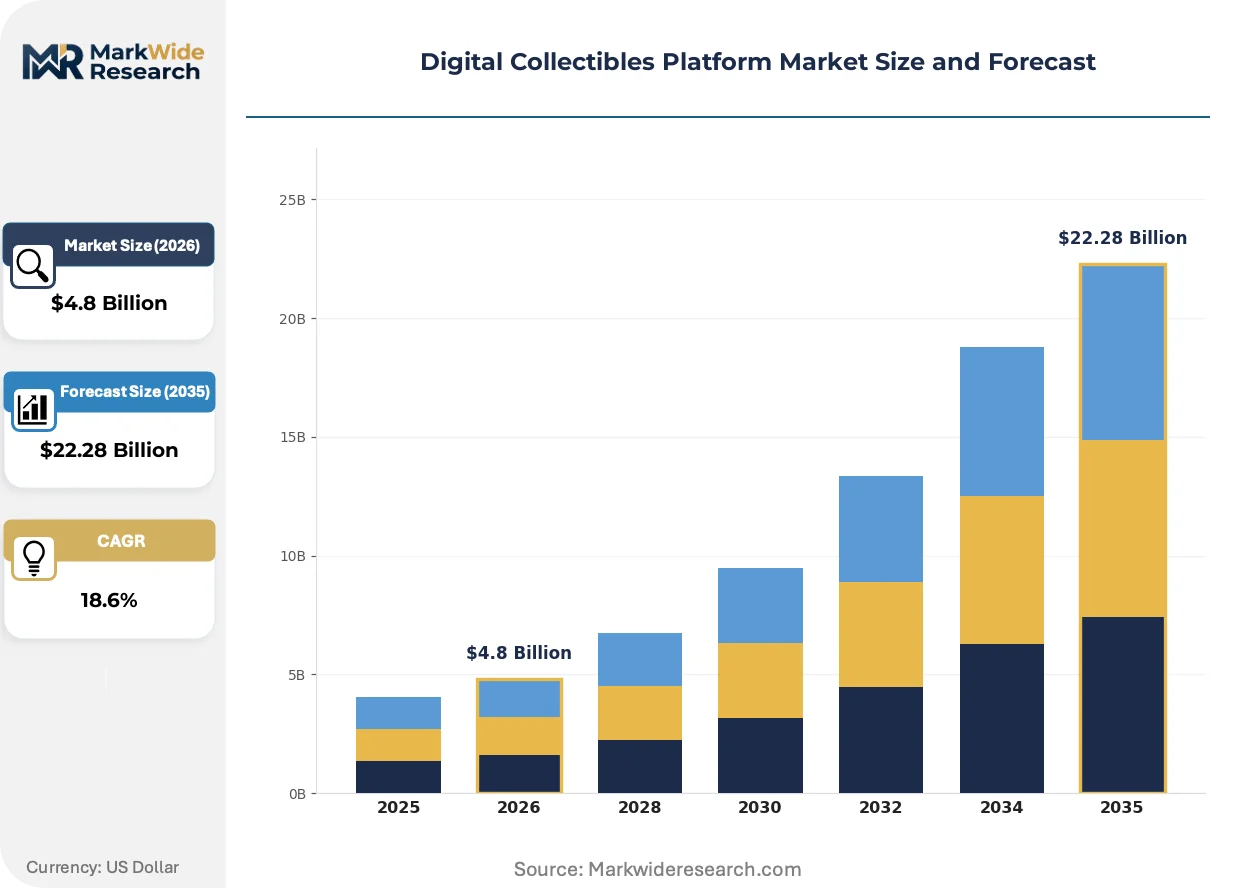
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Art, Music, Video, Virtual Real Estate Technology: Blockchain, Smart Contracts, Cryptography, NFT Standards End User: Collectors, Gamers, Investors, Creators Distribution Channel: Online Marketplaces, Direct Sales, Auctions, Social Media |
| Companies Covered | Vulcan Forged, Rally, Dapper Labs, Sweet, Venly, Whatnot, TCGplayer, GameSquare, OpenSea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Collectibles Platform Market Trends and Innovations
Platform architecture is pivoting from speculative trading infrastructure toward embedded utility layers that serve persistent fan engagement and programmable royalty distribution.
Layer-2 scaling solutions are converging with zero-knowledge proof architectures to compress settlement costs without sacrificing Ethereum mainnet security guarantees. Sports franchises with high-frequency drop schedules adopt these rollups to maintain margin on low-price-point collectible releases. This convergence is displacing single-chain platform strategies and forcing infrastructure providers toward multi-chain orchestration capabilities.
SEC and CFTC jurisdictional clarification efforts are reshaping custody and disclosure requirements for US-facing marketplaces. Platforms must now architect dual compliance stacks separating securities-like token offerings from utility collectibles. Art and fractionalized ownership segments face the steepest restructuring costs as classification uncertainty persists.
Fan token ownership patterns are shifting from speculative holding toward gated utility redemption. Season ticket priority access and voting rights on franchise decisions replace pure price appreciation as primary purchase motivators. European football clubs and North American basketball franchises lead this behavioral pivot, with Asian esports organizations now piloting comparable engagement mechanics.
Digital Collectibles Platform Market Segmentation
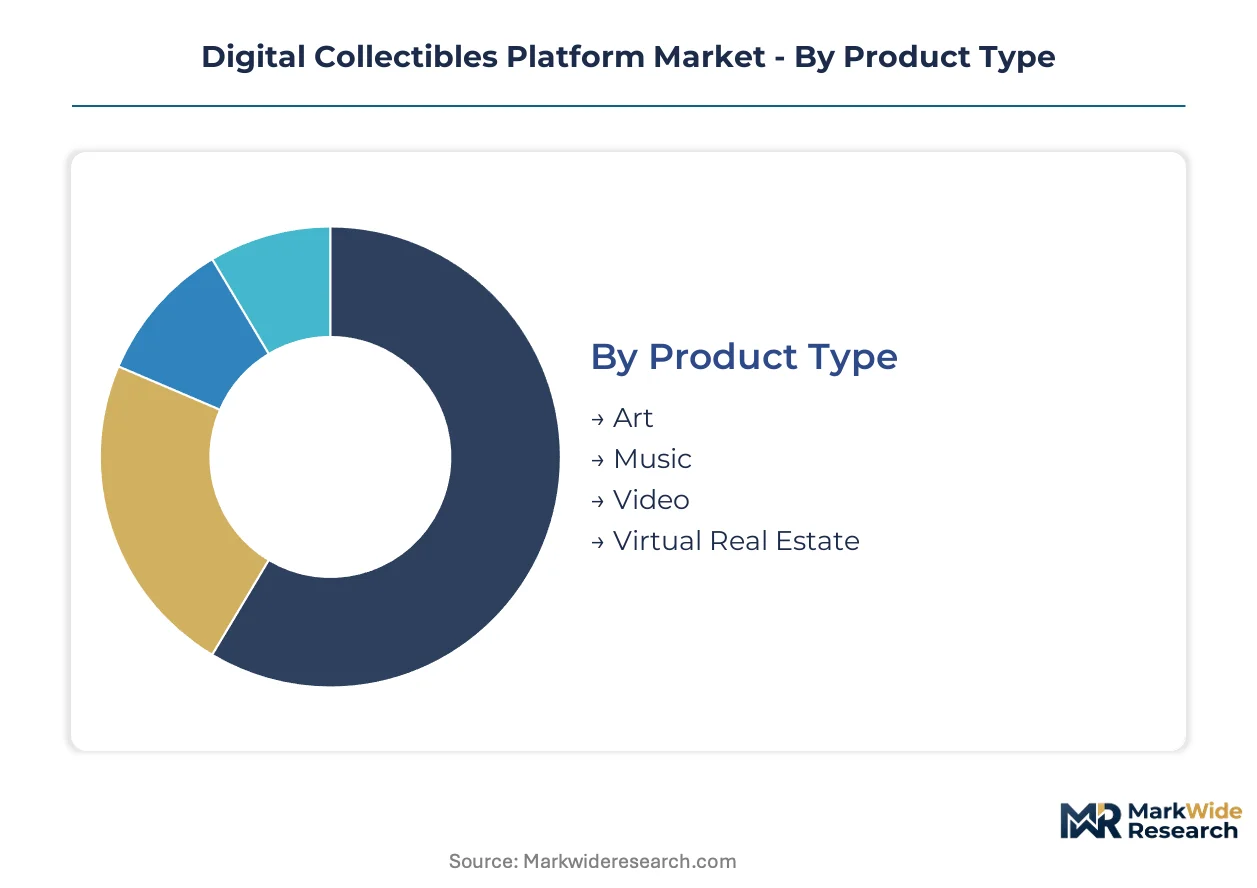
Segmentation in digital collectibles platforms reveals how value pools concentrate across distinct technical layers and user behaviors. Platform operators must align infrastructure investments with the specific custody, provenance, and liquidity requirements of each segment cluster.
Product Type:
Supply concentration in high-value categories is reshaping minting infrastructure priorities and secondary market liquidity provisioning.
- Art:Unique digital works employ ERC-721 standards with cryptographic provenance verification. Demand concentrates among ultra-high-net-worth collectors in the United States, where SEC classification uncertainty constrains fractionalized ownership models.
- Music:Tokenized royalty streams use programmable smart contracts to automate revenue distribution. Streaming-era artists in European markets under MiCA jurisdiction are adopting these structures fastest, bypassing traditional label intermediation.
- Video:Limited-edition clips and generative content leverage layer-2 scaling for cost-efficient minting at volume.
- Virtual Real Estate:Scarcity-driven land parcels in metaverse environments anchor premium transaction values through location-based utility mechanics.
Today's leader: Art. Tomorrow's challenger: Music.
Technology:
Cost tier differentiation separates enterprise-grade infrastructure from consumer-accessible tooling layers.
- Blockchain:Distributed ledger layers provide immutable transaction records and consensus-based state validation. Ethereum's proof-of-stake migration has collapsed energy costs per transaction, triggering institutional capital reallocation toward ESG-compliant infrastructure providers in Germany and Singapore.
- Smart Contracts:Self-executing code automates royalty distribution and ownership transfers without intermediary custody. Audit bottlenecks in certified security review capacity are delaying platform launch timelines across North American and Asian markets.
- Cryptography:Public-private key infrastructure secures wallet access and transaction signing.
- NFT Standards:ERC-721 and ERC-1155 token specifications ensure interoperability across marketplaces and wallets.
Blockchain dominates current infrastructure spending. Smart contracts are gaining share fastest as programmable utility replaces speculative holding.
End User:
Customer type fragmentation demands distinct onboarding flows and custody solutions across behavioral segments.
- Collectors:Provenance-focused buyers prioritize authenticated scarcity and exhibition utility. Self-custody key management complexity limits mainstream conversion rates in Japan and Australia, where regulatory clarity around consumer protection remains under active central bank review.
- Investors:Financial return-oriented participants seek secondary market liquidity and price appreciation. Tax reporting requirements across European jurisdictions under CSRD disclosure mandates are reshaping portfolio tracking tool demand.
- Gamers:Play-to-earn participants integrate collectibles as functional in-game assets.
- Creators:Primary issuers require low-friction minting tools with embedded royalty programming.
Collectors anchor current transaction volume. Investors are expanding most quickly as institutional custody solutions mature.
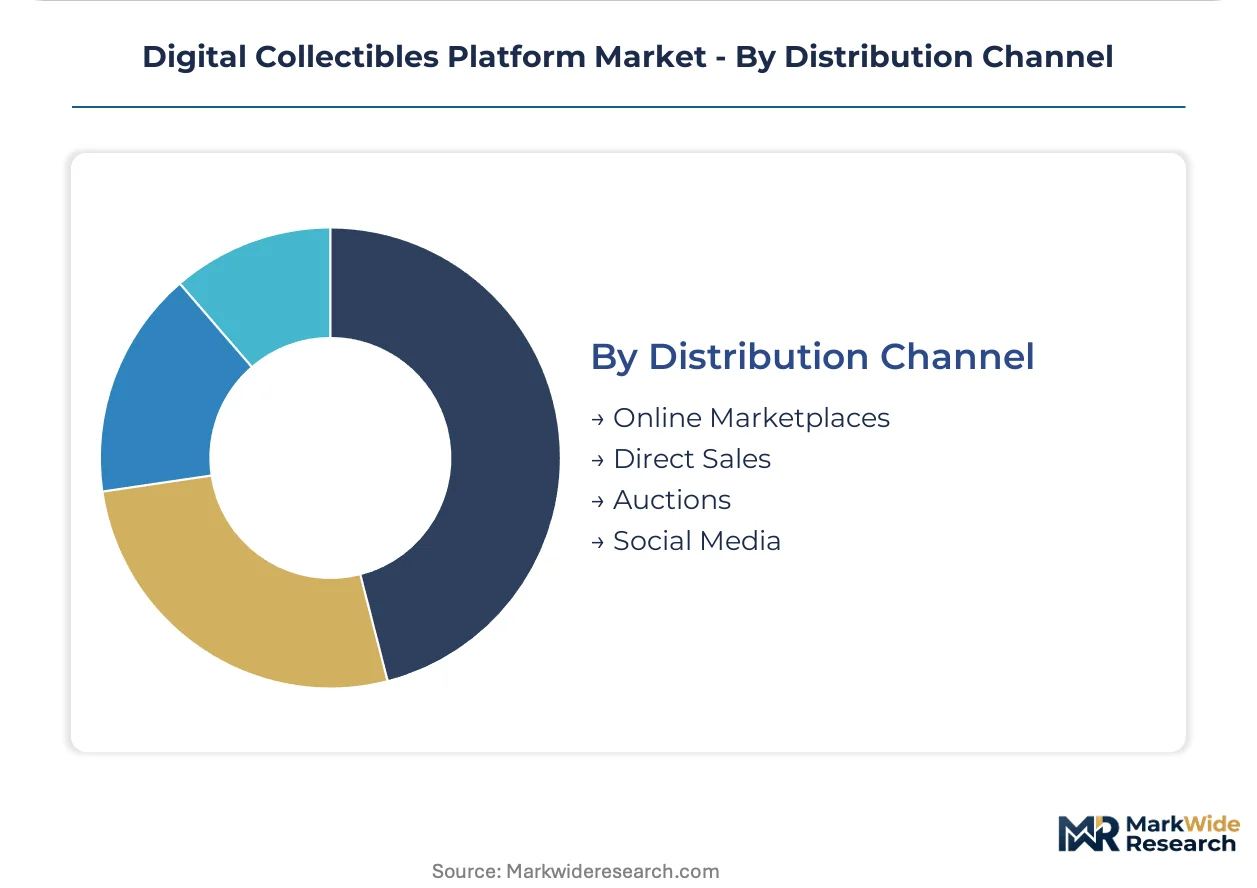
Distribution Channel:
Margin structure varies sharply between intermediated marketplace fees and direct creator-audience relationships.
- Online Marketplaces:Aggregated liquidity platforms capture recurring protocol fees regardless of secondary price performance. Multi-chain listing support in United States-accessible platforms is concentrating liquidity depth among top-tier exchanges facing dual SEC-CFTC compliance architectures.
- Direct Sales:Creator-controlled distribution eliminates intermediary take rates. White-label minting tools embedded in sports franchise mobile applications in Spain and Italy are bypassing standalone marketplace competition through gated fan engagement mechanics.
- Auctions:Price discovery mechanisms serve high-value unique works with transparent bidding histories.
- Social Media:Native platform integration reduces wallet onboarding friction through familiar interfaces.
Online marketplaces dominate fee capture today. Direct sales are climbing the fastest as enterprise embedding accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital flows into blockchain infrastructure startups are reshaping platform development trajectories across multiple jurisdictions. Regulatory fragmentation between securities and commodities classifications creates divergent compliance architectures. Energy cost differentials and licensing clarity determine where minting infrastructure concentrates.
United States
Sports franchises in Dallas and Miami are deploying tokenized fan engagement programs at scale. SEC enforcement actions against unregistered token offerings force dual compliance stacks separating securities-like offerings from utility collectibles. New York and California anchor institutional custody solution development as ESG-conscious buyers demand proof-of-stake validation.
Germany
ESG-mandated institutional capital is reallocating toward carbon-neutral minting infrastructure. BaFin licensing requirements under MiCA framework provisions force custody and disclosure upgrades for marketplace operators. Berlin and Munich clusters host layer-2 scaling startups serving European football club collectible drops.
Singapore
Family office capital is concentrating in blockchain infrastructure funds with ESG screening mandates. Monetary Authority of Singapore digital asset licensing provides regulatory clarity absent in Western jurisdictions. The city-state's fintech cluster attracts platform operators seeking stable compliance environments for Asian market access.
India
Domestic streaming artists are adopting tokenized royalty structures to bypass label intermediation. PLI scheme incentives for blockchain infrastructure position the country as a low-cost minting alternative to Ethereum mainnet congestion. Bangalore and Hyderabad clusters develop white-label wallet solutions for enterprise embedding.
United Arab Emirates
Virtual real estate developers in Dubai are anchoring premium transaction values through location-based scarcity mechanics. VARA licensing framework attracts platform operators seeking regulatory safe harbors for metaverse asset trading. The emirate's free zone clusters host custody providers serving Gulf sovereign wealth fund mandates.
Digital Collectibles Platform Market Competitive Landscape
Global majors compete with regional champions across infrastructure layers and licensing jurisdictions. The vendor base separates into three tiers: proprietary blockchain operators, multi-chain liquidity aggregators, and embedded enterprise tooling providers. Strategic archetypes include sports-licensed drop specialists, carbon-verified minting platforms, and white-label wallet integrators. Dominant competitive moves encompass MiCA compliance architecture investments and layer-2 rollup deployments for cost-efficient high-frequency releases.
Within the proprietary infrastructure tier, Dapper Labs and Venly exemplify divergent embedding strategies. Dapper Labs occupies a position as a sports-licensed drop specialist with captive blockchain economics. Venly sits within the enterprise tooling archetype, representing white-label wallet integration for franchise mobile applications. OpenSea anchors the multi-chain liquidity aggregator position, capturing protocol fees across secondary market transactions regardless of price performance.
| Leading Market Players |
|---|
| Vulcan Forged |
| Rally |
| Dapper Labs |
| Sweet |
| Venly |
| Whatnot |
| TCGplayer |
| GameSquare |
| OpenSea |
| Others |
Pricing and Supply Chain Analysis
Institutional custody buyers in Germany and Singapore anchor pricing power toward carbon-verified minting tiers, locking in premium fee structures for ESG-compliant infrastructure while compressing margins on unverified layer-1 alternatives.
Pricing Analysis
Gas fee volatility on Ethereum mainnet passes directly into minting cost structures, forcing platforms toward layer-2 rollups for cost containment. Three-tier pricing separates premium carbon-offset verified drops from standard proof-of-stake releases and economy-grade bulk minting on congested mainnet. Pricing pressure stems from India's PLI-subsidized infrastructure undercutting Western layer-1 costs. Sports franchises with high-frequency drop schedules exhibit lowest price sensitivity; independent creators in European markets under MiCA disclosure mandates show highest.
Supply Chain Analysis
ISO interoperability certification gates access to enterprise-grade platform deployments, concentrating qualified infrastructure supply in Singapore, Germany, and the United States. Smart contract audit capacity and layer-2 rollup development draw from certified security review pools and zero-knowledge proof engineering clusters. Single-source vulnerability sits with Ethereum mainnet congestion during high-demand NFT drops. Distribution runs through embedded white-label wallet integrations in franchise mobile applications and multi-chain marketplace aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory clarity into infrastructure demand, with EU MiCA framework provisions accelerating compliance architecture investments across European-accessible platforms.
For Market Incumbents: Lock in sports-licensed drop exclusivity through multi-year franchise agreements before embedded enterprise tooling providers capture mobile wallet real estate. Defend margin position by deepening layer-2 rollup deployments for cost-efficient high-frequency releases. Vertical integration into proprietary blockchain infrastructure, as Dapper Labs has executed, sustains fee advantages against multi-chain liquidity aggregators. For New Entrants and Emerging Players: Begin with white-label wallet integration for Asian esports organizations piloting fan token engagement mechanics, the most penetrable segment outside established European football and North American basketball markets. Target India's domestic streaming artists adopting tokenized royalty structures under PLI scheme incentives. A direct sales go-to-market angle through embedded minting tools bypasses standalone marketplace competition. For Investors and Strategic Acquirers: Sports franchise technology divisions are the most active acquirer in this space, consolidating fan engagement infrastructure ahead of tokenized season ticket and voting rights deployments. Long-term viability centers on platforms with multi-chain orchestration capabilities and MiCA-compliant custody architectures. The signal to watch is SEC-CFTC jurisdictional clarification triggering dual compliance stack investments among US-facing marketplaces.| Strategic Initiative | Industry Significance |
|---|---|
| Layer-2 Rollup Deployment | Sports franchises in Dallas and Miami compress minting costs for high-frequency collectible drops. |
| MiCA Compliance Architecture Investment | BaFin licensing requirements in Germany force custody and disclosure upgrades for European marketplaces. |
| Carbon Offset Verification Layer Integration | ESG-mandated institutional capital in Singapore reallocates toward real-time emissions tracking infrastructure. |
| White-Label Wallet Embedding | Venly's enterprise tooling archetype bypasses standalone marketplace competition through franchise mobile applications. |
| Multi-Chain Liquidity Aggregation | OpenSea's protocol fee capture across secondary transactions anchors liquidity depth regardless of price performance. |
Research Methodology
Direct dialogue with platform engineering leads, sports franchise digital officers, smart contract auditors, and custody solution architects grounded the qualitative foundation, cross-referenced against SEC enforcement filings, EU MiCA regulatory texts, layer-2 scaling protocol documentation, and ESG fund disclosure statements. Bottom-up transaction volume estimates from marketplace APIs and top-down infrastructure spending projections from venture capital flow data were triangulated for convergence.
Segment-level outputs across product type, technology layer, end user archetype, and distribution channel were generated through the projection horizon, with CAGRs derived from regression analysis against blockchain adoption curves and institutional custody solution penetration rates. Ethereum proof-of-stake migration timelines and MiCA implementation phases served as structural inflection inputs.
Several conditions sit outside the modeled scope, including unannounced SEC enforcement actions, layer-1 network security incidents, and sovereign cryptocurrency bans. Forecasts reflect assumptions around regulatory clarity trajectories and ESG mandate durability. A model refresh is warranted upon material change in SEC-CFTC jurisdictional classification or EU MiCA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Music NFT Market