
 Asset Tokenization Software Market | 2026-2036
Asset Tokenization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Tokenization Software Market Insights
Smart contract standards are consolidating product economics as ERC-3643 replaces legacy ERC-20 frameworks for permissioned asset tokens. Tokeny Solutions leverages its Luxembourg regulatory licenses to anchor European institutional issuance pipelines. Fireblocks sustains its position through cryptographic custody infrastructure that secures token lifecycle management. Brickken competes by specializing in no-code tokenization workflows for mid-cap real estate sponsors.
Asset tokenization software denotes platforms that encode ownership rights into cryptographically verifiable digital tokens, typically deploying smart contracts on distributed ledger networks to automate transfer restrictions, dividend distribution, and investor whitelisting. These systems serve primary industrial purposes in capital formation, secondary market liquidity provision, and automated regulatory compliance for illiquid asset classes. Real estate tokens currently occupy the largest margin pool as property sponsors seek fractional distribution channels, while equity tokens represent the fastest-growing segment as private companies explore continuous trading models outside traditional exchange frameworks. Blockchain technology underpins all functional layers, though token standards differentiate platform interoperability and jurisdictional enforceability.
The Securities and Exchange Commission shapes US market access through enforcement actions defining digital asset securities classification, while the EU's MiCA framework establishes uniform licensing requirements across member states. Singapore's Monetary Authority applies its Payment Services Act to tokenization service providers, creating a tripartite regulatory landscape that favors platforms with multi-jurisdictional compliance architecture. Stakeholders must monitor evolving custody rule interpretations and stablecoin reserve requirements, as these will determine which technology stacks achieve institutional adoption at scale.
Market Dynamics
The migration from ERC-20 to ERC-3643 smart contract standards is compressing platform differentiation and forcing vendors to rebuild compliance layers around permissioned token architectures. This technical pivot favors incumbents with regulatory licensing depth over pure-play technology providers.
Growth Catalysts
- MiCA Licensing Framework:The EU's Markets in Crypto-Assets regulation creates mandatory compliance pathways that institutional issuers require. Licensed platforms in Luxembourg and Germany capture structured product pipelines from asset managers seeking regulatory certainty.
- Real Estate Sponsor Demand:Property investment trusts in the United States pursue fractional ownership vehicles to unlock retail capital. Tokenization software reduces minimum investment thresholds from $250,000 to $1,000 for commercial real estate exposure.
- Blockchain Settlement Infrastructure:Financial institutions deploy distributed ledger networks to compress T+2 settlement cycles. Custody banks integrate token lifecycle management to compete with fintech settlement providers.
Market Restraints
- Qualified Custody Rule Uncertainty:The SEC's evolving interpretation of digital asset custody requirements creates compliance friction. Banks delay tokenization product launches pending regulatory clarity on segregation and insurance standards.
- Smart Contract Audit Costs:Formal verification of permissioned token code requires specialized security firms charging $150,000-$400,000 per deployment. Mid-cap sponsors absorb this as a fixed cost barrier to entry.
- Jurisdictional Enforcement Gaps:Cross-border token transfers face conflicting property law recognition. Singapore's Payment Services Act and US securities frameworks create divergent compliance obligations for global issuers.
Strategic Opportunities
- Private Equity Continuous Trading:Unlisted companies in the United States explore tokenized share registries to enable secondary liquidity outside traditional exchange frameworks. This displaces periodic tender offer mechanisms with automated matching engines.
- Carbon Credit Tokenization:Verified emission reduction certificates migrate to programmable tokens with automated retirement logic. The EU Green Deal's carbon border adjustment mechanism accelerates demand for traceable offset instruments.
- AI-Driven Compliance Automation:Machine learning systems integrated with token platforms automate investor accreditation and transfer restriction enforcement. This convergence reduces manual KYC processing costs by 60-70 percent for high-volume issuers.
Industry Challenges
- Smart Contract Developer Scarcity:Solidity engineers with securities law fluency command premium compensation. Tokenization platforms compete with DeFi protocols and Layer-1 foundations for this constrained talent pool.
- Legacy System Integration Complexity:Banks require API bridges between token platforms and core banking systems. Custom middleware development extends implementation timelines by 8-14 months for institutional deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Tokenization Software Market |
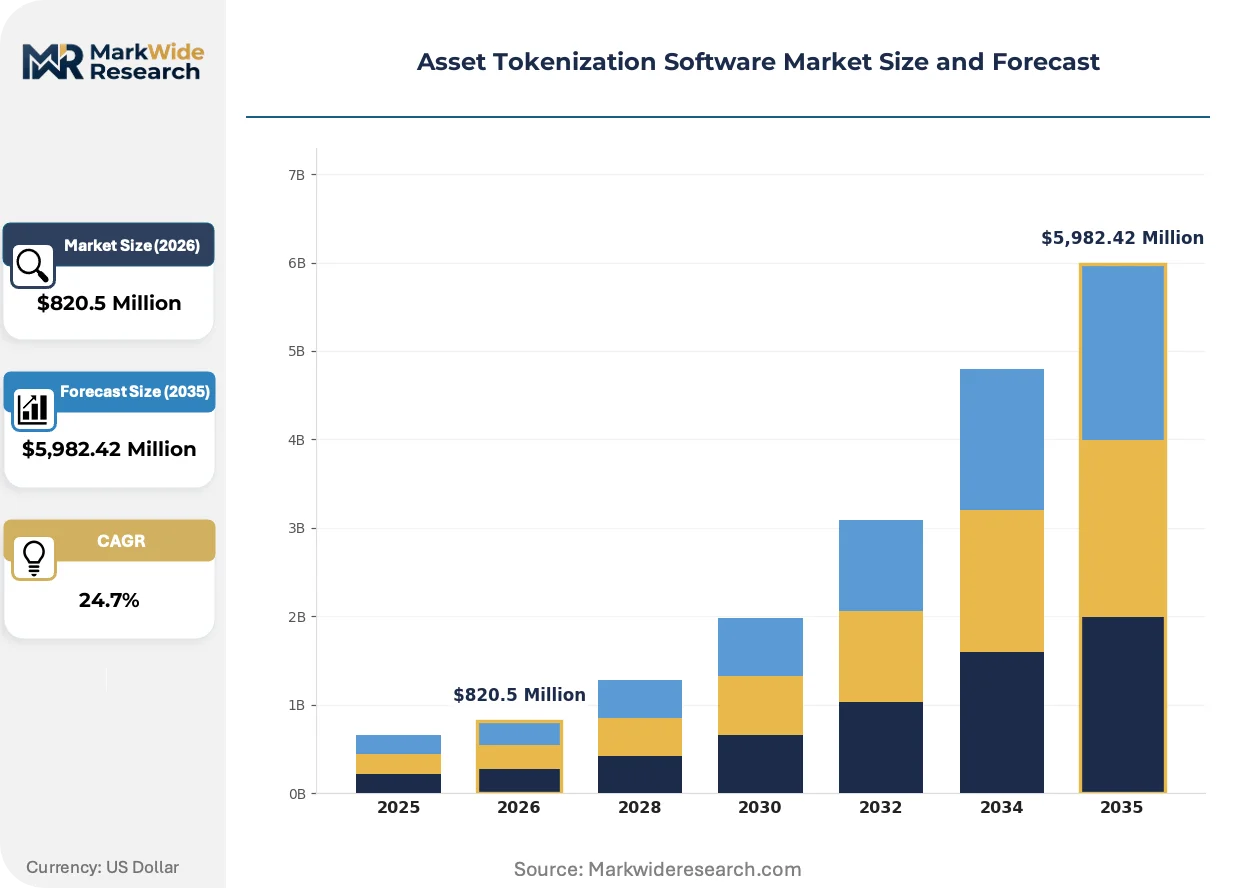
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $5,982.42 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real Estate Tokens, Art Tokens, Equity Tokens, Debt Tokens End User: Financial Institutions, Real Estate Developers, Retail Investors, Crowdfunding Platforms Technology: Blockchain, Smart Contracts, Distributed Ledger, Token Standards Use Case: Investment, Trading, Fractional Ownership, Compliance Management |
| Companies Covered | Tokeny Solutions, Brickken, InvestaX, tZERO, DigiShares, Tokensoft, Spydra, Fireblocks, Kaleido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Tokenization Software Market Trends and Innovations
Permissioned blockchain architectures are displacing public network dependencies as institutional issuers prioritize transaction privacy and regulatory control over decentralization ideals.
Zero-knowledge proof technology is modularizing compliance verification workflows. Token platforms embed zk-SNARK circuits to prove investor accreditation status without revealing underlying identity data. Swiss private banks adopt these systems to satisfy FINMA confidentiality requirements while enabling cross-border secondary trading. The structural compression enables real-time settlement without pre-trade disclosure of counterparty identities.
The EU's Digital Operational Resilience Act imposes mandatory ICT risk management frameworks on tokenization service providers. Platforms must demonstrate business continuity capabilities including 24-hour recovery time objectives for critical token registry functions. German asset servicers invest in redundant node infrastructure across Frankfurt, Luxembourg, and Zurich to satisfy DORA's geographic distribution requirements.
Institutional procurement of tokenization software is consolidating around bundled custody-compliance-issuance suites. Single-vendor relationships displace best-of-breed component assembly as risk committees prefer unified liability structures. This preference shift is most visible among US-regulated investment advisers managing over $1 billion in tokenized assets, where operational due diligence costs favor integrated platform contracts over fragmented vendor management.
Asset Tokenization Software Market Segmentation
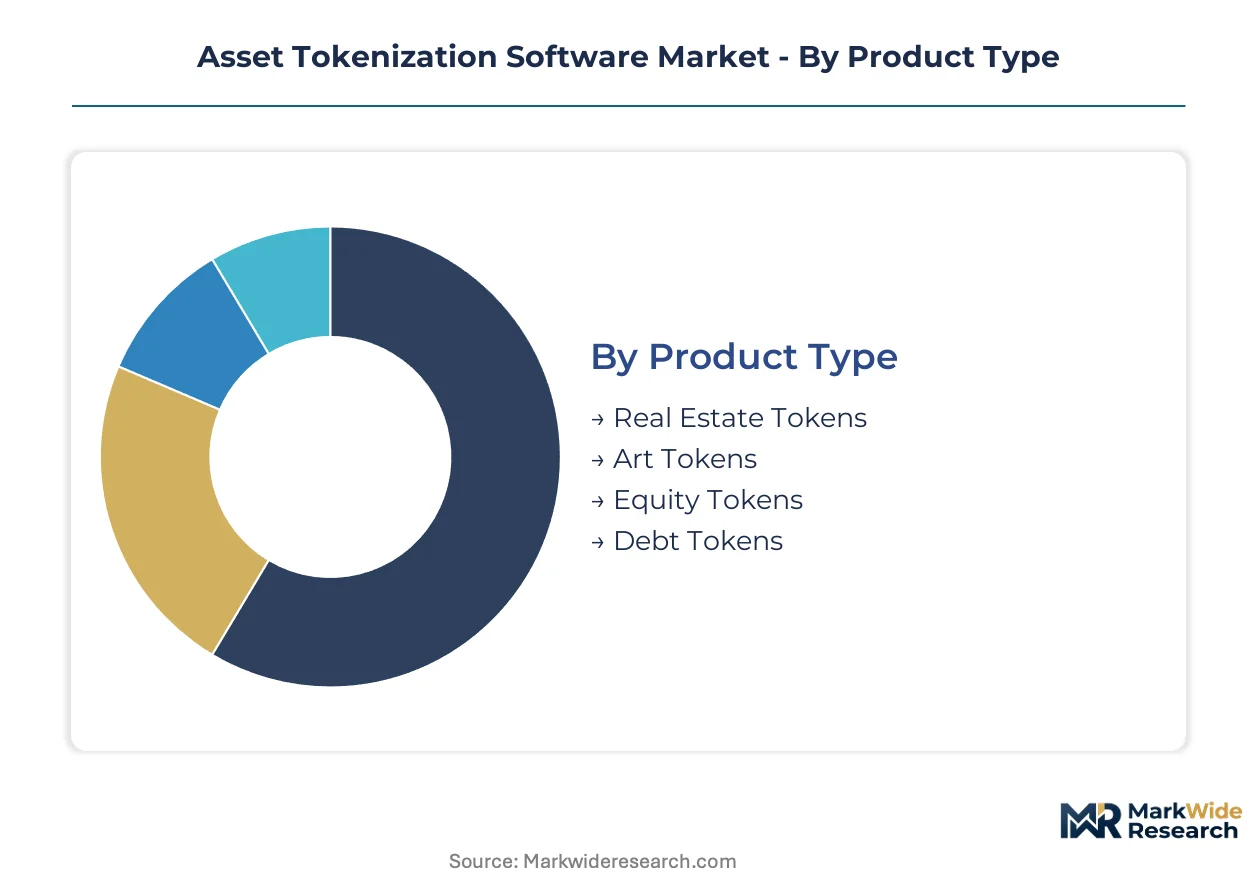
Segmentation in asset tokenization software reveals how platform architecture aligns with asset class liquidity profiles and regulatory treatment. Product type determines smart contract complexity, while end user selection shapes compliance automation requirements.
Product Type:
Real estate tokens function as standalone issuance systems requiring extensive KYC integration, while art and collectibles tokens embed within existing marketplace infrastructure with lighter compliance layers.
- Real Estate Tokens:Encode fractional property ownership with automated dividend distribution and transfer restriction enforcement. Demand concentrates among United States REITs seeking retail capital access; Luxembourg's MiCA licensing framework accelerates European institutional adoption.
- Equity Tokens:Represent private company shares with programmable governance rights and continuous trading capabilities. United States venture-backed firms drive issuance volume; SEC qualified custody uncertainty constrains bank distribution partnerships.
- Art Tokens:Fractionalize blue-chip physical and digital artwork ownership through non-fungible and fungible token structures. Swiss private banks and Dubai wealth platforms anchor primary demand.
- Debt Tokens:Tokenize fixed-income instruments with automated coupon payment and maturity redemption logic. German automotive suppliers and Singapore trade finance platforms lead commercial deployment.
Real estate tokens lead volumes today; equity tokens are gaining share fastest.
End User:
Financial institutions absorb the highest per-seat licensing costs, while retail-facing platforms prioritize volume-scalable transaction pricing.
- Financial Institutions:Custody banks and asset managers deploy tokenization infrastructure for structured product distribution. Singapore's Payment Services Act licensing requirements favor incumbent institutions with existing compliance architecture.
- Crowdfunding Platforms:Mid-cap real estate and startup equity portals integrate white-label tokenization modules. United Kingdom and German platforms drive European volume; regulatory divergence across EU member states fragments vendor selection.
- Real Estate Developers:Commercial property sponsors tokenize development equity and rental income streams. Australian and Canadian metropolitan developers lead adoption outside the United States.
- Retail Investors:Individual participants access fractional positions through platform-aggregated interfaces. Minimum investment threshold compression from $250,000 to $1,000 unlocks mass-market participation.
Financial institutions dominate current revenue; crowdfunding platforms are expanding most quickly.
Technology:
Public blockchain dependencies are contracting as permissioned architectures capture institutional procurement.
- Smart Contracts:Self-executing code automates transfer restrictions, dividend distribution, and investor whitelisting. ERC-3643 standard adoption displaces legacy ERC-20 frameworks for permissioned asset issuance.
- Token Standards:Technical specifications define interoperability, compliance hooks, and jurisdictional enforceability. Security token standards with built-in identity verification gain preference over fungible token templates.
- Blockchain:Distributed ledger networks provide immutable transaction records and cryptographic settlement finality. Enterprise-grade permissioned chains displace public network dependencies for institutional issuers.
- Distributed Ledger:Consensus mechanisms synchronize token ownership records across network participants. Private deployment models satisfy EU Digital Operational Resilience Act geographic distribution requirements.
Smart contracts anchor platform differentiation today; token standards are climbing the fastest as standardization compresses vendor moats.
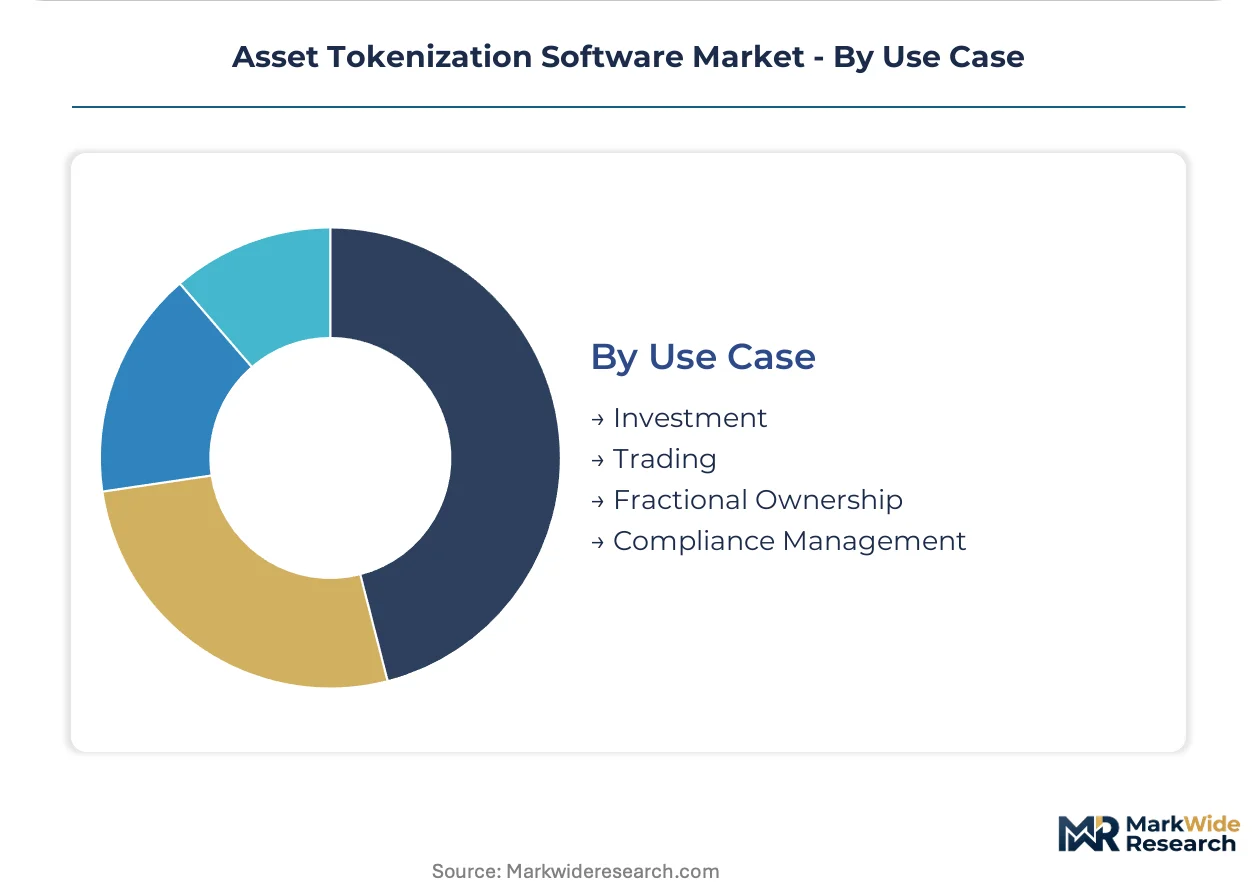
Use Case:
Primary issuance applications command higher platform fees than secondary trading infrastructure.
- Investment:Capital formation workflows encompass token minting, investor onboarding, and primary distribution. United States private equity sponsors and European renewable energy developers drive pipeline volume.
- Compliance Management:Automated regulatory adherence embeds KYC, AML, and transfer restriction enforcement into token logic. MiCA's uniform licensing requirements favor platforms with pre-built compliance modules.
- Fractional Ownership:Division of high-value assets into tradeable units democratizes access to previously illiquid categories. Commercial real estate and fine art applications dominate current deployment.
- Trading:Secondary market liquidity provision enables price discovery and position exit outside traditional exchange frameworks. Automated market maker integration and peer-to-peer matching engines compete for transaction flow.
Investment use cases generate the highest platform fees today; compliance management is seeing the steepest expansion trajectory as regulatory obligations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxembourg's regulatory licensing cluster anchors European institutional tokenization pipelines, while jurisdictional competition for digital asset frameworks intensifies across financial centers seeking to capture structured product issuance volume.
United States
REIT sponsors and private equity firms drive demand for fractional ownership vehicles that compress minimum investment thresholds. The SEC's qualified custody rule interpretations create compliance friction that delays bank product launches. New York and Miami financial clusters concentrate platform development activity for institutional distribution partnerships.
Germany
Automotive suppliers and renewable energy developers tokenize debt instruments and project equity for retail capital access. The EU's Digital Operational Resilience Act mandates geographic redundancy for token registry infrastructure. Frankfurt and Munich host redundant node deployments satisfying recovery time objectives for critical custody functions.
Singapore
Trade finance platforms and wealth management institutions deploy tokenization for cross-border settlement compression. The Monetary Authority's Payment Services Act licensing framework favors incumbent institutions with existing compliance architecture. The city-state's fintech cluster attracts regional headquarters for Asia-Pacific issuance pipelines.
Switzerland
Private banks adopt zero-knowledge proof systems to satisfy FINMA confidentiality requirements while enabling secondary trading. Swissmedic and financial regulator coordination shapes digital asset securities classification for wealth management products. Zurich and Geneva anchor custody infrastructure development for ultra-high-net-worth tokenized portfolios.
United Arab Emirates
Real estate developers and sovereign wealth vehicles explore tokenized development equity for international retail distribution. The Dubai International Financial Centre's digital asset framework competes with Abu Dhabi's regulatory sandbox for issuance volume. The Emirates' tax-neutral structuring attracts Middle East and Africa regional tokenization headquarters.
Asset Tokenization Software Market Competitive Landscape
Global majors compete with regional champions across regulatory licensing depth, creating a tiered structure where compliance architecture separates sustainable platforms from technology-only providers. The vendor base stratifies between custody-integrated suites and specialized issuance modules. Three archetypes dominate: licensed infrastructure providers, no-code workflow specialists, and cryptographic custody platforms. Consolidation pressures favor unified liability structures over fragmented vendor management, while multi-jurisdictional licensing emerges as the primary defensive moat.
Within the licensed infrastructure tier, Tokeny Solutions exemplifies European regulatory anchoring through Luxembourg financial authority permissions. Fireblocks occupies a position emphasizing cryptographic custody infrastructure for token lifecycle security. Brickken represents the no-code specialization vector targeting mid-cap real estate sponsors with simplified issuance workflows. These three patterns illustrate how compliance depth, technical infrastructure, and workflow accessibility define competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Tokeny Solutions |
| Brickken |
| InvestaX |
| tZERO |
| DigiShares |
| Tokensoft |
| Spydra |
| Fireblocks |
| Kaleido |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between MiCA-licensed infrastructure suites and unlicensed technology modules manifests in both pricing premiums and supply chain qualification requirements. Licensed platforms in Luxembourg and Germany command subscription tiers three to four levels above commodity SaaS providers, while procurement committees at US-regulated investment advisers mandate unified vendor liability structures that compress best-of-breed assembly economics.
Pricing Analysis
Input-cost pass-through from smart contract audit services drives pricing compression at the mid-market tier. Formal verification specialists charging substantial fixed fees per deployment force platform vendors to absorb or tier these costs across subscription levels. Price differentiation rests on regulatory licensing depth versus pure-play technology accessibility. Pricing pressure stems from ERC-3643 standardization homogenizing core compliance features. Financial institutions show least price sensitivity due to operational due diligence cost avoidance, while crowdfunding platforms absorb highest sensitivity as fixed audit costs consume issuance margins.
Supply Chain Analysis
Dual-sourcing requirements for cryptographic custody infrastructure mandate multi-vendor qualification across financial institutions deploying token lifecycle management. Supply concentration centers on Luxembourg, Germany, and Singapore as regulatory licensing clusters. Raw material dependencies include distributed ledger node infrastructure, zero-knowledge proof circuit libraries, and API middleware bridges to core banking systems. Supply chain risk runs through single-source vulnerability for Solidity engineering talent with securities law fluency. Distribution runs through direct enterprise sales for institutional deployments and white-label partnerships for mid-cap sponsor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in asset tokenization software hinges on compliance automation cost-down trajectories as machine learning systems displace manual KYC processing. Premium-tier consolidation around bundled custody-compliance-issuance suites captures pricing power from risk committee preferences at US-regulated investment advisers.
For Market Incumbents: Acquire regulatory licensing assets in MiCA jurisdictions to anchor European institutional issuance pipelines. Deepen cryptographic custody infrastructure partnerships to defend against fintech settlement providers encroaching on token lifecycle management. Fortify API middleware capabilities to compress the 8-14 month legacy system integration timelines that delay institutional deployments. For New Entrants and Emerging Players: Mid-cap real estate sponsors in Australian and Canadian metropolitan markets represent underserved buyer archetypes with compressed minimum investment threshold requirements. Carbon credit tokenization for EU Green Deal compliance offers penetrable white-space as verified emission reduction certificates migrate to programmable instruments. Pursue no-code workflow positioning to bypass smart contract developer scarcity constraining incumbent platform roadmaps. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdictional licensing depth separates sustainable platforms from technology-only providers facing standardization compression. Long-term viability favors vendors with unified liability structures spanning custody, compliance, and issuance functions. Watch SEC qualified custody rule interpretations as the signal indicating whether bank distribution partnerships accelerate or stall institutional procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Acquisition | Luxembourg and German regulatory permissions anchor European institutional issuance pipelines. |
| Zero-Knowledge Proof Integration | zk-SNARK circuits satisfy FINMA confidentiality requirements while enabling cross-border secondary trading. |
| AI Compliance Automation | Machine learning systems reduce manual KYC processing costs for high-volume token issuers. |
| Private Equity Continuous Trading | Tokenized share registries displace periodic tender offers with automated matching engines. |
| Carbon Credit Tokenization | Programmable tokens with automated retirement logic address EU carbon border adjustment demand. |
Research Methodology
Bottom-up financial institution and crowdfunding platform modeling reconciled against top-down blockchain infrastructure deployment tracking forms the analytical core. Primary interviews with tokenization platform CTOs, REIT sponsor capital formation officers, Luxembourg regulatory compliance leads, and Singapore wealth management technologists combined with secondary validation from SEC enforcement action filings, EU MiCA regulatory texts, and Monetary Authority of Singapore licensing registers. Bottom-up and top-down triangulation cross-checks vendor-reported deployment metrics against institutional procurement pipeline disclosures.
Input-output matrix framing connects smart contract standard adoption rates to platform revenue tier migration across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, deployment technology, and primary use case, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from license issuance velocity and institutional procurement cycle compression. Forecast inputs incorporate MiCA implementation timelines and SEC custody rule interpretation trajectories.
Underlying measurement precision varies by segment; MiCA-licensed platform deployments carry tighter precision than emerging carbon credit tokenization applications. Forecasts reflect assumptions regarding regulatory clarity timelines and smart contract audit cost trajectories. Deviation in SEC qualified custody rule finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market