
 Crustacean Market | 2026-2036
Crustacean Market Size, Share, and Industry Trends Forecast 2026-2036
Crustacean Market Intelligence
Project financing for large-scale, controlled-environment aquaculture facilities is tilting the competitive landscape toward operators with significant capital access. Thai Union Group leverages its global processing and distribution network to manage diverse supply sources. Maruha Nichiro Corporation sustains its market position through extensive R&D in aquaculture feed and disease prevention. Trident Seafoods Corporation dominates specific North American channels with its integrated wild-catch and processing operations.
Crustaceans are aquatic arthropods, distinguished by their chitinous exoskeletons, which are primarily harvested for human consumption. This category encompasses a diverse range of species, where commercial value is determined by size, texture, and origin. Shrimp represents the largest species segment by volume, while high-value species like lobster command premium pricing. The frozen product form facilitates global trade and dominates supply chains, supplying both food service and retail packaging applications.
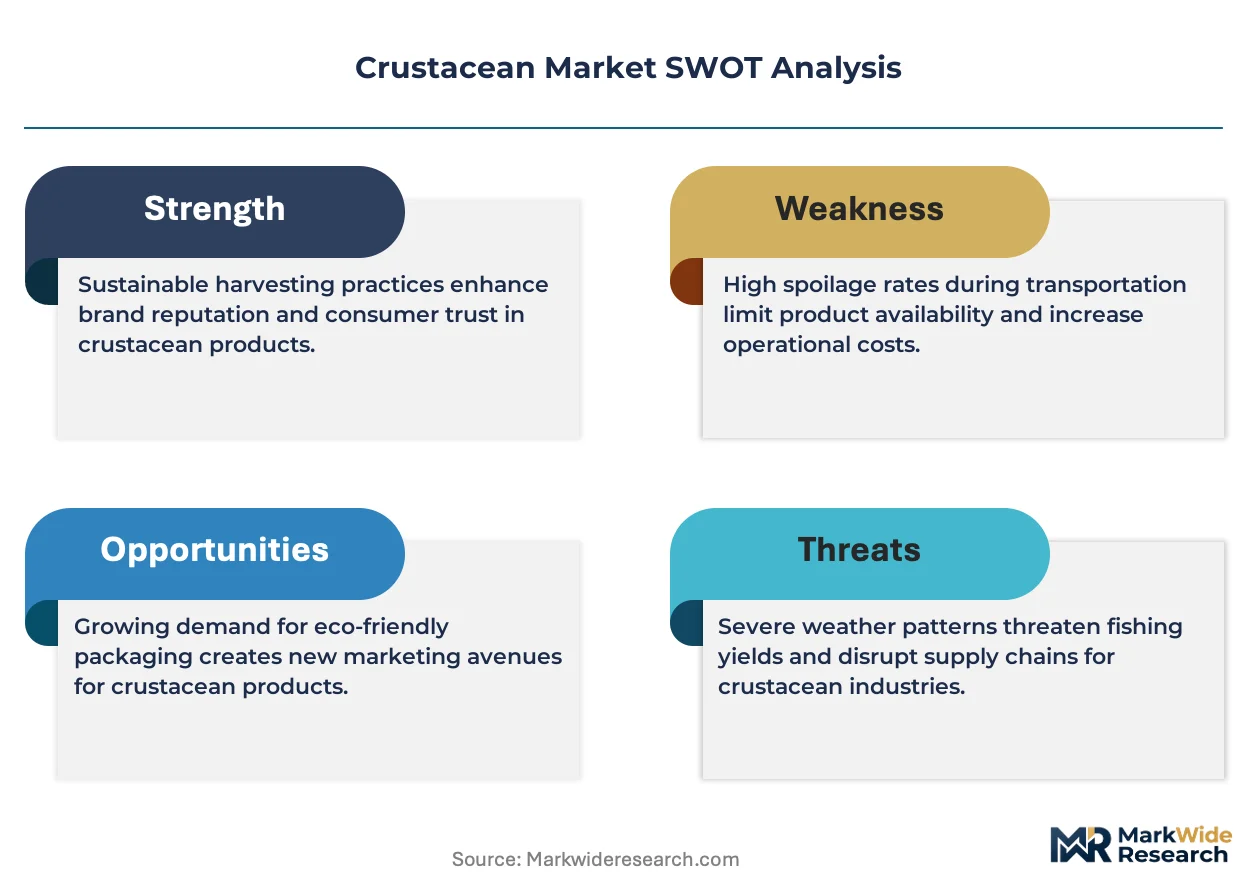
Market access is governed by stringent food safety and import regulations, including the U.S. FDA's Hazard Analysis Critical Control Point (HACCP) system. In parallel, the European Union's traceability requirements under the Common Fisheries Policy and China's SAMR standards dictate quality control protocols. Producers must therefore navigate the strategic choice between investing in sustainable wild-catch certifications and scaling capital-intensive aquaculture technologies.
Market Dynamics
The market's structure is defined by the strategic divergence between capital-intensive recirculating aquaculture systems and certified sustainable wild-catch fisheries. This split dictates investment profiles, supply chain resilience, and access to regulatory-gated markets across the globe.
Growth Catalysts
- Recirculating Aquaculture Systems:Advances in RAS technology improve production yields and environmental control, enabling higher-density farming of species like shrimp and lobster closer to urban consumption centers.
- Food Service Sector Expansion:Rising disposable incomes in China and Southeast Asia are driving significant consumption volume in the food service channel, particularly for premium species like lobster and king crab.
- Sustainable Sourcing Mandates:Consumer and retailer preference for certified products, such as those meeting Marine Stewardship Council standards, creates a price premium and expands market access in Europe and North America.
Market Restraints
- Feed Cost Volatility:Dependence on fishmeal and soy for aquaculture feed creates exposure to commodity price fluctuations, compressing producer margins for high-volume shrimp farming.
- Aquaculture Disease Outbreaks:Pathogens like White Spot Syndrome Virus in shrimp farming pose a persistent threat to production volumes, causing supply chain disruptions and financial losses for producers in key Asian hubs.
- Stringent Import Controls:Navigating complex regulations, such as the U.S. FDA's HACCP and the EU's traceability rules under the Common Fisheries Policy, acts as a significant barrier for smaller exporters.
Strategic Opportunities
- Cellular Aquaculture Development:Investment in cellular-based crustacean meat offers a path to bypass traditional supply chain constraints and address sustainability concerns in developed markets, especially for shrimp.
- Underdeveloped African Markets:Rising middle-class populations in countries like Nigeria and South Africa present untapped markets for frozen and value-added crustacean products, currently served by limited local supply.
- Value-Added Product Forms:The development of pre-marinated, cooked, or meal-kit crustacean products caters to consumer demand for convenience in North American and European retail channels, creating higher-margin opportunities.
Industry Challenges
- High Capital for RAS Facilities:The significant upfront investment required for large-scale, controlled-environment aquaculture facilities limits market entry to well-capitalized operators and creates a competitive disadvantage for smaller producers.
- Certification Complexity:Obtaining and maintaining sustainability certifications like Best Aquaculture Practices or Aquaculture Stewardship Council involves costly audits and operational changes, challenging smaller-scale farmers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crustacean Market |
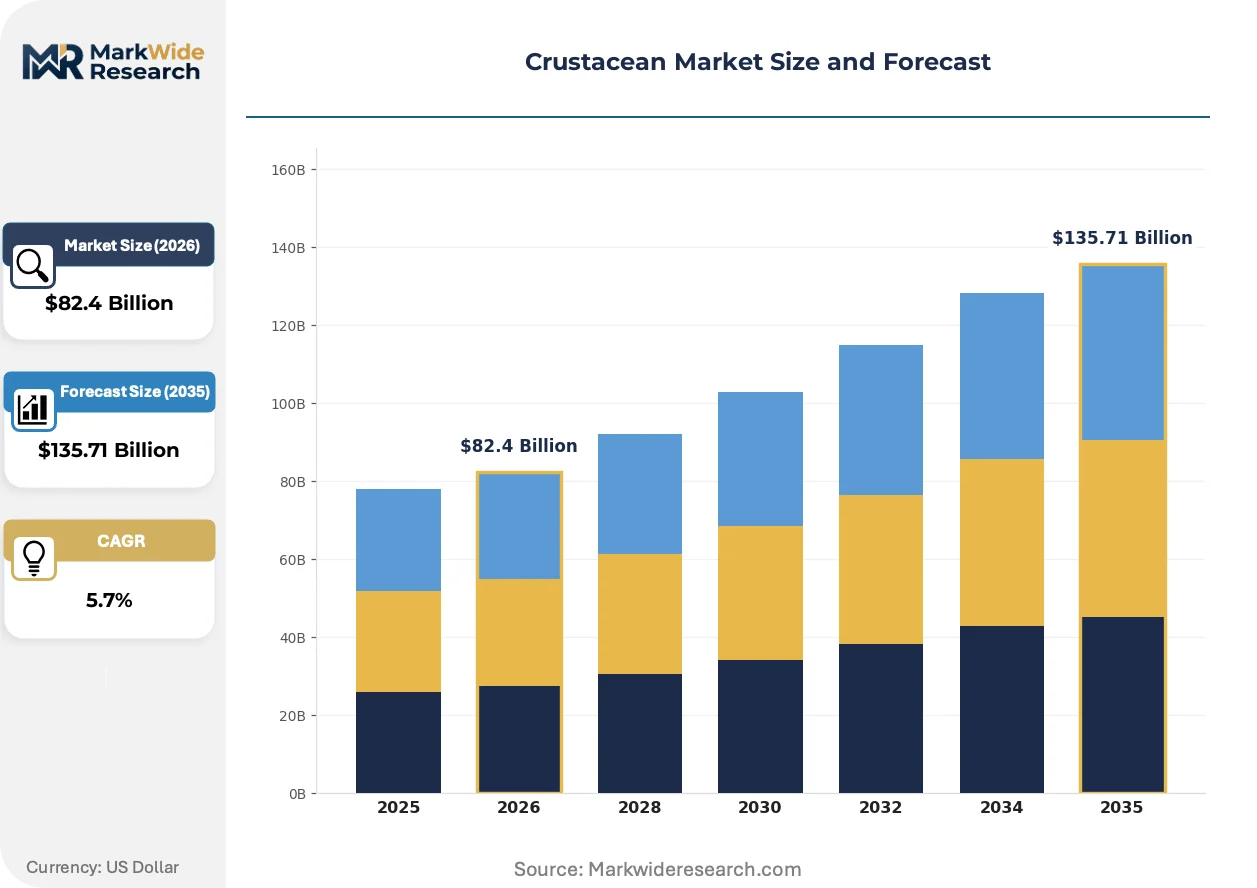
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $135.71 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Species: Shrimp, Lobster, Crab, Prawn, Krill Product Form: Fresh, Frozen, Cooked, Dried, Canned Application: Food Service, Retail Packaging, Seafood Processing, Pharmaceutical Extraction, Nutraceuticals Customer Type: Seafood Wholesalers, Exporters, Food Manufacturers, Research Institutions, Cosmetic Producers |
| Companies Covered | Clearwater Seafoods, Pacific Seafood Group, Thai Union Group, Nippon Suisan Kaisha, Maruha Nichiro Corporation, Phillips Foods, Inc., Trident Seafoods Corporation, Aqua Star Corp., High Liner Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crustacean Market Strategic Shifts & Innovations
Digitalization of the supply chain introduces new levels of precision and transparency. The integration of sensor data with production management platforms is enabling predictive analytics for feed optimization and disease prevention in aquaculture.
AI-powered imaging and sensor technology provides real-time monitoring of water quality, biomass, and animal health in aquaculture tanks. Food service and large-scale aquaculture operators are the primary adopters, seeking to optimize input costs and reduce mortality rates. This technology is virtualizing farm management, allowing remote oversight and automated adjustments to environmental parameters, which decentralizes operational expertise.
The European Union's enhanced traceability requirements under the Common Fisheries Policy mandate detailed documentation from catch to final sale. This forces producers and importers to invest in robust tracking systems, often blockchain-based, to ensure compliance. The shrimp and lobster segments, which have complex supply chains originating in Asia and the Americas, are most affected by these stringent documentation rules.
Consumer purchasing decisions are increasingly influenced by provenance and sustainability narratives, shifting value away from commodity products. This is disrupting traditional retail channels, where private-label brands now compete by offering QR-code-enabled traceability back to the specific farm or vessel. This shift is most pronounced in European retail markets, particularly in Germany and France, for frozen shrimp products.
Crustacean Market Segmentation
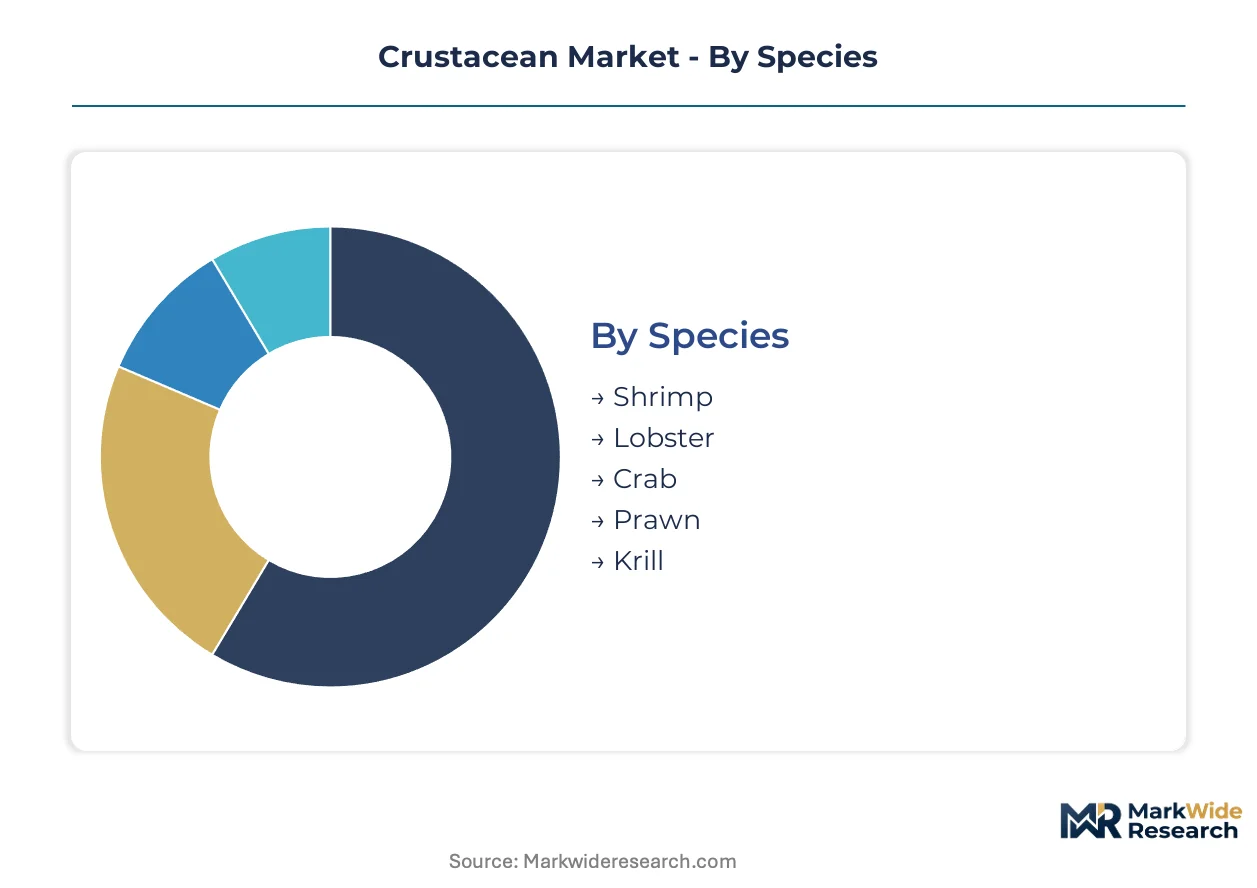
The Crustacean Market is broadly segmented to reflect the diverse biological characteristics, processing stages, and end-user applications that define its commercial landscape. Understanding these segments is critical for identifying specific market dynamics, supply chain concentrations, and emerging demand patterns across different product categories.
Species:
The crustacean species market exhibits a varied maturity spectrum, from established staples to emerging niche products.
- Shrimp:These decapod crustaceans, available in diverse sizes, are extensively farmed globally. Shrimp dominates food service consumption in China and Southeast Asia, driven by its culinary versatility and widespread appeal.
- Lobster:Large marine crustaceans, prized for their firm, sweet meat, are a premium offering. Lobster commands high pricing in North American and European fine dining sectors, supported by affluent consumer preferences.
- Crab:Valued for its delicate meat, crab is popular in Asian and North American culinary traditions.
- Prawn:Often confused with shrimp, these are specifically large, swimming decapods primarily used for culinary purposes.
- Krill:Small crustaceans, primarily harvested for aquaculture feed and nutraceutical extraction.
Shrimp handles the majority of throughput; Krill is the fastest mover on share.
Product Form:
Product form segmentation reflects distinct supply chain concentrations and consumer utility.
- Frozen:Crustaceans preserved at sub-zero temperatures maintain texture and flavor for extended periods. Frozen products facilitate global trade routes, supplying both food service and retail channels across Europe.
- Cooked:Pre-processed crustaceans, often steamed or boiled, are ready for immediate consumption. Cooked forms cater to convenience-driven consumers in North American and European retail, reducing preparation time.
- Fresh:These short shelf-life products primarily serve local and high-end restaurant markets.
- Dried:A shelf-stable product, dried crustaceans are used in Asian culinary traditions and various snack applications.
- Canned:Preserved crustacean meat offers extended shelf life for retail and pantry stocking.
Frozen products underpin global logistics; cooked forms are capturing greater retail shelf space.
Application:
Application categories delineate where significant crustacean volume is directed for end-use.
- Food Service:Bulk-purchased crustaceans are supplied to restaurants, hotels, and catering operations. Food service drives significant consumption volume in China and Southeast Asia, leveraging rising disposable incomes.
- Retail Packaging:Consumer-ready crustacean products, often branded and portioned, are sold directly to consumers. Retail packaging addresses convenience trends in European and North American supermarkets, offering ready-to-cook options.
- Seafood Processing:This segment utilizes raw crustacean inputs for further value-added product manufacturing.
- Pharmaceutical Extraction:Bioactive compounds like chitin are derived from crustacean shells for medical applications.
- Nutraceuticals:Crustacean components such as astaxanthin are utilized for dietary supplements and health products.
Food service consumption commands the largest share; nutraceuticals are expanding most quickly.
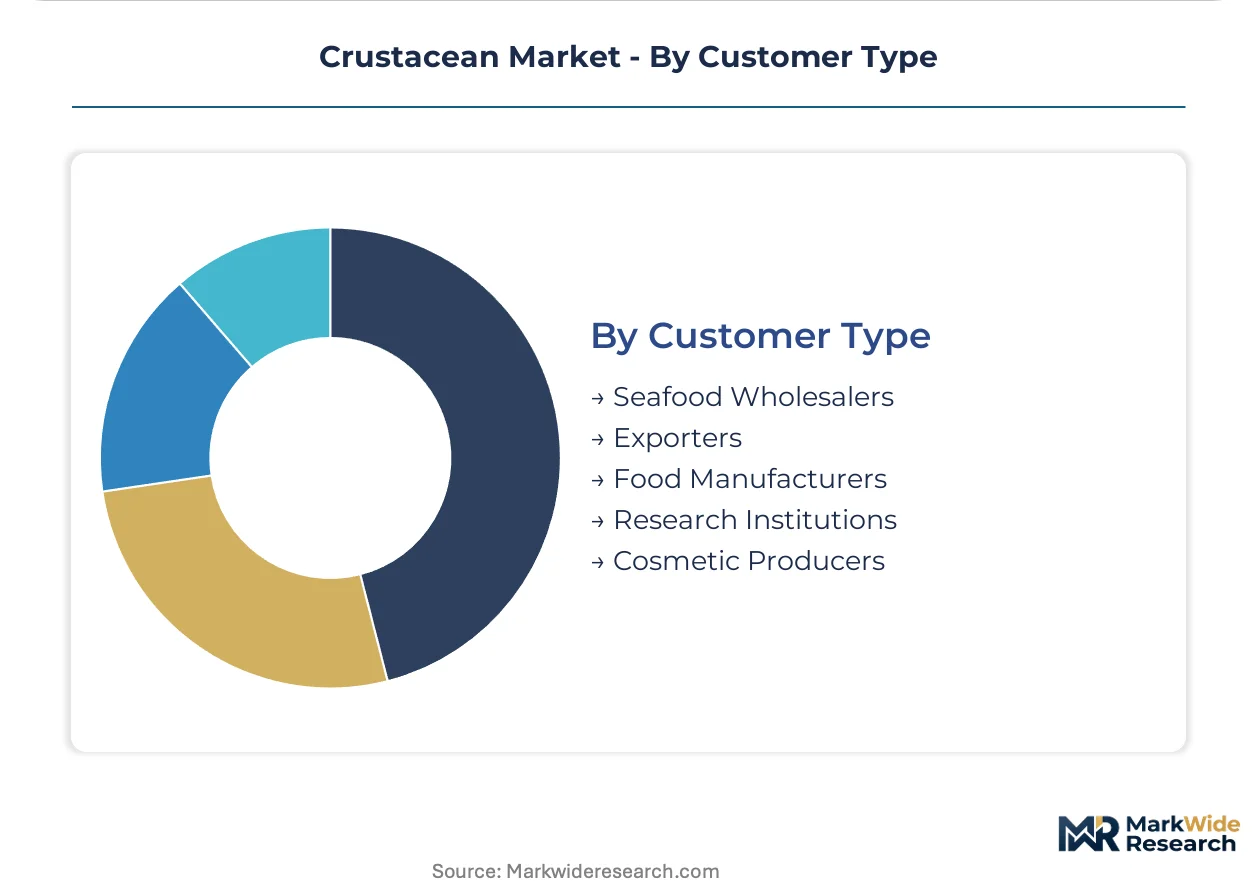
Customer Type:
Customer types reflect varying margin profiles and purchasing power within the crustacean market.
- Seafood Wholesalers:These large-volume buyers distribute crustaceans to diverse downstream clients, including restaurants and retailers. Seafood wholesalers are central to supply chain efficiency, connecting producers to fragmented market segments globally.
- Food Manufacturers:Companies acquire crustaceans as raw ingredients for processed foods, meal kits, or ready-to-eat products. Food manufacturers are driven by consumer convenience trends, integrating crustacean proteins into prepared meals in Europe.
- Exporters:Businesses specialize in cross-border trade of crustacean products, managing logistics and regulatory compliance.
- Research Institutions:Academic or private entities purchase crustaceans for scientific study, including aquaculture development.
- Cosmetic Producers:Utilize crustacean-derived ingredients like chitosan for skincare and beauty product formulations.
Seafood wholesalers form the primary distribution backbone; cosmetic producers represent a niche but growing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies promoting sustainable aquaculture and stringent food safety standards are reshaping regional market dynamics for crustaceans. These regulatory frameworks influence production methods, trade flows, and consumer access across diverse geographies. Strategic investments in processing infrastructure and cold chain logistics further support market expansion.
China
Rising disposable incomes drive significant food service consumption, particularly for shrimp and lobster. The State Administration for Market Regulation (SAMR) enforces strict quality control protocols for imported seafood. Coastal cities like Guangzhou and Shanghai are major import and processing hubs, handling large volumes.
United States
Consumer demand for convenient, value-added crustacean products supports retail growth. The U.S. FDA's Hazard Analysis Critical Control Point (HACCP) system governs import safety and domestic processing. Major ports such as Los Angeles and Seattle handle extensive crustacean imports.
Germany
European consumers increasingly prefer sustainably certified crustacean products, creating a price premium. The European Union's Common Fisheries Policy mandates enhanced traceability requirements for all seafood imports. Hamburg serves as a central European gateway for frozen seafood distribution.
Thailand
Extensive aquaculture operations, especially for shrimp, position the country as a major global exporter. The Thai Department of Fisheries implements regulations to control disease outbreaks and promote sustainable farming practices. Samut Sakhon is a key processing and export hub for shrimp products.
Japan
Culinary traditions and affluent consumers sustain demand for premium crustacean species, including crab and prawn. The Ministry of Agriculture, Forestry and Fisheries (MAFF) oversees quality standards and import regulations for seafood. Tokyo's Toyosu Market remains a central point for high-quality seafood distribution.
Crustacean Market Key Industry Players
Channel-controlling players compete with product-specialist players, defining the crustacean market's tiered structure. The competitive landscape features large integrated seafood companies alongside specialized aquaculture producers and regional distributors. Archetypes include global processing giants, niche high-value species suppliers, and domestic market-focused operators. Geographic expansion and strategic partnerships represent dominant competitive moves, particularly for securing diverse supply sources and market access.
Global processing giants like Thai Union Group and Japan's Maruha Nichiro Corporation exemplify players with extensive supply chains and R&D capabilities. Thai Union Group leverages its global processing and distribution network to manage diverse supply sources, underpinning its market position. Maruha Nichiro Corporation, a Japan-based entity, sustains its market presence through significant investment in aquaculture feed and disease prevention research. Trident Seafoods Corporation, operating primarily from North America, anchors its position through integrated wild-catch and processing operations, serving specific regional channels. These companies collectively shape market dynamics through scale and specialized offerings.
| Leading Market Players |
|---|
| Clearwater Seafoods |
| Pacific Seafood Group |
| Thai Union Group |
| Nippon Suisan Kaisha |
| Maruha Nichiro Corporation |
| Phillips Foods, Inc. |
| Trident Seafoods Corporation |
| Aqua Star Corp. |
| High Liner Foods |
| Others |
Cost & Logistics Intelligence
Samut Sakhon's extensive shrimp processing capacity drives global crustacean pricing, influencing margins across diverse retail and food service channels. This concentration of supply in key Asian hubs directly impacts the cost structure for importers worldwide.
Pricing Analysis
Sustainability certification creates a significant price spread, influencing market access and consumer preference. The dominant pricing structure across the market is commodity spot pricing for bulk raw materials, transitioning to contract-based long-term offtake for value-added products. Price differentiation stems from quality grade, such as species origin and size, and also from certified sustainable sourcing. Pricing pressure stems from feed cost volatility, compressing producer margins in high-volume shrimp farming. Food service operators in China exhibit high price sensitivity, while European retail consumers show lower sensitivity for certified premium products.
Supply Chain Analysis
Aquaculture disease outbreaks, particularly White Spot Syndrome Virus, pose a persistent structural risk to crustacean supply. Geographic supply concentration centers in Thailand, China, and Vietnam for shrimp, while lobster supply draws heavily from North America. Raw material dependencies include fishmeal and soy for aquaculture feed, exposing producers to commodity price fluctuations. The dominant distribution model runs through seafood wholesalers, connecting producers to fragmented market segments globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crustacean market is experiencing a platform-economics inflection driven by digitalization of the supply chain, enabling new levels of precision and transparency. This shift fosters greater interoperability among producers, processors, and logistics providers.
For Market Incumbents: Pre-empt emerging cellular aquaculture technologies through strategic R&D investments and partnerships. Consolidate processing operations in key export hubs like Samut Sakhon to enhance cost efficiencies and supply chain control. This defends against margin compression from rising input costs and addresses the long-term threat of alternative protein sources.
For New Entrants and Emerging Players: Build out niche market positions by focusing on value-added product forms for convenience-driven retail channels. The most penetrable segments include pre-marinated or meal-kit crustacean products in European and North American supermarkets. A strong go-to-market angle involves leveraging QR-code-enabled traceability to differentiate products based on provenance and sustainability narratives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated seafood companies controlling both wild-catch and processing operations. Long-term viability favors entities investing in advanced recirculating aquaculture systems and cellular aquaculture. An acquisition target archetype involves mid-sized, technology-forward aquaculture firms with strong sustainability credentials. The signal to watch is successful commercialization of cellular crustacean products, indicating a disruptive shift.
| Strategic Initiative | Industry Significance |
|---|---|
| RAS Technology Investment | Improves production yields and environmental control, reducing reliance on volatile wild-catch. |
| Blockchain Traceability Implementation | Ensures compliance with EU regulations and meets consumer demand for provenance. |
| Cellular Aquaculture R&D | Bypasses traditional supply chain constraints and addresses sustainability concerns in developed markets. |
| Value-Added Product Development | Catters to consumer demand for convenience in North American and European retail. |
| Geographic Expansion into Africa | Taps into rising middle-class populations in underdeveloped markets like Nigeria and South Africa. |
Research Approach
The analysis maps crustacean sub-sectors, including shrimp farming, frozen product forms, and food service applications, each validated through extensive interviews with aquaculture operators and seafood wholesalers. Primary research encompassed conversations with food manufacturers, regulatory affairs leads, and retail category buyers. Secondary validation drew from U.S. FDA filings, EU Common Fisheries Policy reports, and trade statistics from key import/export countries. This approach ensured robust bottom-up and top-down triangulation.
Assumptions regarding technological adoption rates for RAS and consumer preference shifts for certified products were held constant across the analysis window. The analytical framework modeled segmentation dimensions including species, product form, application, customer type, and regional market dynamics. Compound annual growth rates were derived from historical data trends and projected market drivers. Industry-specific forecast inputs included feed commodity price volatility and disease outbreak frequency.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large integrated seafood companies or specialized aquaculture producers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and consumer purchasing power. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Anchovy Market
Seafood
Sea Biscuits Market
Seafood
Milkfish Market
Seafood
Fish Hydrolysate Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Canned Seafood Market
Seafood
Fish Protein Market
Seafood
Sea Bass Market
Seafood
Global Seafood Market
Seafood
Salmon Market
Seafood
Cod Fish Market
Seafood
Japan Frozen Seafood Market
Seafood
Canned Sardines Market
Seafood
Asia-Pacific Seafood Market
Seafood
Fish Maw Market
Seafood
Seafood Takeout Market