
 Sea Bass Market | 2026-2036
Sea Bass Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Bass Market Outlook
Consolidation among European food service distributors is repositioning procurement leverage toward large-scale aquaculture suppliers. Grieg Seafood leverages its Norwegian salmon expertise to extend into sea bass farming technologies. Selonda Aquaculture anchors Mediterranean production capacity with integrated hatchery-to-harvest operations in Greece. Mowi competes through its established marine protein supply chains and species diversification strategy.
Sea bass comprises marine perciform fish species within the family Moronidae, characterized by silvery elongated bodies, firm white flesh with moderate fat content, and optimal culinary preparation at internal temperatures of 57–63°C for moisture retention. Farmed sea bass dominates volume as controlled aquaculture environments yield consistent size grading and year-round availability that wild catch cannot match. Frozen product formats lead margin pools through extended shelf life and reduced spoilage risk, while vacuum packaging gains traction in retail channels by preserving texture and minimizing oxidation during distribution.
The European Commission's Common Fisheries Policy and EFSA aquaculture residue monitoring shape product standards across EU member states, while FDA seafood HACCP requirements govern United States import access through hazard control documentation. Stakeholders must monitor evolving maximum residue limit adjustments and traceability mandates that determine market entry eligibility for non-European suppliers.
Market Dynamics
EU food safety standards and the F-Gas Regulation are compressing cold-chain margins while Mediterranean aquaculture clusters in Greece, Spain, and Turkey concentrate supply expansion, reshaping procurement leverage toward integrated farm-to-retail operators.
Growth Catalysts
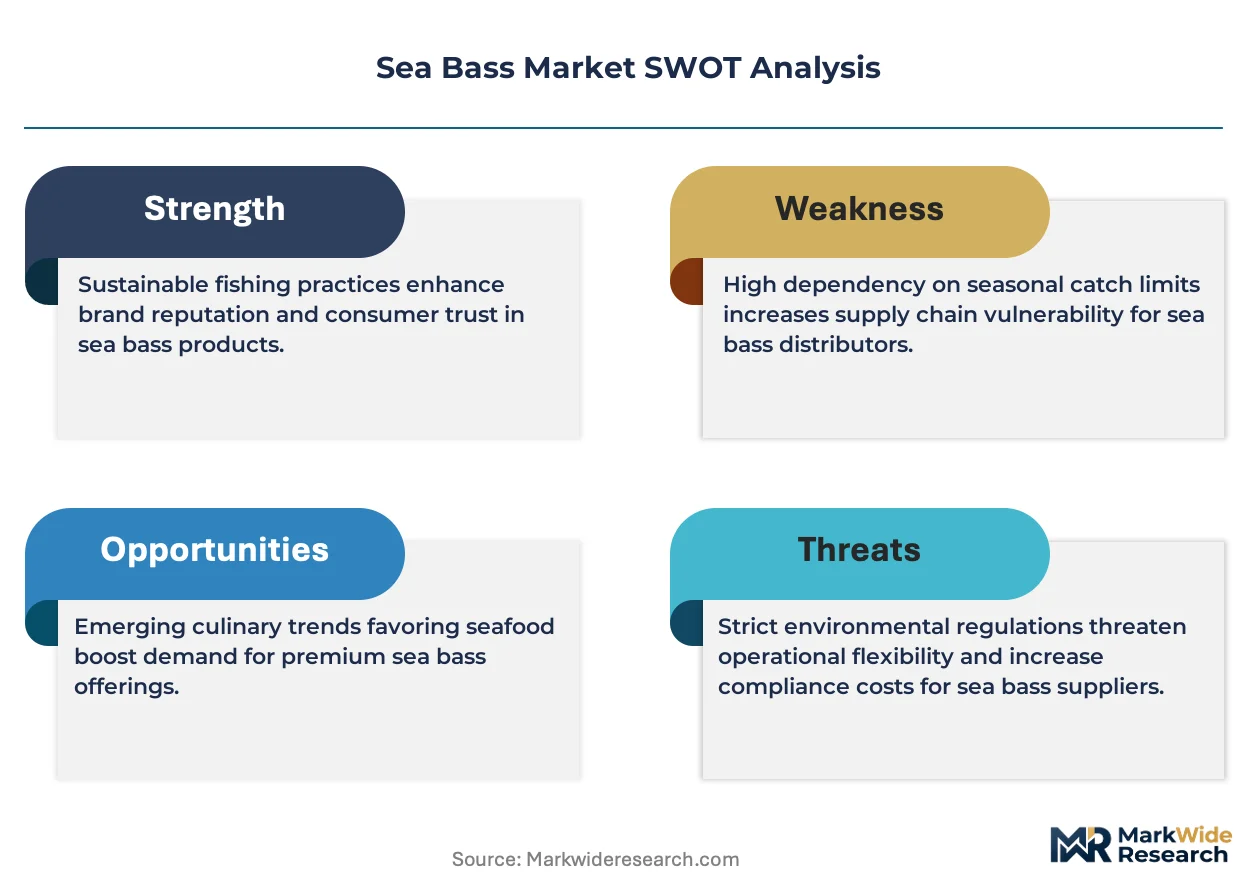
- EFSA aquaculture residue monitoring:Stringent EU testing protocols elevate farmed product premiums by certifying contaminant-free supply chains for retail and food service buyers.
- Recirculating aquaculture systems (RAS):Closed-loop water treatment technologies enable inland production facilities to bypass coastal zoning constraints and reduce disease transmission risks.
- Turkish coastal farming zones:Aegean and Mediterranean shoreline concessions expand year-round grow-out capacity with lower labor costs than EU member state operations.
Market Restraints
- F-Gas Regulation phase-down:EU-mandated hydrofluorocarbon reduction raises refrigeration equipment retrofit costs for processing and distribution facilities.
- Feed input cost volatility:Fishmeal and fish oil price swings tied to Peruvian anchovy harvest variability compress farming margins during El Niño cycles.
- Wild catch substitution:Lower-priced wild Mediterranean sea bream and meagre compete in food service channels where species flexibility exists.
Strategic Opportunities
- Carbon footprint labeling mandates:EU Green Deal requirements for environmental product declarations create first-mover advantage for farms with verified low-emission RAS operations.
- Direct-to-retailer frozen contracts:Bypassing traditional auction markets through long-term supply agreements with supermarket chains stabilizes revenue visibility.
- Hybrid solar-diesel hatcheries:Photovoltaic integration with backup generation reduces energy cost exposure in Greek and Spanish breeding facilities.
Industry Challenges
- Veterinary specialist scarcity:Qualified fish health professionals command premium compensation in isolated coastal farming regions, constraining expansion timelines.
- Traceability system integration:Merging farm-level data with EU-wide blockchain tracking platforms requires capital outlays for sensor deployment and software licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Bass Market |
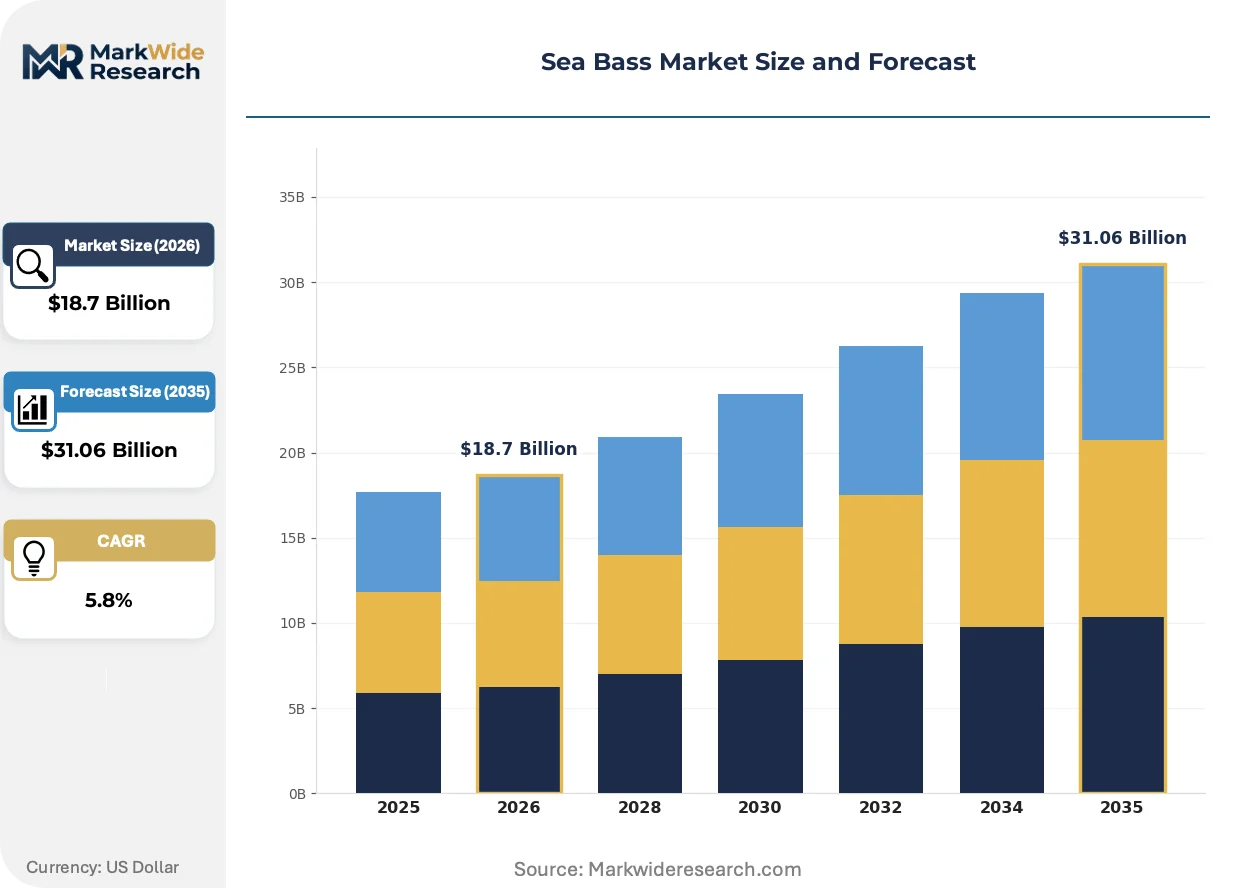
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farmed, Wild Caught, Fresh, Frozen Distribution Channel: Retail, Food Service, Direct Sales, Online Packaging Type: Tray, Vacuum Pack, Canned, Bulk End User: Households, Restaurants, Catering Services, Exporters |
| Companies Covered | American Seafoods Group, Grieg Seafood, Selonda Aquaculture, Vinh Hoan, SalMar, Lerøy Seafood Group, Cermaq, Bakkafrost, Mowi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Bass Market Strategic Shifts
Processing automation and alternative protein feed formulations are compressing cost structures while regulatory disclosure requirements and buyer consolidation rewrite contracting terms across Mediterranean supply chains.
Single-cell protein derived from bacterial fermentation is expanding into commercial sea bass feed formulations as Norwegian and Dutch biotechnology suppliers scale production. Greek integrated farms are trialing these inputs at 15-30% fishmeal substitution rates. The technology is expanding into premium product positioning by enabling carbon intensity reductions that satisfy EU Green Deal procurement criteria.
The EU F-Gas Regulation's 2030 phase-down schedule forces cold-chain operators to retrofit processing plants with CO2 or ammonia-based refrigeration systems. Spanish and Turkish packers face capital expenditure decisions between transitional HFO blends and leapfrog natural refrigerant architectures. Coastal facilities in Murcia and Izmir are clustering shared infrastructure investments to defray individual compliance burdens.
Centralized procurement by European retail consortiums is consolidating purchase volumes toward fewer approved suppliers with integrated hatchery-to-harvest traceability. French and German supermarket buying groups now mandate lot-level digital records accessible via QR code. Greek farms with Selonda-style vertical control capture disproportionate contract share against fragmented independent growers lacking certification infrastructure.
Sea Bass Market Segmentation
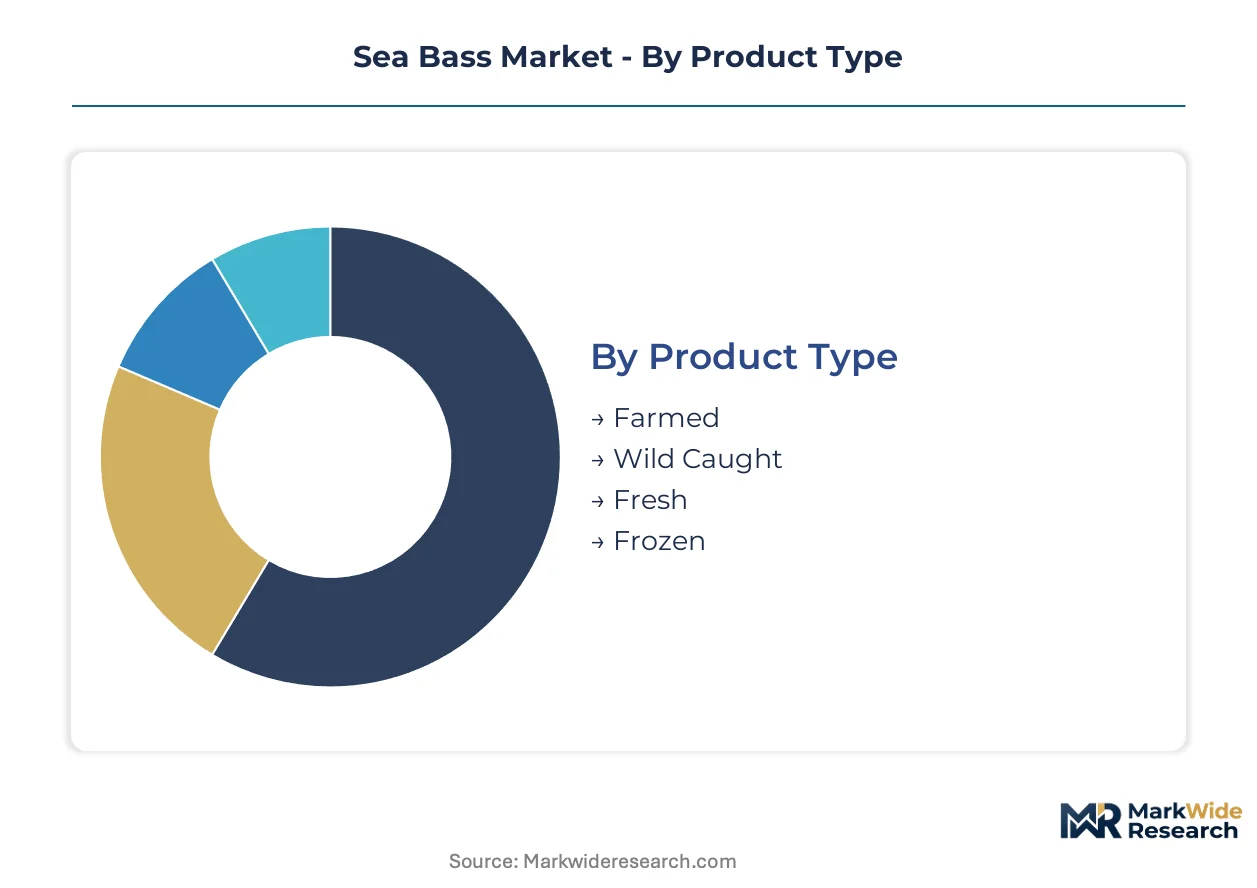
Sea bass procurement patterns diverge sharply across product origins and channel structures. Capital deployment requirements vary by segment, determining which operators capture margin expansion in Mediterranean aquaculture clusters.
Product Type:
Farmed sea bass demands the heaviest upfront capital, requiring hatchery infrastructure, recirculating systems, and veterinary compliance frameworks that wild-caught alternatives bypass entirely.
- Farmed:Controlled aquaculture environments in Greece, Spain, and Turkey deliver consistent size grading and year-round availability. EFSA residue monitoring protocols certify contaminant-free supply chains, commanding retail premiums across EU member states.
- Wild Caught:Lower-volume Mediterranean harvests face seasonal constraints and quota limitations under the Common Fisheries Policy. French and Italian coastal fleets supply niche food service channels where provenance storytelling supports menu pricing.
- Fresh:Chilled distribution through short cold chains serves high-turnover restaurant accounts in urban centers. F-Gas Regulation compliance costs compress margins for processors maintaining 0-4°C throughput.
- Frozen:Blast-freezing at harvest locks in texture for export-grade fillets. Extended shelf life reduces spoilage risk in supermarket distribution, stabilizing revenue visibility for Turkish and Greek producers.
Most installed capacity flows through Farmed. Expansion is steepest in Frozen.
Distribution Channel:
Channel selection determines working capital intensity, with food service contracts requiring extended payment terms while retail and direct sales accelerate cash conversion cycles.
- Retail:French and German supermarket buying groups consolidate procurement volumes toward approved suppliers with QR-code traceability. Vacuum-packed fillets dominate chilled counters, while frozen SKUs anchor promotional calendars.
- Food Service:Restaurant chains across Spain and Italy specify farmed sea bass for menu consistency. Contract pricing structures absorb feed cost volatility through quarterly adjustment clauses.
- Direct Sales:Integrated Greek farms bypass auction markets through long-term agreements with processing cooperatives. Reduced intermediary layers capture margin otherwise lost to distributor markups.
- Online:Home-delivery platforms in urban UK and Netherlands markets trial portion-controlled frozen shipments. Cold-chain packaging investments limit geographic reach to same-day delivery zones.
Food Service channels absorb the highest volume tonnage. Online is climbing the fastest as delivery infrastructure matures.
Packaging Type:
Packaging format selection reflects shelf-life requirements and retail channel specifications, with capital equipment needs scaling from simple tray sealing to vacuum chamber investments.
- Vacuum Pack:Modified atmosphere packaging extends retail case life to 12-14 days. Spanish processors in Murcia cluster shared vacuum infrastructure to defray individual equipment costs.
- Tray:Overwrapped polystyrene dominates fresh counter presentation in Mediterranean supermarkets. Lower barrier properties restrict distribution radius to 48-hour delivery windows.
- Canned:Thermal processing in olive oil targets export markets with limited cold-chain reliability. Portuguese canneries supply Middle Eastern and African demand through established trade routes.
- Bulk:Unpackaged whole fish shipments serve processing facilities and large-scale catering operators. Izmir-based packers specialize in containerized bulk exports to Russian and Eastern European buyers.
Vacuum Pack commands premium positioning. Bulk shipments handle the highest absolute tonnage through export corridors.
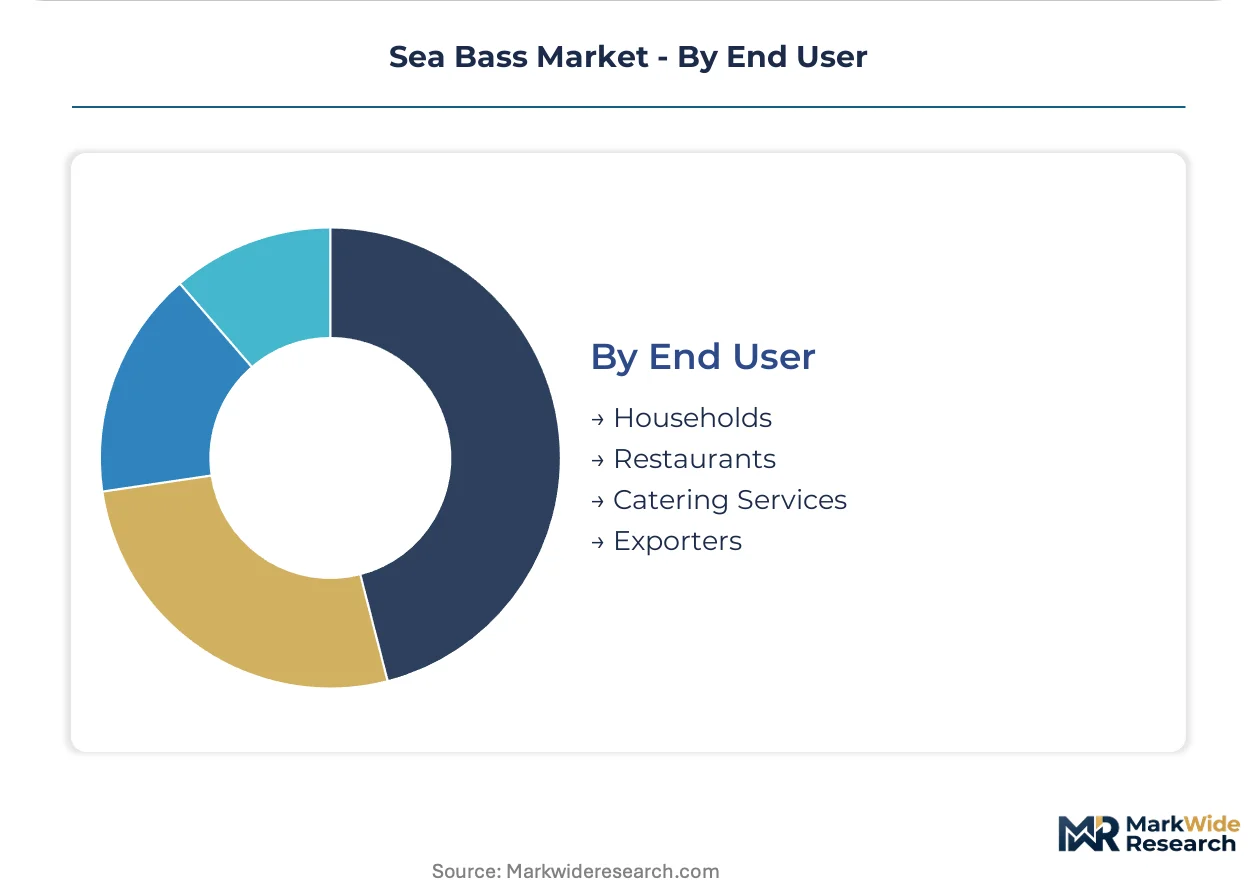
End User:
End-user segmentation tracks consumption occasion and preparation complexity, with households demanding convenience formats while restaurants prioritize yield optimization and plate presentation.
- Restaurants:Full-service operators in Athens, Barcelona, and Marseille specify 300-400 gram whole fish for tableside presentation. Farmed supply guarantees consistent cook times across menu engineering specifications.
- Households:Retail-purchased fillets target mid-week meal occasions in Northern European markets. Recipe-ready portioning reduces preparation barriers for time-constrained consumers.
- Catering Services:Institutional feeding contracts in hotel chains and corporate dining specify frozen IQF portions. Batch cooking requirements favor predictable yield rates from uniform farmed stock.
- Exporters:Reprocessing facilities in Vietnam and Thailand import frozen Mediterranean sea bass for value-added portioning. EU-origin labeling supports premium positioning in Asian retail channels.
Restaurants represent the highest value-per-kilogram consumption. Exporters are gaining share fastest as Asian demand for Mediterranean provenance intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aquaculture veterinarians and marine biologists cluster around Mediterranean coastal farming zones, with Greek hatcheries, Spanish processing corridors, and Turkish grow-out concessions competing for technical talent to support expansion timelines.
Greece
Integrated farm-to-harvest operators dominate supply consolidation as retail buyers mandate QR-code traceability. EFSA residue monitoring protocols certify contaminant-free supply chains, commanding premiums across EU member states. The Amvrakikos Gulf and Ionian coastline host Selonda-style vertical operations capturing disproportionate contract share from French and German supermarket buying groups.
Spain
Murcia-based processors cluster shared vacuum infrastructure investments to defray F-Gas Regulation compliance costs for natural refrigerant retrofits. The country's national food safety regulator enforces cold-chain documentation requirements that compress margins for facilities maintaining 0-4°C throughput. Catalonian and Valencian coastal zones concentrate year-round grow-out capacity serving Barcelona and Marseille restaurant chains.
Turkey
Aegean and Mediterranean shoreline concessions expand production with lower labor costs than EU member state operations, attracting contract pricing from European retail consortiums. The F-Gas Regulation's extraterritorial pressure on export-bound cold chains forces Izmir-based packers toward CO2 refrigeration architectures. Containerized bulk shipments from Turkish ports supply Russian and Eastern European reprocessing demand.
Italy
French and Italian coastal fleets supply niche food service channels where provenance storytelling supports menu pricing for wild-caught alternatives. The Common Fisheries Policy quota limitations constrain Mediterranean harvest volumes, pushing restaurant procurement toward farmed substitutes. Sicily and Puglia farming concessions integrate with mainland processing cooperatives bypassing traditional auction markets.
Norway
Salmon expertise transfers into sea bass farming technologies as RAS system vendors scale closed-loop water treatment for species diversification. Norwegian cold-chain engineering suppliers retrofit Mediterranean facilities with ammonia-based refrigeration systems compliant with EU Green Deal procurement criteria. Bergen and Trondheim marine protein research clusters develop alternative feed formulations reducing fishmeal dependency.
Sea Bass Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Mediterranean aquaculture corridors. The vendor base organizes around three strategic archetypes: integrated hatchery-to-harvest operators controlling full supply chains, salmon incumbents leveraging marine protein expertise for species expansion, and Asian reprocessors adding value to frozen Mediterranean imports. Dominant competitive moves include backward integration into breeding facilities and long-term supply agreements with retail buying groups displacing traditional auction market dependence.
Among Norwegian salmon specialists extending into sea bass, Grieg Seafood and Mowi occupy positions exemplifying technology transfer archetypes, while Selonda Aquaculture anchors the integrated Mediterranean pure-play tier. These three represent contrasting strategic postures: Nordic diversification versus Hellenic vertical focus, with each archetype capturing distinct contract segments based on traceability depth and cold-chain certification.
| Leading Market Players |
|---|
| American Seafoods Group |
| Grieg Seafood |
| Selonda Aquaculture |
| Vinh Hoan |
| SalMar |
| Lerøy Seafood Group |
| Cermaq |
| Bakkafrost |
| Mowi |
| Others |
Value Chain & Pricing Dynamics
Aquaculture veterinary specialists clustering around Greece's Amvrakikos Gulf and Turkey's Aegean coastline drive labor-cost spreads that separate premium farmed product from economy-grade imports. Turkish grow-out concessions leverage lower wage structures to undercut Greek integrated farms on bulk frozen contracts, while EFSA-certified Greek operators capture retail premiums through traceability guarantees demanded by French and German supermarket buying groups.
Pricing Analysis
Fresh versus frozen format splits dominate pricing architecture, with chilled whole fish commanding restaurant premiums against blast-frozen fillet commodities. Price differentiation hinges on EFSA residue certification tier and vacuum-packaging grade, separating traceable farmed supply from untraceable wild alternatives. Pricing pressure intensifies in frozen segments as Turkish capacity expansions flood Eastern European reprocessing channels. Food service buyers exhibit highest price sensitivity, accepting species substitution when sea bass premiums exceed menu engineering thresholds.
Supply Chain Analysis
Regional distribution centers in Murcia and Izmir operate hub-and-spoke cold chains radiating toward Northern European retail consolidation points. Supply concentrates in Greece, Turkey, and Spain, with Norwegian engineering inputs feeding RAS technology retrofits. Fishmeal and fish oil price volatility, tethered to Peruvian anchovy harvest cycles, injects margin instability across farming operations. Single-source vulnerability concentrates in Mediterranean hatchery genetics, where three broodstock suppliers dominate European fingerling supply. Distribution runs through integrated farm-to-retail operators bypassing traditional auction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sea bass market compounds steadily as aquaculture volume displaces volatile wild catch, with restaurant chain procurement standardization locking in predictable offtake. EFSA certification requirements and retail traceability mandates create defensive moats for compliant operators.
For Market Incumbents: Lock in long-term supply agreements with French and German supermarket buying groups before Turkish competitors achieve full EFSA equivalency certification. Invest in captive hatchery capacity to insulate against broodstock supplier concentration risk. Prioritize CO2 refrigeration retrofits at Spanish processing facilities to preempt F-Gas Regulation compliance deadlines.
For New Entrants and Emerging Players: The 15-20% price gap between premium EFSA-certified Greek farmed product and economy-grade Turkish bulk frozen supply offers white-space entry for mid-tier traceable operators. Target UK and Netherlands home-delivery platforms with portion-controlled frozen shipments, where cold-chain packaging investments limit incumbent geographic reach. Pursue direct-to-retailer contracts with Scandinavian supermarket chains seeking Mediterranean provenance alternatives.
For Investors and Strategic Acquirers: Valuations sit cheapest among fragmented independent Greek growers lacking integrated hatchery infrastructure and QR-code traceability systems. Five-to-ten-year viability favors operators with RAS technology licenses and verified low-emission production credentials. Monitor EU Green Deal carbon footprint labeling mandate implementation timelines as inflection signals for premium contract reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Operations | Captive broodstock supply reduces dependency on concentrated Mediterranean genetics suppliers. |
| CO2 Refrigeration Retrofit Program | Murcia and Izmir packers achieve F-Gas Regulation compliance ahead of 2030 phase-down deadlines. |
| Alternative Protein Feed Adoption | Single-cell protein formulations at 15-30% fishmeal substitution satisfy EU Green Deal procurement criteria. |
| Direct-to-Retailer Contract Structure | Long-term frozen supply agreements with supermarket chains displace auction market price volatility. |
| Blockchain Traceability Deployment | QR-code lot-level records meet French and German buying group digital documentation mandates. |
Study Parameters
Coverage spans Mediterranean production clusters and Northern European consumption centers, with primary inputs from each. The analysis combines structured interviews with aquaculture farm managers, veterinary health officers, retail category buyers, and cold-chain logistics operators with secondary validation from EFSA residue monitoring databases, EU Common Fisheries Policy quota records, and F-Gas Regulation implementation filings. Bottom-up farm capacity assessments triangulate against top-down import trade statistics across the analysis window.
Granularity-level modeling disaggregates volume and value across farmed versus wild origin, fresh versus frozen format, and retail versus food service channel splits, with additional segmentation by packaging type and end-user occasion. CAGRs derive from trend extrapolation of aquaculture productivity gains, feed cost trajectories, and regulatory compliance cost absorption rates. Forecast inputs incorporate El Niño cycle impacts on Peruvian anchovy harvests and EU Green Deal carbon labeling mandate adoption curves.
Caveats apply where feed input commodity spikes, veterinary disease outbreaks, or F-Gas Regulation enforcement delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Carp Market
Seafood
Fish Meal Market
Seafood
Fish Protein Concentrate Market
Seafood
Europe Shrimp Market
Seafood
Striped Bass Market
Seafood
Global Smoked Fish Market
Seafood
Global Seafood Market
Seafood
Smoked Salmon Market
Seafood
Sea Biscuits Market
Seafood
Seafood Powders Market
Seafood
Food Clamshells Market
Seafood
Edible Seaweed Market
Seafood
Caviar Market
Seafood
Seafood Flavors Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
United States Lobster Market