
 Bioactive Proteins in Coffee Market | 2026-2036
Bioactive Proteins in Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Proteins in Coffee Market Outlook
Brazil is rewriting supply dynamics for coffee-derived bioactives through expanded wet-processing infrastructure that preserves protein integrity from cherry to extract. Nestlé S.A. leverages its vertically integrated coffee supply chain to secure high-availability feedstocks for protein fractionation at scale. Kerry Group anchors its position through specialized enzymatic modification capabilities that tailor coffee protein functionality for beverage applications. Cargill Inc. competes across the Arabica-Robusta sourcing spectrum, sustaining margin flexibility amid volatile green coffee differentials.
Bioactive proteins in coffee comprise nitrogenous compounds including albumins, globulins, and glutelins extracted from green or roasted coffee matrices, typically yielding 10-15% protein by dry weight depending on cultivar and processing method; these proteins serve primarily as functional ingredients delivering emulsification, antioxidant capacity, and bioactive peptide precursors for human nutrition. Hydrolyzed Proteins dominate current revenue pools due to superior digestibility and faster absorption kinetics in sports nutrition formulations, while Native Proteins retain premium positioning in clean-label cosmetic applications where structural integrity drives claims substantiation. Functional Blends represent the fastest-expanding category as formulators combine coffee proteins with complementary botanicals to achieve synergistic bioactivity profiles in dietary supplements.
The FDA evaluates coffee protein concentrates under GRAS self-determination or food additive petition pathways, while the EU EFSA novel food authorization process mandates comprehensive toxicological dossiers for non-traditional protein sources. BIS certification requirements in India and evolving FSSAI standards for plant protein fortification are creating divergent compliance architectures for exporters. Stakeholders must monitor regulatory harmonization progress between CODEX-aligned frameworks and jurisdiction-specific purity thresholds to optimize multi-market launch sequencing.
Market Dynamics
Enzymatic extraction platforms are compressing protein isolation timelines from weeks to days, forcing wet-processing infrastructure upgrades across origin markets and reshaping supplier qualification criteria for functional ingredient buyers.
Growth Catalysts
- Sports Nutrition Formulations:Hydrolyzed coffee proteins deliver superior nitrogen retention kinetics that protein powder manufacturers in Germany and the Netherlands actively specify for post-workout recovery products.
- EU Novel Food Regulation:Streamlined EFSA authorization pathways for enzymatically treated plant proteins are accelerating ingredient approval timelines for coffee-derived bioactives entering European dietary supplements.
- Gut Health Positioning:Bioactive peptide precursors from coffee glutelins demonstrate prebiotic functionality that functional beverage formulators leverage for microbiome-focused product lines targeting digestive wellness.
Market Restraints
- Green Coffee Differential Volatility:Arabica-Robusta price spreads exceeding 80 cents per pound compress margin predictability for protein fractionation operations dependent on specific cultivar chemistries.
- Brazilian Supply Concentration:Wet-processing infrastructure capable of preserving protein integrity clusters in Minas Gerais and São Paulo states, creating single-origin vulnerability for global hydrolysate supply.
- Thermal Degradation Limits:Roast profile temperatures above 220°C denature functional protein structures, restricting viable feedstock sourcing to lightly processed or green coffee matrices with limited availability.
Strategic Opportunities
- Cosmetic Applications:Native coffee proteins with intact tertiary structures command premium positioning in Korean and French clean-label skincare formulations where structural integrity substantiates antioxidant claims.
- FSSAI Fortification Mandates:India's evolving standards for plant protein fortification in packaged foods create regulatory tailwinds for coffee protein concentrates entering South Asian nutrition markets.
- Precision Fermentation Convergence:Hybrid production models combining agricultural coffee protein extraction with microbial expression systems enable novel bioactive peptide libraries unavailable through conventional hydrolysis alone.
Industry Challenges
- Enzymologist Talent Scarcity:Commercial-scale protein isolation requires specialized biocatalysis expertise concentrated in Hamburg and Berlin biotechnology clusters, constraining replication speed for new extraction facilities.
- GRAS Dossier Complexity:FDA notification pathways for novel coffee protein hydrolysates demand 12-18 month toxicological study timelines that delay revenue recognition for ingredient innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Proteins in Coffee Market |
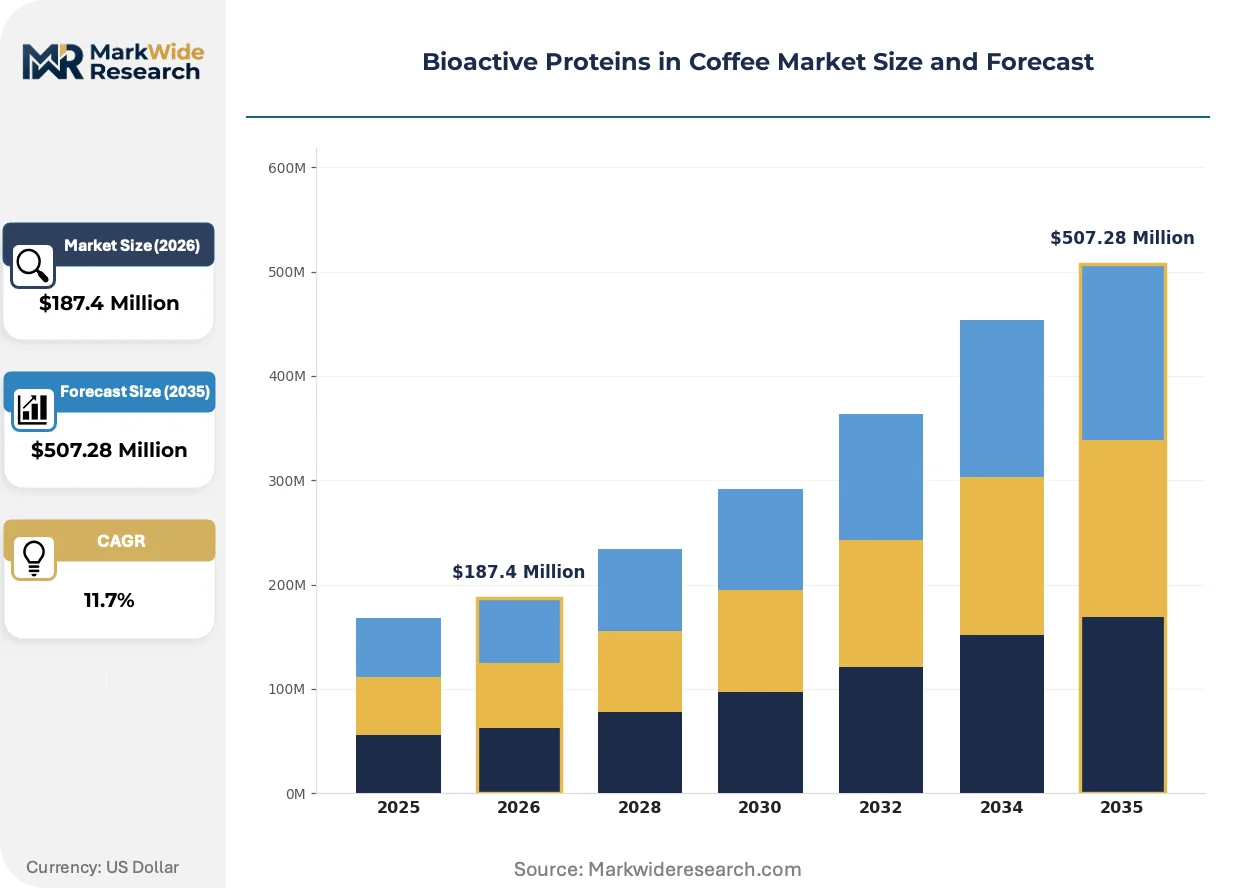
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Proteins, Native Proteins, Enzymatically Modified Proteins, Functional Blends Source: Arabica Beans, Robusta Beans, Coffee Cherries, Coffee Extracts Application: Nutraceuticals, Food & Beverages, Dietary Supplements, Cosmetics Form: Powder, Liquid, Capsule, Granule |
| Companies Covered | Nestlé S.A., Starbucks, Peet's Coffee, Dutch Bros, Archer Daniels Midland Company, Kerry Group, Cargill Inc., Fonterra Co-operative Group Ltd., BASF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Proteins in Coffee Market Strategic Shifts
Continuous flow enzymatic reactors are displacing batch processing architectures, while regulatory clarity on novel protein authorizations and shifting procurement criteria among functional food manufacturers collectively restructure competitive positioning.
Subcritical water extraction is collapsing the energy intensity and solvent dependency of conventional protein isolation methods. Sports nutrition contract manufacturers in Germany and the United States are retrofitting extraction lines with continuous-flow hydrothermal systems. This technology compression enables margin recovery for mid-scale processors previously excluded by capital barriers to organic solvent-based fractionation.
EFSA's evolving guidance on bioactive peptide safety assessment is tightening toxicological evidence requirements for hydrolyzed plant proteins entering European dietary supplements. The industrial consequence is extended dossier preparation timelines and elevated third-party testing expenditure for novel food applicants. Coffee protein suppliers with existing novel food authorizations leverage this regulatory friction to defend incumbent positions against new market entrants.
Ingredient sourcing criteria among North American functional beverage brands now prioritize carbon footprint documentation alongside functional performance specifications. Procurement teams request lifecycle assessments spanning cherry harvest through spray-dried concentrate, displacing price-primary vendor selection protocols. This behavioral shift concentrates contract awards with suppliers operating integrated wet-processing and renewable energy infrastructure, most visible in sustainability-focused product lines from Pacific Northwest formulators.
Bioactive Proteins in Coffee Market Segmentation
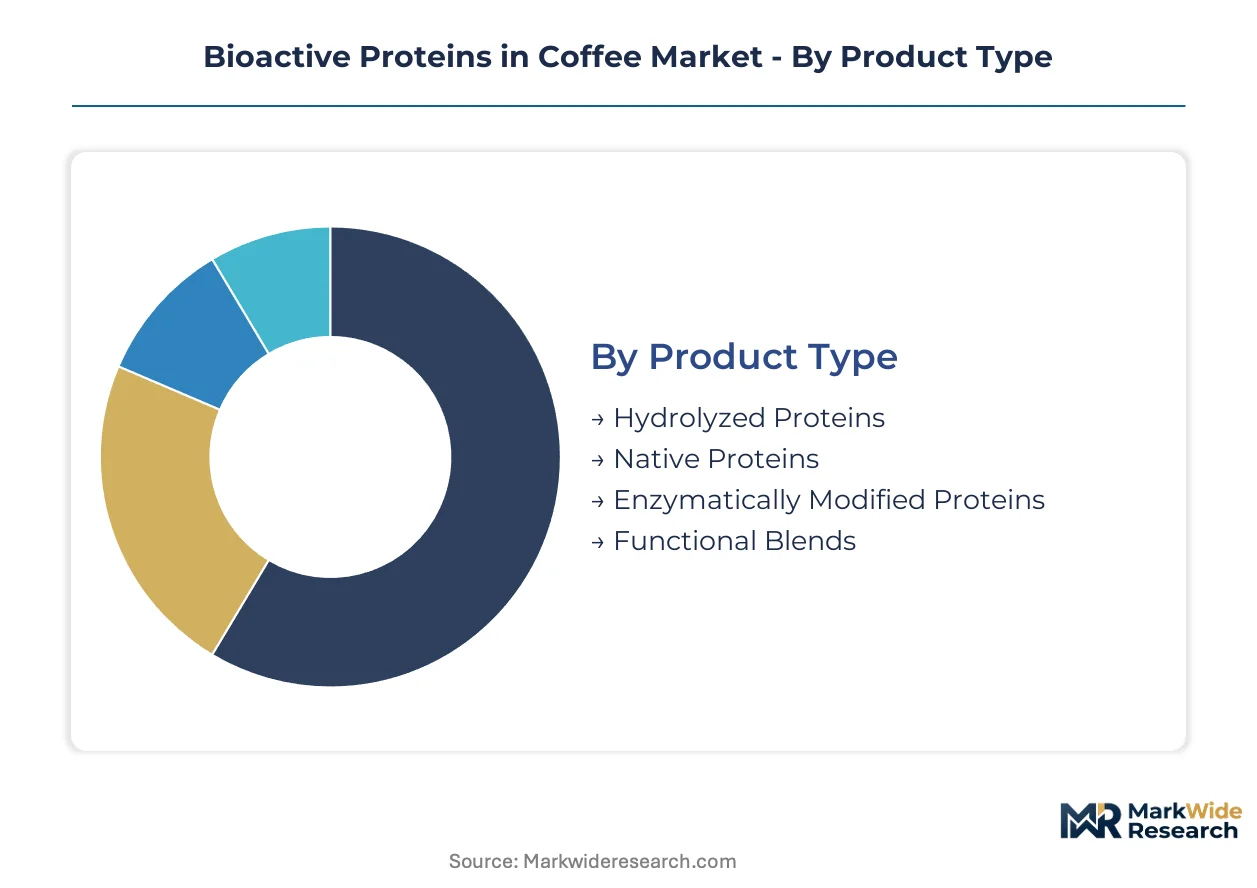
Segmentation in the bioactive proteins in coffee market reflects divergent technical requirements across extraction methods, cultivar chemistries, and end-use specifications. Each dimension carries distinct margin profiles and regulatory pathways that reshape procurement criteria for ingredient buyers.
Product Type:
After-sales service intensity varies sharply across product types, with hydrolyzed proteins demanding enzymologist technical support for shelf-life optimization and application troubleshooting that native protein buyers rarely require.
- Hydrolyzed Proteins:These proteins undergo controlled enzymatic cleavage into peptides with molecular weights typically below 10 kDa, delivering superior nitrogen retention kinetics. Demand concentrates among German sports nutrition contract manufacturers specifying rapid absorption profiles for post-workout formulations, constrained by enzymologist talent scarcity in commercial-scale isolation facilities.
- Native Proteins:Intact albumins, globulins, and glutelins retain tertiary structures essential for emulsification and film-forming functionality. Korean and French clean-label cosmetic formulators command premium positioning where structural integrity substantiates antioxidant efficacy claims in skincare applications.
- Enzymatically Modified Proteins:Targeted biocatalysis adjusts surface hydrophobicity and solubility indices for beverage emulsion stability. Food technologists in the Netherlands specify these for plant-based milk alternatives requiring sustained suspension.
- Functional Blends:Synergistic combinations with botanical proteins or prebiotic fibers. Dietary supplement innovators in the United States leverage these for microbiome-positioned product lines with differentiated bioactivity profiles.
Hydrolyzed proteins hold the largest share; momentum sits with functional blends.
Source:
Cost tier stratification across sources mirrors wet-processing infrastructure availability and protein preservation requirements from harvest through extraction.
- Arabica Beans:Higher protein concentrations in mild cultivars from high-altitude regions yield premium hydrolysates with cleaner sensory profiles. Brazilian wet-processing clusters in Minas Gerais preserve protein integrity through controlled fermentation, though Arabica-Robusta price volatility compresses margin predictability.
- Robusta Beans:Elevated caffeine and chlorogenic acid co-extraction requires additional purification stages. Southeast Asian processors in Vietnam leverage Robusta abundance for cost-sensitive nutraceutical applications where bitter notes are masked in capsule formats.
- Coffee Cherries:Cascara-derived proteins from the fruit pulp represent underutilized feedstocks. Sustainability-focused formulators in the Pacific Northwest specify these for carbon footprint reduction in lifecycle assessments.
- Coffee Extracts:Pre-concentrated matrices from soluble coffee production enable streamlined protein recovery. Nestlé's vertically integrated supply chain secures these feedstocks for fractionation at commercial scale.
Arabica beans dominate value capture; coffee cherries are climbing the fastest as circular economy positioning intensifies.
Application:
Application segments diverge by regulatory pathway complexity and clinical substantiation requirements for bioactive claims.
- Nutraceuticals:EFSA novel food authorization mandates comprehensive toxicological dossiers for coffee protein hydrolysates entering European dietary supplements, extending preparation timelines for entrants lacking existing approvals.
- Food & Beverages:FDA GRAS self-determination pathways enable faster market access for qualified suppliers. Functional beverage manufacturers prioritize carbon footprint documentation alongside performance specifications in procurement protocols.
- Dietary Supplements:India's FSSAI fortification mandates create regulatory tailwinds for coffee protein concentrates entering South Asian nutrition markets with plant protein positioning.
- Cosmetics:Korean beauty formulators specify native proteins with intact tertiary structures for antioxidant claims in clean-label skincare, commanding premium pricing over hydrolyzed alternatives.
Food and beverages command volume leadership; nutraceuticals show the steepest expansion trajectory.
Form:
Form selection dictates supply chain configuration from spray-drying infrastructure through final packaging requirements.
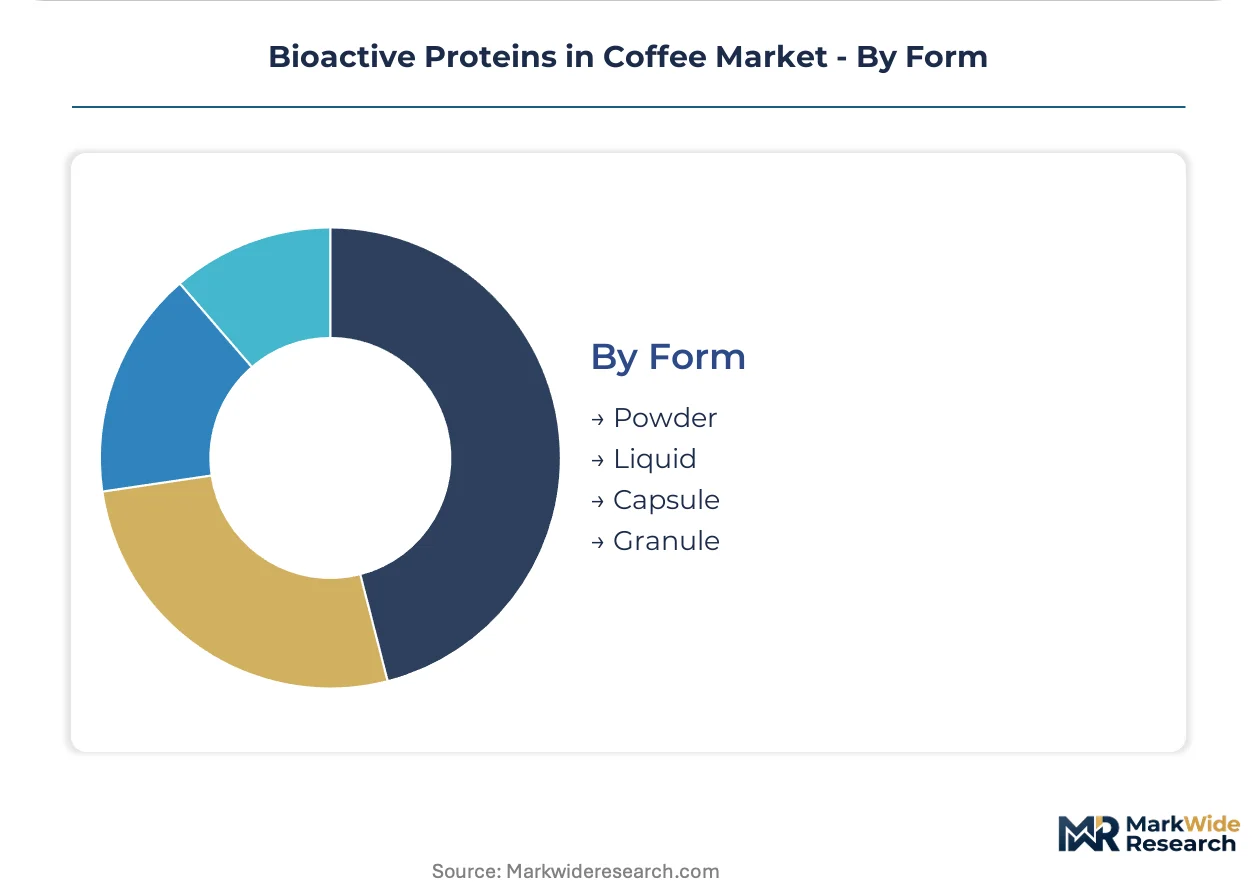
- Powder:Spray-dried concentrates dominate sports nutrition and bulk ingredient distribution, with shelf stability dependent on moisture specification control below 5%.
- Liquid:Ready-to-drink functional beverages in Germany and the Netherlands specify liquid hydrolysates for manufacturing efficiency, constrained by cold-chain requirements.
- Capsule:Precise dosing for dietary supplement positioning masks sensory limitations of Robusta-derived proteins in premium formats.
- Granule:Intermediate dissolution kinetics for instant beverage applications, specified by food service channels requiring rapid reconstitution.
Powder maintains incumbent position; liquid formats are gaining share fastest in ready-to-drink channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet-processing infrastructure for protein preservation clusters in Brazil, Germany, India, and the United States, with each geography developing distinct regulatory and commercial pathways for coffee-derived bioactives.
Germany
EFSA novel food authorization streamlines market entry for enzymatically treated plant proteins. Sports nutrition manufacturers in Hamburg and Berlin specify hydrolyzed coffee proteins for post-workout recovery formulations. Biotechnology clusters around Hamburg advance continuous-flow enzymatic reactors that compress isolation timelines from weeks to days.
United States
FDA GRAS self-determination pathways enable faster commercialization for qualified suppliers. Pacific Northwest functional beverage brands prioritize carbon footprint documentation alongside performance specifications in procurement protocols. Seattle and Portland formulators drive demand for cascara-derived proteins in sustainability-positioned product lines.
Brazil
Expanded wet-processing infrastructure in Minas Gerais and São Paulo preserves protein integrity from cherry to extract. ANVISA regulatory frameworks govern novel ingredient approvals for domestic nutraceutical applications. Coffee biotechnology investments concentrate in São Paulo state, where controlled fermentation protocols yield premium hydrolysate feedstocks.
India
FSSAI fortification mandates for plant proteins in packaged foods create regulatory tailwinds for coffee protein concentrates. Karnataka and Tamil Nadu processing hubs develop enzymatic extraction capabilities for South Asian nutrition markets. Bangalore-based ingredient innovators target dietary supplement channels with microbiome-positioned functional blends.
Netherlands
Food technologists specify enzymatically modified coffee proteins for plant-based milk alternatives requiring sustained emulsion stability. REACH compliance frameworks influence purity thresholds for imported bioactive ingredients. Rotterdam and Amsterdam logistics clusters facilitate distribution of spray-dried concentrates across European contract manufacturing networks.
Bioactive Proteins in Coffee Market Competitive Environment
Vertically integrated beverage conglomerates and specialized ingredient modifiers split the market into distinct capability tiers. Tier-one players leverage captive coffee supply chains and enzymatic modification platforms to control feedstock quality and functional performance specifications. Tier-two specialists concentrate on application-specific formulations for sports nutrition and cosmetic channels. Dominant competitive moves include backward integration into wet-processing infrastructure and strategic partnerships with enzymology research clusters.
Within the integrated supply chain tier, Nestlé S.A. and Cargill Inc. exemplify archetypes that combine agricultural sourcing with downstream fractionation capabilities. Kerry Group occupies a position among specialized enzymatic modification specialists that tailor protein functionality for beverage emulsion systems. These three entities anchor the competitive structure through distinct strategic postures: captive feedstock security, biochemical processing expertise, and application-driven formulation services respectively.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Starbucks |
| Peet's Coffee |
| Dutch Bros |
| Archer Daniels Midland Company |
| Kerry Group |
| Cargill Inc. |
| Fonterra Co-operative Group Ltd. |
| BASF Corporation |
| Others |
Value Chain & Pricing Dynamics
Hamburg-Rotterdam freight corridors dictate landed cost spreads between Brazilian wet-processing clusters and German enzymatic modification facilities, compressing margin buffers for mid-scale hydrolysate suppliers while amplifying pricing power among integrated operators with captive logistics.
Pricing Analysis
EU Novel Food Regulation dictates the pricing tier structure for bioactive proteins in coffee, separating EFSA-authorized premium hydrolysates from standard-grade concentrates awaiting dossier approval. Certification tier and volume scale drive price differentiation, with sports nutrition contract manufacturers in Germany showing lowest price sensitivity for rapid-absorption formulations. Cost compression in standard-grade native proteins is intensifying because Brazilian wet-processing capacity expansion outpaces qualified enzymologist availability.
Supply Chain Analysis
Tariff exposure between Brazil and the European Union dominates supply chain risk calculus for coffee protein concentrates, though the current Mercosur negotiation status leaves duty rates unresolved. Feedstock sourcing draws from Minas Gerais wet-processing clusters, Vietnamese Robusta abundance, and Pacific Northwest cascara recovery operations. Enzymologist talent scarcity in commercial-scale isolation facilities constitutes the critical bottleneck. Distribution runs through Rotterdam and Amsterdam logistics hubs into European contract manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German sports nutrition contract manufacturers and Pacific Northwest functional beverage brands, forcing ingredient suppliers into longer-term offtake commitments with carbon disclosure requirements.
For Market Incumbents: Harden EFSA novel food authorization moats through accelerated toxicological dossier investment before regulatory friction tightens further. Secure backward integration into Minas Gerais wet-processing infrastructure to control protein integrity from cherry harvest, insulating margin structures against Arabica-Robusta price volatility that threatens fractionation economics. For New Entrants and Emerging Players: Mid-scale enzymatic modification services for beverage emulsion stability represent the most penetrable entry point, given Kerry Group's capacity concentration and food technologist demand in the Netherlands. India's FSSAI fortification mandates offer regulatory tailwinds for plant protein positioning without EFSA timeline burdens. Target microbiome-focused functional blend formulations where synergistic botanical combinations enable differentiated claims. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified coffee conglomerates with underutilized wet-processing assets and stranded protein fractionation capabilities lacking enzymologist staffing. Long-term viability hinges on hybrid production models combining agricultural extraction with precision fermentation convergence. Monitor EFSA guidance evolution on bioactive peptide safety assessment as the inflection signal for novel food authorization timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wet-Processing Infrastructure | Captive protein integrity control from Brazilian cherry harvest through extraction secures margin predictability against green coffee differential volatility. |
| EFSA Novel Food Authorization Acceleration | First-mover toxicological dossier completion defends incumbent positioning as regulatory friction tightens hydrolyzed plant protein entry requirements. |
| Continuous-Flow Enzymatic Reactor Deployment | Hamburg biotechnology cluster adoption compresses isolation timelines from weeks to days, forcing batch facility obsolescence. |
| Precision Fermentation Convergence Investment | Hybrid agricultural-microbial production models unlock novel bioactive peptide libraries unavailable through conventional hydrolysis alone. |
| Carbon Footprint Documentation Integration | Pacific Northwest formulator procurement criteria now mandate lifecycle assessments spanning cherry harvest through spray-dried concentrate. |
Study Parameters
A spread of perspectives from enzymology research directors, sports nutrition contract manufacturing procurement leads, functional beverage formulators, and EFSA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notification filings, EFSA novel food authorization registers, ANVISA regulatory frameworks, and FSSAI fortification mandate documentation. Bottom-up protein fractionation capacity modeling triangulated against top-down functional ingredient demand forecasting across the analysis window.
Demand-supply balance framing anchored the quantitative architecture, with segmentation dimensions spanning product type hydrolysis degree, source cultivar chemistry, application regulatory pathway complexity, and form supply chain configuration. CAGRs derived from elasticity-adjusted price trajectory modeling and capacity utilization projections. Industry-specific inputs included enzymologist talent cluster density, wet-processing infrastructure investment pipelines, and evolving novel food authorization timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in green coffee differential spreads, freight corridor cost structures, or biotechnology talent mobility would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and enzymatic extraction technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Italy Coffee Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Grinder Market
Coffee
RTD Coffee Market
Coffee
Global Professional Coffee Machine Market
Coffee
Decaffeinated Coffee Market
Coffee
Office Coffee Service (OCS) Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Drip Coffee Machine Market
Coffee
United States Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Green Coffee Market
Coffee
Espresso Powder Market
Coffee
Chewable Coffee Market
Coffee
Coffee Roaster Machine Market