
 Asia-Pacific Shrimp Market | 2026-2036
Asia-Pacific Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Shrimp Market Outlook
Food service distribution is tilting toward integrated suppliers capable of delivering traceable, value-added shrimp products across Asia-Pacific markets. Charoen Pokphand Foods PCL leverages captive feed mills and hatchery networks to secure consistent raw material flows. Thai Union Group PCL anchors its competitive position through vertical control from vessel to retail shelf. Minh Phu Seafood specializes in high-margin processed and cooked shrimp for Japanese and European buyers.
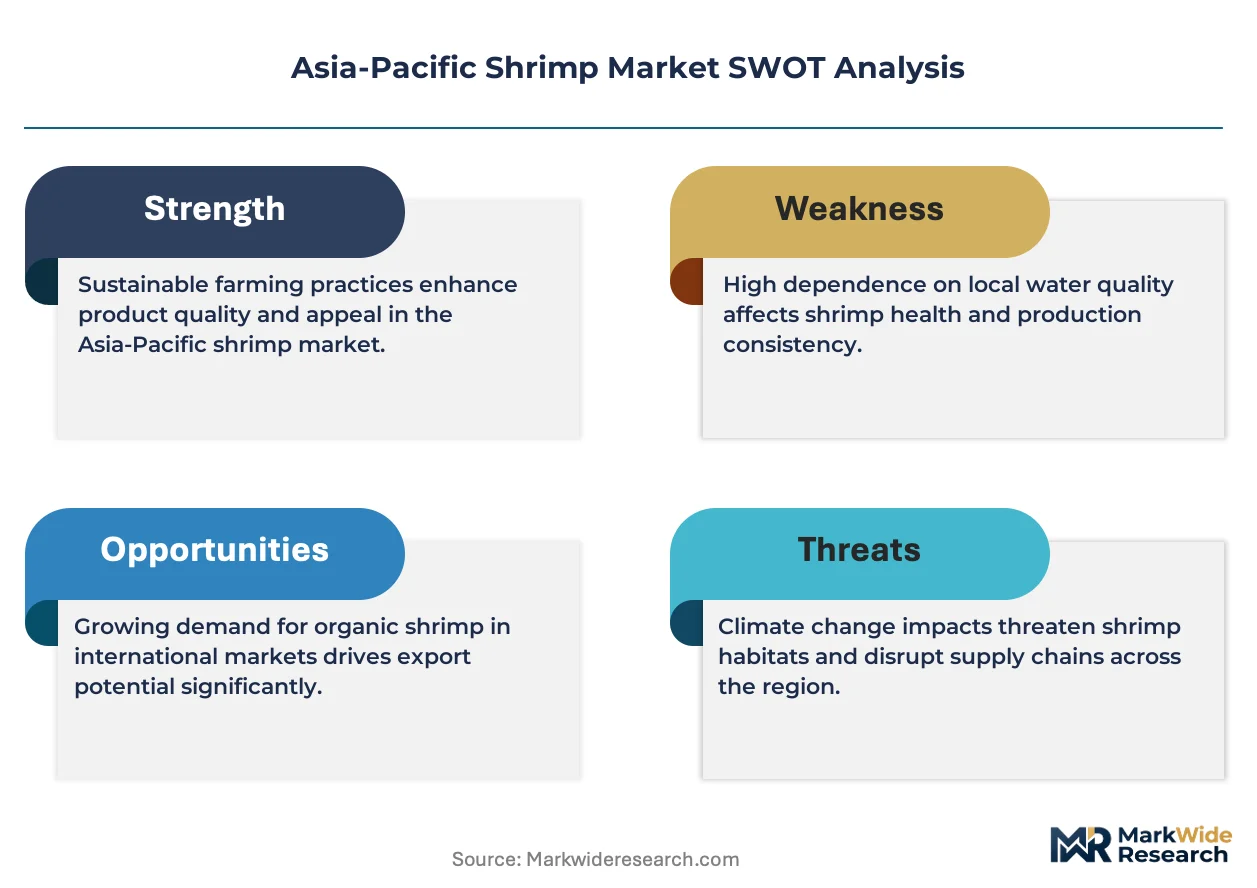
Asia-Pacific shrimp encompasses marine and aquaculture-derived decapod crustaceans, primarily Penaeus monodon and Litopenaeus vannamei species, processed into head-on, headless, peeled, cooked, and value-added formats for human consumption. Warm water farmed shrimp dominates volume output across Southeast Asian coastal zones, where pond-based intensive aquaculture achieves harvest cycles under 120 days. Cold water varieties command premium positioning in Japanese retail and sushi supply chains, while vacuum pack and tray formats capture expanding supermarket shelf space as consumers shift from wet-market purchasing.
China's SAMR enforces GB standards for aquatic product labeling and additive limits, while Vietnam's MARD implements antibiotic residue monitoring under EU equivalence protocols. India's FSSAI and MPEDA coordinate export certification requirements that determine market access for frozen container shipments. Stakeholders must monitor evolving maximum residue limits in destination markets and invest in blockchain-enabled traceability systems before compliance windows tighten.
Market Dynamics
Vietnam's MARD antibiotic residue protocols are compressing supply timelines across the Mekong Delta processing cluster, forcing exporters to accelerate traceability investments before EU equivalence windows tighten.
Growth Catalysts
- EU Equivalence Protocols:Vietnam's MARD enforcement of antibiotic residue monitoring is accelerating blockchain adoption across integrated farming-to-export infrastructure in the Mekong Delta.
- Food Service Procurement:Southeast Asian restaurant chains and hotel operators are consolidating supplier bases toward traceable, value-added shrimp formats with shorter lead times.
- Intensive Pond Technology:Warm water aquaculture achieving sub-120-day harvest cycles is expanding output volumes across Indonesian and Thai coastal zones.
Market Restraints
- Feed Input Volatility:Soybean and fishmeal price swings compress margins for pond-based operators lacking captive feed mill capacity.
- Processing Concentration:Vietnam's Mekong Delta hosts disproportionate export infrastructure, creating single-point vulnerability for frozen container throughput.
- Cold Water Substitution:Japanese sushi supply chains retain preference for wild-caught cold water varieties in premium retail segments.
Strategic Opportunities
- Philippines Domestic Retail:Supermarket penetration remains below Thai and Vietnamese levels, creating shelf space for vacuum-pack and tray format introductions.
- Blockchain Traceability:EU and Japanese buyers are mandating farm-to-fork verification systems that integrated Vietnamese suppliers can monetize through certification premiums.
- Indonesian Hatchery Expansion:Government aquaculture development zones in Sulawesi and Sumatra offer land and water concessions for vertically integrated operations.
Industry Challenges
- Antibiotic Testing Capacity:Mekong Delta laboratories face backlogs certifying export batches under tightened MARD protocols, extending shipment release timelines.
- Skilled Pond Management:Intensive aquaculture requires trained technicians for water quality monitoring and disease prevention, with talent concentrated among established Thai operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Shrimp Market |
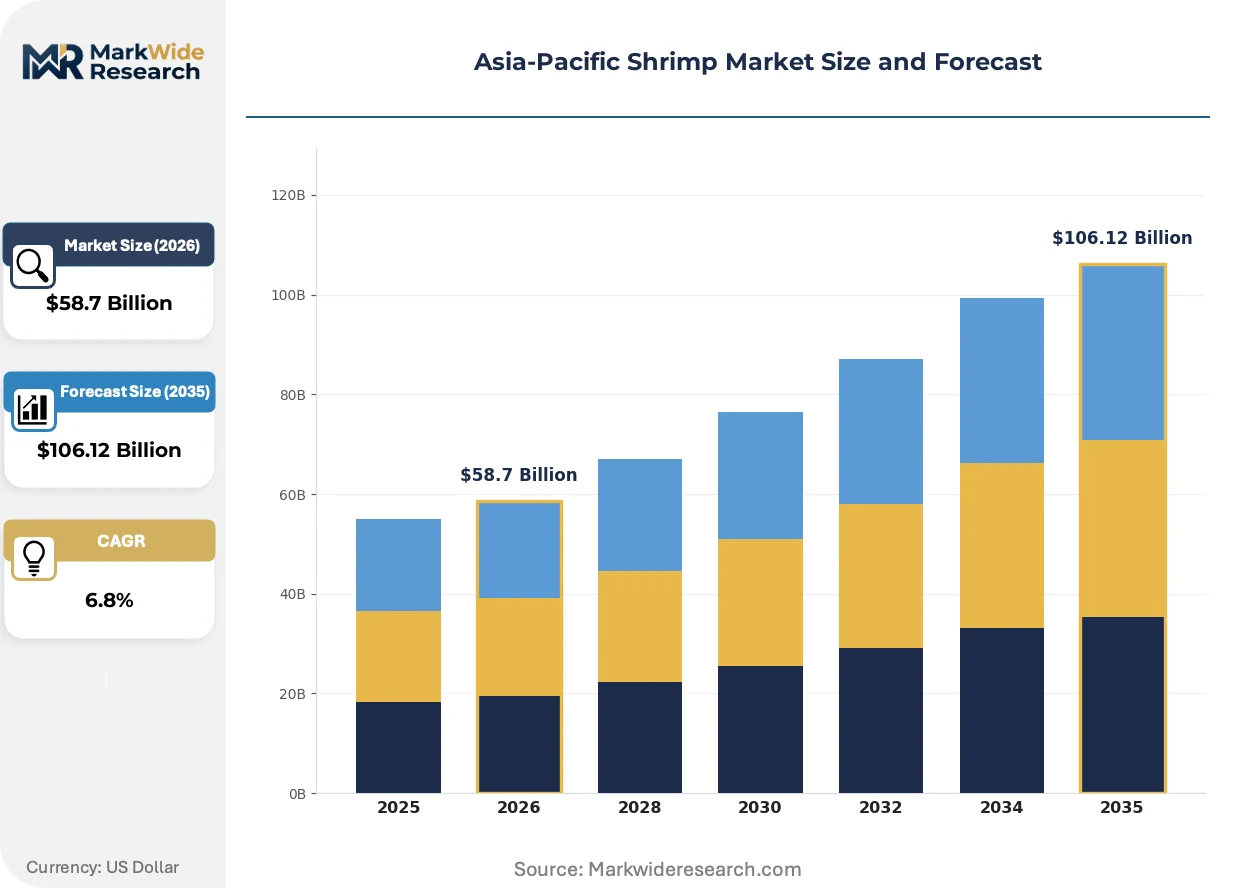
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Water, Warm Water, Freshwater, Farmed End User: Restaurants, Supermarkets, Exporters, Food Service Distribution Channel: Online, Wholesalers, Retail, Direct Sales Packaging Type: Bulk, Vacuum Pack, Tray, Canned |
| Companies Covered | Thai Union Group PCL, Charoen Pokphand Foods PCL, Apex Frozen Foods Ltd, Maruha Nichiro Corporation, Minh Phu Seafood, PT Central Proteina Prima, Avanti Feeds, Blue Snow Food Co. Ltd, Amara Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Shrimp Market Strategic Shifts
Processing technology and buyer verification requirements are compressing traditional supply chain layers across Asia-Pacific shrimp markets.
Recirculating aquaculture systems (RAS) is hybridizing with conventional pond infrastructure in Thai and Indonesian operations. Mid-scale processors seeking biosecurity certification for EU and Japanese buyers are piloting closed-loop water treatment alongside open pond networks. This hybrid architecture is compressing the technology adoption curve between intensive and extensive farming models.
China's SAMR enforcement of GB standards for aquatic product labeling and additive limits is tightening import documentation requirements. Processors serving Chinese retail and food service channels must now align additive declarations with domestic labeling rules. Vietnamese and Thai exporters are responding by segregating production lines and reformulating value-added products for China-bound shipments.
Japanese retail buyers are consolidating supplier relationships around integrated processors capable of delivering cooked and prepared shrimp with full traceability documentation. Wet-market purchasing continues declining in Tokyo and Osaka metropolitan areas. This channel rotation is most visible in premium supermarket formats where vacuum-pack shelf presence now determines supplier selection criteria.
Asia-Pacific Shrimp Market Segmentation
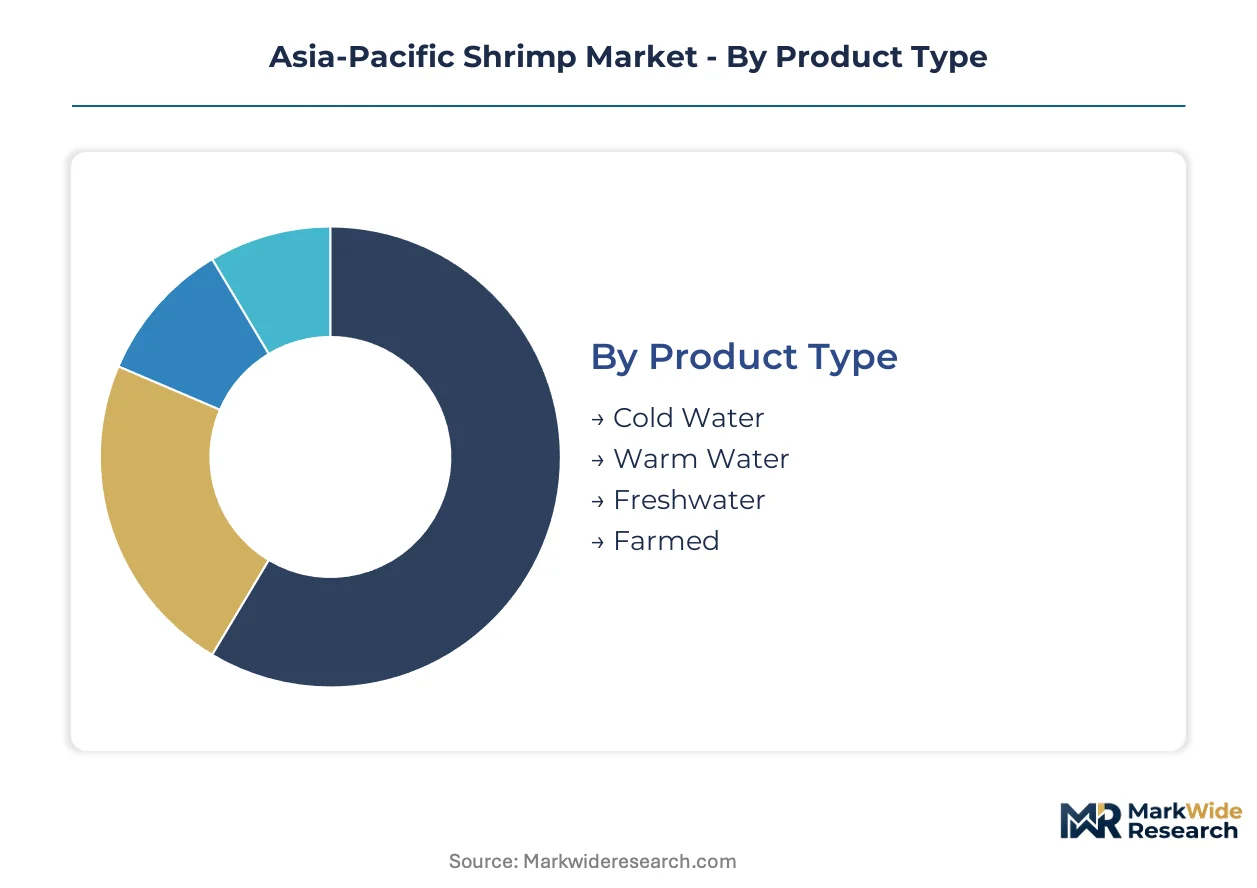
Segmentation in Asia-Pacific shrimp markets determines pricing power and procurement strategy. Cold water varieties command Japanese sushi premiums while warm water farmed volumes dominate Southeast Asian food service. Packaging and channel choices increasingly hinge on traceability requirements from EU and Japanese buyers.
Product Type:
After-sales service intensity concentrates in cold water segments where Japanese buyers demand rapid replacement for quality failures and documentation gaps.
- Warm Water:Penaeus monodon and Litopenaeus vannamei farmed across Thai and Indonesian coastal zones with sub-120-day harvest cycles. Food service operators in Bangkok, Jakarta, and Ho Chi Minh City anchor procurement volumes for restaurant and hotel chains seeking consistent sizing and shorter lead times.
- Cold Water:Wild-caught varieties from northern Pacific waters processed for Japanese retail and sushi supply chains. Tokyo and Osaka metropolitan supermarkets retain preference for these premium formats despite wet-market decline, with vacuum-pack shelf presence determining supplier selection.
- Freshwater:Riverine and lake-sourced decapods from Mekong Delta pond systems serving domestic Vietnamese and Cambodian wet markets.
- Farmed:Intensive pond aquaculture across Sulawesi and Sumatra development zones with government land concessions supporting vertically integrated operations.
Warm water holds the largest share; momentum sits with cold water as Japanese retail consolidation accelerates.
End User:
Cost tier differentiation separates commodity exporters from integrated processors serving premium food service channels.
- Food Service:Southeast Asian restaurant chains and hotel operators consolidating supplier bases toward traceable, value-added formats. Vietnamese Mekong Delta processors leverage integrated farming-to-export infrastructure to compress lead times for frozen and prepared shipments.
- Supermarkets:Retail formats in Tokyo, Osaka, Bangkok, and Jakarta rotating from wet-market purchasing toward vacuum-pack and tray shelf presence. Chinese SAMR enforcement of GB labeling standards forces production line segregation for China-bound shipments.
- Restaurants:Independent and chain dining establishments across Philippines and Indonesia with below-Thai supermarket penetration creating entry opportunities.
- Exporters:Mekong Delta and Thai Eastern Seaboard processors certifying under EU equivalence protocols and Japanese full-traceability documentation requirements.
Food service commands the revenue concentration; supermarkets are climbing the fastest as channel rotation accelerates.
Distribution Channel:
Volume flows concentrate through wholesale networks serving processing clusters, with direct sales capturing premium traceability contracts.
- Wholesalers:Traditional aggregation points in Vietnam's Mekong Delta and Thailand's Samut Sakhon province consolidating farm outputs for export container loading. Single-point vulnerability exists as disproportionate infrastructure concentrates in these coastal zones.
- Direct Sales:Integrated processors like Charoen Pokphand Foods and Thai Union Group bypassing intermediaries to anchor competitive position through vessel-to-retail-shelf vertical control.
- Retail:Supermarket and wet-market storefronts across Philippines with penetration gaps below Thai and Vietnamese levels.
- Online:Emerging e-commerce platforms for frozen seafood in Chinese and Japanese urban markets with SAMR and METI labeling compliance requirements.
Wholesalers retain the dominant flow; direct sales show steepest expansion trajectory as buyer consolidation favors integrated suppliers.
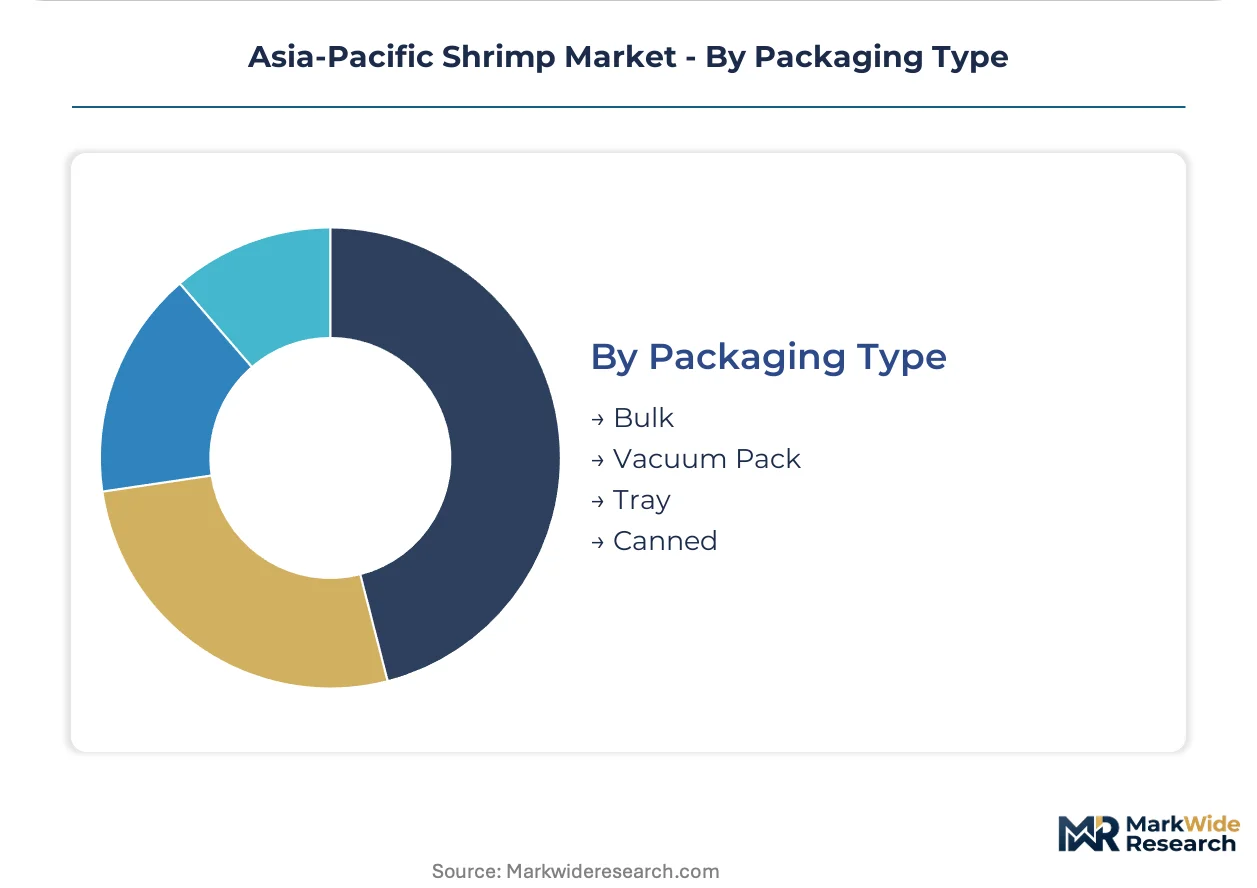
Packaging Type:
Margin structure stratifies across premium certification-grade vacuum packs versus commodity bulk formats for reprocessing.
- Vacuum Pack:Modified atmosphere packaging capturing Japanese and Korean retail shelf space with blockchain-enabled traceability documentation. Minh Phu Seafood and comparable processors monetize certification premiums through EU and Japanese buyer mandates.
- Tray:Consumer-ready formats for supermarket penetration in Philippines and Indonesian urban centers with below-regional-average modern retail development.
- Bulk:Industrial frozen blocks for reprocessing by secondary processors and food service distributors across Southeast Asia.
- Canned:Shelf-stable prepared shrimp for emergency stockpiling and remote distribution in archipelagic Indonesian and Philippine markets.
Bulk retains volume leadership; vacuum pack gains share fastest as traceability requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cai Mep-Thi Vai deepwater port complex underwrites Vietnam's export dominance, handling frozen container throughput from the Mekong Delta processing cluster with direct vessel calls to EU and Japanese markets.
Vietnam
Mekong Delta food service procurement and Japanese retail traceability mandates drive demand concentration. MARD antibiotic residue protocols are accelerating blockchain adoption across integrated farming-to-export infrastructure. Cai Mep-Thi Vai port terminals and Can Tho processing plants are compressing lead times for vacuum-pack shipments.
Thailand
Bangkok hotel chains and restaurant operators consolidate supplier bases toward value-added formats with full documentation. CP Foods and Thai Union anchor captive feed mill networks across Samut Sakhon and Surat Thani provinces. Eastern Seaboard processing zones are integrating RAS pilot systems with conventional pond networks.
China
SAMR enforcement of GB labeling standards is reshaping import documentation for frozen and prepared shrimp. Yangtze River Delta supermarkets and e-commerce platforms are rotating from wet-market purchasing toward vacuum-pack shelf presence. Qingdao and Dalian cold storage terminals are segregating production lines for domestic-bound shipments.
Indonesia
Sulawesi and Sumatra government aquaculture development zones offer land concessions for vertically integrated operations. Domestic restaurant chains in Jakarta and Surabaya create below-regional-average supermarket penetration gaps for tray format introductions. Makassar and Medan hatchery clusters are expanding broodstock capacity for intensive pond systems.
Japan
Tokyo and Osaka metropolitan supermarkets consolidate supplier relationships around cooked and prepared shrimp with farm-to-fork verification. METI labeling compliance requirements and sushi supply chain preferences for wild-caught cold water varieties retain premium positioning. Nagoya and Fukuoka distribution terminals are mandating blockchain traceability for EU-equivalent Vietnamese suppliers.
Asia-Pacific Shrimp Market Competitive Environment
On the supply side, the industry is bifurcated between integrated conglomerates with captive feed-to-retail infrastructure and specialized processors serving premium export channels. Scale-driven players compete through vessel-to-shelf vertical control, while mid-tier operators differentiate via certification-grade traceability systems. Strategic moves concentrate on hatchery network expansion and blockchain-enabled documentation investments.
Within the integrated conglomerate tier, Charoen Pokphand Foods PCL and Thai Union Group PCL exemplify supply-side consolidation through captive feed mill and hatchery networks. Minh Phu Seafood occupies a position among specialized processors monetizing certification premiums for Japanese and European buyers requiring full traceability documentation.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Charoen Pokphand Foods PCL |
| Apex Frozen Foods Ltd |
| Maruha Nichiro Corporation |
| Minh Phu Seafood |
| PT Central Proteina Prima |
| Avanti Feeds |
| Blue Snow Food Co. Ltd |
| Amara Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Vietnamese Mekong Delta processing plants is compressing spot pricing for bulk frozen blocks while tightening premiums for blockchain-certified vacuum packs. This utilization divergence rewards integrated operators with captive hatchery networks and punishes commodity traders lacking traceability infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU-equivalent certified product from domestic-grade bulk and reprocessing feedstock. Price differentiation rests on MARD antibiotic clearance documentation and Japanese METI labeling compliance, with food service buyers in Bangkok and Jakarta showing highest sensitivity to per-kilogram fluctuations. Pricing pressure stems from soybean and fishmeal input volatility squeezing pond-operator margins. Cold water wild-caught varieties retain least price elasticity among Tokyo supermarket procurement committees.
Supply Chain Analysis
Contract-manufacturing concentration sits with Mekong Delta processors in Vietnam and Samut Sakhon operators in Thailand, with Sulawesi hatcheries emerging as third pole. Raw material flows draw from Indonesian broodstock networks, Thai captive feed mills, and Vietnamese pond clusters. Single-point vulnerability concentrates in Cai Mep-Thi Vai container throughput. Distribution runs through wholesale aggregation at Can Tho and Eastern Seaboard terminals before direct sales capture EU and Japanese traceability premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific shrimp markets face substitution defense against plant-based seafood analogs and lab-grown crustacean proteins gaining shelf trials in Korean and Japanese retail. Incumbents must harden traceability moats before alternative protein price parity arrives.
For Market Incumbents: Entrench EU-equivalence certification through accelerated blockchain deployment across Mekong Delta farming networks. Deepen backward integration into Sulawesi hatchery concessions before Indonesian land concessions expire. Cold water substitution in Japanese sushi channels and feed input volatility represent immediate threats requiring captive supply hedging. For New Entrants and Emerging Players: Establish a beachhead in Philippine supermarket tray formats where modern retail penetration trails Thai benchmarks by double digits. Target Indonesian domestic restaurant chains in Surabaya and Medan with value-added cooked products bypassing wholesale layers. Lead with vacuum-pack traceability narratives matching METI compliance requirements without legacy infrastructure drag. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RAS-hybrid pond systems as biosecurity hardware becomes table stakes for EU market access. Mid-scale Vietnamese processors with incomplete traceability stacks represent distressed acquisition targets. Monitor MARD laboratory backlog durations as early signal of compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Networks | Captive broodstock supply from Sulawesi and Sumatra development zones secures genetic consistency and disease resistance. |
| Blockchain Traceability Deployment | Farm-to-fork verification systems unlock EU and Japanese certification premiums for Mekong Delta exporters. |
| RAS-Hybrid Pond Pilot Expansion | Closed-loop water treatment integration in Thai Eastern Seaboard operations accelerates biosecurity clearance timelines. |
| Philippines Retail Channel Development | Tray format introductions exploit below-regional supermarket penetration in Manila and Cebu urban corridors. |
| Feed Mill Capacity Addition | Captive soybean and fishmeal processing in Samut Sakhon buffers margin compression from agricultural commodity swings. |
Study Parameters
Operator-level perspectives from hatchery managers, Mekong Delta processing plant directors, Japanese supermarket category buyers, and EU import compliance officers anchored the qualitative base. Secondary validation drew from Vietnam MARD export certification databases, Thai customs trade flows, Japanese METI food labeling registries, and EU RASFF alert notifications. Bottom-up volume estimates triangulated against top-down consumption models across warm water, cold water, and freshwater product categories.
Scenario-bracketing framed projections across antibiotic protocol enforcement intensity, feed input cost trajectories, and alternative protein substitution rates. Segmentation dimensions modeled included product type, end-user channel, packaging format, and country-level regulatory cluster. CAGRs derived from trend extrapolation of historical trade volumes adjusted for policy inflection points. Forecast inputs incorporated MARD laboratory capacity expansion schedules and Indonesian aquaculture zone concession timelines.
Sensitivities concentrate around EU equivalence protocol tightening, Japanese retail buyer consolidation, and feed commodity price spikes. Forecasts reflect assumptions on traceability technology adoption curves and cold storage infrastructure buildout. Quarterly review of MARD certification backlogs, Cai Mep-Thi Vai container throughput, and METI labeling enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Oil Market
Seafood
South America Canned Seafood Market
Seafood
European Frozen Seafood Market
Seafood
Shellfish Market
Seafood
Mackerel Market
Seafood
Fish Nutrition Market
Seafood
United States Seafood Market
Seafood
Surimi Market
Seafood
Food Clamshells Market
Seafood
Tuna Market
Seafood
Canned Sardines Market
Seafood
Mussel Extract Market
Seafood
Molluscs Market
Seafood
North America Frozen Seafood Market
Seafood
Canned Salmon Market
Seafood
Global Frozen and Canned Seafood Market