
 Canned Seafood Market | 2026-2036
Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Seafood Market Intelligence
Food service procurement is decoupling from frozen-only contracts as operators seek longer shelf-life proteins with lower spoilage risk. Thai Union Group PCL leverages its integrated tuna fleet to control raw material costs across Southeast Asian processing hubs. Bumble Bee Foods, LLC anchors North American retail placement through decades of brand equity in shelf-stable tuna. StarKist Co competes aggressively on price in the mass-market pouch segment while maintaining volume throughput.
Canned seafood comprises fish and shellfish preserved through thermal processing in hermetically sealed containers, typically achieving commercial sterility at F0 values exceeding three minutes to eliminate Clostridium botulinum spores. The primary commercial purpose centers on delivering protein with eighteen to sixty-month ambient shelf stability for retail and institutional buyers. Tuna dominates value pools due to global catch volumes and consumer familiarity, while salmon commands premium positioning in European and North American specialty channels. Pouch packaging is accelerating fastest as brands reduce freight costs and target on-the-go consumption occasions. Glass jar formats retain strength in Mediterranean private-label sardine exports where visual product inspection drives purchase decisions.
The FDA enforces low-acid canned food regulations under 21 CFR Part 113, mandating scheduled thermal process filings that shape plant certification requirements and market entry timelines for new processors. EU REACH restrictions on epoxy-based can coatings accelerate migration toward polyester and oleoresin alternatives, raising reformulation costs for European packagers. Japan's Food Sanitation Act sets maximum mercury thresholds for canned tuna that directly influence sourcing specifications for Maruha Nichiro Corporation and its competitors. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use packaging as these rules increasingly dictate material selection and regional production economics.
Market Dynamics
Food service labor inflation is rewiring procurement contracts toward ambient-stable proteins that reduce spoilage waste and kitchen prep time, compressing the traditional frozen-seafood procurement cycle.
Growth Catalysts
- EU REACH epoxy restrictions:Packagers across Germany, France, and Italy are accelerating polyester and oleoresin coating adoption, creating first-mover advantages for compliant can suppliers.
- Southeast Asian fleet integration:Thai and Philippine tuna vessel networks are consolidating catch-to-can processing, reducing raw material transit costs for regional exporters.
- Pouch format freight economics:Retailers in Japan and South Korea are prioritizing flat-pack shelf-stable seafood that cuts cube utilization and last-mile distribution spend.
Market Restraints
- Wild catch volatility:Skipjack and yellowfin tuna biomass fluctuations in the Western Central Pacific drive raw material cost instability for canneries dependent on purse-seine supply.
- Mercury threshold compliance:Japan's Food Sanitation Act maximum limits for canned tuna force processors to reject higher-grade fish, constraining usable catch volumes.
- Glass jar freight penalty:Mediterranean sardine exporters face 15-20% higher logistics costs versus metal can alternatives, limiting price competitiveness in distant markets.
Strategic Opportunities
- Extended producer responsibility frameworks:EU packaging waste directives are incentivizing mono-material can designs that simplify recycling infrastructure and command retail shelf placement.
- On-the-go consumption channels:Convenience retailers in South Korea and Taiwan are expanding chilled grab-and-go sections that favor single-serve pouch seafood with extended ambient stability.
- Epoxy-alternative coating patents:European chemical suppliers with REACH-compliant oleoresin formulations are capturing can lining contracts from legacy epoxy-dependent competitors.
Industry Challenges
- Thermal process engineering talent:FDA 21 CFR Part 113 filing requirements demand specialized retort specialists, and canneries in the US Southeast report 18-month recruitment cycles for qualified process authorities.
- Legacy equipment retooling:European packagers face 24-36 month capex cycles to convert can lines from epoxy to polyester coating application systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Seafood Market |
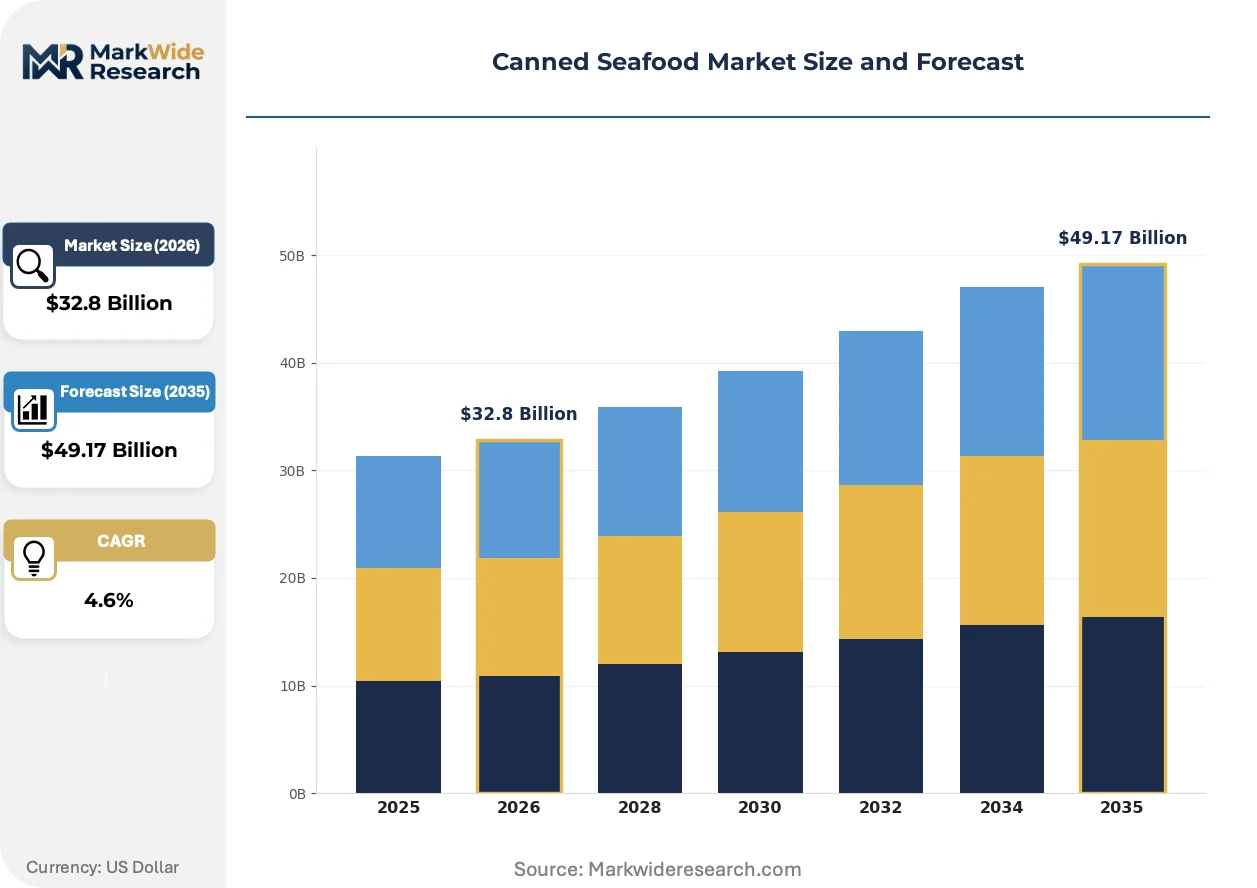
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Salmon, Sardines, Mackerel Packaging Type: Can, Jar, Pouch, Glass Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale End User: Households, Restaurants, Cafeterias, Food Services |
| Companies Covered | Thai Union Group PCL, Bumble Bee Foods, LLC, StarKist Co, Bolton Group, Century Pacific Foods Inc., Trident Seafoods Corp., Maruha Nichiro Corporation, Wild Planet Foods, Inc., Dongwon Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Seafood Market Strategic Shifts & Innovations
Packaging material science and thermal process optimization are converging to redefine shelf-stable seafood economics, with coating chemistry and format geometry commanding disproportionate R&D allocation.
Retort pouch laminates with aluminum oxide barrier layers are modularizing the traditional cylindrical can supply chain, enabling food service distributors to stack pallets 40% higher and cut warehouse footprint. College and corporate dining contractors in California and Texas are specifying pouch-only protein contracts to reduce receiving dock congestion. The format is modularizing procurement specifications away from rigid container mandates toward cube-efficient flexible packaging.
EU REACH Annex XVII restrictions on bisphenol-A in food contact materials are forcing European canners to validate oleoresin and vinyl organosol alternatives before 2025 compliance deadlines. German metal packaging plants report 12-18 month qualification cycles for new coating-chemistries paired with existing seaming equipment. Small-format specialty seafood in glass jars faces disproportionate cost pressure, as oleoresin adhesion on tinplate outperforms glass neck finishes.
Food service procurement teams are unbundling frozen-seafood contracts into dual-source ambient and frozen agreements, with hospital and long-term care operators in Florida and Arizona leading the shift. Distributors are responding with temperature-zone-segregated warehousing that separates shelf-stable protein from cold-chain SKUs. The pattern is most visible in US Sun Belt institutional feeding, where labor turnover makes thaw-and-prep frozen protocols operationally fragile.
Canned Seafood Market Segmentation
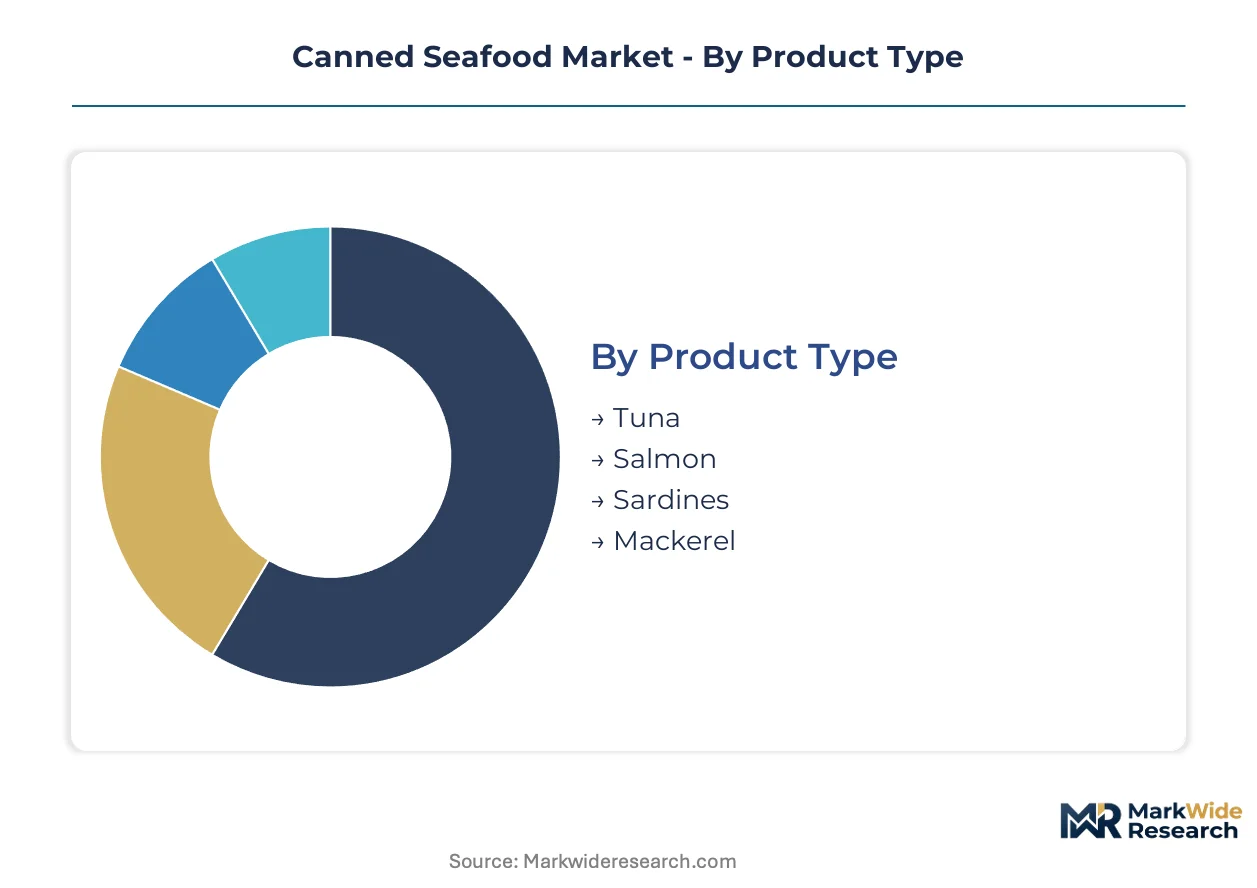
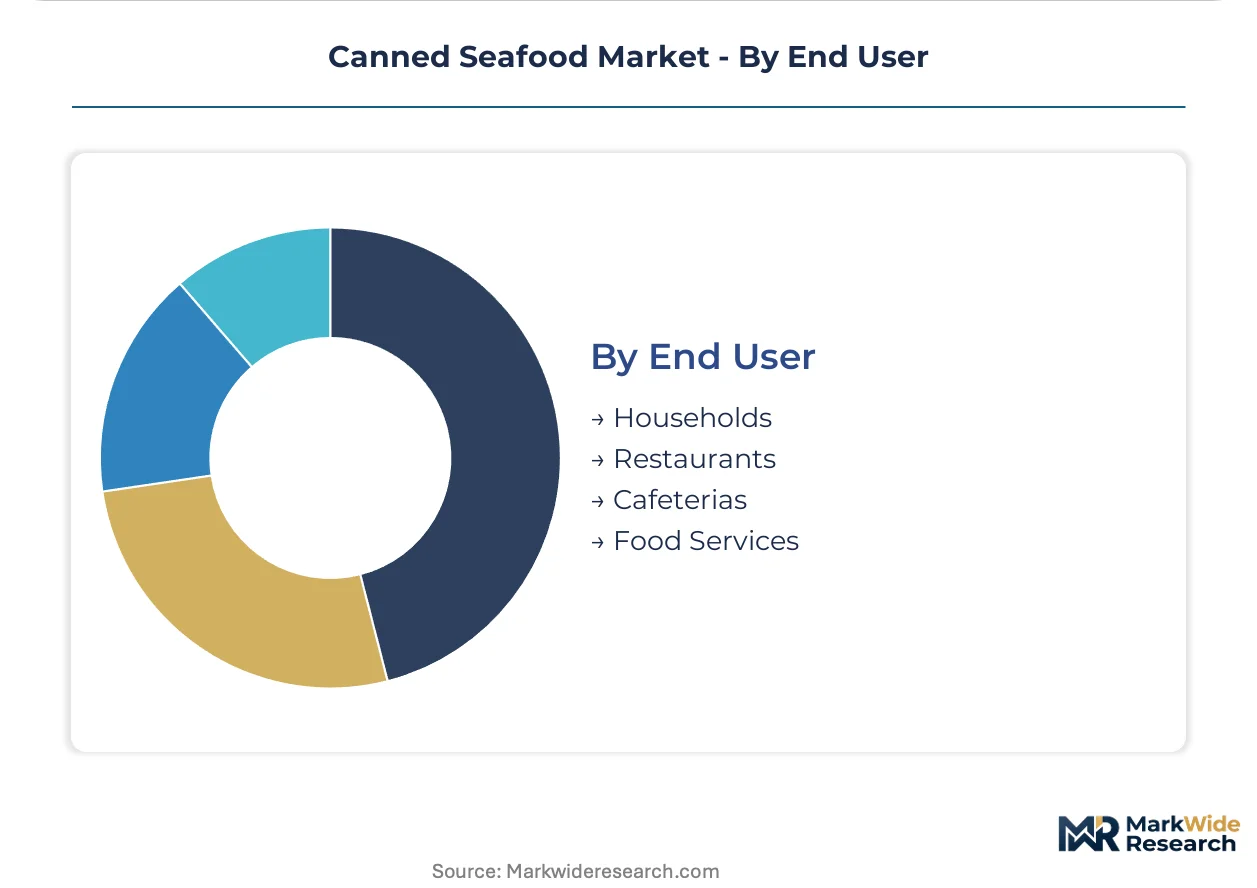
Canned seafood procurement patterns diverge sharply by buyer sophistication and operational constraints. Segment-level differences in spoilage tolerance, labor intensity, and storage economics dictate format selection and channel preference across institutional and retail buyers.
Product Type:
Buyer differentiation centers on protein cost thresholds and menu versatility requirements.
- Tuna:Skipjack and yellowfin varieties dominate institutional procurement due to neutral flavor profiles that adapt to salad, sandwich, and casserole applications. US hospital cafeterias and Southeast Asian food service distributors specify tuna as the default shelf-stable protein for high-volume feeding operations.
- Salmon:Pink and sockeye grades command premium positioning in European specialty retail and North American natural food channels. German and French buyers prioritize MSC-certified salmon for private-label lines where provenance labeling drives shelf placement.
- Sardines:Portuguese and Spanish canneries anchor Mediterranean export supply, with glass jar formats preferred for visual oil clarity inspection.
- Mackerel:Japanese and South Korean processors dominate Pacific catch supply, targeting domestic retail and processed fish cake manufacturers.
Volume sits with tuna; growth tilts toward salmon as certification premiums expand addressable markets.
Packaging Type:
Cost tier and freight economics separate buyers selecting rigid versus flexible formats.
- Can:Three-piece tinplate construction with epoxy or polyester interior coatings remains the default for retail multipacks and institutional cases. German retailers specify mono-material steel designs to satisfy EU extended producer responsibility sorting requirements.
- Pouch:Retortable multilayer laminates with aluminum oxide barriers enable 40% pallet stacking efficiency gains. California college dining contractors and South Korean convenience chains specify pouch-only contracts to reduce receiving dock congestion and warehouse footprint.
- Jar:Glass containers with lug closures retain dominance in Mediterranean sardine exports where oil clarity and fillet integrity inspection influence purchase decisions.
- Glass:Specialty seafood in presentation jars commands premium placement in French and Italian gourmet retail, though freight penalties limit export competitiveness.
Can formats capture baseline volume; pouch configurations are climbing the fastest as logistics operators prioritize cube efficiency.
Distribution Channel:
Customer type and order scale determine channel selection and service level requirements.
- Supermarkets:Multinational retail banners in Germany, France, and Japan negotiate annual tuna contracts with volume rebates and promotional slotting fees. Shelf-stable seafood competes for linear footage against fresh and frozen alternatives.
- Online Retailers:Direct-to-consumer subscription models for premium salmon and specialty tinned fish are expanding in US coastal metros and UK urban centers, bypassing traditional wholesale markups.
- Specialty Stores:Italian and Spanish delicatessen channels emphasize DOP-labeled sardines and artisanal tuna conservas with heritage production claims.
- Wholesale:Broadline distributors serving US Sun Belt institutional feeding operations are unbundling frozen contracts to add ambient protein SKUs in temperature-zone-segregated warehouses.
Supermarkets anchor volume throughput; online retailers are gaining share fastest as subscription mechanics reduce customer acquisition costs.
End User:
Operational maturity and labor availability shape format and product specifications.
- Households:Multipack tuna purchases concentrate in US and Japanese mass retail, with pouch singles gaining traction among younger demographics seeking portable protein.
- Restaurants:Full-service operators in Florida and Arizona are specifying ambient-stable seafood to reduce thaw-and-prep labor dependency in high-turnover kitchen environments.
- Cafeterias:Corporate and university dining contractors in California and Texas prioritize pouch formats to streamline receiving and reduce cold-chain infrastructure.
- Food Services:Hospital and long-term care operators lead the shift from frozen-only to dual-source ambient and frozen procurement contracts.
Households represent the largest consumption base; food services are expanding most quickly as labor inflation rewires procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Seaboard Special Economic Zone concentrates tuna processing capacity, anchoring Southeast Asian supply chains for global export. This zone draws raw material from integrated vessel fleets and feeds canneries serving retail and food service buyers across Asia, Europe, and North America.
United States
California and Texas institutional dining contractors drive pouch format procurement for corporate and university cafeterias. FDA 21 CFR Part 113 regulations mandate scheduled thermal process filings that shape plant certification timelines for domestic processors. The American Southeast reports acute shortages of qualified retort specialists, with recruitment cycles extending eighteen months for process authority positions.
Thailand
Thai Union Group PCL leverages its integrated tuna fleet to control raw material costs across Bangkok and Samut Sakhon processing hubs. The country's Food and Drug Administration enforces GMP standards for canned fishery products that align with EU and US export requirements. Samut Sakhon province anchors the world's largest tuna canning cluster, with annual throughput feeding retail private-label and branded contracts across five continents.
Japan
Maruha Nichiro Corporation and domestic competitors source skipjack and yellowfin under the Food Sanitation Act's mercury threshold limits for canned tuna. METI's fisheries policy frameworks influence vessel licensing and catch allocation in Western Central Pacific purse-seine operations. Yaizu and Shimizu ports in Shizuoka Prefecture concentrate domestic canning and distribution infrastructure for retail and processed fish cake manufacturers.
Germany
Retail banners negotiate annual tuna contracts with volume rebates and promotional slotting fees in Frankfurt and Hamburg procurement centers. EU REACH Annex XVII restrictions on bisphenol-A accelerate polyester and oleoresin coating adoption across German metal packaging plants. Bavarian chemical suppliers with compliant oleoresin formulations capture can lining contracts from legacy epoxy-dependent competitors.
South Korea
Dongwon Industries Co., Ltd. anchors domestic retail placement and exports across Northeast Asian markets. The Ministry of Food and Drug Safety enforces heavy metal limits and labeling standards for imported and domestically processed canned seafood. Busan-Ulsan corridor facilities prioritize flat-pack pouch formats for convenience retail chains seeking cube-efficient distribution and extended ambient stability.
Canned Seafood Market Key Industry Players
Top-tier vendors anchor integrated fleet-to-can operations, while mid-scale processors compete on regional sourcing flexibility and format specialization. The market structures around three concentration nodes: Southeast Asian tuna integrators, North American retail brand houses, and European private-label packagers. Strategic archetypes include vessel-owning raw material controllers, retail brand equity holders, and coating-chemistry specialists. Dominant competitive moves center on fleet consolidation for supply security and pouch line conversion for logistics efficiency.
Among Southeast Asian integrators, Thai Union Group PCL and Dongwon Industries Co., Ltd. exemplify the vessel-owning archetype with captive supply chains from catch to retail shelf. North American retail placement concentrates around Bumble Bee Foods, LLC and StarKist Co, which occupy positions defined by decades of brand equity in shelf-stable tuna and aggressive price positioning in mass-market pouches. These four names represent the competitive spectrum from upstream raw material control through downstream retail channel capture.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Bumble Bee Foods, LLC |
| StarKist Co |
| Bolton Group |
| Century Pacific Foods Inc. |
| Trident Seafoods Corp. |
| Maruha Nichiro Corporation |
| Wild Planet Foods, Inc. |
| Dongwon Industries Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Food service procurement concentration among US hospital and long-term care operators anchors contract-based pricing that rewards volume commitments with preferential rates. These institutional buyers leverage dual-source ambient and frozen agreements to compress supplier margins while securing supply security.
Pricing Analysis
Short lead-time premiums dominate spot procurement for skipjack tuna, with Thai Union and Dongwon commanding price advantages through captive fleet supply. Three-tier pricing structure across MSC-certified premium, standard commodity, and private-label economy levels segments buyer willingness-to-pay. Cost compression in the economy tier intensifies because Southeast Asian processors compete on raw material access. Food service distributors exhibit highest price sensitivity, while European specialty retailers absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Reverse-logistics flows for retail multipack returns concentrate in California and Texas distribution centers, where temperature-zone-segregated warehousing complicates product rotation. Primary supply draws from Thailand, the Philippines, and Indonesia, with tuna catch dependency on Western Central Pacific purse-seine operations. Tinplate and oleoresin coating inputs hinge on German and Japanese chemical suppliers. Single-source vulnerability in integrated fleet networks threatens raw material security during El Niño catch disruptions. Distribution runs through broadline distributors serving institutional buyers and multinational retail banners in Germany, France, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH epoxy restrictions and FDA thermal process filing requirements are forcing capital-constrained processors toward exit or acquisition, consolidating competitive control among fleet-integrated majors.
For Market Incumbents: Lock in coating-chemistry supplier exclusivity with Bavarian oleoresin specialists before qualification cycles extend. Convert legacy can lines to pouch formats in California and Texas to capture food service procurement shifts away from frozen contracts. Defend against private-label encroachment by securing MSC certification premiums in European specialty channels. For New Entrants and Emerging Players: EU REACH Annex XVII in Germany opens a window for compliant can lining specialists to displace legacy epoxy-dependent packagers. Target South Korean convenience retail chains with flat-pack pouch formats that reduce last-mile distribution spend. Enter through direct-to-consumer subscription mechanics for premium salmon in US coastal metros, bypassing wholesale markups. For Investors and Strategic Acquirers: The window for entry favors vessel-owning mid-cap processors in Southeast Asia with captive raw material access. Long-term viability centers on backward integration into tuna fleet networks that insulate against wild catch volatility. Monitor Japan's Food Sanitation Act mercury threshold enforcement as an inflection signal for sourcing specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Integration | Captive skipjack supply through Thai and Philippine vessel networks secures raw material cost control against biomass fluctuations. |
| Pouch Line Conversion | Retort laminate adoption in California and Texas food service channels cuts warehouse footprint and receiving dock congestion. |
| Coating Chemistry Transition | Oleoresin validation in German metal packaging plants satisfies EU REACH compliance and captures can lining contracts. |
| Certification Investment | MSC labeling for salmon and tuna commands shelf placement premiums in French and German specialty retail. |
| Dual-Source Procurement Contracts | Ambient-frozen unbundling in Florida and Arizona institutional feeding reduces spoilage waste and kitchen prep labor. |
Research Approach
Document review covered FDA 21 CFR Part 113 filings, EU REACH Annex XVII compliance databases, and Japanese Food Sanitation Act mercury threshold guidelines, complemented by interviews with cannery process authorities, food service procurement directors, and retail category buyers. Secondary validation drew from customs trade records, SEC filings of publicly traded processors, and fisheries catch data from the Western Central Pacific. Bottom-up volume modeling triangulated against top-down value estimates from distributor revenue disclosures.
Output projections span product type, packaging format, distribution channel, and end-user segmentation across the analysis window. CAGRs derive from historical volume trajectories, fleet capacity expansion plans, and regulatory compliance cost absorption rates. Modeled inputs include skipjack and yellowfin biomass indices, oleoresin coating adoption curves, and pouch format penetration in institutional feeding contracts.
Caveats apply where El Niño catch disruptions, REACH enforcement acceleration, or FDA process authority recruitment shortages could materially shift the outlook. Practitioners should monitor Western Central Pacific Fisheries Commission quota negotiations and EU extended producer responsibility implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Powder Market
Seafood
Shellfish Market
Seafood
Smoked Whiting Market
Seafood
United Arab Emirates Seafood Market
Seafood
United States Plant-Based Seafood Market
Seafood
Tuna Fish Market
Seafood
Milkfish Market
Seafood
Tinned Fish Market
Seafood
Latin America Salmon Market
Seafood
Frozen Seafood Market
Seafood
South America Canned Seafood Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Halibut Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Seafood Flavors Market