
 Salmon Market | 2026-2036
Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Salmon Market Intelligence
Market Context
Pre-portioned fillet bundling is consolidating buyer choice across retail and foodservice channels. Mowi ASA leverages its integrated feed-to-fork model to dominate Atlantic salmon supply. Cooke Aquaculture anchors North American production through vertically owned hatcheries and processing assets. SalMar ASA specializes in offshore farming technology, differentiating through deep-water site licenses.
Technical Definition and Segment Structure
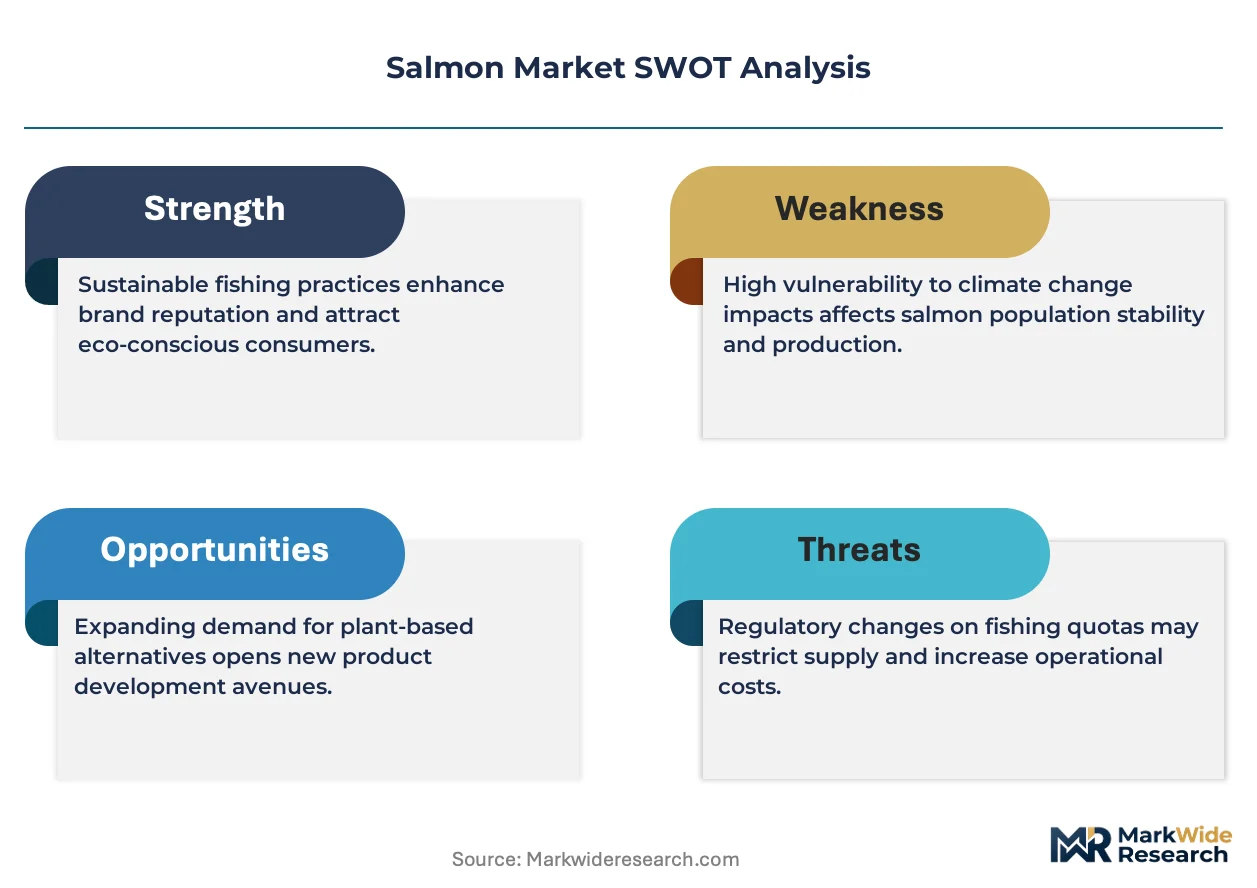
Salmon denotes anadromous fish of the family Salmonidae, farmed Atlantic salmon (Salmo salar) constituting over 70% of commercially traded volume, with flesh protein content typically ranging 20-22% and omega-3 fatty acid thresholds defining premium grade classification. Fresh salmon commands the highest margin pool in product type segmentation due to perishability-driven supply constraints and just-in-time logistics requirements, while frozen salmon extends shelf life for price-sensitive household segments in landlocked markets. Online retail distribution is expanding fastest among channels, though supermarkets still control the largest volume throughput.
Regulatory Framework and Outlook
EU Ecolabel criteria and ASC (Aquaculture Stewardship Council) certification shape product standards and market access for European salmon imports, while Norway's national regulator encloses coastal farming through strict maximum allowable biomass limits per production site. The FDA and USDA jointly oversee U.S. salmon imports, with HACCP compliance mandatory for all foreign processing facilities. Stakeholders must monitor evolving sea lice treatment chemical restrictions and their cascading impact on organic certification eligibility.
Market Dynamics
EU Ecolabel certification tightening and ASC standards are restructuring competitive access across European foodservice channels, forcing feed-to-fork traceability investments that favor integrated producers with captive hatchery networks.
Growth Catalysts
- EU Ecolabel Mandates:Certification requirements for farmed seafood are expanding restaurant menu placements across Western Europe, creating preferential procurement pipelines for compliant suppliers.
- Pre-portioned Retail Formats:Supermarket bundling of fresh fillets is consolidating household purchase decisions toward branded, ready-to-cook SKUs with embedded origin claims.
- Norwegian Fjord Concentration:Integrated production zones around Troms and Nordland leverage deep-water site licenses to control premium Atlantic salmon supply pipelines.
Market Restraints
- Feed Input Volatility:Marine-derived fishmeal and fish oil prices fluctuate with Peruvian anchovy harvest quotas, compressing margin predictability for non-integrated growers.
- Coastal Licensing Bottlenecks:Norway's maximum allowable biomass limits per production site constrain expansion velocity regardless of capital availability.
- Landlocked Market Access:Fresh salmon distribution to Central European and inland Chinese cities requires cold-chain infrastructure that frozen product bypasses.
Strategic Opportunities
- Offshore Deep-Water Sites:Post-smolt transfer to exposed ocean locations reduces sea lice pressure and opens production capacity beyond fjord carrying capacities.
- Online Direct-to-Consumer Channels:E-commerce platforms are capturing subscription-based household segments with traceability storytelling and portion customization.
- Recirculating Aquaculture Systems:Land-based RAS technology enables production proximity to major US and Asian demand centers, decoupling from coastal site scarcity.
Industry Challenges
- Sea Lice Treatment Chemistry:Regulatory restrictions on emamectin benzoate and hydrogen peroxide are narrowing organic certification eligibility windows.
- Genetic Breeding Cycle Timelines:Selective breeding for disease resistance and growth rates requires 4-5 year maturation before commercial-scale deployment.
Report Scope
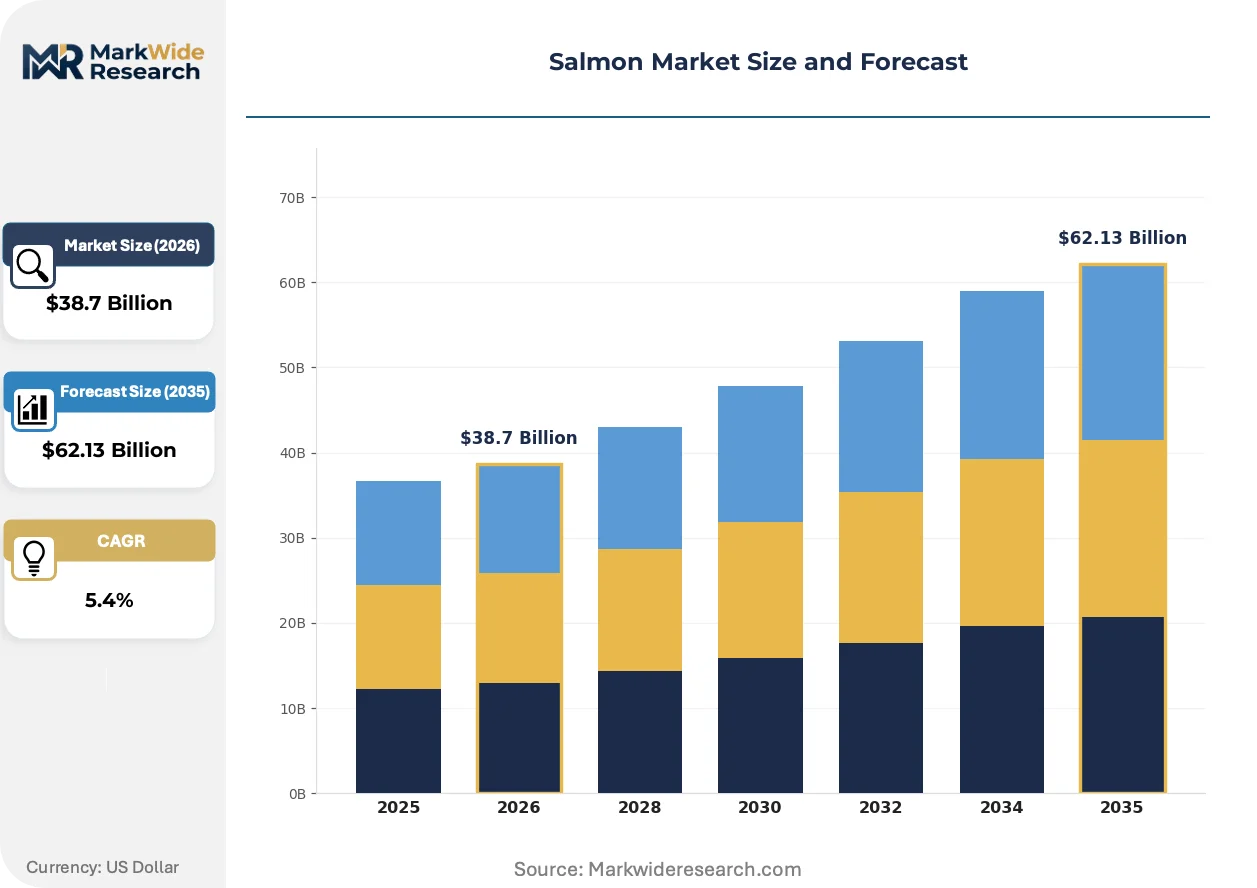
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salmon Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Salmon, Frozen Salmon, Smoked Salmon, Canned Salmon Distribution Channel: Supermarkets, Fishmongers, Online Retail, Food Service End User: Households, Restaurants, Hotels, Catering Services Quality Grade: Premium, Standard, Organic, Farmed |
| Companies Covered | Greig Seafood, Salmones Camanchaca, Mowi ASA, Cooke Aquaculture, Blumar SA, SalMar ASA, Bakkafrost, The Irish Organic Salmon Company, Cermaq Group ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salmon Market Strategic Shifts & Innovations
Digital traceability platforms and automated feeding systems are compressing operational decision cycles across hatchery and grow-out phases, while alternative protein feed sources are disrupting traditional marine ingredient dependence.
Closed-containment semi-closed sea systems are expanding into exposed coastal waters previously considered unsuitable for net-pen farming. Scottish and Canadian operators are deploying these structures to reduce sea lice infestation rates and mortality events. The technology is expanding into premium market segments by enabling antibiotic-free production claims that command retail price premiums.
EU Green Deal sustainability criteria and CSRD disclosure mandates are requiring Scope 3 emissions reporting across aquaculture supply chains. Feed producers must now document embedded carbon in soy and fishmeal sourcing. European retailers are responding by prioritizing suppliers with certified low-carbon production profiles in procurement tenders.
Foodservice buyers are consolidating supplier relationships around single-source traceability platforms that integrate harvest date, feed composition, and transport temperature data. Large European restaurant chains are replacing spot-market purchasing with annual volume contracts tied to ASC certification. This concentration is most visible in German and French foodservice procurement, where sustainability scorecards now determine vendor eligibility.
Salmon Market Segmentation
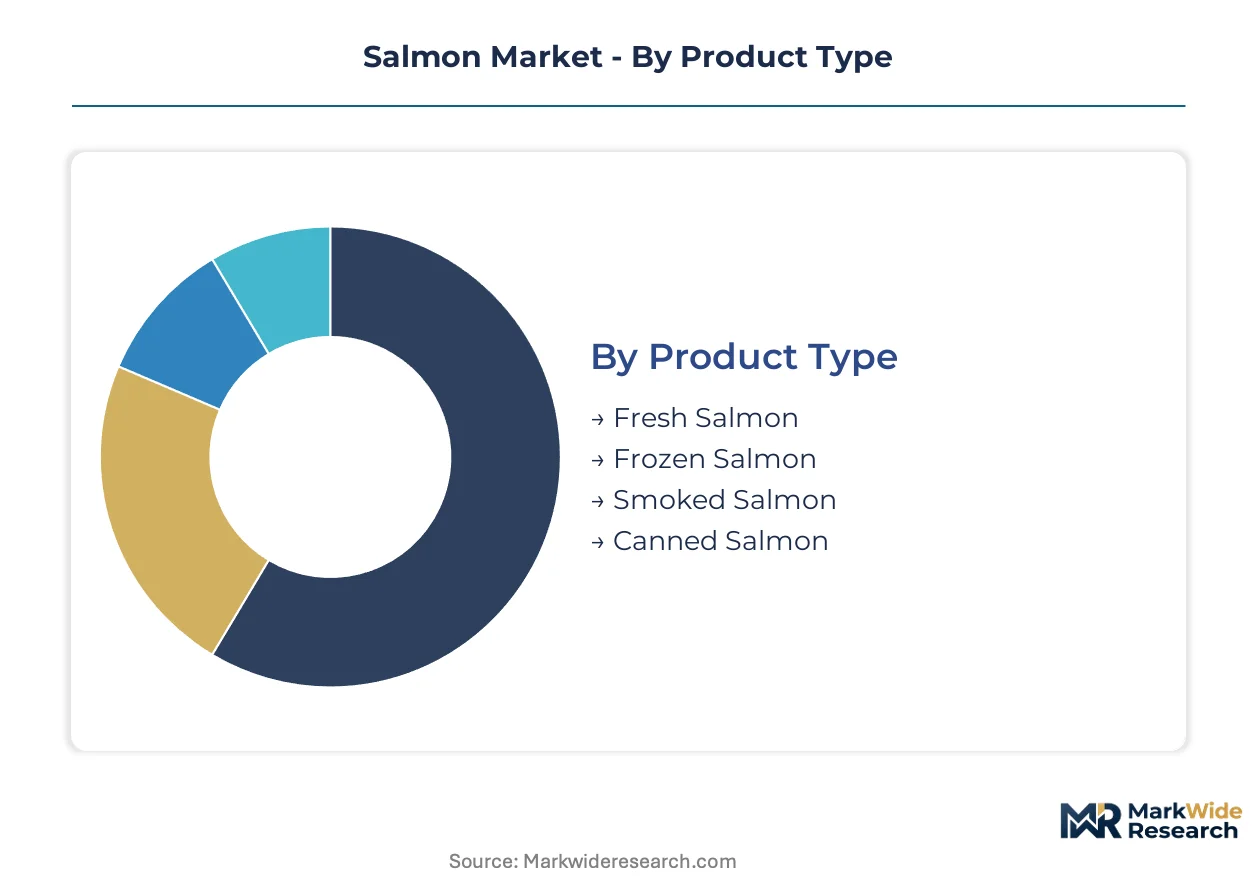
Salmon market segmentation reflects divergent logistics requirements and margin structures across freshness tiers. Product type and distribution channel configurations determine cold-chain investment intensity and certification compliance burdens for producers.
Product Type:
Fresh salmon commands the steepest price premiums but imposes the most severe perishability constraints, while frozen and processed formats trade margin for geographic reach.
- Fresh Salmon:Whole fish and fillets maintained at 0-4°C through harvest-to-retail cold chains define this segment. Norwegian fjord producers dominate supply to German and French supermarket chains, where ASC certification now gates procurement eligibility.
- Frozen Salmon:Blast-frozen at -40°C immediately post-processing, this format extends shelf life to 12-18 months. Demand concentrates in landlocked Central European cities and inland Chinese provinces where fresh distribution remains economically prohibitive.
- Smoked Salmon:Cold-smoked fillets carry higher value-added margins through artisanal processing traditions concentrated in Scotland and Poland.
- Canned Salmon:Retort-preserved product serves price-sensitive segments and emergency stockpiling demand, with Alaskan wild-caught supply anchoring North American production.
Mature deployment sits with fresh salmon. Newer deployment is concentrated in frozen salmon for emerging market penetration.
Distribution Channel:
Channel selection determines traceability investment requirements and direct consumer relationship depth for salmon suppliers.
- Supermarkets:Multi-banner retail chains in Norway, Sweden, and the UK control the largest volume throughput, with pre-portioned fillet bundling now standard across Tesco, Sainsbury's, and ICA Gruppen banners. EU Ecolabel compliance is becoming a mandatory tender condition.
- Online Retail:Subscription-based direct-to-consumer platforms are gaining share fastest among urban households seeking origin transparency and portion customization. German startups and Nordic established players lead this channel's expansion trajectory.
- Fishmongers:Independent specialty retailers maintain relevance in Mediterranean markets through whole-fish butchery services and local provenance claims.
- Food Service:Restaurant and hotel procurement teams are consolidating around annual volume contracts tied to ASC certification, with French and German hospitality chains most advanced in sustainability scorecard implementation.
Volume concentration remains with supermarkets. Margin expansion is concentrated in online retail.
End User:
End-user segmentation separates at-home preparation convenience from out-of-home culinary execution requirements.
- Households:Retail purchasers prioritize ready-to-cook portion formats with embedded cooking instructions, driving pre-marinated and skin-on fillet SKU proliferation across Northern European markets.
- Restaurants:Fine-dining establishments in Copenhagen, Paris, and London specify whole-fish delivery for in-house butchery, while casual dining chains standardize on pre-portioned frozen fillets.
- Hotels:Breakfast buffet and banquet operations favor cold-smoked salmon for labor efficiency and holding stability.
- Catering Services:Event and institutional foodservice demands cost-optimized frozen and canned formats with predictable yield rates.
Procurement sophistication sits with restaurants. Volume scaling is concentrated in households.
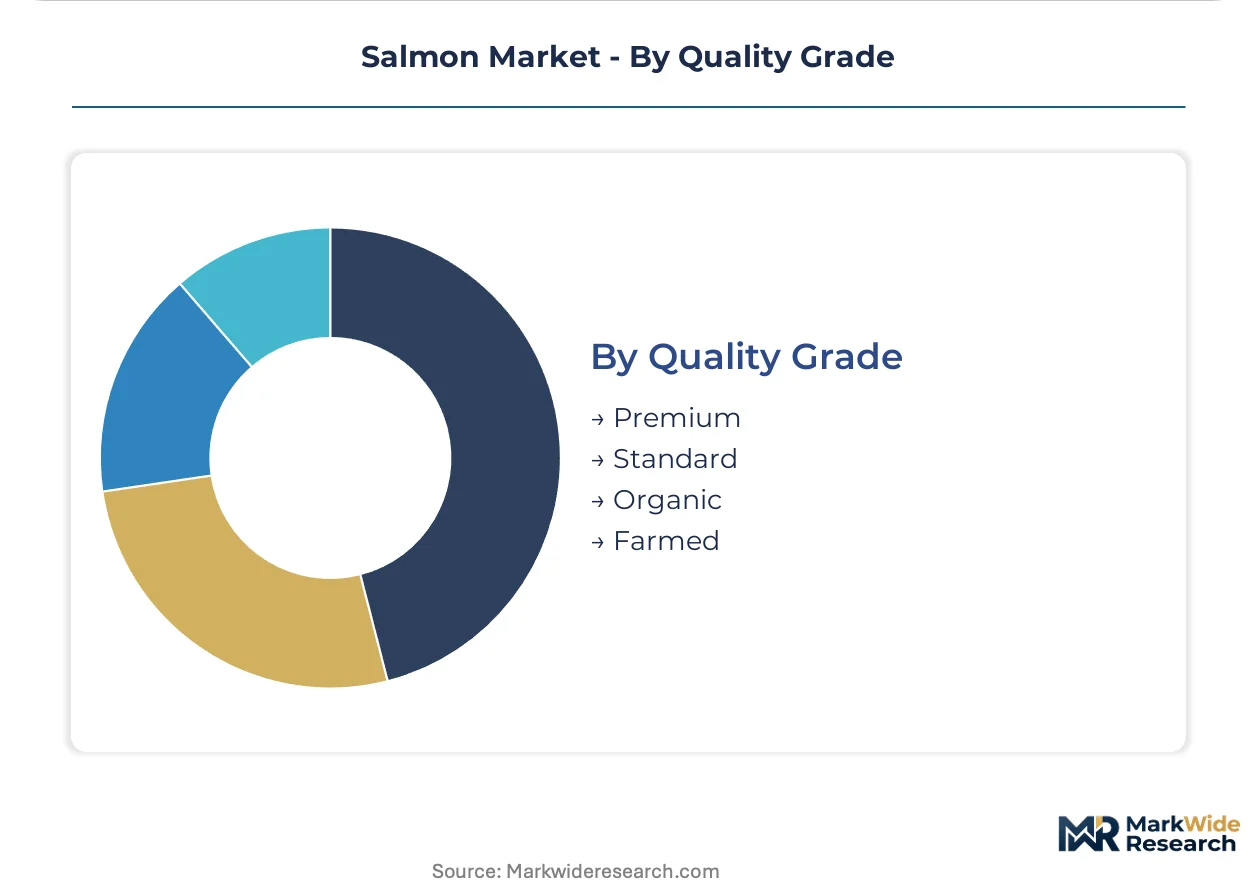
Quality Grade:
Quality tiering reflects certification burden, genetic stock, and farming intensity differences that translate into price stratification.
- Premium:Designated by superior fat content, specific lineage documentation, and restricted harvest windows. Norwegian deep-water farmed salmon and Scottish organic production command this tier.
- Standard:Conventional farmed Atlantic salmon meeting baseline food safety and traceability requirements without specialty certification. This tier supplies mass-market retail and foodservice spot purchasing.
- Organic:Certified production excluding synthetic feed additives and restricted sea lice treatments. EU organic regulations and Debio standards in Norway define compliance boundaries.
- Farmed:General category encompassing all aquaculture-origin salmon, distinct from wild-caught Alaskan and Pacific varieties. Farmed salmon constitutes over 70% of commercially traded volume.
Certification investment sits with organic. Market penetration is concentrated in standard grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway produces the majority of farmed Atlantic salmon while consuming nations cluster in Western Europe and East Asia. This production-consumption divide shapes logistics infrastructure and regulatory diplomacy across the value chain.
Norway
Deep-water fjord sites around Troms and Nordland host integrated feed-to-fork operations controlling premium supply pipelines. The Norwegian Food Safety Authority enforces strict maximum allowable biomass limits per production site, constraining expansion velocity. Bergen anchors the country's processing and export logistics cluster.
Germany
Supermarket chains in Berlin, Hamburg, and Munich drive pre-portioned fresh fillet demand with embedded origin claims. EU Ecolabel compliance gates procurement eligibility for farmed seafood imports. The Hamburg port cluster handles refrigerated cargo distribution to landlocked Central European cities.
United States
Seattle and Boston metropolitan areas concentrate foodservice procurement teams consolidating around ASC-certified annual volume contracts. The FDA and USDA jointly oversee salmon imports with mandatory HACCP compliance for foreign processing facilities. Pacific Northwest hatchery networks supply domestic smolt production.
China
Shanghai and Beijing urban households increasingly subscribe to direct-to-consumer platforms offering traceability storytelling and portion customization. The country's national food safety regulator enforces import inspection protocols for cold-chain seafood. Dalian and Qingdao process frozen salmon for inland province distribution.
United Kingdom
Scottish coastal waters host organic-certified farms commanding retail price premiums through antibiotic-free production claims. The UK's food standards agency implements post-Brexit import controls diverging from EU Ecolabel frameworks. Grimsby and Peterhead anchor smokehouse processing traditions for value-added exports.
Salmon Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across feed, farming, and processing tiers. Market structure tilts toward consolidation around integrated producers with captive hatchery networks and deep-water site licenses. Three archetypes dominate: Norwegian fjord-based integrated giants, North American regional processors, and Chilean volume exporters. Competitive moves center on M&A for coastal licensing access and strategic partnerships for alternative feed sourcing.
Among Norwegian-based integrated producers, Mowi ASA and SalMar ASA exemplify the feed-to-fork archetype with control spanning smolt production through retail distribution. Cooke Aquaculture anchors North American positioning through vertically owned hatchery and processing assets. These three occupy positions where traceability investments and certification compliance create procurement advantages in EU and US foodservice channels.
| Leading Market Players |
|---|
| Greig Seafood |
| Salmones Camanchaca |
| Mowi ASA |
| Cooke Aquaculture |
| Blumar SA |
| SalMar ASA |
| Bakkafrost |
| The Irish Organic Salmon Company |
| Cermaq Group ASA |
| Others |
Cost & Logistics Intelligence
Fjord-based aquaculture technicians in Troms and Nordland command wage premiums that widen spreads between premium ASC-certified fillets and standard-grade alternatives. Labor-cost differentials between integrated Norwegian producers and non-integrated Chilean operators feed directly into retail price stratification across European supermarket banners.
Pricing Analysis
Margin tightening in standard-grade Atlantic salmon traces to Peruvian anchovy harvest volatility and fishmeal price spikes. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence, with ASC and EU Ecolabel compliance adding procurement overhead. Price differentiation hinges on genetic stock documentation and restricted harvest windows for premium tiers. Household segments in landlocked Central European markets exhibit highest price sensitivity, while fine-dining procurement teams in Copenhagen and Paris absorb premiums for whole-fish traceability.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale restaurant chain demand through annual volume contracts tied to ASC certification. Supply concentrates in Norway, Chile, and Scotland, with Norwegian fjord sites controlling premium Atlantic salmon pipelines. Raw material dependencies center on marine-derived fishmeal, fish oil, and soy protein concentrates for feed formulation. Single-source vulnerability around Peruvian anchovy quotas creates margin unpredictability for non-integrated growers. Distribution runs through refrigerated cargo networks from Bergen and Peterhead to Hamburg and Grimsby processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coastal licensing bottlenecks in Norway constrain biomass expansion regardless of capital deployment, propping pricing power for license-holding incumbents. Maximum allowable biomass limits function as a structural capacity ceiling insulating margins.
For Market Incumbents: Cement feed-to-fork traceability investments to defend procurement relationships with EU foodservice chains consolidating around ASC-mandated annual contracts. Deepen backward integration into hatchery networks to secure smolt supply against genetic breeding cycle delays. Prioritize offshore deep-water site licenses to bypass fjord carrying capacity constraints and expand production footprint. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting urban households in Shanghai and Beijing seeking portion customization and origin transparency. Penetrate landlocked Central European cities where fresh distribution gaps create frozen salmon white space. Position around RAS technology to decouple from coastal site scarcity and serve US and Asian demand centers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated Norwegian producers given EU Ecolabel tightening and foodservice procurement consolidation. Long-term viability favors archetypes with captive hatchery networks and deep-water site licenses over volume-exposed Chilean exporters. Monitor sea lice treatment chemistry restrictions as inflection indicator for organic certification eligibility windows.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Deep-Water Site Licensing | SalMar ASA's exposed ocean farming technology bypasses fjord biomass caps. |
| Recirculating Aquaculture System Deployment | Land-based production decouples from Norwegian coastal licensing scarcity. |
| Alternative Protein Feed Sourcing | Soy and insect-based formulations reduce Peruvian anchovy quota dependence. |
| Digital Traceability Platform Integration | Harvest-to-retail data streams satisfy EU CSRD Scope 3 disclosure mandates. |
| Closed-Containment Semi-Closed Sea Systems | Scottish and Canadian operators deploy antibiotic-free production for retail premiums. |
Research Approach
Trade flow databases, customs records, and ASC certification registries formed the secondary backbone for volume and trade pattern validation. Primary interviews with hatchery operations managers, feed procurement directors, supermarket category buyers, and foodservice sustainability officers triangulated against secondary sources. Bottom-up smolt production counts and top-down export value aggregation reconciled through iterative cross-validation.
Historical trendline analysis of Norwegian export volumes and EU import values established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across product type, distribution channel, quality grade, and end-user archetype. CAGRs derived from regression analysis of biomass expansion rates against maximum allowable biomass regulatory ceilings. Feed input cost indices and sea lice treatment chemistry restriction timelines served as industry-specific forecast modifiers.
Peruvian anchovy quota volatility, EU Ecolabel criteria revisions, and sea lice treatment regulatory restrictions are the dominant revision risks for forecast accuracy. Forecasts reflect assumptions around licensing regime stability and cold-chain infrastructure expansion in landlocked markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Europe Salmon Market
Seafood
Oyster Market
Seafood
Sea Bream Market
Seafood
Molluscs Market
Seafood
Japan Lobster Market
Seafood
Caviar Market
Seafood
Trout Market
Seafood
Fish Protein Concentrate Market
Seafood
Global Commercial Fishing Market
Seafood
Organic Shrimp Market
Seafood
Rainbow Trout Market
Seafood
United States Lobster Market
Seafood
Canned Tuna Market
Seafood
South America Canned Seafood Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market