
 Fish Protein Market | 2026-2036
Fish Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Protein Market Analysis
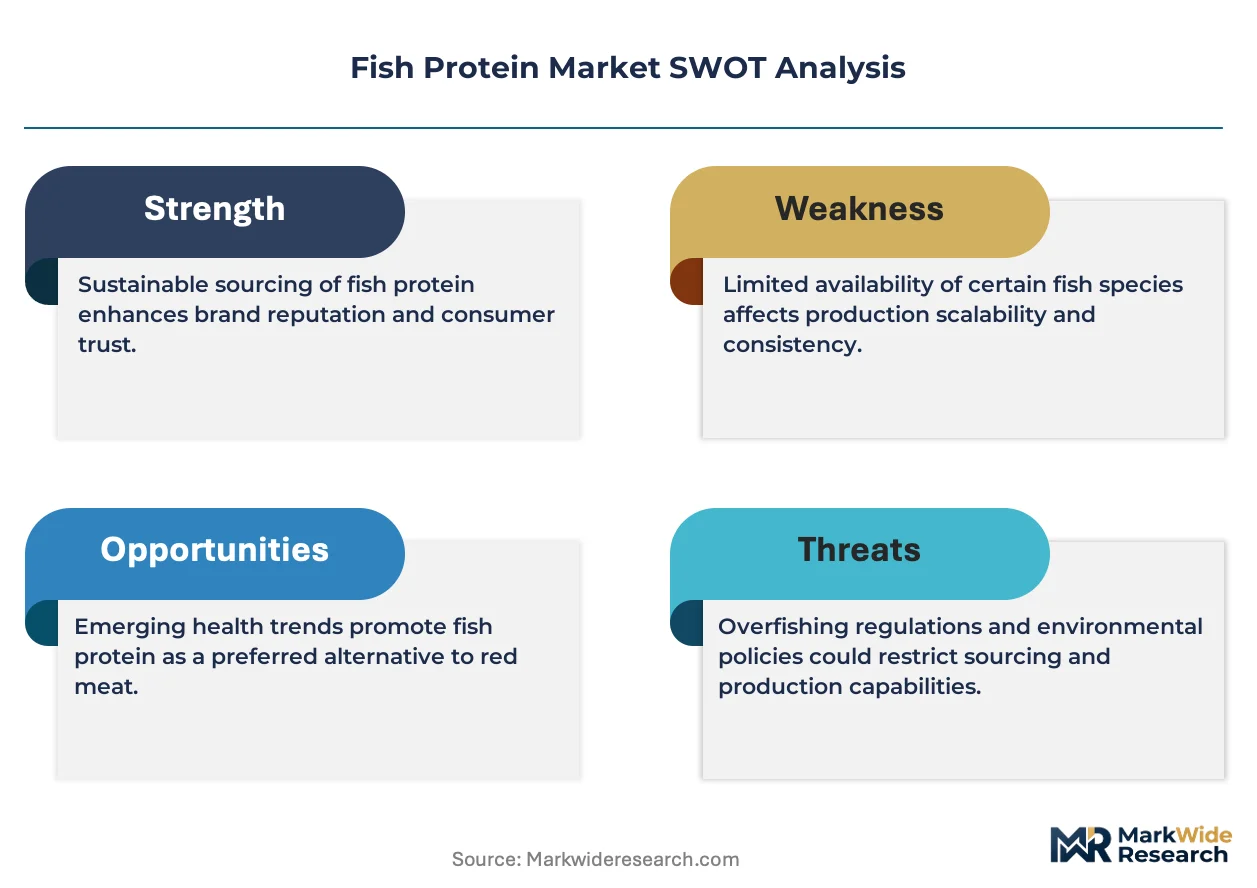
A capital-intensity divergence between integrated marine harvesters and specialized biotech refiners is reorganizing competitive dynamics in fish protein supply. Omega Protein Corporation leverages vertical integration across Gulf of Mexico menhaden fisheries to control raw material throughput from catch to concentrate. Diana Aqua anchors European demand through its specialized hydrolysate portfolio for premium aquafeed formulations. Aker BioMarine AS competes in Antarctic krill-derived protein segments, extending its polar logistics network into high-value human nutrition channels.
Fish protein encompasses concentrated or isolated nitrogenous compounds extracted from whole fish, trimmings, or processing byproducts through mechanical pressing, solvent extraction, or enzymatic hydrolysis, yielding products with protein content ranging from 60% in fish meal to over 90% in isolates. These ingredients serve primarily as functional nutrition inputs for animal feed, human dietary supplements, and formulated food systems where amino acid completeness and bioavailability matter. Fish meal retains structural dominance in aquaculture feed economics due to its cost-positioned protein density and long-established inclusion protocols for salmon and shrimp diets. Fish protein isolate commands premium positioning in human nutrition applications, where powder and capsule forms capture margin pools from sports nutrition and clinical dietary management segments. Liquid hydrolysates within the form dimension are gaining traction in pet food palatability systems and specialized calf milk replacers.
FDA oversight of seafood allergen labeling and GRAS notifications shapes human-grade fish protein market access in the United States, while EFSA sets maximum residue limits for environmental contaminants that determine which raw material streams qualify for European food and feed applications. EU F-Gas Regulation and national cold-chain efficiency standards in Norway indirectly influence processing economics by dictating refrigeration infrastructure investments at extraction facilities. Stakeholders must monitor how evolving marine stewardship certifications interact with national quota allocations to determine which supply basins will remain economically viable for sustained protein recovery operations.
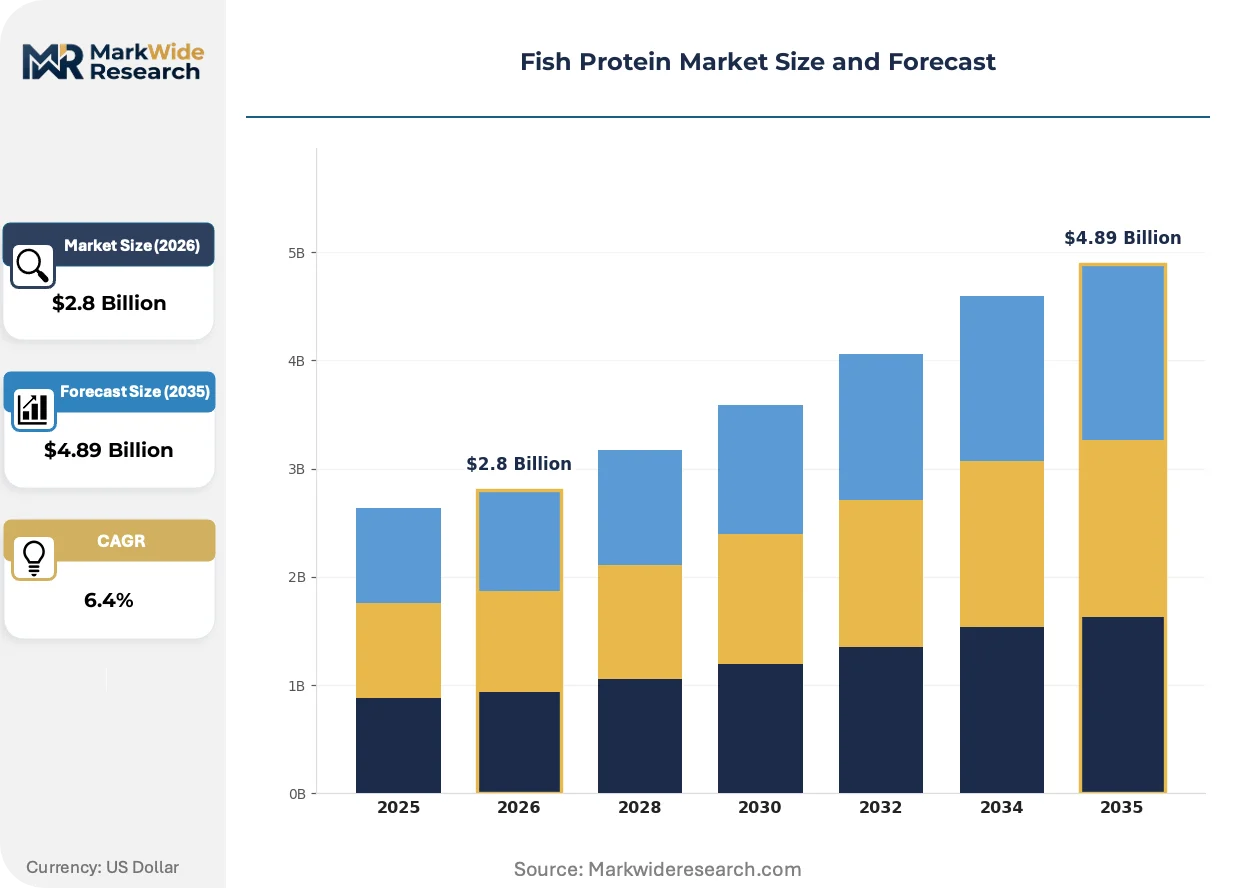
Market Dynamics
Enzymatic hydrolysis is displacing solvent extraction as the dominant recovery method, driven by EU REACH heavy-metal thresholds that disqualify legacy chemical processes from food-grade certification. This technology shift compresses capital returns for conventional fish meal processors while opening margin pools for biotech refiners with fermentation capabilities.
Growth Catalysts
- Sports nutrition clean-label mandates:North American brands are reformulating with hydrolyzed fish protein isolates to replace dairy and soy allergens in premium powder lines.
- EU F-Gas Regulation:Cold-chain efficiency standards in Norway are accelerating ammonia-based refrigeration retrofits at coastal extraction facilities, reducing energy cost per kilogram of isolate output.
- Aquaculture feed amino acid completeness:Salmon and shrimp producers in Chile and Vietnam are locking multi-year contracts for fish meal to secure lysine and methionine profiles that plant proteins cannot replicate.
Market Restraints
- Wild catch quota volatility:Peruvian anchovy biomass fluctuations and El Niño cycles create raw material scarcity that propagates through global fish meal pricing.
- Antarctic krill harvest concentration:Polar logistics networks control over 80% of krill-derived protein capacity, creating single-source dependency for human nutrition applications.
- Heavy-metal bioaccumulation:EFSA maximum residue limits for mercury and cadmium disqualify predatory species from European food-grade streams, constraining eligible raw material pools.
Strategic Opportunities
- Pet food palatability systems:Liquid hydrolysates are penetrating premium dog and cat formulations in the United States as palatants that mask bitter active pharmaceutical ingredients.
- India aquafeed infrastructure:Shrimp farming expansion in Andhra Pradesh and Gujarat is outpacing domestic fish meal supply, creating import substitution potential for organized processors.
- Enzyme immobilization technology:Fixed-bed reactor systems are enabling continuous hydrolysis with 40% lower enzyme consumption than batch methods, compressing unit economics for mid-scale refiners.
Industry Challenges
- Marine stewardship certification timelines:MSC chain-of-custody audits require 12-18 month documentation periods that delay market access for new harvester-processor verticals.
- Fermentation scale-up capex:Commercial enzymatic hydrolysis lines demand stainless steel bioreactor investments that strain balance sheets below 5,000-ton annual throughput.
- Cross-contamination protocols:FDA seafood allergen labeling rules require dedicated production suites that prevent shared equipment with crustacean or mollusk lines, inflating facility costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Protein Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Meal, Fish Oil, Fish Protein Concentrate, Fish Protein Isolate End User: Aquaculture, Nutrition Supplements, Food Industry, Pet Food Form: Powder, Liquid, Granules, Capsules Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Omega Protein Corporation, Diana Aqua, Hofseth BioCare, Bio-Marine Ingredients Ireland, Copalis Sea, Nutreco N.V., Cargill Incorporated, Aker BioMarine AS, BioMar A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Protein Market Emerging Trajectories
Processing technology is fragmenting into two parallel tracks: high-volume mechanical pressing for commodity feed applications and precision enzymatic systems for human nutrition. This divergence is compressing mid-tier solvent extraction capacity while rewarding specialists with fermentation expertise.
Membrane filtration is bifurcating the isolate production landscape. Ceramic ultrafiltration systems now separate peptide fractions by molecular weight, enabling targeted bioactive concentrates for clinical nutrition. Sports nutrition brands in Germany and the United States are adopting these fractionated isolates at triple the rate of standard hydrolysates. The technology is compressing commodity protein margins while opening pharmaceutical-grade pricing tiers.
EFSA contaminant thresholds are tightening extraction protocols across European processing clusters. New maximum residue limits for dioxins and PCBs in fish oil coproducts are forcing processors to divert marginal raw materials to feed-grade streams exclusively. Norwegian facilities near Bergen are responding with real-time mass spectrometry screening at intake points, rejecting batches before they enter food-grade production lines.
Direct procurement contracts are displacing spot-market purchasing among large aquafeed compounders. Cargill and BioMar are locking three-to-five-year offtake agreements with Peruvian and Mauritanian reduction fisheries, securing volume certainty at the expense of price flexibility. This behavioral shift is most visible in Chilean salmon feed economics, where integrated producers now trade formula pricing for supply security.
Fish Protein Market Segmentation
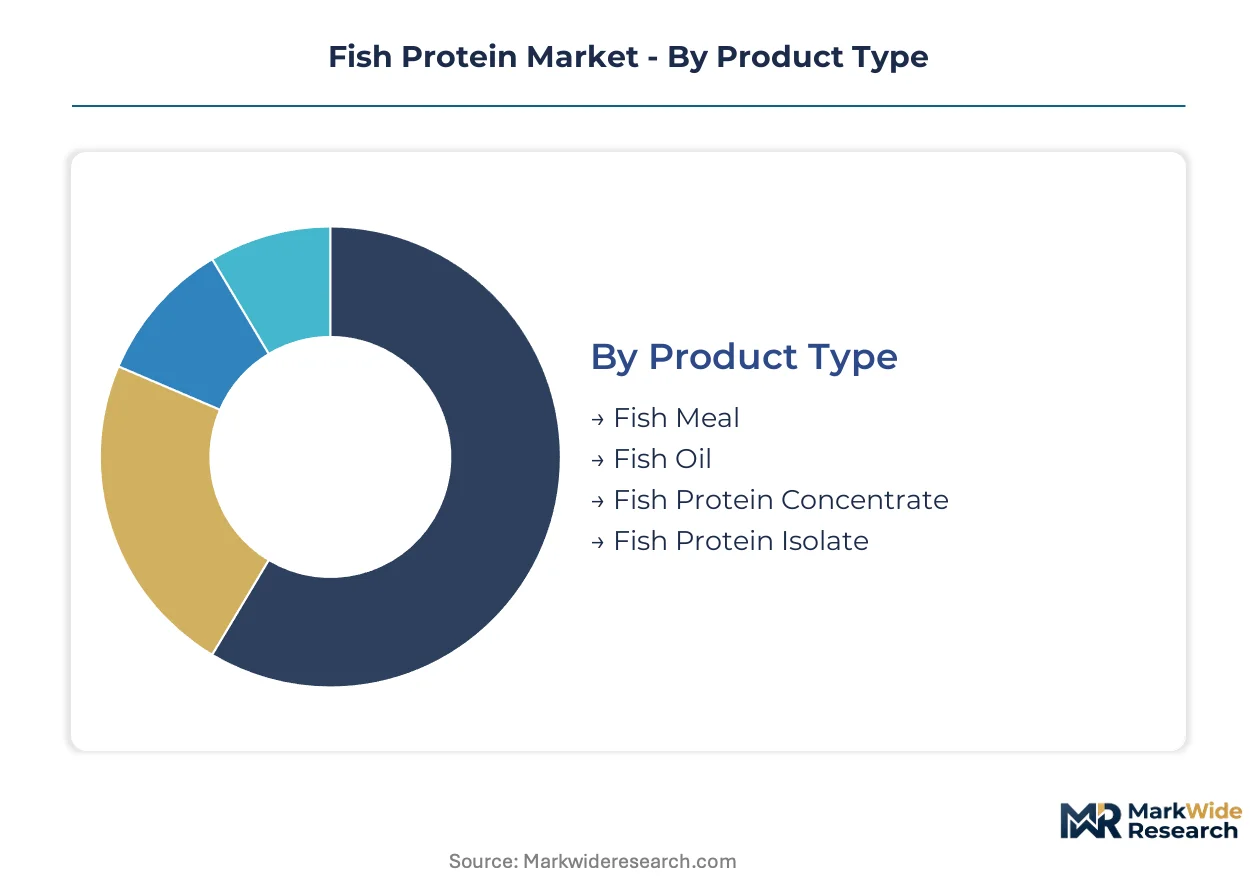
Fish protein segmentation reveals divergent vulnerability profiles across product tiers. Commodity grades face mounting pressure from plant-based alternatives, while isolate and concentrate fractions defend position through functional specificity that soy and pea proteins cannot replicate.
Product Type:
Substitution pressure intensifies along the value chain, with commodity products absorbing the heaviest competitive fire from alternative proteins.
- Fish Meal:Ground and dried whole fish or trimmings yielding 60-70% crude protein content, standardized for amino acid density in compound feeds. Demand concentrates in Chilean salmon farming operations and Vietnamese shrimp hatcheries, where lysine and methionine completeness justifies premium inclusion rates despite volatile Peruvian anchovy supply.
- Fish Protein Isolate:Refined through enzymatic hydrolysis and membrane filtration to exceed 90% protein purity with minimal fat and ash. Sports nutrition brands in Germany and the United States are scaling purchases for clean-label powder formulations that exclude dairy and soy allergens.
- Fish Oil:Pressed or solvent-extracted lipid fraction rich in omega-3 fatty acids EPA and DHA, co-produced with protein meals.
- Fish Protein Concentrate:Intermediate grade at 70-85% protein content, positioned between commodity meal and premium isolate for mid-tier aquafeed and pet food applications.
Fish meal retains volume leadership; fish protein isolate holds the steepest expansion curve.
End User:
Cost tier stratification separates feed-grade commodity buyers from clinical and premium nutrition purchasers willing to absorb isolate premiums.
- Aquaculture:Salmon and shrimp producers in Norway and Chile dominate procurement, locking multi-year offtake contracts with Peruvian reduction fisheries to secure lysine-complete formulations.
- Nutrition Supplements:Powder and capsule formats for sports recovery and clinical dietary management, where bioavailability metrics command pricing power over commodity alternatives.
- Food Industry:Functional protein inputs for surimi, processed seafood, and texture-modified formulations in Japan and South Korea.
- Pet Food:Palatability systems leveraging liquid hydrolysates to mask bitter active pharmaceutical ingredients in premium therapeutic diets.
Aquaculture commands absolute volume share; nutrition supplements are climbing the fastest.
Form:
Application requirements dictate form selection, with powder and liquid fractions diverging toward distinct end-use channels.
- Powder:Spray-dried hydrolysates and isolates dominate sports nutrition and clinical supplement manufacturing, where solubility and flow properties determine processing economics.
- Liquid:Unconcentrated hydrolysates serve pet food palatant systems and specialized calf milk replacers, where direct pumpability eliminates reconstitution steps.
- Granules:Agglomerated meal forms for aquafeed pelleting lines, optimizing bulk density and dust control during pneumatic conveying.
- Capsules:Encapsulated isolates for clinical dietary management and precision-dosed supplement regimens.
Powder maintains production dominance; liquid hydrolysates are expanding most quickly in pet food channels.
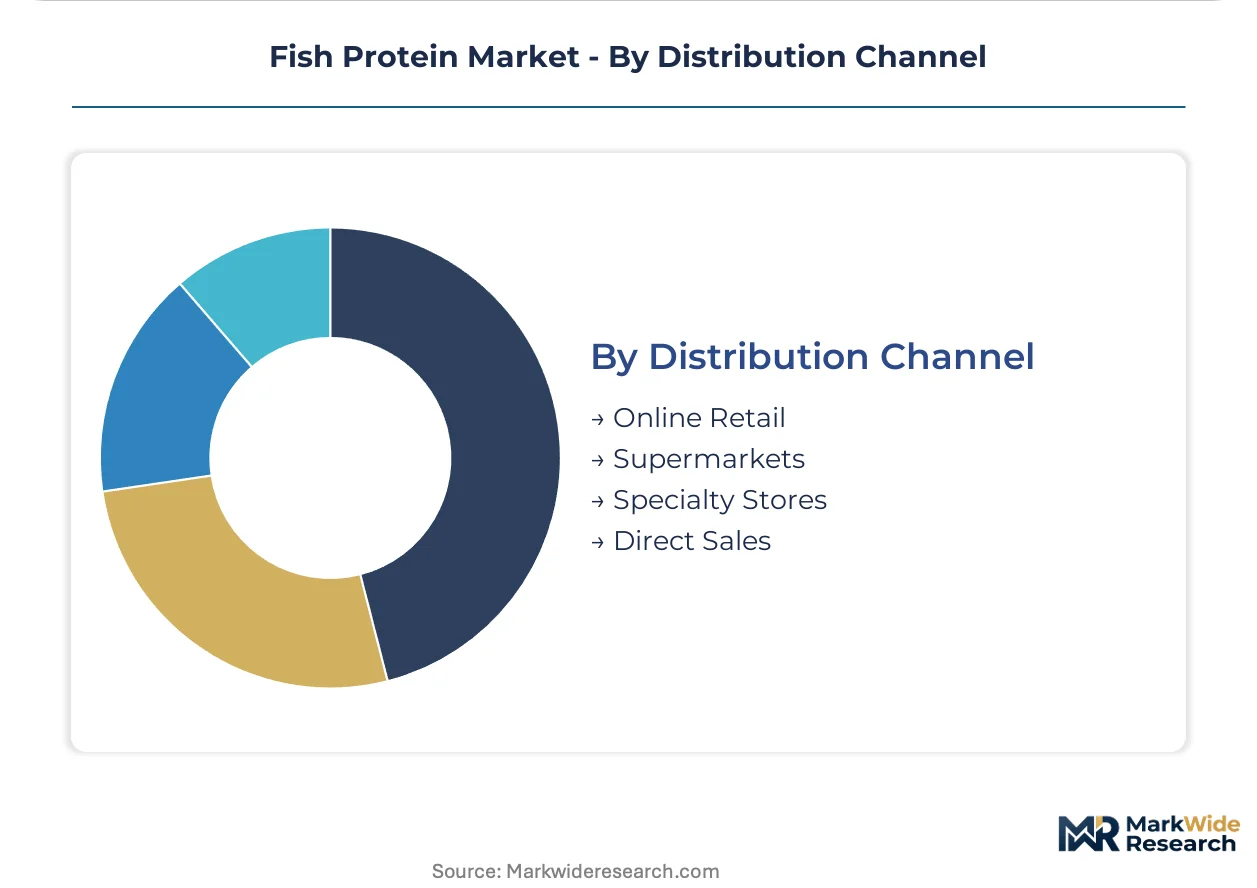
Distribution Channel:
Customer type and purchase scale reshape channel configuration, with institutional buyers bypassing retail entirely.
- Direct Sales:Long-term supply agreements between reduction fisheries and aquafeed compounders, displacing spot-market purchasing for volume certainty.
- Specialty Stores:Premium isolate and supplement products targeting sports nutrition consumers in Germany and the United States.
- Online Retail:Direct-to-consumer powder and capsule sales, accelerated by subscription models for clinical dietary management.
- Supermarkets:Limited presence for commodity meal and oil; marginal shelf space for finished supplement products.
Direct sales anchor institutional procurement; online retail is gaining share fastest in human nutrition segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway concentrates human-grade isolate demand through sports nutrition channels, while Peru and Chile anchor aquafeed commodity flows; this consumption-mix differential shapes investment patterns across extraction technologies and cold-chain infrastructure.
Norway
Coastal processing clusters around Bergen and Ålesund drive enzymatic hydrolysis capacity expansion for premium isolate output. EU F-Gas Regulation mandates ammonia-based refrigeration retrofits, compressing energy costs per kilogram. Marine research institutes co-located with extraction facilities accelerate peptide fractionation technology transfer to commercial operators.
Peru
Anchovy reduction fisheries supply lysine-complete fish meal to Chilean salmon producers through multi-year offtake contracts. El Niño-driven biomass volatility triggers raw material scarcity that propagates through global pricing benchmarks. Callao port infrastructure handles bulk export volumes to Asian aquafeed compounders.
United States
Sports nutrition brands in California and Texas scale hydrolyzed isolate purchases for clean-label powder formulations. FDA seafood allergen labeling and GRAS notification requirements shape human-grade market access protocols. Gulf of Mexico menhaden fisheries support vertically integrated harvest-to-concentrate operations.
Chile
Salmon farming operations in Los Lagos and Aysén regions lock supply contracts for amino acid-complete feed formulations. National quota allocations interact with marine stewardship certifications to determine eligible raw material streams. Puerto Montt processing hubs integrate with Peruvian reduction fishery logistics.
Germany
Sports nutrition and clinical dietary management segments absorb fractionated isolates at triple the rate of standard hydrolysates. EFSA maximum residue limits for mercury and cadmium disqualify predatory species from food-grade streams. Hamburg and Bremen distribution nodes handle membrane-filtered peptide concentrates for pharmaceutical-grade applications.
Fish Protein Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive raw material supplies and the latter competing on fermentation expertise and fractionation technology. The structure rewards backward integration into fishery assets while penalizing mid-scale solvent extraction operators facing REACH compliance costs. Three archetypes dominate: vertically integrated marine harvesters, biotech refiners with enzymatic capabilities, and aquafeed compounders securing supply through long-term contracts. Competitive moves concentrate on capacity expansion in polar logistics networks and strategic partnerships linking reduction fisheries to compound feed formulators.
Among integrated harvester-processors, Omega Protein Corporation exemplifies Gulf of Mexico vertical control from catch to concentrate. Diana Aqua occupies a position within the European hydrolysate specialist tier, while Aker BioMarine AS anchors Antarctic krill-derived protein capacity. These three represent divergent geographic and raw-material strategies within a market splitting between commodity feed economics and premium human nutrition margins.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| Diana Aqua |
| Hofseth BioCare |
| Bio-Marine Ingredients Ireland |
| Copalis Sea |
| Nutreco N.V. |
| Cargill Incorporated |
| Aker BioMarine AS |
| BioMar A/S |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles at Peruvian reduction fisheries compress pricing power for spot-market buyers while amplifying leverage for compounders holding multi-year offtake agreements. This temporal asymmetry between supply-commitment structures and harvest volatility concentrates margin capture among vertically integrated harvester-processors with captive cold-chain infrastructure.
Pricing Analysis
Long-term offtake contracts now govern three-quarters of aquafeed-grade fish meal procurement, displacing spot-market purchasing that once set global benchmarks. Three-tier pricing structure across pharmaceutical-grade isolate, food-grade concentrate, and feed-grade meal separates buyers by certification burden and amino acid completeness requirements. Cost compression in commodity meal tiers is intensifying because plant-protein substitution in shrimp diets is accelerating. Aquaculture compounders exhibit highest price sensitivity, while sports nutrition brands absorb isolate premiums for allergen-free positioning.
Supply Chain Analysis
Callao port congestion during El Niño episodes creates chokepoint vulnerability that propagates raw material scarcity through Chilean salmon feed operations. Supply concentrates in Peru, Norway, and Vietnam, with each node drawing from distinct fishery bases—anchovy, Atlantic cod trimmings, and pangasius byproducts respectively. Enzyme supply for hydrolysis rests on fermentation capacity concentrated in Danish and Dutch biotech clusters. Tariff exposure on Antarctic krill derivatives threatens single-source dependency for human nutrition applications. Distribution runs through direct sales agreements between reduction fisheries and aquafeed formulators, bypassing commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish protein market is recovering from El Niño-driven supply contraction, with biomass normalization in Southeast Pacific fisheries restoring raw material throughput to coastal processing clusters.
For Market Incumbents: Fortify backward integration into Gulf of Mexico and North Atlantic fishery assets to secure captive raw material streams against Peruvian anchovy volatility. Invest in enzymatic hydrolysis certification for EU REACH compliance before 2026 regulatory tightening disqualifies solvent-extraction legacy capacity. Prioritize ammonia-based refrigeration retrofits at Bergen-area facilities to capture F-Gas Regulation energy cost advantages. For New Entrants and Emerging Players: Anchor in Indian aquafeed infrastructure gaps, where shrimp farming expansion in Andhra Pradesh outpaces domestic fish meal supply and import substitution premiums persist. Target pet food palatability systems in the United States, where liquid hydrolysate demand for masking bitter pharmaceutical ingredients remains undersupplied. Pursue toll-manufacturing partnerships with established Norwegian processors to bypass MSC chain-of-custody audit timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine ingredient conglomerates seeking to divest non-core protein recovery assets amid portfolio rationalization pressures. Five-to-ten-year viability hinges on enzymatic capability positioning versus commodity meal exposure. Monitor Antarctic krill harvest quota allocations as inflection indicator for polar logistics network valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Assets | Omega Protein's Gulf of Mexico vertical control secures raw material throughput against Peruvian supply volatility. |
| Enzymatic Hydrolysis Capacity Expansion | Bergen-area facilities capture EU REACH compliance premiums while displacing solvent-extraction competitors. |
| Membrane Filtration Technology Adoption | German sports nutrition brands absorb fractionated isolates at triple standard hydrolysate rates for clinical applications. |
| Direct Sales Agreement Structuring | Cargill and BioMar lock Chilean salmon feed supply security through three-to-five-year Peruvian offtake contracts. |
| Polar Logistics Network Extension | Aker BioMarine leverages Antarctic krill-derived protein capacity into high-value human nutrition channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aquafeed procurement directors, enzymatic hydrolysis plant managers, marine stewardship certification auditors, and sports nutrition brand formulators. Secondary validation drew from customs trade data on fish meal exports, EFSA maximum residue limit determinations, SEC filings of publicly traded marine ingredient processors, and Norwegian Fisheries Directorate harvest statistics. Bottom-up volume modeling across extraction facility throughput combined with top-down GDP-elasticity checks to triangulate market sizing.
Across the analysis window, projections segmented by product grade tier, end-use application, form factor, and regional processing cluster density were constructed. CAGRs were derived from regression analysis against aquaculture production forecasts and sports nutrition category growth trajectories. Key inputs included El Niño Southern Oscillation cycle probabilities, EU F-Gas Regulation implementation timelines, and enzyme immobilization technology adoption curves.
Underlying assumptions cover biomass recovery rates in Southeast Pacific fisheries and REACH compliance cost trajectories for solvent-extraction retrofits, with deviation risk concentrated in Antarctic krill quota reallocation and plant-protein substitution acceleration in Asian shrimp diets. Practitioners should keep alternative scenarios live as marine stewardship certification interaction with national quota allocations evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Octopus Market
Seafood
Organic Seafood Market
Seafood
US Crustacean Market
Seafood
Surimi Market
Seafood
Oyster Market
Seafood
Fish Powder Market
Seafood
Haddock Market
Seafood
Asian Sea Bass Market
Seafood
Europe Dried Scallop Market
Seafood
Seafood Takeout Market
Seafood
Mussels Market
Seafood
Global Shrimp Market
Seafood
Europe Shrimp Market
Seafood
United Arab Emirates Seafood Market
Seafood
Sea Bass Market
Seafood
Fish Meal Market