
 US Crustacean Market | 2026-2036
US Crustacean Market Size, Share, and Industry Trends Forecast 2026-2036
US Crustacean Market Analysis
Processing labor availability in Gulf Coast peeling houses is unwinding historical production bottlenecks, though seasonal visa program constraints still limit peak throughput. Pacific Seafood controls integrated cold-chain logistics from boat to retail case across the West Coast. Louisiana Crawfish Company leverages direct farm-to-restaurant relationships to sustain premium positioning in foodservice channels. Seaview Crab Company dominates Chesapeake Bay blue crab supply through dockside buying stations and custom picking operations.
US crustaceans comprise decapod shellfish species harvested from marine, estuarine, and freshwater environments, typically processed at temperatures near 4°C to preserve muscle protein integrity and prevent histamine formation. The primary commercial purpose centers on human food consumption, with substantial secondary flows into pet food and nutraceutical extraction. Shrimp and crab lead product type volume due to established retail familiarity and versatile menu applications across casual and upscale dining formats. Foodservice channel growth outpaces retail as post-pandemic dining patterns normalize and operators rebuild shellfish-centric menu sections. Frozen processing method holds structural advantage for inventory flexibility and export compliance, though fresh product commands margin premiums in coastal metropolitan markets.
FDA seafood HACCP regulations mandate hazard analysis and critical control point documentation for all domestic and imported crustacean processing, while NOAA fisheries observers enforce quota compliance in federal waters from Maine to Alaska. USDA catfish inspection rules overlap partially with certain freshwater crustacean categories, creating dual-jurisdiction complexity for crawfish processors in Louisiana and Texas. State-level health departments in Florida, California, and Washington impose additional molluscan shellfish tag requirements that extend administratively to crustacean distributors in shared facilities. Stakeholders must monitor evolving traceability mandates under the Food Safety Modernization Act and assess whether blockchain-enabled lot tracking investments will become competitive necessities rather than optional differentiators.
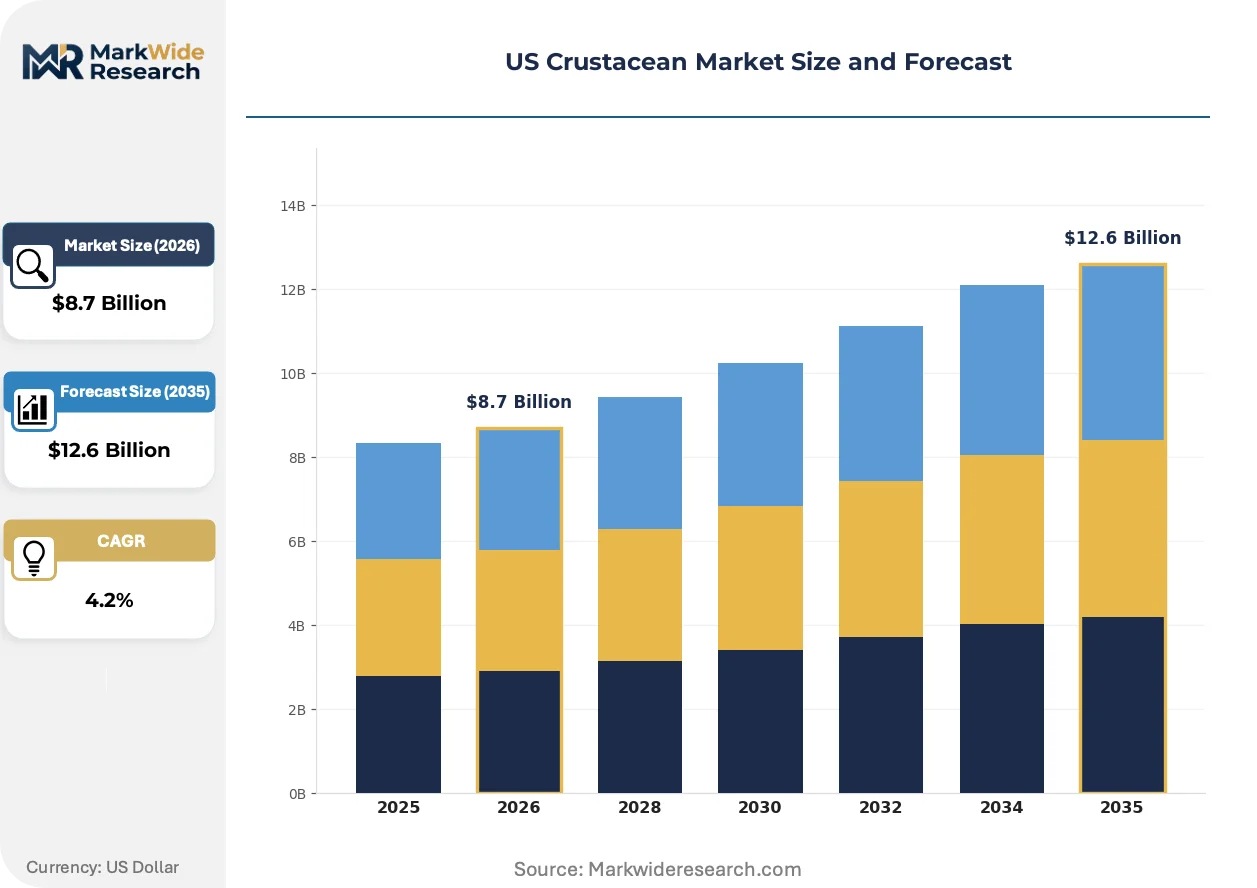
Market Dynamics
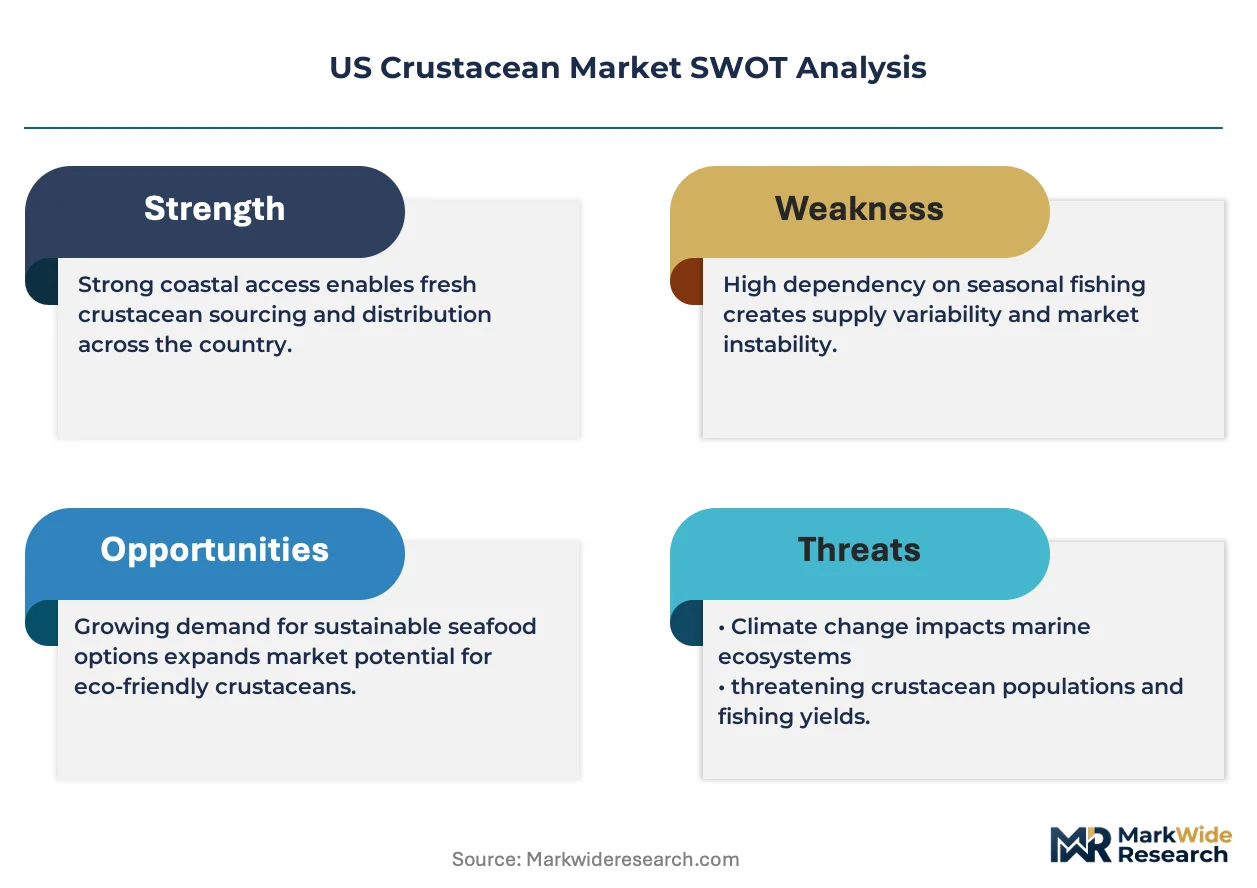
NOAA fisheries observer coverage mandates and FDA HACCP documentation requirements are tightening cold-chain accountability, forcing processors to upgrade traceability infrastructure from dock to retail case. This regulatory compression is reshaping capital allocation across Gulf Coast peeling houses and Chesapeake Bay picking operations.
Growth Catalysts
- H-2B Visa Program Expansions:Seasonal worker allocations for Louisiana and Texas peeling houses are unwinding labor bottlenecks that historically constrained peak throughput during crawfish and shrimp harvest windows.
- Foodservice Menu Rebuilding:Post-pandemic dining normalization is driving quick-service and fine-dining operators to restore shellfish-centric sections, expanding procurement volumes for domestic crab and shrimp suppliers.
- Blockchain Traceability Pilots:FDA Food Safety Modernization Act compliance investments are enabling lot-level tracking from harvest vessel to retail case, satisfying buyer demands for source verification.
Market Restraints
- Feed Input Cost Volatility:Soybean meal and fishmeal price swings in aquaculture supply chains compress margins for Texas and Louisiana crawfish pond operators dependent on formulated feeds.
- Dual-Jurisdiction Complexity:USDA catfish inspection rules overlap with FDA seafood HACCP for certain freshwater crustacean categories, creating administrative friction for processors handling both regulatory frameworks.
- Climate-Driven Harvest Variability:Gulf Coast hypoxic zone expansion and Chesapeake Bay salinity shifts introduce production uncertainty for wild-catch blue crab and shrimp operations.
Strategic Opportunities
- Underpenetrated Inland Markets:Frozen processing infrastructure investments can extend distribution reach to Midwest and Mountain West metropolitan areas currently underserved by fresh product logistics.
- Nutraceutical Extraction Expansion:Chitin and astaxanthin recovery from processing waste streams opens secondary revenue channels for high-volume shrimp peeling operations.
- Direct Farm-to-Restaurant Channels:Bypassing traditional seafood distributors through dockside purchasing agreements captures margin premiums in coastal foodservice markets.
Industry Challenges
- Skilled Peeler Labor Scarcity:Experienced hand-picking specialists for Chesapeake Bay blue crab are aging out of the workforce faster than training programs replenish qualified replacements.
- Cold-Chain Capex Intensity:Maintaining 4°C processing temperatures through blast freezing and refrigerated transport requires continuous equipment upgrades that strain mid-scale operator balance sheets.
- State-Level Tagging Fragmentation:Florida, California, and Washington molluscan shellfish documentation requirements extend administratively to crustacean distributors in shared facilities, multiplying compliance touchpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Crustacean Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lobster, Crab, Shrimp, Prawn Distribution Channel: Retail, Foodservice, Online, Wholesale End User: Restaurants, Households, Supermarkets, Processing Plants Processing Method: Frozen, Fresh, Canned, Dried |
| Companies Covered | Seaview Crab Company, RDM Aquaculture, Louisiana Crawfish Company, Pacific Seafood, Cajun Crawfish Company, Riceland Crawfish, Santa Monica Seafood Company, Crawfish Town U.S.A., The Fresh Lobster Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Crustacean Market Emerging Trajectories
Automation and digital traceability are converging to reshape how crustaceans move from harvest to consumption. These shifts are compressing traditional processing economics while opening new competitive vectors for operators with capital deployment capacity.
High-pressure processing technology is decomposing the historical trade-off between shelf-life extension and texture quality in crab meat products. Mid-scale Chesapeake Bay processors are piloting HPP units at accelerating rates. This equipment deployment is decomposing the frozen-fresh binary that has structured pricing tiers for decades.
FDA seafood HACCP regulations are mandating electronic hazard analysis documentation for all domestic crustacean processing facilities. The industrial consequence is accelerated IT infrastructure spending across Gulf Coast and Mid-Atlantic operations. Smaller peeling houses in Louisiana are consolidating to share compliance costs, shifting competitive position toward scaled operators.
Foodservice procurement patterns are rotating toward shorter-term purchasing agreements with source-verification requirements. Distributors are losing share to direct dockside relationships as restaurant groups build in-house sourcing capabilities. This disintermediation is most visible in Gulf Coast metropolitan markets where crawfish and shrimp aquaculture clusters enable same-day delivery logistics.
US Crustacean Market Segmentation
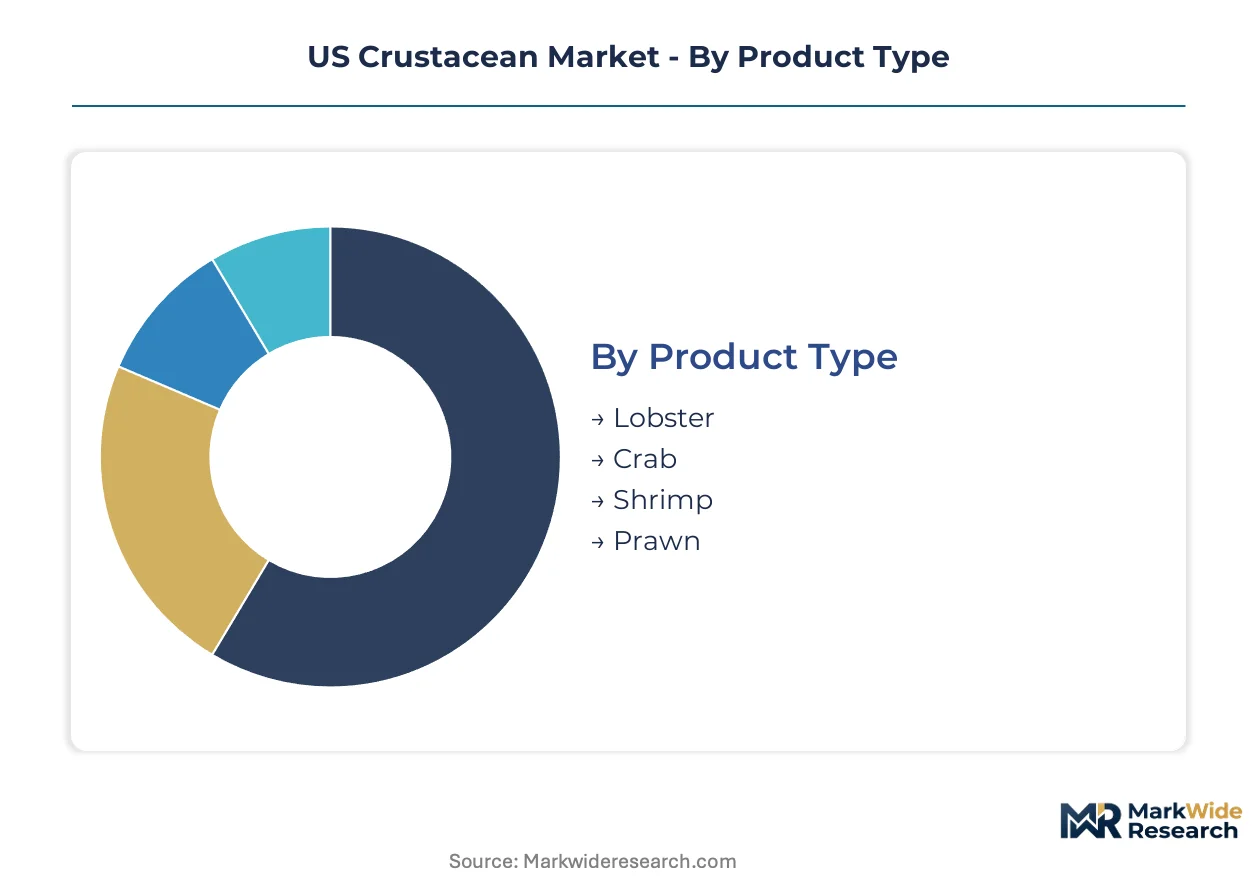
Crustacean procurement patterns diverge sharply across product categories and channel structures, with substitution dynamics between wild-catch and aquaculture supply reshaping competitive economics. Understanding segment-level pressure points reveals where processors must defend margin position against alternative protein sources.
Product Type:
Shrimp faces the most acute substitution threat from imported aquaculture supply, while domestic crab and lobster leverage traceability premiums to resist price-based displacement.
- Shrimp:Penaeid and caridean species dominate US landing volumes, with Gulf brown shrimp and Pacific white shrimp anchoring domestic aquaculture expansion. Louisiana and Texas pond operations concentrate supply for foodservice distributors seeking HACCP-documented domestic sourcing.
- Crab:Callinectes sapidus (blue crab) from Chesapeake Bay and Cancer magister (Dungeness) from Pacific Northwest command structural premiums through hand-picking labor intensity. Maryland and Virginia picking houses face skilled worker scarcity that constrains throughput during peak season.
- Lobster:Homarus americanus from Maine and Massachusetts waters serves high-end foodservice through live-tank distribution networks. Cold-chain mortality rates limit geographic reach beyond coastal metropolitan markets.
- Prawn:Macrobrachium rosenbergii freshwater aquaculture in Texas and Hawaii supplies niche ethnic restaurant demand with shorter supply chains than marine shrimp imports.
Shrimp anchors the volume base while crab gains share at the steepest rate through premium positioning in Chesapeake Bay regional cuisine revival.
Distribution Channel:
Channel cost structures stratify sharply, with direct procurement models compressing traditional distributor margins in coastal markets where dockside access is feasible.
- Foodservice:Quick-service chains and independent restaurants in Gulf Coast metropolitan areas rebuild shellfish-centric menu sections through direct farm relationships that bypass seafood distributors. Post-pandemic dining normalization drives procurement volume recovery.
- Retail:Supermarket seafood counters in inland metropolitan areas depend on frozen processing infrastructure for inventory flexibility. Fresh product penetration concentrates in coastal markets within 48-hour cold-chain reach.
- Wholesale:Broadline distributors consolidate purchasing across multiple species for institutional buyers including hospitals, universities, and corporate cafeterias. Volume commitments enable margin compression through scale.
- Online:Direct-to-consumer platforms extend reach to Mountain West and Midwest markets underserved by traditional seafood retail infrastructure. Cold-chain packaging costs constrain unit economics outside urban delivery zones.
Foodservice channels concentrate procurement volume while online distribution expands most quickly through last-mile logistics investments.
End User:
End-use applications split between immediate consumption and downstream processing, with regulatory compliance intensity varying by operational scale.
- Restaurants:Fine-dining groups in New Orleans, Baltimore, and Seattle metropolitan markets source live product through dockside purchasing agreements. Same-day delivery logistics enable menu flexibility for daily catch variations.
- Processing Plants:Gulf Coast peeling houses and Chesapeake Bay picking operations supply value-added crab meat and shrimp products to retail and foodservice channels. FDA HACCP documentation requirements drive IT infrastructure consolidation among mid-scale operators.
- Supermarkets:Regional chains in Florida and California impose traceability requirements that extend administratively to crustacean distributors sharing facilities with molluscan shellfish operations. State-level tagging mandates multiply compliance touchpoints.
- Households:Direct consumption concentrates in coastal states with established seafood preparation traditions. Frozen retail products extend access to inland markets with limited fresh distribution infrastructure.
Restaurants anchor premium procurement volume while processing plants expand throughput most rapidly through automation investments in peeling and picking operations.
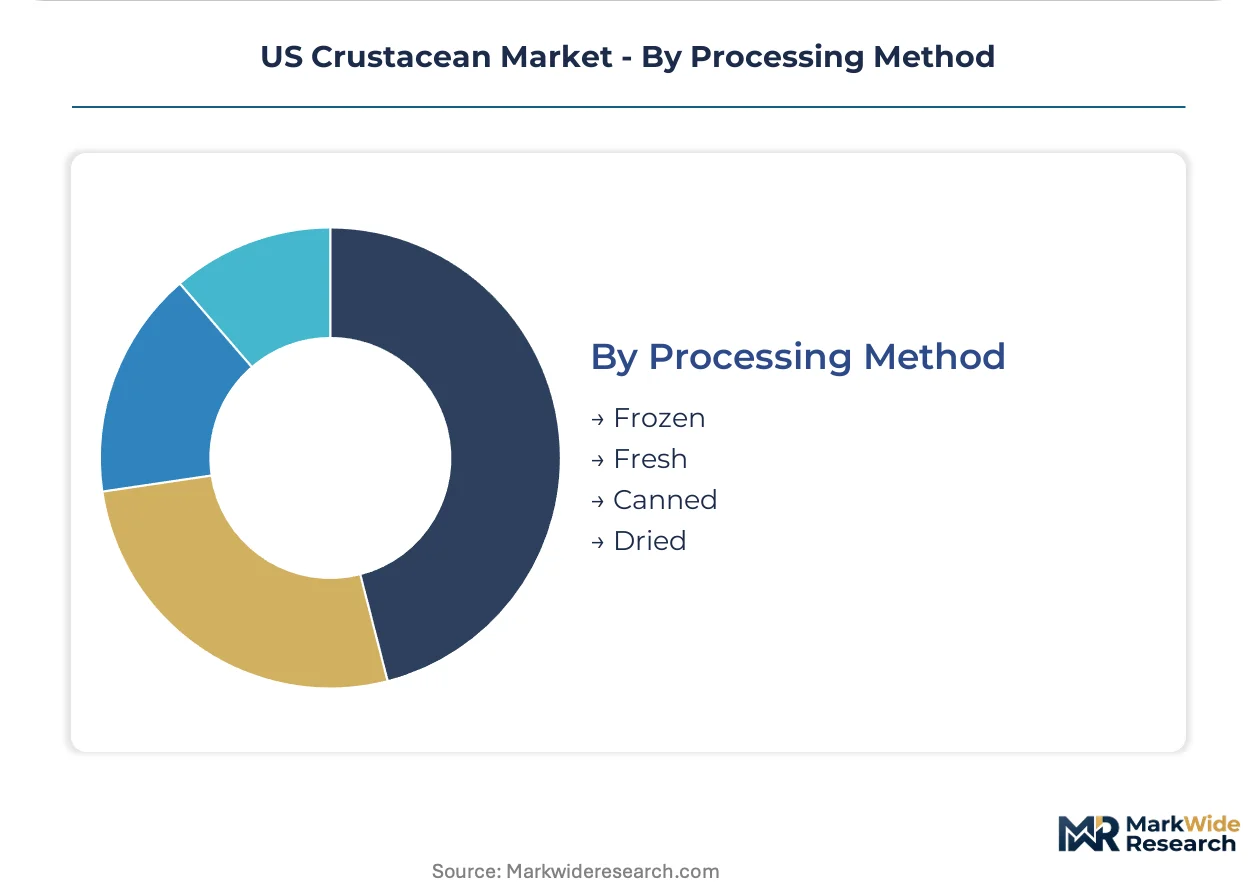
Processing Method:
Processing technology selection determines shelf-life extension economics and export compliance eligibility, with capital intensity favoring scaled operators.
- Frozen:Blast freezing at 4°C preserves muscle protein integrity while enabling inventory flexibility and extended distribution reach to inland markets. Gulf Coast operations invest in continuous freezing lines to capture foodservice procurement volume.
- Fresh:Same-day processing and refrigerated transport command margin premiums in coastal metropolitan markets with established live-tank infrastructure. Cold-chain mortality and spoilage risks constrain geographic expansion.
- Canned:Thermal processing extends shelf life for retail pantry categories with lower per-unit value than frozen or fresh alternatives. Domestic canning operations face import competition from Southeast Asian processors.
- Dried:Traditional preservation for ethnic market segments concentrates in California and Hawaii processing facilities serving Asian-American consumer demand. Limited scale constrains mainstream retail penetration.
Frozen processing anchors supply chain volume while fresh product commands the steepest margin premiums in coastal metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US sub-regions diverge sharply between Gulf Coast live-product traditions and inland frozen-retail dependence, with coastal metropolitan markets commanding premium pricing through same-day dockside logistics.
Gulf Coast
Louisiana and Texas metropolitan markets anchor domestic crawfish and shrimp demand through direct farm-to-restaurant procurement networks. FDA seafood HACCP documentation requirements and NOAA fisheries observer mandates tighten cold-chain accountability across regional peeling houses. Houston and New Orleans foodservice operators bypass traditional distributors through dockside purchasing agreements with pond operators in Acadiana and Southeast Texas aquaculture clusters.
Chesapeake Bay
Maryland and Virginia markets sustain premium blue crab consumption through hand-picked meat traditions in Baltimore and Washington DC metropolitan dining. State-level health departments impose molluscan shellfish tagging requirements that extend administratively to crustacean distributors in shared facilities. Skilled picker labor scarcity in Cambridge and Crisfield constrains peak-season throughput for regional picking houses supplying value-added crab products.
Pacific Northwest
Seattle and Portland metropolitan markets drive Dungeness crab and spot prawn demand through live-tank distribution networks serving fine-dining operators. Integrated cold-chain logistics from boat to retail case enable same-day delivery logistics across coastal Washington and Oregon. Tacoma and Astoria processing facilities face cold-chain capex intensity pressures from continuous equipment upgrades for 4°C temperature maintenance.
New England
Maine and Massachusetts markets concentrate live lobster demand through Boston and Portland metropolitan foodservice channels with established seafood preparation traditions. Cold-chain mortality rates limit geographic reach beyond coastal metropolitan markets for Homarus americanus distribution. Rockland and Gloucester harbor operations maintain live-tank infrastructure for premium procurement by regional restaurant groups.
Southeast Atlantic
Florida metropolitan markets from Miami to Jacksonville sustain diverse crustacean consumption across retail and foodservice channels with state-level tagging fragmentation multiplying compliance touchpoints. USDA catfish inspection rules overlap with FDA seafood HACCP for freshwater crustacean categories, creating dual-jurisdiction complexity for processors handling both regulatory frameworks. Tampa and Fort Lauderdale distributors consolidate purchasing across multiple species for institutional buyers including hospitals and universities.
US Crustacean Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the US crustacean market structure. Gulf Coast and Pacific Coast operations concentrate supply chain control through backward integration into aquaculture ponds and harbor buying stations. Three strategic archetypes dominate: vertically integrated processors with captive supply, regional specialists with direct farm relationships, and broadline distributors consolidating multi-species purchasing. Competitive moves center on cold-chain infrastructure expansion and direct procurement channel development that disintermediates traditional seafood distribution.
Among Gulf Coast-based specialists, Louisiana Crawfish Company and Cajun Crawfish Company exemplify the direct farm-to-restaurant archetype through regional pond operations and dockside logistics. Pacific Seafood occupies a position representing integrated cold-chain control from harvest vessel to retail case across West Coast markets. Seaview Crab Company anchors the Chesapeake Bay specialist tier through harbor buying stations and custom picking operations. These three operators collectively illustrate how geographic concentration and procurement channel strategy differentiate competitive positioning in domestic crustacean supply.
| Leading Market Players |
|---|
| Seaview Crab Company |
| RDM Aquaculture |
| Louisiana Crawfish Company |
| Pacific Seafood |
| Cajun Crawfish Company |
| Riceland Crawfish |
| Santa Monica Seafood Company |
| Crawfish Town U.S.A. |
| The Fresh Lobster Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Gulf Coast peeling houses and foodservice distributors lock in both supply access and price visibility for brown shrimp and crawfish harvests, insulating processors from spot market volatility while committing buyers to volume minimums through seasonal windows.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Louisiana pond operators and quick-service chains, with spot markets filling residual demand from independent restaurants. Price differentiation hinges on HACCP certification tier and geographic delivery cost, with FDA-documented domestic product commanding premiums over imported alternatives. Cost compression in frozen shrimp is intensifying because Southeast Asian aquaculture supply expands processing capacity. Quick-service chains exhibit highest price sensitivity, while fine-dining groups absorb premiums for traceability-verified live product.
Supply Chain Analysis
Louisiana and Texas anchor domestic crawfish and shrimp aquaculture production, with Chesapeake Bay and Pacific Northwest feeding crab and Dungeness supply. Processing draws from soybean meal and fishmeal inputs, plus specialized blast freezing equipment for 4°C cold-chain maintenance. Single-source vulnerability concentrates in H-2B visa-dependent peeling labor for Gulf Coast operations. Distribution runs through direct farm-to-restaurant channels in coastal metropolitan markets, with broadline distributors consolidating inland frozen product reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution defense against imported aquaculture shrimp, where traceability gaps allow price undercutting despite quality differentials in domestic supply.
For Market Incumbents: Fortify cold-chain infrastructure investments to sustain 4°C integrity from pond to retail case, locking in FDA HACCP compliance premiums that imported competitors struggle to replicate. Deepen backward integration into aquaculture pond operations to capture margin compression from feed input volatility. Channel control through dockside purchasing agreements with restaurant groups defends against distributor disintermediation.
For New Entrants and Emerging Players: Lead with blockchain-enabled lot tracking pilots that satisfy Food Safety Modernization Act traceability mandates, differentiating against legacy operators with paper-based documentation. Target Mountain West and Midwest metropolitan markets where frozen processing infrastructure gaps limit incumbent penetration. Same-day delivery logistics partnerships with regional cold-chain specialists accelerate foodservice channel access without capital-heavy fleet investments.
For Investors and Strategic Acquirers: Regional specialists with direct farm relationships and harbor buying station networks offer consolidation platforms for fragmented Gulf Coast and Chesapeake Bay processing capacity. Long-term viability rests on automation deployment that decomposes labor dependency in hand-picking operations. Watch H-2B visa allocation volumes as inflection indicator for peak-season throughput constraints at target operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | 4°C blast freezing investments enable FDA HACCP compliance for extended distribution reach. |
| Backward Integration into Aquaculture | Pond ownership captures margin from feed input cost volatility in Louisiana and Texas. |
| Blockchain Traceability Deployment | Lot-level tracking satisfies Food Safety Modernization Act mandates for source verification. |
| Direct Farm-to-Restaurant Channels | Dockside purchasing agreements bypass seafood distributors in Gulf Coast metropolitan markets. |
| Automation in Peeling Operations | Mechanical processing decomposes H-2B visa dependency for peak-season throughput. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Gulf Coast pond operators, Chesapeake Bay picking house managers, foodservice procurement directors, and FDA compliance officers; and secondary validation through NOAA fisheries landings data, FDA seafood HACCP inspection records, state health department tagging requirements, and USDA catfish inspection filings. Bottom-up volume estimates from regional processing capacity triangulated against top-down consumption surveys across foodservice and retail channels.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, processing method, distribution channel, and geographic consumption cluster. CAGRs derived from historical landing volume trajectories, aquaculture pond expansion permits, and foodservice menu placement recovery patterns. Forecast inputs incorporated H-2B visa allocation trends and cold-chain equipment capex cycles specific to shrimp peeling and crab picking operations.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or stable H-2B seasonal worker flows would require recalibration. Forecasts reflect assumptions regarding post-pandemic dining normalization and traceability mandate implementation timelines. Recalibration cycles align with material shifts in NOAA fisheries management frameworks and Food Safety Modernization Act compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Tuna Market
Seafood
Processed Seafood Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Canned Anchovy Market
Seafood
Molluscs Market
Seafood
Canned Salmon Market
Seafood
North America Seafood Market
Seafood
United States Salmon Market
Seafood
Europe Shrimp Market
Seafood
United States Plant-Based Seafood Market
Seafood
Seafood Flavors Market
Seafood
Krill Meal Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Middle East Seafood Market
Seafood
Canned Mackerel Market