
 ASEAN Probiotic Supplements Market | 2026-2036
ASEAN Probiotic Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Probiotic Supplements Market Outlook
Market Dynamics
Pharmacy-led distribution in ASEAN is fragmenting as e-commerce platforms and direct-to-consumer models capture shelf space from traditional health stores. Nestle SA leverages its regional dairy and nutrition infrastructure to anchor probiotic supply chains across multiple ASEAN markets. Amway Corporation competes through its direct-selling network, which sustains margin control and consumer education at the point of purchase. BioGaia AB specializes in clinically validated strains, positioning its portfolio toward pediatric and premium adult segments where clinical credibility commands price premiums.
Product and Segment Structure
ASEAN probiotic supplements comprise live microbial preparations, typically delivering colony-forming units in the range of one to fifty billion per dose, formulated for oral consumption to modulate intestinal microbiota and support host metabolic and immune functions. Capsules dominate current volume due to stability advantages in tropical climates, though gummies represent the fastest-growing format as taste-driven adoption spreads among younger demographics and compliance-sensitive consumers. Digestive health anchors application-level revenue, yet immune support commands expanding shelf space as post-pandemic wellness priorities reshape purchase patterns across pharmacies and online retail channels.
Regulatory Environment
ASEAN harmonization initiatives through the ASEAN Harmonization on Cosmetic Regulatory Scheme intersect with national frameworks including Thailand's FDA supplement registration requirements and Indonesia's BPOM halal certification mandates, creating layered compliance obligations for cross-border marketers. The EU-ASEAN Free Trade Agreement negotiations and evolving ASEAN Medical Device Directive interpretations further complicate product classification and health claim substantiation. Stakeholders must monitor divergent strain approval pathways and emerging national labeling standards to preempt market access disruptions.
Market Dynamics
Pharmacy-led distribution across ASEAN is fragmenting under pressure from e-commerce platforms and direct-to-consumer models, forcing traditional health stores to cede shelf space while manufacturers rebuild logistics for tropical stability requirements.
Growth Catalysts
- Thailand's FDA labeling tightening:Reformulation investments are upgrading product quality standards and accelerating premium strain adoption among domestic manufacturers seeking compliance advantage.
- Urban pharmacy networks:Indonesia's metropolitan corridors are deepening probiotic penetration through pharmacist recommendation programs that convert walk-in traffic into repeat purchasers.
- Microencapsulation technology:Advanced coating processes are extending shelf life in humid climates, reducing cold-chain dependency and unlocking rural distribution economics previously considered unviable.
Market Restraints
- Strain registration costs:Indonesia's BPOM mandates multi-year clinical dossiers for novel probiotic strains, creating capital barriers for mid-tier entrants lacking R&D scale.
- Halal certification complexity:Cross-border marketers face divergent national interpretations of fermentation-derived ingredient permissibility, forcing parallel product lines and inventory duplication.
- Refrigeration infrastructure gaps:Last-mile cold-chain deficiencies in the Philippines and Vietnam limit viability of high-CFU liquid formats, constraining format innovation to shelf-stable alternatives.
Strategic Opportunities
- Vietnam's emerging middle class:Ho Chi Minh City and Hanoi corridors show underpenetrated pharmacy channels where early entrants can anchor brand recognition before competitive density increases.
- Gummy format expansion:Palatability-driven adoption among pediatric and geriatric segments is opening compliance-sensitive demographics previously resistant to capsule regimens.
- EU-ASEAN FTA alignment:Negotiations on mutual recognition of health claim substantiation are creating pathways for European strain portfolios to enter with reduced regulatory duplication.
Industry Challenges
- Microbiologist talent scarcity:Qualified strain characterization specialists are concentrated in Singapore and Thailand, forcing Malaysian and Indonesian manufacturers to outsource stability testing at premium rates.
- Legacy ERP integration:Batch-level traceability requirements for ASEAN harmonization are colliding with decades-old inventory systems at family-owned distributors, delaying real-time compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Probiotic Supplements Market |
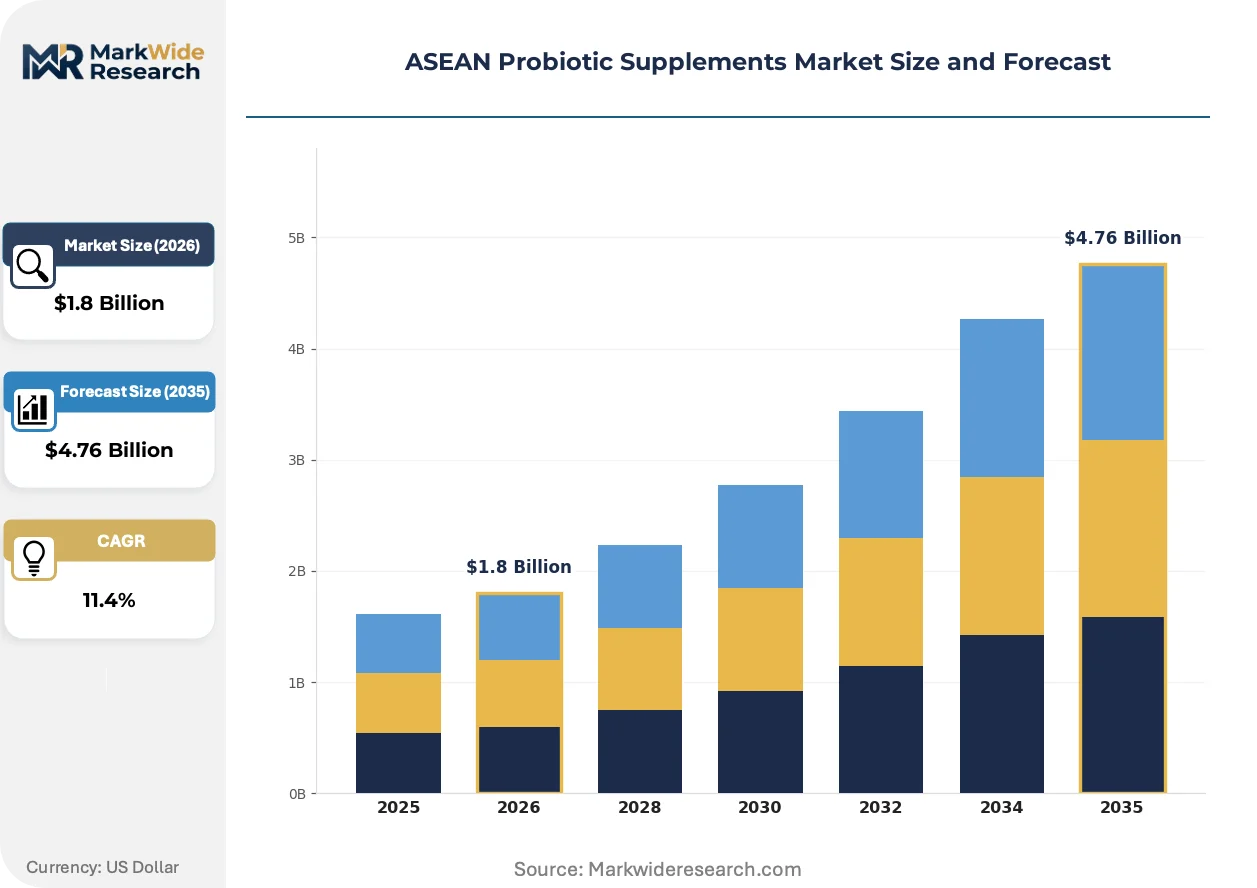
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Gummies, Drinks Application: Digestive Health, Immune Support, Weight Management, Sports Nutrition End User: Adults, Children, Seniors, Athletes Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | GNC Holdings LLC, Reckitt Benckiser LLC, Church & Dwight Co Inc, Nestle SA, Nature's Way Products LLC, Amway Corporation, Pharma Care Laboratories Pty Ltd, BioGaia AB, Procter & Gamble, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Probiotic Supplements Market Strategic Shifts
Digital traceability and climate-adapted formulation science are converging to reshape how probiotic supplements are manufactured, distributed, and verified across Southeast Asia's fragmented regulatory landscape.
Blockchain-enabled supply chain verification is digitizing batch provenance records from fermentation through retail shelf. Major pharmacy chains in Singapore and Bangkok are mandating QR-linked strain documentation for private-label assortment, compressing trust-building timelines for new market entrants. This transparency infrastructure is digitizing quality assurance workflows that previously relied on paper certificates of analysis.
Thailand's Ministry of Public Health has tightened dietary supplement labeling rules, compelling manufacturers to declare specific strain identifiers and CFU counts at end-of-shelf-life rather than manufacture date. Domestic formulators are responding with accelerated stability testing protocols and conservative potency overages. The regulatory friction most affects imported brands lacking local analytical infrastructure, creating compliance-driven consolidation pressure.
Subscription-based replenishment models are displacing traditional pharmacy repurchase cycles among urban Indonesian consumers. Direct-to-consumer platforms in Jakarta and Surabaya are capturing immune-focused buyers through automated delivery scheduling, while pharmacy chains counter with loyalty-program bundling. This channel friction is most visible in immune support segments where purchase frequency exceeds digestive health baselines by significant margins.
ASEAN Probiotic Supplements Market Segmentation
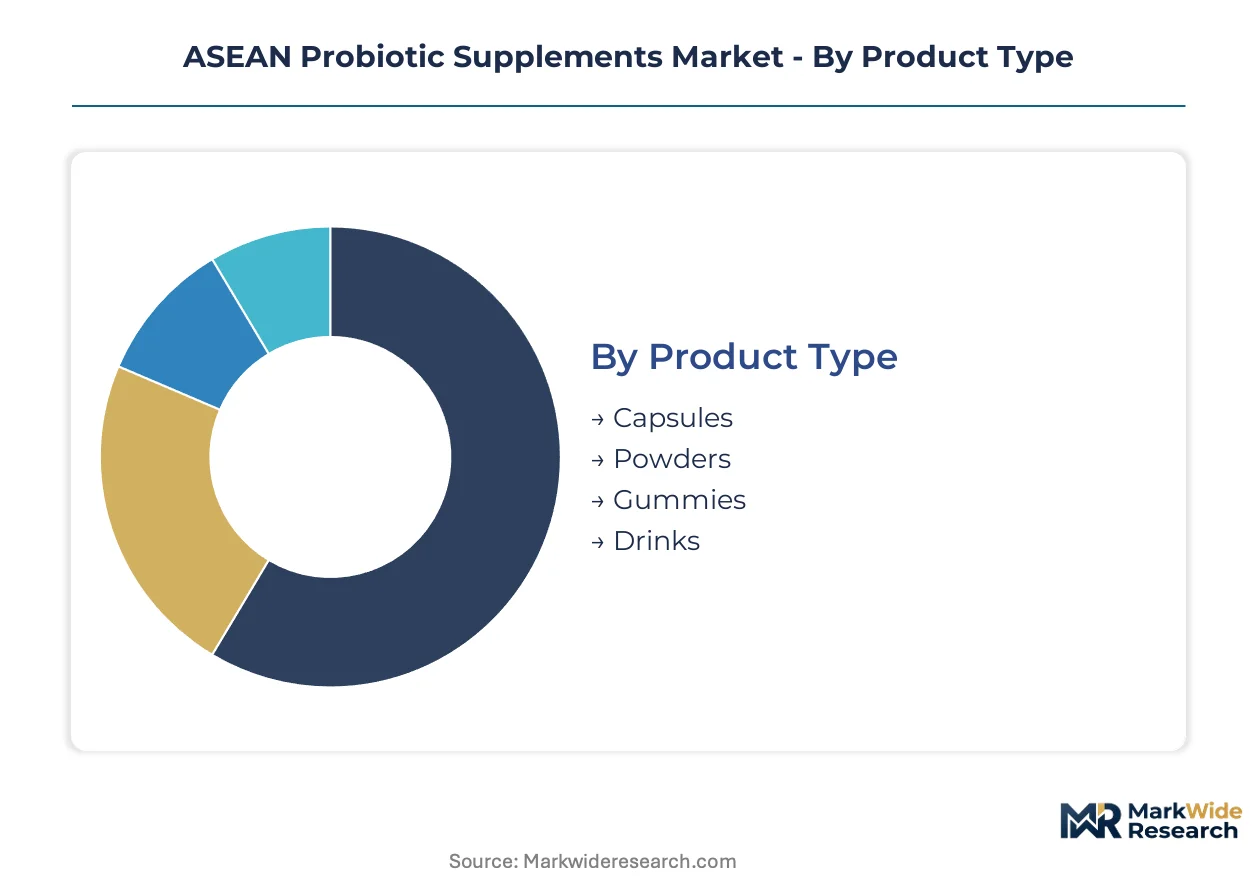
ASEAN probiotic supplements fragment across four structural dimensions that determine formulation priorities, channel economics, and regulatory exposure. Product format stability requirements in tropical climates, combined with divergent national certification mandates, force manufacturers to align segment portfolios with specific country-level infrastructure constraints.
Product Type:
Capsule formats turn inventory fastest in pharmacy channels due to established cold-chain independence, while liquid drinks face extended purchase cycles from refrigeration dependency and shorter shelf stability.
- Capsules:Gelatin or vegetable-based shells containing freeze-dried probiotic cultures with enteric coatings to survive gastric acid. Demand concentrates in Thailand's pharmacy networks where pharmacist recommendations drive repeat purchases despite higher unit prices than alternatives. The format's humidity resistance anchors manufacturer preference for cross-border distribution.
- Gummies:Chewable matrices incorporating pectin or gelatin carriers with flavor masking for pediatric and geriatric compliance. Indonesia's urban e-commerce platforms show the steepest adoption curves as taste-sensitive consumers abandon capsule regimens. Palatability premiums support margin structures 15-25% above baseline formats.
- Powders:Sachet-dried formulations enabling dose flexibility and beverage integration. Malaysian health stores report steady turnover among adult consumers seeking customizable CFU loading.
- Drinks:Liquid fermentation-based products requiring continuous refrigeration. Vietnam's last-mile cold-chain gaps constrain viable distribution to Ho Chi Minh City and Hanoi metro corridors exclusively.
Capsules anchor the volume base while gummies gain share at the steepest rate.
Application:
Margin structures diverge sharply across therapeutic positioning, with immune support commanding shelf-space premiums and digestive health operating on volume-driven economics.
- Digestive Health:Core positioning addressing irritable bowel syndrome, antibiotic-associated diarrhea, and general microbiome maintenance through Lactobacillus and Bifidobacterium strains. Indonesia's pharmacy-led recommendation programs sustain the highest category penetration rates across ASEAN, though price competition intensifies as private-label entrants proliferate.
- Immune Support:Formulations emphasizing IgA stimulation and respiratory defense through specific strains like Lactobacillus rhamnosus GG. Post-pandemic purchase patterns in Singapore and Bangkok show subscription-based replenishment cycles displacing traditional pharmacy repurchase behavior.
- Weight Management:Emerging positioning targeting metabolic modulation and appetite regulation. Thai FDA labeling tightening has forced reformulation investments for satiety claim substantiation.
- Sports Nutrition:Niche segment targeting exercise recovery and protein absorption optimization. Philippine gym-channel distribution remains underdeveloped due to strain registration cost barriers.
Digestive health dominates absolute revenue contribution while immune support expands most quickly through direct-to-consumer channel migration.
End User:
Customer lifetime value calculations favor adult segments with sustained compliance, while pediatric and senior acquisition costs compress as gummy formats reduce taste-driven abandonment.
- Adults:Working-age consumers aged 18-55 with discretionary health spending and established supplement routines. Urban Indonesian professionals drive the highest per-capita consumption through automated subscription platforms.
- Children:Pediatric formulations emphasizing strain safety profiles and palatability compliance. Thailand's Ministry of Public Health labeling rules now mandate explicit pediatric dosing guidance, raising compliance costs for imported brands.
- Seniors:Geriatric-focused products addressing medication interaction risks and swallowing difficulty. Singapore's aging demographic supports premium pricing for bioavailability-enhanced formats.
- Athletes:Performance-oriented consumers seeking exercise recovery and gut permeability management. Malaysian fitness center distribution networks show nascent penetration.
Adults sustain the revenue base while children climb the fastest as parental health investment priorities shift toward early microbiome intervention.
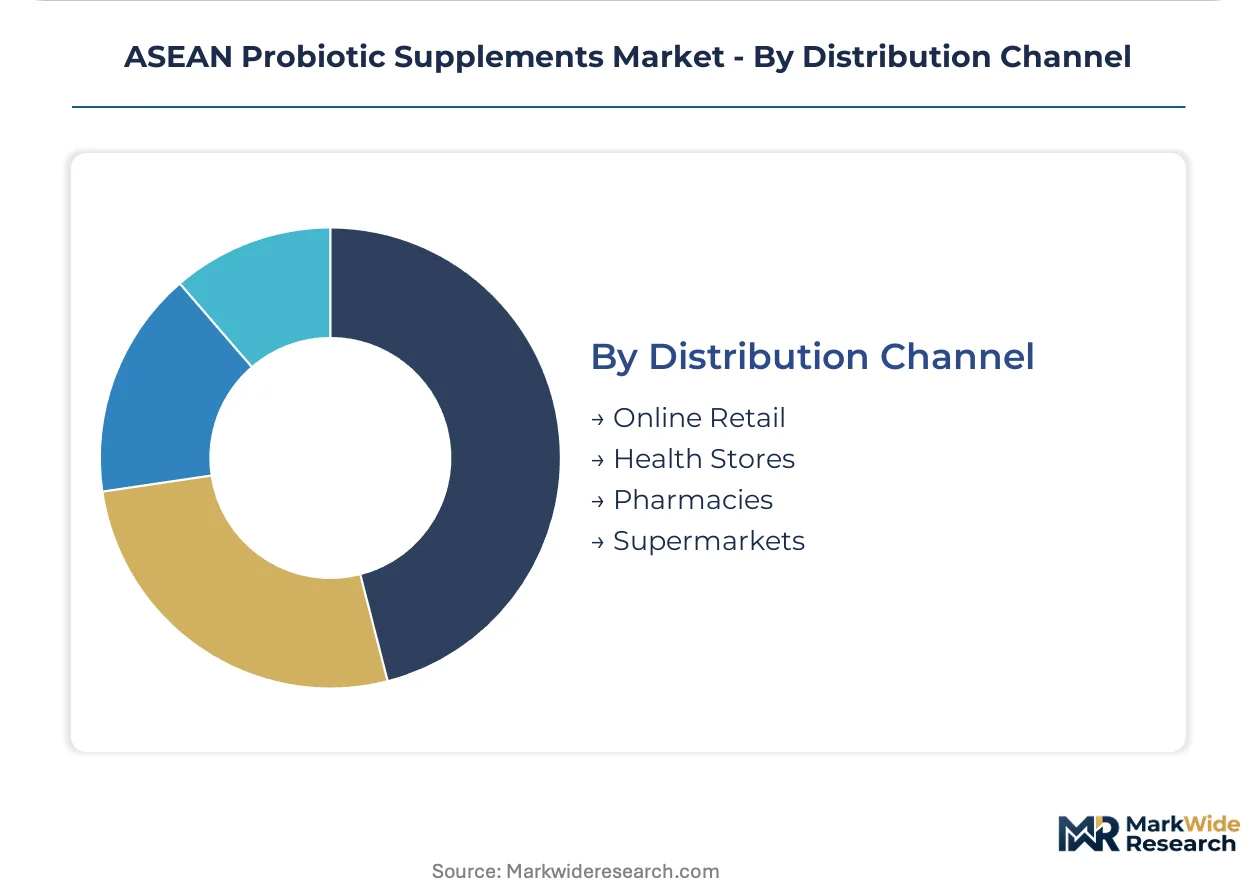
Distribution Channel:
Working capital requirements separate channel strategies, with online retail demanding inventory flexibility and pharmacies requiring relationship investments with licensed professionals.
- Pharmacies:Licensed dispensaries with trained staff capable of strain-specific counseling and contraindication screening. Indonesia's metropolitan corridors show deepening penetration through pharmacist recommendation programs that convert walk-in traffic.
- Online Retail:E-commerce platforms and direct-to-consumer models capturing immune-focused buyers through subscription scheduling. Jakarta and Surabaya digital marketplaces lead ASEAN in probiotic subscription density.
- Health Stores:Specialized retailers emphasizing natural and organic positioning. Malaysia's independent health store networks face consolidation pressure from pharmacy chain private-label expansion.
- Supermarkets:Mass-market retail with limited staff expertise and price-competitive assortment. Thailand's modern trade channels show probiotic placement expansion in refrigerated dairy adjacencies.
Pharmacies defend the volume foundation while online retail gains share at the steepest trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang Deep Sea Port anchors Thailand's position as ASEAN's primary probiotic import gateway, with cold-chain infrastructure extending north through Bangkok's pharmaceutical distribution corridors.
Indonesia
Jakarta's pharmacy networks and Surabaya's e-commerce platforms drive probiotic penetration through pharmacist recommendation programs and subscription-based replenishment models. BPOM's halal certification mandates create layered compliance obligations for cross-border marketers, forcing parallel product lines for fermentation-derived ingredients. The Greater Jakarta corridor concentrates immune-support format innovation as urban professionals shift purchase patterns toward automated delivery scheduling.
Thailand
Bangkok's modern trade channels and Chiang Mai's health store networks sustain capsule format dominance through established cold-chain independence. The Ministry of Public Health's tightened dietary supplement labeling rules compel manufacturers to declare strain identifiers and CFU counts at end-of-shelf-life, accelerating domestic reformulation investments. The Eastern Economic Corridor's logistics infrastructure supports regional distribution economics for shelf-stable formats.
Singapore
The city-state's aging demographic and premium retail infrastructure support bioavailability-enhanced geriatric formulations with margin structures 15-25% above regional baselines. The Health Sciences Authority's alignment with ASEAN harmonization initiatives streamlines strain approval pathways for clinically validated portfolios. Biopolis research clusters anchor microbiologist talent concentration, forcing regional manufacturers to outsource stability testing at premium rates.
Vietnam
Ho Chi Minh City and Hanoi corridors show underpenetrated pharmacy channels where early entrants can anchor brand recognition before competitive density increases. Last-mile cold-chain gaps constrain liquid format viability to metro corridors exclusively, directing manufacturer preference toward microencapsulated shelf-stable alternatives. The country's emerging middle class drives gummy format adoption among pediatric and geriatric compliance-sensitive segments.
Malaysia
Kuala Lumpur's health store networks face consolidation pressure from pharmacy chain private-label expansion, while Penang's independent retailers emphasize natural and organic positioning. Family-owned distributors struggle with legacy ERP integration against batch-level traceability requirements for ASEAN harmonization, delaying real-time compliance reporting. The Klang Valley's logistics infrastructure supports cross-border distribution into southern Thai markets.
ASEAN Probiotic Supplements Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The ASEAN probiotic supplements market fragments across multinational nutrition conglomerates, direct-selling networks, and clinically validated strain developers. Three archetypes dominate: dairy and nutrition infrastructure leverage, direct-to-consumer margin control, and clinical credibility positioning. Competitive moves concentrate on tropical stability technology licensing and pharmacist recommendation program partnerships.
Within the infrastructure-leverage tier, Nestle SA anchors regional supply chain integration through existing dairy and nutrition distribution networks. Amway Corporation occupies the direct-selling archetype, sustaining margin control and consumer education at point of purchase across multiple ASEAN markets. BioGaia AB exemplifies the clinical validation specialist, positioning toward pediatric and premium adult segments where strain-specific credibility commands price premiums.
| Leading Market Players |
|---|
| GNC Holdings LLC |
| Reckitt Benckiser LLC |
| Church & Dwight Co Inc |
| Nestle SA |
| Nature's Way Products LLC |
| Amway Corporation |
| Pharma Care Laboratories Pty Ltd |
| BioGaia AB |
| Procter & Gamble |
| Others |
Value Chain & Pricing Dynamics
Laem Chabang Deep Sea Port's cold-chain cost dynamics concentrate supply power among Thai distributors while fragmenting downstream price tiers across pharmacy, e-commerce, and direct-to-consumer channels. Tropical stability requirements force manufacturers to absorb microencapsulation premiums, passing differentiated costs to buyers based on format resilience and channel service levels.
Pricing Analysis
Volume-discount tiering structures stratify across premium clinically validated strains, standard pharmacy-grade formulations, and economy private-label alternatives. Price differentiation hinges on halal certification grade and CFU potency guarantees at end-of-shelf-life, with Thailand's FDA labeling tightening compressing margins for non-compliant imports. Pricing pressure intensifies in standard tiers as Indonesian pharmacy chains consolidate procurement around house brands. Subscription-based buyers in Jakarta show lowest price sensitivity, while supermarket walk-in traffic in Manila demands economy positioning.
Supply Chain Analysis
Tariff exposure between EU strain developers and ASEAN finished goods assemblers dominates supply chain risk planning for cross-border marketers. Fermentation capacity concentrates in Thailand, Singapore, and South Korea, with freeze-dried culture dependencies drawing from Danish and Japanese specialist suppliers. Single-source vulnerability runs through clinical strain licensing agreements that lock manufacturers to specific bioreactor facilities. Distribution runs through Bangkok's pharmaceutical corridors for pharmacy fulfillment, while Jakarta's e-commerce platforms bypass traditional wholesale tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN probiotic supplements sit in early-cycle expansion as microencapsulation technology unlocks rural distribution economics previously blocked by refrigeration gaps. Gummy format adoption among pediatric and geriatric segments accelerates penetration rates beyond historical digestive health baselines.
For Market Incumbents: Entrench pharmacist recommendation programs in Indonesia's metropolitan corridors before e-commerce platforms capture immune-support subscription volumes. Deepen backward integration into tropical stability testing infrastructure in Bangkok to preempt compliance costs from Thailand's FDA labeling tightening. Acquire or license microencapsulation coating technology to defend margin position against cold-chain-independent format competitors.
For New Entrants and Emerging Players: Vietnam's underpenetrated pharmacy channels in Ho Chi Minh City and Hanoi corridors represent the most penetrable entry point before competitive density increases. Pediatric gummy formulations targeting taste-driven compliance gaps in Malaysian health stores offer secondary white-space traction. Lead with direct-to-consumer subscription models to bypass incumbent pharmacy relationship investments and capture urban Indonesian professional demand.
For Investors and Strategic Acquirers: Regional strain characterization laboratories with BPOM and Thai FDA analytical accreditation command scarcity premiums as microbiologist talent concentrates in Singapore and Bangkok. Monitor halal certification backlog clearance rates at Indonesia's BPOM as the inflection signal for cross-border market access velocity. Position for consolidation plays around family-owned distributors struggling with ASEAN harmonization traceability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Thai and Vietnamese manufacturers gain shelf-stable format independence from cold-chain gaps. |
| Halal Certification Fast-Track Investment | Indonesia's BPOM compliance advantage opens parallel product line rationalization for cross-border marketers. |
| Pharmacist Recommendation Program Partnerships | Indonesian pharmacy chains convert walk-in traffic into repeat purchasers through strain-specific counseling. |
| Direct-to-Consumer Platform Launch | Jakarta and Surabaya subscription models displace traditional pharmacy repurchase cycles for immune-focused buyers. |
| Clinical Strain Portfolio Acquisition | Pediatric and premium adult segments command price premiums where BioGaia AB's validation archetype sets benchmarks. |
Study Parameters
Desk research of ASEAN regulatory filings, BPOM and Thai FDA registration databases, and e-commerce platform SKU audits preceded structured interviews with pharmacy chain procurement directors, probiotic formulators, cold-chain logistics operators, and halal certification consultants. Primary fieldwork validated strain approval pathway timelines and tropical stability testing protocols against secondary trade data and customs import records. Bottom-up channel volume estimates triangulated with top-down manufacturer capacity disclosures.
Fixed assumptions across the projection horizon held ASEAN harmonization implementation timelines, EU-ASEAN FTA negotiation progress, and microencapsulation technology diffusion rates constant while varying urbanization pace and pharmacy channel consolidation speed. Segmentation modeling incorporated product format stability requirements, application-level margin structures, end-user compliance behavior, and distribution channel working capital intensity. CAGRs derived from fitted adoption curves applied to population-adjusted per-capita consumption benchmarks, with strain registration cost trajectories and halal certification queue lengths as industry-specific sensitivity inputs.
Practitioners should monitor BPOM registration backlog clearance rates, Thai FDA enforcement intensity on end-of-shelf-life labeling, and cold-chain infrastructure investment announcements in Vietnam and the Philippines for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Microbial Food Culture Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Digestive and Intestinal Remedies Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Bifidobacteria Lysates Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
North America Microbial Food Culture Market
Probiotic Supplements
Probiotic Strains Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Probiotics After Antibiotic Recovery Market
Probiotic Supplements
Europe Probiotic Supplements Market