
 Commercial Ice Dispenser Market | 2026-2036
Commercial Ice Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Ice Dispenser Market Outlook
Multi-source component procurement is decoupling from the traditional single-vendor ice machine bundling that dominated commercial kitchen outfitting. Hoshizaki America, Inc. leverages its refrigeration engineering heritage to sustain premium positioning in under-counter systems. Manitowoc Ice anchors North American distribution through broad foodservice dealer networks. Scotsman Ice Systems differentiates via proprietary scale-reduction technologies that extend equipment service intervals.
A commercial ice dispenser is a mechanized refrigeration appliance that produces, stores, and delivers ice through automated dispensing mechanisms, typically operating between 500 and 1,800 pounds of daily output using modular evaporator plates or auger-driven extrusion systems. The equipment serves food safety and labor efficiency objectives by eliminating manual ice handling in high-volume hospitality and healthcare environments. Floor-standing units dominate institutional deployments where volume throughput and sanitation compliance justify capital investment, while countertop configurations capture fastest growth in limited-service restaurants optimizing front-of-house footprint. Application segmentation reveals hotels and supermarkets as margin-rich verticals due to 24-hour operational requirements and brand-sensitive procurement standards.
The U.S. FDA Food Code and NSF/ANSI 7 commercial refrigeration standards govern ice contact surfaces and sanitation protocols, compelling equipment replacement cycles when regulatory revisions tighten material or cleaning specifications. The EPA ENERGY STAR program and DOE commercial refrigeration efficiency rules shape product development roadmaps by certifying lower-kilowatt-hour configurations that qualify for utility rebate programs. Stakeholders must monitor how state-level building electrification mandates and evolving sanitation codes interact with equipment replacement timelines and capital allocation decisions.
Market Dynamics
Food service chains are retrofitting kitchens with automated ice handling systems to reduce labor exposure and contamination risk, while FDA Food Code updates on ice safety handling force equipment replacement cycles across institutional kitchens.
Growth Catalysts
- Quick-service restaurant expansion:Chains in the United States are standardizing automated ice dispensers across new locations to ensure consistent sanitation protocols and reduce manual handling liability.
- Healthcare facility renovations:Hospital and long-term care construction projects specify NSF/ANSI 7 certified equipment to meet Joint Commission infection control standards.
- ENERGY STAR utility rebates:Lower-kilowatt-hour configurations qualify for state-level incentive programs that compress payback periods for high-volume operators.
Market Restraints
- Stainless steel price volatility:Fluctuations in nickel and chromium input costs compress margin on premium under-counter units where material grade determines compliance.
- Compressor supply concentration:Sourcing of high-efficiency refrigeration compressors clusters among a limited set of specialized suppliers, creating lead time risk.
- Water filtration integration complexity:Regional water chemistry variation forces customized pre-treatment configurations that extend specification cycles and raise installed cost.
Strategic Opportunities
- Supermarket beverage island automation:Grocery chains are deploying self-serve ice stations at fountain drink locations to reduce labor and improve throughput during peak hours.
- State building electrification mandates:California and New York efficiency requirements are accelerating replacement of legacy natural gas-reliant systems with all-electric refrigeration.
- IoT-enabled predictive maintenance:Sensor integration with scale-detection algorithms is converging with equipment leasing models to create subscription revenue streams.
Industry Challenges
- Refrigeration technician shortage:The specialized skill set for sealed system repair and EPA Section 608 certification limits service network expansion in secondary markets.
- Legacy kitchen integration friction:Retrofit installations must accommodate existing floor drains, electrical panels, and ventilation configurations that vary by building vintage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Ice Dispenser Market |
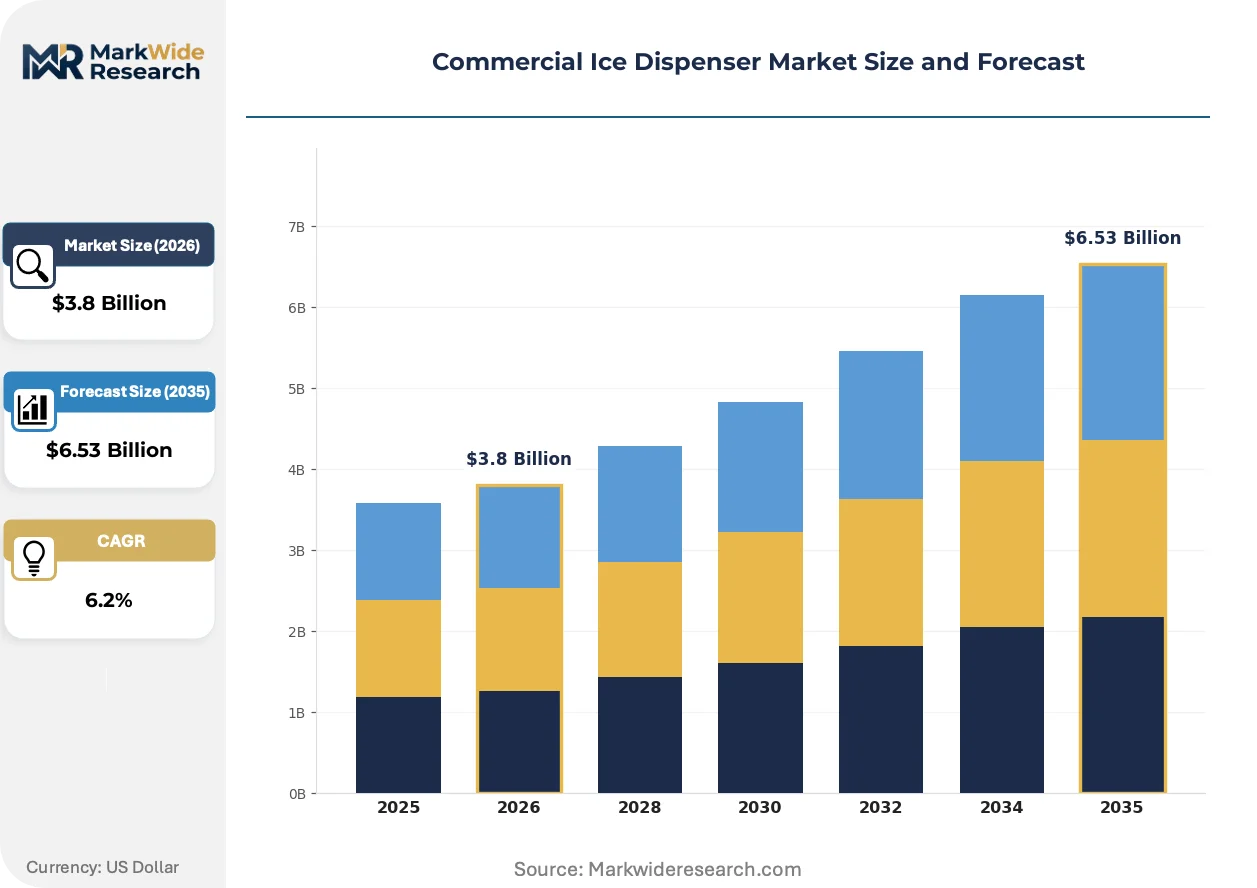
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-standing, Under-counter, Modular Application: Restaurants, Bars, Hotels, Supermarkets Capacity: Small, Medium, Large, Extra Large End User: Catering Services, Food Service Chains, Healthcare Facilities, Marine Industry |
| Companies Covered | Scotsman Ice Systems, Hoshizaki America, Inc., Manitowoc Ice, Cornelius Inc., Ice-O-Matic, Follett Corporation, NewAir, Beverage-Air, Electrolux Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Ice Dispenser Market Strategic Shifts
Equipment manufacturers are embedding connectivity and sanitation automation into core product architectures, shifting competitive differentiation from pure output capacity to operational intelligence and compliance assurance.
Antimicrobial copper-nickel alloys are replacing traditional stainless steel on ice contact surfaces to inhibit biofilm formation in high-use environments. Hospital cafeterias and nursing stations are specifying these surfaces to reduce manual cleaning frequency. This material transition is converging with automated self-sanitizing cycles to compress labor allocation for ice equipment maintenance.
The EPA ENERGY STAR Version 5.0 commercial ice maker specification tightens maximum energy consumption thresholds by approximately ten percent for most equipment categories. Manufacturers must redesign evaporator plate geometries and optimize harvest cycles to maintain certification eligibility. Hotels and full-service restaurants facing utility rebate program requirements are prioritizing certified models to capture incentive value.
Equipment-as-a-service contracts are displacing traditional capital purchase arrangements among multi-location operators. Chains are bundling installation, maintenance, and filter replacement into per-pound ice fees to convert fixed costs to variable expenses. This financing shift is most visible in the United States quick-service segment where franchisees prioritize cash flow predictability over asset ownership.
Commercial Ice Dispenser Market Segmentation
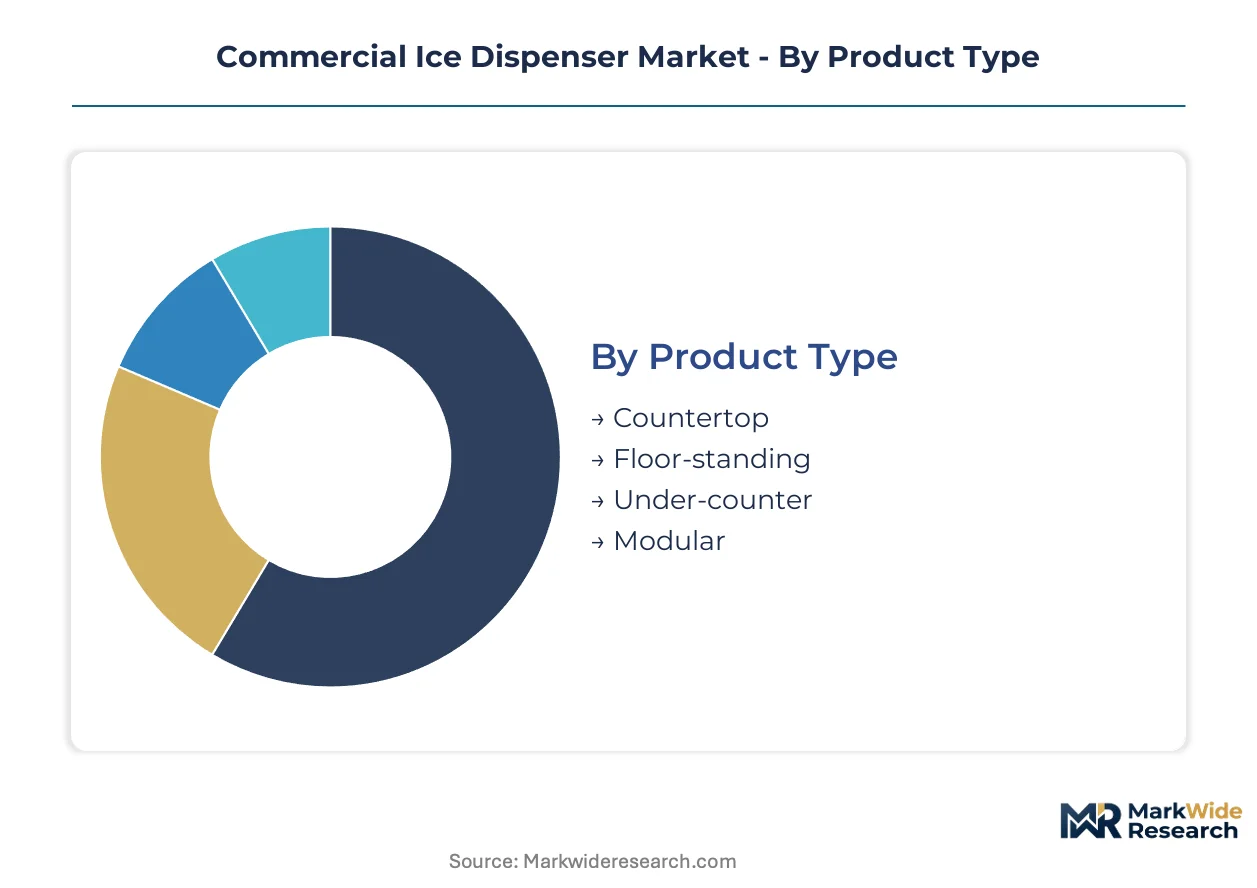
Commercial ice dispenser procurement patterns diverge sharply between high-volume institutional buyers prioritizing throughput reliability and smaller operators optimizing capital efficiency. Segmentation reveals how equipment specifications, capacity tiers, and end-use environments reshape vendor pricing power and service model requirements across the installed base.
Product Type:
Volume throughput separates premium positioning from economy tiers, with installation footprint and labor integration determining margin capture.
- Floor-standing:These units deploy vertical evaporator stacks and high-capacity storage bins delivering 1,000-plus pounds daily output for hospital cafeterias and casino beverage stations. Institutional buyers in the United States specify NSF/ANSI 7 certified models to satisfy Joint Commission audits and state health department inspections.
- Countertop:Compact auger-driven systems with front-access dispensing dominate quick-service restaurant front-of-house layouts where square footage commands premium lease rates. Chains standardize these configurations across franchise locations to reduce installation variance and compress training protocols.
- Under-counter:Integrated refrigeration systems fit beneath existing prep lines in legacy kitchen renovations where floor space is constrained.
- Modular:Separated ice-making heads and remote condensing units allow custom bin sizing for supermarket beverage islands and hotel banquet prep areas.
Mature deployment sits with floor-standing units in healthcare and hospitality. Newer deployment is concentrated in countertop systems for limited-service restaurant retrofits.
Application:
Operational intensity and sanitation scrutiny reshape equipment specifications across hospitality verticals, with 24-hour duty cycles separating commercial-grade from light-commercial procurement.
- Hotels:Property-wide ice provisioning demands redundant capacity and brand-consistent styling for corridor vending locations. Full-service properties in the United States specify ENERGY STAR certified equipment to capture utility rebate value across multi-building portfolios.
- Supermarkets:Self-serve fountain drink islands require high-throughput dispensing with automated filling sensors to reduce spillage and labor monitoring. Grocery chains deploying these systems face FDA Food Code compliance for ice contact surfaces in customer-accessible zones.
- Restaurants:Back-of-house production kitchens and front-of-house beverage stations create dual procurement tracks with diverging capacity and styling requirements.
- Bars:Cocktail-focused operations prioritize nugget ice extrusion for texture and rapid chilling in high-margin beverage programs.
Procurement consolidation is most advanced in hotels. Specification fragmentation persists in independent restaurants.
Capacity:
Daily output thresholds align with shift patterns and peak demand spikes, with oversizing penalties in energy consumption and capital recovery.
- Large:Systems rated 800-1,500 pounds per day serve college dining halls and regional hospital campuses where meal period surges compress ice production windows. These installations require three-phase electrical service and dedicated floor drains that constrain retrofit feasibility in older buildings.
- Extra Large:Industrial-scale configurations exceeding 1,500 pounds daily deploy modular evaporator arrays for stadium concessions and central commissary operations. Marine industry buyers specify corrosion-resistant condensing for offshore platform and cruise ship galleys.
- Medium:300-800 pound ratings capture independent restaurant and catering service demand with single-phase electrical compatibility.
- Small:Under-300-pound units serve office breakrooms and boutique hospitality settings with limited peak demand.
Specification maturity clusters in large-capacity healthcare and education procurement. Fastest specification evolution is occurring in extra-large marine and commissary deployments.
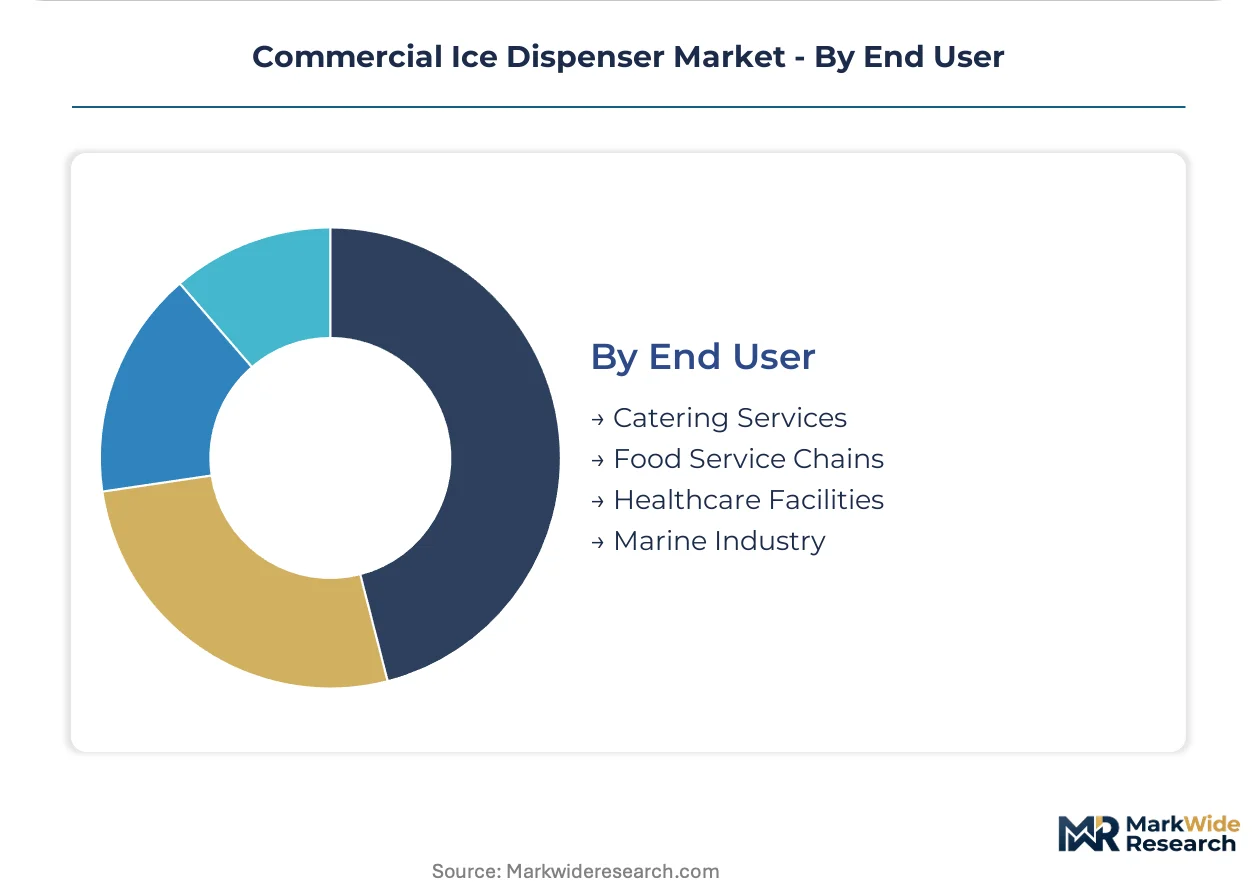
End User:
Contract structure and asset ownership models reshape vendor relationships, with leased equipment penetration varying by operator scale and capital access.
- Food Service Chains:Standardized equipment specifications across franchise networks enable national service contracts and predictive maintenance programs. Major quick-service brands in the United States are converting to equipment-as-a-service arrangements to shift ice production costs from capex to opex.
- Healthcare Facilities:Infection control protocols and Joint Commission accreditation requirements drive NSF/ANSI 7 certification and antimicrobial surface specifications. Hospital construction projects specify ice dispensers with automated self-sanitizing cycles to reduce environmental services labor allocation.
- Catering Services:Mobile and temporary deployment patterns favor portable ice transport over fixed installations, limiting dispenser penetration.
- Marine Industry:Vessel motion, salt air exposure, and space constraints demand specialized corrosion-resistant construction and secured mounting systems.
Contract standardization is furthest along in food service chains. Specification complexity is expanding fastest in healthcare facilities facing evolving FDA Food Code interpretations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from Pittsburgh and Cleveland anchors North American equipment fabrication, while nickel-chromium supply chains from Sudbury and Norilsk shape regional manufacturing economics across major demand centers.
United States
Quick-service restaurant expansion and healthcare facility renovations drive procurement volume in Texas, Florida, and California. The FDA Food Code updates on ice safety handling compel equipment replacement cycles across institutional kitchens. Chicago and Atlanta clusters concentrate distribution infrastructure serving the Midwest and Southeast markets.
Germany
Hotel renovation programs and supermarket beverage island automation sustain demand in Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation and national building efficiency codes accelerate replacement of legacy refrigeration systems. Frankfurt and Munich industrial zones host fabrication facilities supplying Central European foodservice chains.
China
Coastal hospitality development and central kitchen commissary construction propel large-capacity installations in Shanghai and Guangdong province. National GB standards for commercial refrigeration equipment tighten energy efficiency thresholds. Yangtze River Delta manufacturing clusters produce modular systems for domestic and export markets.
Japan
Convenience store beverage automation and hospital cafeteria upgrades sustain replacement demand in Tokyo and Osaka metropolitan areas. METI energy efficiency labeling programs and JIS sanitation standards shape product specifications. Nagoya industrial corridor hosts precision refrigeration component suppliers.
United Kingdom
Hotel chain standardization programs and pub beverage station retrofits drive countertop system adoption in London and Southeast England. The UK Health and Safety Executive guidance on food contact surfaces influences procurement specifications. Midlands manufacturing clusters assemble under-counter units for European distribution.
Commercial Ice Dispenser Market Competitive Environment
Product portfolio diversification dominates the current landscape as manufacturers extend beyond ice production into water filtration and IoT-enabled service platforms. The vendor base organizes around three strategic archetypes: diversified refrigeration conglomerates with cross-category engineering capabilities, specialized ice equipment pure-plays with deep distribution networks, and component-integrated systems houses bundling filtration and dispensing. Geographic expansion into Southeast Asian hospitality markets and strategic partnerships with beverage equipment distributors represent the dominant competitive moves.
Within the diversified conglomerate tier, Electrolux Group and Hoshizaki America, Inc. exemplify cross-category refrigeration engineering heritage applied to commercial ice systems. Scotsman Ice Systems occupies a position among specialized pure-plays with concentrated expertise in ice production technologies. Manitowoc Ice anchors the North American distribution-focused archetype through broad foodservice dealer networks. These three company structures illustrate how competitive positioning diverges between integrated engineering platforms and focused distribution strategies.
| Leading Market Players |
|---|
| Scotsman Ice Systems |
| Hoshizaki America, Inc. |
| Manitowoc Ice |
| Cornelius Inc. |
| Ice-O-Matic |
| Follett Corporation |
| NewAir |
| Beverage-Air |
| Electrolux Group |
| Others |
Value Chain & Pricing Dynamics
EPA ENERGY STAR Version 5.0 certification gates qualified supply for premium-tier commercial ice dispensers, compressing manufacturer margins on non-compliant inventory while elevating certified unit pricing by fifteen to twenty percent above legacy equivalents. Quick-service restaurant chains and hospital procurement committees now specify certified configurations exclusively, forcing distributors to absorb write-downs on pre-standardization stock.
Pricing Analysis
Warranty and service bundling separates premium from standard tiers, with multiyear maintenance contracts and predictive monitoring subscriptions adding thirty to forty percent to total cost of ownership. Three-tier pricing structure across premium, standard, and economy levels reflects NSF/ANSI 7 certification grade, antimicrobial surface specifications, and IoT connectivity modules. Cost compression in economy countertop units is intensifying because stainless steel feedstock volatility and compressor supply concentration squeeze assembler margins. Independent restaurants and catering services exhibit highest price sensitivity, while healthcare facility construction projects demonstrate lowest sensitivity due to infection control compliance mandates and Joint Commission accreditation requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale food service chain demand, while broadline foodservice dealer networks capture mid-market independent restaurant procurement. Manufacturing concentration centers on the United States, China, and Germany, with Yangtze River Delta clusters producing modular evaporator assemblies and Midwest U.S. fabrication facilities stamping stainless steel enclosures. Nickel and chromium sourcing draws from Sudbury and Norilsk mining operations, while high-efficiency refrigeration compressors hinge on specialized suppliers in Japan and Germany. Single-source vulnerability in compressor procurement creates lead time risk for North American equipment assemblers. Distribution runs through authorized service dealer networks requiring EPA Section 608 certified technician coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial ice dispenser manufacturing is consolidating around diversified refrigeration conglomerates with captive component supply, as stainless steel price volatility and EPA efficiency mandates force capital-constrained pure-plays toward exit or acquisition.
For Market Incumbents: Deepen backward integration into refrigeration compressor sourcing to insulate margin from single-supplier concentration risk in Japan and Germany. Expand predictive maintenance platform subscriptions to convert transactional equipment sales into recurring revenue streams, defending against emerging IoT-native entrants with software-first service models. Prioritize NSF/ANSI 7 certification maintenance and antimicrobial copper-nickel alloy surface integration to sustain healthcare procurement preference. For New Entrants and Emerging Players: Sensor-integrated scale detection algorithms offer a technology-first wedge into equipment-as-a-service contracts displacing capital purchases among quick-service franchisees. Target supermarket beverage island automation as the most penetrable application segment, where grocery chains seek self-serve ice stations without legacy service relationships. Pursue white-label manufacturing partnerships with Yangtze River Delta fabricators to compress initial capital requirements and accelerate ENERGY STAR certification timelines. For Investors and Strategic Acquirers: Accelerating conversion of quick-service chains from capital purchase to per-pound ice subscription fees is the leading indicator that equipment-as-a-service economics have crossed viability thresholds for platform rollups. Five-to-ten year viability favors diversified refrigeration conglomerates with cross-category engineering platforms over pure-play ice equipment specialists facing component supply concentration. Monitor state-level building electrification mandate adoption in California and New York as inflection signals for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Platform Launch | Converts fixed capital expenditure to variable operating expense for franchise chains. |
| Antimicrobial Surface Certification | Captures healthcare procurement preference under Joint Commission infection control standards. |
| Compressor Supply Agreement | Secures allocation priority from Japanese and German specialized refrigeration component suppliers. |
| IoT Predictive Maintenance Integration | Enables subscription revenue streams and reduces customer churn through automated service dispatch. |
| State Electrification Mandate Compliance | Qualifies equipment for California and New York utility rebate programs accelerating replacement cycles. |
Study Parameters
Multi-period observation of FDA Food Code enforcement patterns, EPA ENERGY STAR certification timelines, and food service chain capital expenditure cycles anchored the trend analysis, supplemented by interviews with commercial kitchen equipment procurement directors, healthcare facility engineering managers, foodservice dealer network principals, and refrigeration technician training program administrators. Secondary validation drew from FDA inspection data, NSF International certification registries, state utility rebate program disclosures, and DOE commercial refrigeration efficiency rulemakings. Bottom-up equipment shipment tallies by product configuration and top-down food service construction spending estimates were triangulated to constrain forecast variance.
Segment-weighting applied capacity tier, installation type, and end-use environment as primary stratification dimensions, with regional regulatory cluster and utility incentive program intensity as secondary modifiers. Growth trajectories across the projection horizon were derived from replacement cycle analysis tied to FDA Food Code revision history and equipment service life distributions. Industry-specific forecast inputs included quick-service restaurant expansion pipelines, hospital construction permitting data, and supermarket beverage island retrofit announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt stainless steel price spikes, compressor supply disruptions, or accelerated state building electrification mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Smokeless Indoor Grills Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Qatar Food Service Market
Food Service
Contract Catering Market
Food Service
Cutting Boards Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Europe Barbeque Grill Market
Food Service
Pasteurized Eggs Market
Food Service
Online Catering Market
Food Service
Instant Noodle Vending Machine Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Vietnam Food Service Market
Food Service
Global Online Food Ordering Market