
 Commercial Food Processors Market | 2026-2036
Commercial Food Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Food Processors Market Outlook
Equipment leasing and managed-service contracts are reshaping competitive dynamics in commercial food processing, lowering capital barriers for mid-scale catering operators and independent restaurant groups. Hobart leverages its integrated service networks to sustain long-term customer relationships across institutional kitchens. Robot-Coupe anchors its position through specialized product lines targeting high-volume French and European culinary traditions. Sammic competes aggressively in compact footprint designs suited for space-constrained commercial environments.
Commercial food processors are motorized kitchen machines designed to mechanically reduce, mix, emulsify, or homogenize food ingredients at throughput rates typically exceeding 50 kilograms per hour, constructed from food-grade stainless steel with sealed bearing assemblies and variable-speed drives for operational flexibility. Batch processors dominate current installed bases due to their versatility across recipe-driven operations, while continuous processors represent the fastest-expanding category as automated production lines in food manufacturing scale output requirements. Thermal technology applications command premium positioning in pasteurization and sous-vide preparation segments where temperature precision directly affects product safety outcomes.
NSF International certification requirements in the United States and CE marking obligations under EU machinery directives establish mandatory safety and sanitation benchmarks that filter non-compliant suppliers from market access. FDA food code provisions and EFSA hygiene standards further constrain equipment design specifications, particularly for surfaces contacting ready-to-eat products. Stakeholders must monitor evolving energy efficiency mandates and circular economy material requirements that will increasingly determine procurement specifications and supplier qualification criteria.
Market Dynamics
Central kitchen consolidation among multi-unit restaurant operators is compressing equipment procurement cycles and elevating throughput specifications above standalone durability metrics. This structural concentration favors suppliers capable of integrating predictive maintenance software with hardware platforms.
Growth Catalysts
- FDA Food Code modernization:Enhanced temperature logging requirements for ready-to-eat processing are forcing equipment upgrades across US institutional foodservice operations.
- High-throughput continuous processing:Automated production lines in prepared meal manufacturing are displacing batch configurations for sauce, dough, and emulsion applications.
- German precision engineering demand:Central European procurement specifications prioritize sealed bearing assemblies and variable-speed drive precision that filter lower-tier suppliers from contract eligibility.
Market Restraints
- Food-grade stainless steel volatility:Nickel and chromium price swings compress margin predictability for equipment fabricators locked into annual contract pricing.
- NSF International certification timelines:Extended laboratory testing protocols for novel thermal processing technologies delay commercialization by 8-14 months.
- Induction motor substitution:Brushless DC alternatives in adjacent commercial equipment categories threaten incumbent drive system architectures.
Strategic Opportunities
- India FSSAI compliance gap:Domestic food safety infrastructure expansion creates first-mover positioning for certified equipment platforms in institutional catering.
- IoT-enabled predictive maintenance:Sensor-integrated bearing assemblies and cloud-connected variable-speed drives converge to create subscription revenue streams.
- EU Green Deal material mandates:Circular economy requirements for repairable components and recycled content create procurement preference for modular equipment designs.
Industry Challenges
- Mechatronics technician scarcity:Shortages of specialists capable of diagnosing integrated mechanical-electrical failures in sealed drive systems extend service resolution times.
- CE marking documentation burden:EU machinery directive technical file requirements demand specialized regulatory affairs capacity that smaller fabricators struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Food Processors Market |
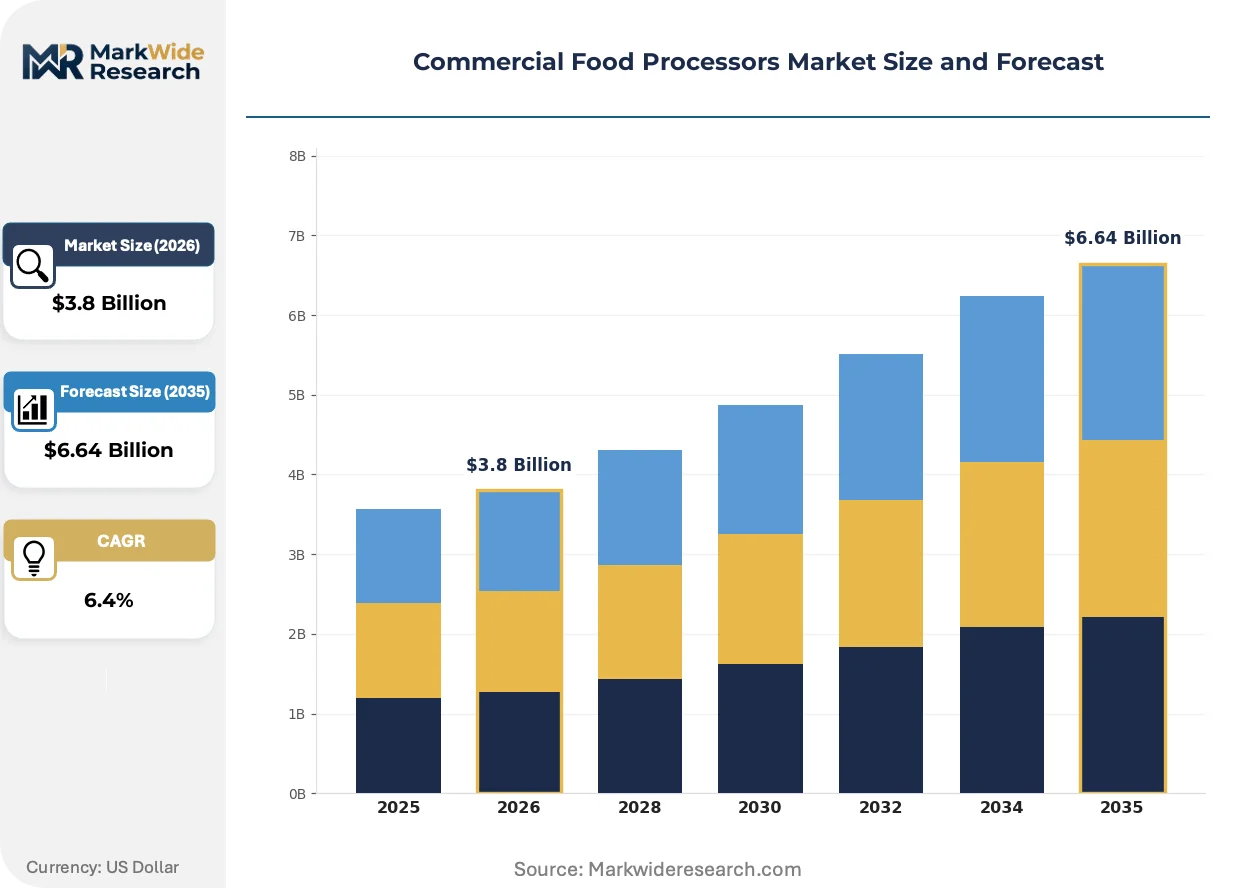
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Processors, Continuous Processors, Industrial Mixers, Emulsifiers End User: Restaurants, Catering Services, Food Manufacturers, Supermarkets Technology: Mechanical, Thermal, Chemical, Ultrasonic Application: Baking, Cooking, Preservation, Food Packaging |
| Companies Covered | Hobart, Robot-Coupe, Sammic, Waring, Berkel, Electrolux, Magimix, Skyfood Equipment, Vollrath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Food Processors Market Strategic Shifts
Equipment intelligence layers are migrating from aftermarket add-ons to factory-integrated standard configurations. This shift compresses the competitive window for pure-play hardware suppliers and elevates software-enabled service contracts as primary margin sources.
Brushless DC motor technology is migrating from premium positioning to mid-tier equipment specifications. High-volume contract food manufacturers in prepared meal and bakery segments are specifying these drives for energy recovery and precision torque control. The technology is migrating from niche sous-vide and thermal processing applications into general-purpose mixing and emulsification platforms.
EU F-Gas Regulation phase-down schedules are constraining refrigerant choices in thermal processing equipment with cooling stages. Manufacturers must redesign heat exchange systems around lower-global-warming-potential alternatives. German and French equipment fabricators face the most acute redesign timelines due to earlier national implementation of leakage monitoring requirements.
Leasing structures are displacing outright purchase for mid-scale catering operators and independent restaurant groups. Equipment-as-a-service contracts bundle maintenance, certification renewal, and technology refresh cycles into per-hour or per-kilogram throughput fees. This model concentrates most visibly in North American institutional foodservice and UK contract catering where capital rationing pressures are most acute.
Commercial Food Processors Market Segmentation
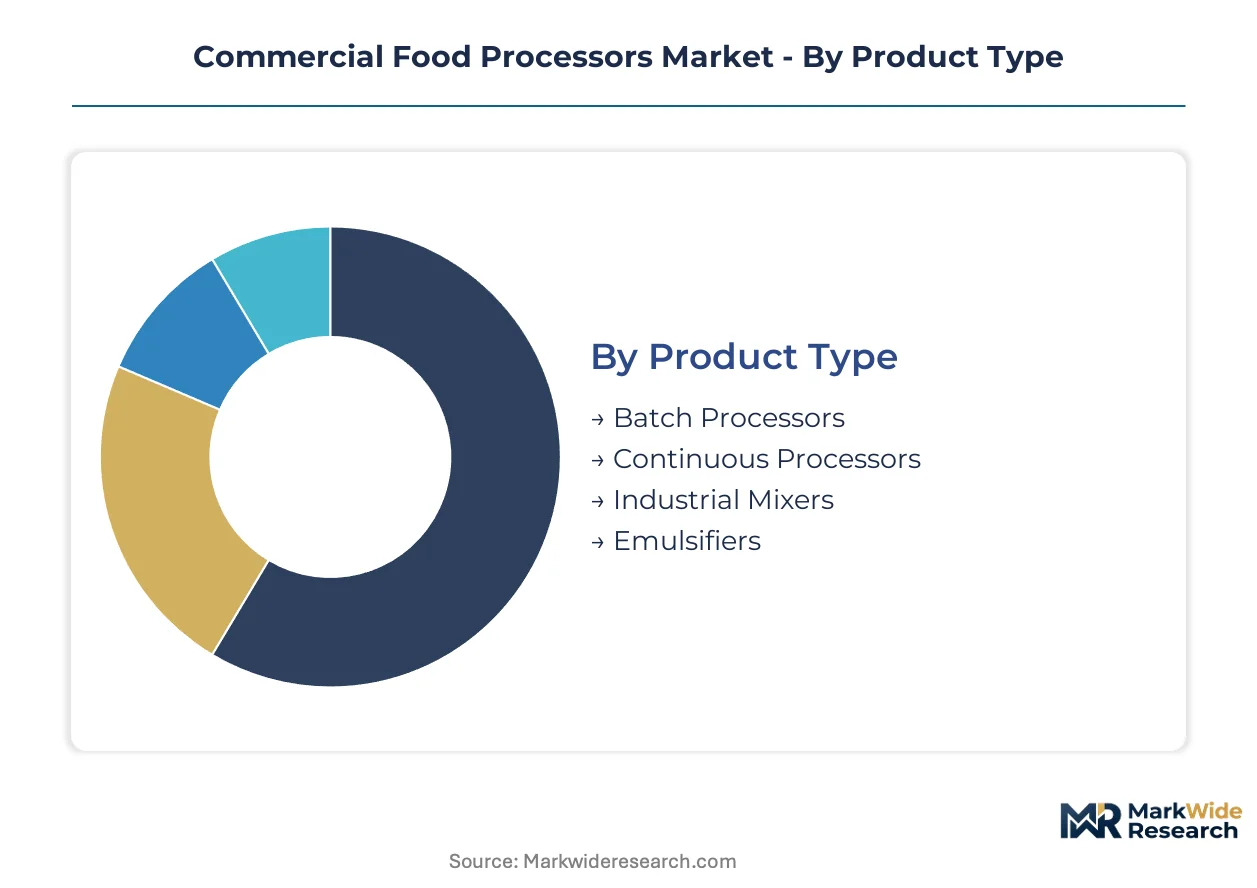
Equipment specification varies sharply across operational environments, from recipe-driven kitchens requiring batch flexibility to automated manufacturing lines demanding continuous throughput. Procurement criteria diverge by end-use intensity, with food manufacturers prioritizing uptime metrics while restaurant operators emphasize footprint efficiency.
Product Type:
Use-case spectrum spans intermittent recipe execution to uninterrupted production flows, with equipment architecture determining operational economics.
- Batch Processors:Vessel-based systems with sealed lids and variable-speed drives accommodate diverse ingredient combinations through programmable cycle controls. Restaurant chains in Germany specify these units for central kitchen operations where recipe variety exceeds volume consistency, though NSF International certification timelines extend procurement cycles.
- Continuous Processors:Inline configurations with screw-fed or pump-driven material transport sustain output rates above 500 kilograms per hour for sauce and emulsion manufacturing. Prepared meal manufacturers in North America are specifying these systems as central kitchen consolidation compresses equipment replacement timelines.
- Industrial Mixers:Planetary and spiral configurations handle dough and batter viscosities with torque-rated gearboxes.
- Emulsifiers:High-shear rotor-stator assemblies stabilize oil-water interfaces for dressing and spread production.
The dominant share belongs to Batch Processors, while Continuous Processors is closing the gap fastest.
End User:
Capital deployment patterns separate asset-heavy manufacturers from operationally leveraged service providers.
- Restaurants:Full-service and quick-service operators deploy compact footprint units with rapid changeover capabilities for menu diversification. Independent restaurant groups in the United Kingdom are shifting toward equipment-as-a-service contracts as capital rationing pressures intensify.
- Food Manufacturers:Contract packaging and prepared meal facilities specify NSF-certified or CE-marked platforms with predictive maintenance integration. FDA Food Code modernization around temperature logging is forcing equipment upgrades across US institutional manufacturing operations.
- Catering Services:Event and contract caterers prioritize mobility and rapid sanitation protocols.
- Supermarkets:In-store prepared food departments require retail-hardened designs with customer-facing safety guards.
Food Manufacturers command the largest installed base, though Restaurants is expanding most quickly through leasing penetration.
Technology:
Energy transfer mechanisms determine precision thresholds and regulatory compliance burdens across processing applications.
- Mechanical:Motor-driven cutting, mixing, and grinding systems with sealed bearing assemblies dominate general-purpose applications. German procurement specifications prioritize variable-speed drive precision that filters lower-tier suppliers from contract eligibility.
- Thermal:Jacketed vessels and induction heating platforms enable pasteurization and sous-vide preparation with temperature control within 0.5 degrees Celsius. EU F-Gas Regulation phase-down schedules are constraining refrigerant choices in cooling-stage equipment, forcing heat exchange redesigns.
- Chemical:pH adjustment and enzymatic treatment systems for specific preservation applications.
- Ultrasonic:High-frequency cavitation for cell disruption and homogenization in specialty ingredient processing.
Mechanical systems retain the dominant share, while Thermal platforms are gaining share fastest through prepared meal safety requirements.
Application:
Process stage determines equipment durability specifications and cleaning protocol intensity.
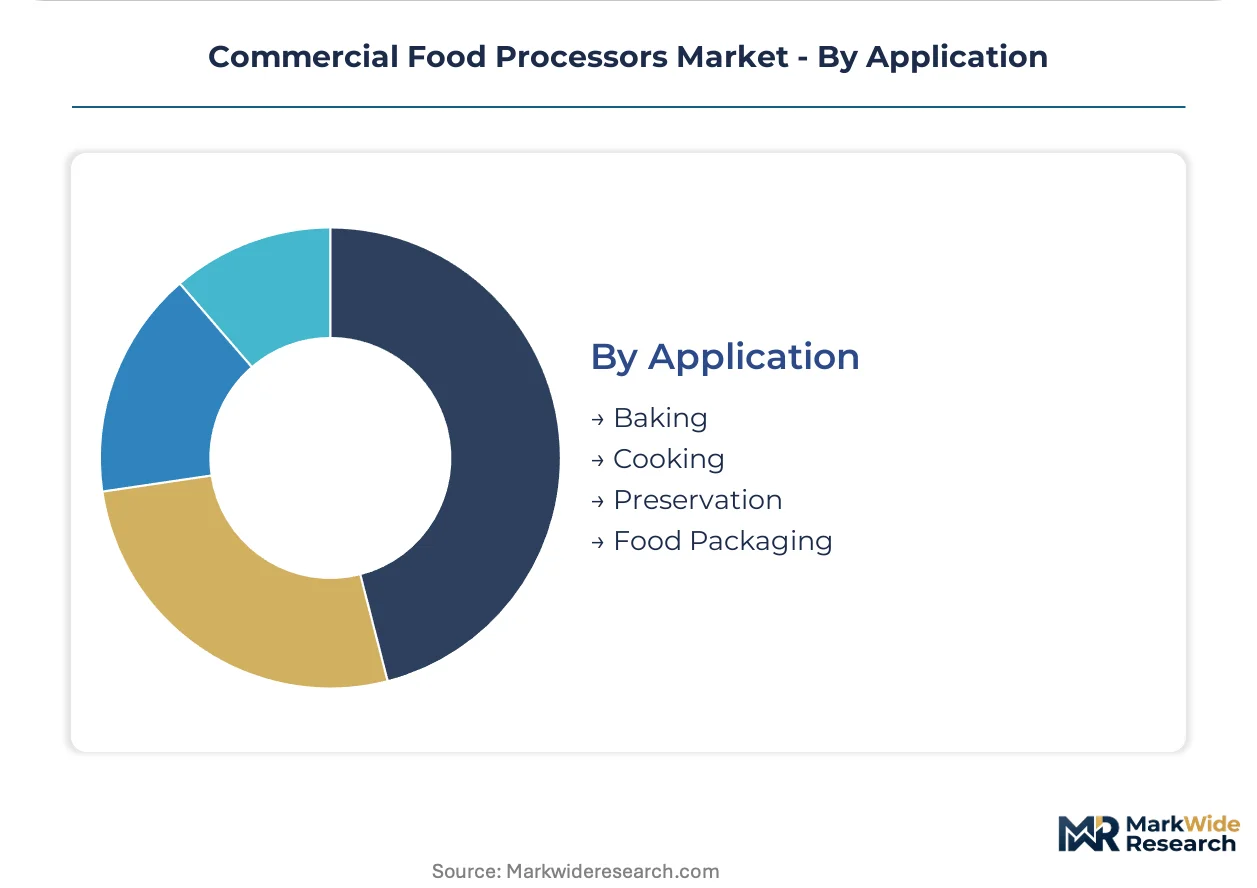
- Cooking:Thermal processing platforms with integrated temperature logging satisfy FDA and EFSA hygiene standards for ready-to-eat production. Central kitchen investments across North American restaurant chains are elevating throughput specifications above standalone durability metrics.
- Preservation:Pasteurization and rapid cooling systems extend shelf-life for prepared meal distribution. Brushless DC motor technology is migrating into these platforms for energy recovery and precision torque control.
- Baking:Dough development and batter mixing equipment for bakery manufacturing.
- Food Packaging:Portioning and sealing integration with processing lines for retail-ready output.
Cooking applications hold the dominant share, while Preservation is climbing the fastest through cold-chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision engineering clusters while North American operators absorb premium markups for certified thermal platforms. This asymmetry reflects divergent regulatory stringency and procurement sophistication across Atlantic markets.
United States
Central kitchen consolidation among multi-unit restaurant chains compresses equipment replacement cycles toward continuous processing configurations. FDA Food Code modernization around temperature logging mandates accelerates thermal platform upgrades across institutional foodservice operations. Chicago and Dallas-Fort Worth metropolitan clusters host dense concentrations of contract food manufacturers specifying NSF-certified predictive maintenance integration.
Germany
Procurement specifications prioritize sealed bearing assemblies and variable-speed drive precision that systematically filter lower-tier fabricators from contract eligibility. EU machinery directive CE marking obligations and F-Gas Regulation phase-down schedules constrain refrigerant choices in cooling-stage equipment. Stuttgart and Munich engineering corridors concentrate fabricators redesigning heat exchange systems around lower-global-warming-potential alternatives.
United Kingdom
Independent restaurant groups and contract caterers shift decisively toward equipment-as-a-service contracts as capital rationing pressures intensify post-pandemic. UK Food Standards Agency hygiene protocols align with EFSA standards to constrain surface specifications for ready-to-eat contact equipment. Greater London and Manchester institutional catering hubs drive leasing penetration across mid-scale operator segments.
India
FSSAI compliance infrastructure expansion creates first-mover positioning opportunities for certified equipment platforms in institutional catering and prepared meal manufacturing. Central government PLI scheme incentives for food processing machinery attract domestic assembly investments. Mumbai and Bengaluru metropolitan clusters concentrate emerging central kitchen deployments among quick-service restaurant chains.
France
High-volume culinary traditions sustain specialized product line demand for batch processors accommodating recipe-driven operations in premium foodservice segments. ANSM and DGCCRF enforcement of EU hygiene standards elevates documentation burdens for equipment technical files. Lyon and Paris gastronomy clusters anchor procurement specifications for precision-engineered thermal processing platforms.
Commercial Food Processors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in bearing assemblies and drive architectures. The vendor base stratifies across three tiers: multinational kitchen equipment conglomerates with integrated service networks, mid-scale regional fabricators with certification depth in specific geographies, and compact-specialist manufacturers targeting space-constrained installations. Dominant competitive moves include predictive maintenance software integration with hardware platforms and equipment-as-a-service contract structures displacing outright purchase.
Among European precision engineering specialists, Robot-Coupe and Sammic occupy positions within the premium-tier batch and compact processor segments respectively. Hobart anchors the integrated service network archetype through its institutional kitchen presence. These three fabricators exemplify divergent strategic positioning: specialized culinary tradition alignment, aggressive footprint minimization, and long-term relationship sustainment through managed service contracts.
| Leading Market Players |
|---|
| Hobart |
| Robot-Coupe |
| Sammic |
| Waring |
| Berkel |
| Electrolux |
| Magimix |
| Skyfood Equipment |
| Vollrath |
| Others |
Value Chain & Pricing Dynamics
Food-grade stainless steel volatility determines both pricing tier spreads and supply chain shape, compressing margin predictability for equipment fabricators locked into annual contract pricing while forcing procurement diversification across nickel and chromium sourcing corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture NSF International and CE marking certification premiums alongside predictive maintenance integration, while economy tiers serve independent restaurant groups with stripped-down mechanical configurations. Price differentiation hinges on sealed bearing assembly precision and variable-speed drive sophistication. Cost compression in mid-tier equipment is intensifying because brushless DC motor substitution threatens incumbent induction motor architectures. Contract food manufacturers exhibit least price sensitivity due to throughput-critical operations, whereas independent catering operators absorb highest sensitivity under capital rationing pressures.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese, Indonesian, and South African nickel-chromium processing clusters. Food-grade bearing assemblies rest on German and Japanese precision manufacturing, while variable-speed drive electronics center on Taiwanese and South Korean semiconductor fabrication. Single-source vulnerability concentrates in sealed bearing technologies where German engineering standards dominate procurement specifications. Distribution runs through regional equipment distributors with NSF International certification maintenance capabilities, supplemented by direct OEM channels for central kitchen consolidation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service substitution threatens traditional hardware margins, requiring incumbents to defend recurring revenue streams against leasing-native entrants while navigating brushless DC motor displacement of established drive architectures.
For Market Incumbents: Insulate service revenue through predictive maintenance software integration with hardware platforms, locking central kitchen operators into long-term managed contracts. Deepen backward integration into sealed bearing assembly production to offset German precision engineering premiums. Brushless DC motor substitution demands accelerated R&D in energy recovery torque control to defend drive system market position. For New Entrants and Emerging Players: Pursue FSSAI compliance positioning in Indian institutional catering where certified equipment platforms face limited domestic competition. Target compact footprint designs for UK independent restaurant groups under acute capital rationing pressure. Equipment-as-a-service contract structures offer fastest penetration path against established OEMs. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors predictive maintenance software capabilities over pure hardware scale. Long-term viability over the coming decade hinges on IoT-enabled service revenue conversion. Acquisition targets should demonstrate sensor-integrated bearing assembly portfolios. Watch brushless DC motor adoption rates in prepared meal manufacturing as inflection indicator for drive architecture displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Integration | Sensor-integrated bearing assemblies enable subscription revenue streams from central kitchen operators. |
| Backward Integration into Drive Systems | In-house production of brushless DC motors defends margin position against motor substitution threats. |
| FSSAI Certification Investment | First-mover positioning in Indian institutional catering creates protected market access under expanding food safety infrastructure. |
| Equipment-as-a-Service Launch | Per-kilogram throughput pricing penetrates capital-constrained UK independent restaurant segments. |
| EU Green Deal Compliance Redesign | Modular repairable component architectures satisfy circular economy mandates for German procurement specifications. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at contract food manufacturers, central kitchen operations directors, aftermarket service heads, and regulatory affairs specialists at NSF International and CE marking bodies; and secondary validation through FDA Food Code documentation, EFSA hygiene standard filings, EU machinery directive technical files, and customs records on stainless steel equipment imports. Bottom-up triangulation across manufacturer shipment data and top-down validation through end-user capital expenditure surveys anchored volume estimates.
Forecast inputs span product type segmentation across batch, continuous, and thermal processing configurations; end-use intensity differentiating food manufacturers from restaurant operators; and technology migration tracking mechanical to thermal to intelligent equipment platforms. CAGRs were derived from equipment replacement cycle compression analysis and central kitchen consolidation velocity modeling across the projection horizon. Nickel-chromium price volatility scenarios and F-Gas Regulation phase-down timelines fed industry-specific sensitivity testing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by brushless DC motor specialists or IoT-native equipment-as-a-service entrants would shift outcomes beyond modeled ranges. Cross-checking against NSF International certification issuance rates and central kitchen capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Cook Processor Market