
 Canned Sardines Market | 2026-2036
Canned Sardines Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Sardines Market Analysis
Moroccan and Portuguese cannery operations is consolidating around vertically integrated coastal processing hubs. Thai Union Group leverages its cold-chain logistics network to sustain shelf-stable seafood exports across Asian retail channels. Frinsa Group anchors Iberian supply through dedicated Atlantic fishing partnerships. Dongwon Industries dominates Korean distribution with in-house vessel fleets and automated canning lines.
Canned sardines are small pelagic fish preserved through steam-cooking, oil-brining or water-packing in hermetically sealed containers with shelf lives exceeding 36 months at ambient temperatures. The product serves as an affordable animal protein source for retail pantry stocking and food service portion control. Skinless variants lead volume in North American supermarkets where convenience drives repeat purchase, while spicy formulations in oil capture premium margin pools in Southeast Asian convenience stores. Glass jar packaging for gourmet private-label lines sits at the fastest-growing edge of European distribution.
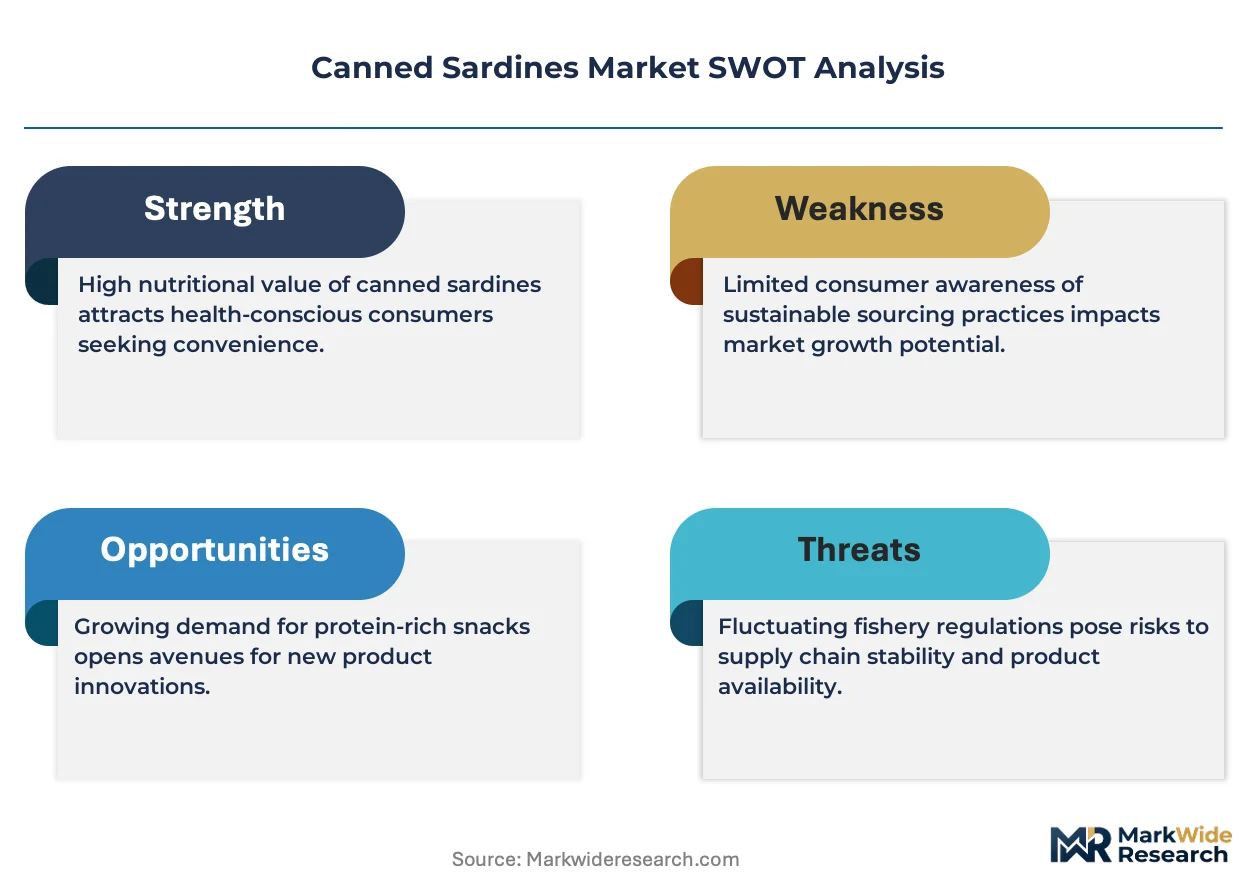
EFSA maximum residue limits for histamine and heavy metals shape EU import gatekeeping, while FDA HACCP mandates govern US cannery compliance and lot traceability. The EU Green Deal fisheries quota framework is forcing processors to document sustainable stock sourcing or face tariff escalation at bloc entry. Stakeholders must monitor evolving Marine Stewardship Council chain-of-custody requirements and decide whether to absorb certification costs or redirect supply toward less regulated Asian wholesale channels.
Market Dynamics
EU Green Deal fisheries quota frameworks are forcing processors to document sustainable stock sourcing or face tariff escalation at bloc entry, compressing margins for non-compliant suppliers while rewarding certified operators with preferential channel access.
Growth Catalysts
- EFSA traceability mandates:The EU's tightened residue limits for histamine and heavy metals are accelerating investment in automated lot-tracking systems. Canneries that achieve full chain-of-custody documentation secure faster customs clearance and retail shelf placement.
- Household pantry restocking cycles:Mature European markets demonstrate structurally embedded consumption patterns in Portugal and Spain, where per capita sardine intake supports volume stability regardless of macroeconomic pressure.
- Glass jar premiumization:Gourmet private-label lines in hermetically sealed glass containers are capturing margin expansion in continental European distribution, with ambient shelf-life parity to traditional tin formats.
Market Restraints
- Pelagic stock volatility:Atlantic sardine biomass fluctuations off Morocco and Portugal create raw material input cost instability that processors cannot fully hedge through forward contracts.
- Single-source supply concentration:Iberian and North African coastal processing hubs dominate global canning capacity, creating geographic vulnerability to port congestion and climate-related fishing moratoriums.
- Plant-based protein substitution:Shelf-stable legume and mycoprotein alternatives are displacing canned fish in North American and Northern European retail meal-planning occasions.
Strategic Opportunities
- Marine Stewardship Council certification gap:Asian wholesale channels currently operate with less stringent chain-of-custody requirements, offering temporary margin shelter for processors delaying EU compliance investment.
- Spicy oil formulation expansion:Southeast Asian convenience store channels demonstrate unmet demand for premium heat-profile variants that command price multiples over standard brine packs.
- Cold-chain logistics convergence:Integration of refrigerated transport networks with ambient shelf-stable distribution is unifying previously separate seafood supply streams and opening food service penetration.
Industry Challenges
- Histamine testing laboratory capacity:EFSA enforcement requires third-party verification that outstrips certified testing facility availability in North African sourcing regions, extending lot-release timelines.
- Automated canning line retrofit costs:Legacy Portuguese and Spanish facilities face capital intensity barriers when upgrading to vision-sorting and laser-coding systems required for full traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Sardines Market |
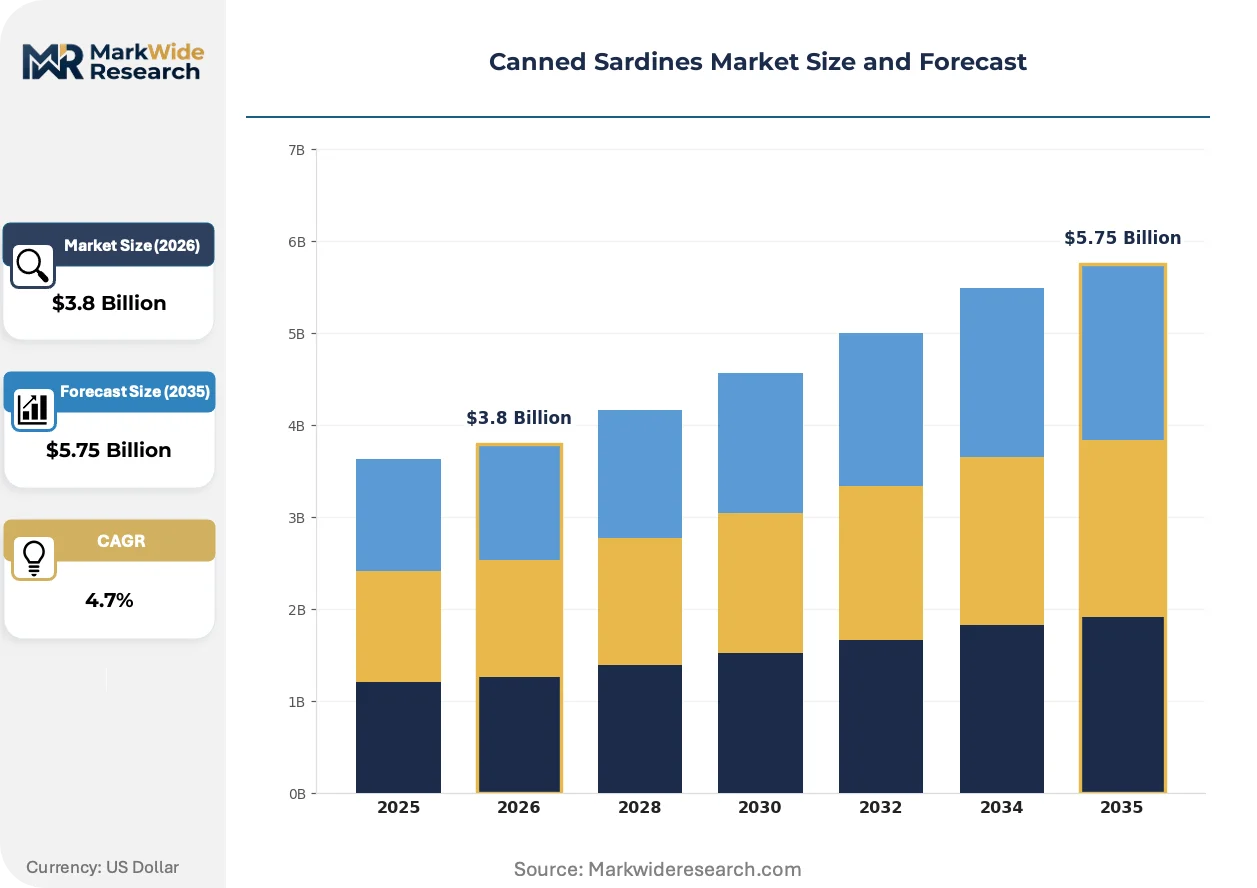
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinless, With Skin, Spicy, In Oil Packaging Type: Can, Glass Jar, Pouch, Tin Distribution Channel: Supermarket, Online, Convenience Store, Wholesale End User: Retail, Food Service, Households, Industrial |
| Companies Covered | Bolton Group, Frinsa Group, Thai Union Group, Crown Prince, Ocean Brands, Bumble Bee Foods, Dongwon Industries, Wild Planet Foods, Starkist Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Sardines Market Emerging Trajectories
Processing technology and packaging formats are converging to address traceability mandates while capturing premiumization opportunities in convenience-oriented retail channels. These shifts favor operators with capital reserves for automated line investment.
Retort pouch technology is unifying the portability advantages of flexible packaging with the shelf-stability credentials of traditional tin formats. Southeast Asian retailers are adopting these SKUs for single-serve meal solutions that reduce warehouse storage cube requirements. The format compression is enabling direct-to-convenience-store distribution that bypasses traditional wholesale consolidation layers.
EU Green Deal fisheries quota frameworks are mandating electronic catch documentation and vessel monitoring systems for all imports entering bloc ports. Moroccan and Portuguese flag fleets must now transmit real-time position data to secure unloading authorization. Small-scale artisanal operators lacking satellite connectivity face exclusion from EU-bound supply chains unless they consolidate through cooperative data-sharing arrangements.
Skinless and boneless product specifications are displacing traditional whole-fish packs in North American supermarket resets as meal-preparation time compression drives purchase decisions. Retail buyers in the US are prioritizing pull-tab lid convenience and single-serve portion geometry over commodity pricing. The preference shift is visible in planogram allocations that relegate traditional formats to bottom-shelf positions while eye-level placement goes to value-added SKUs.
Canned Sardines Market Segmentation
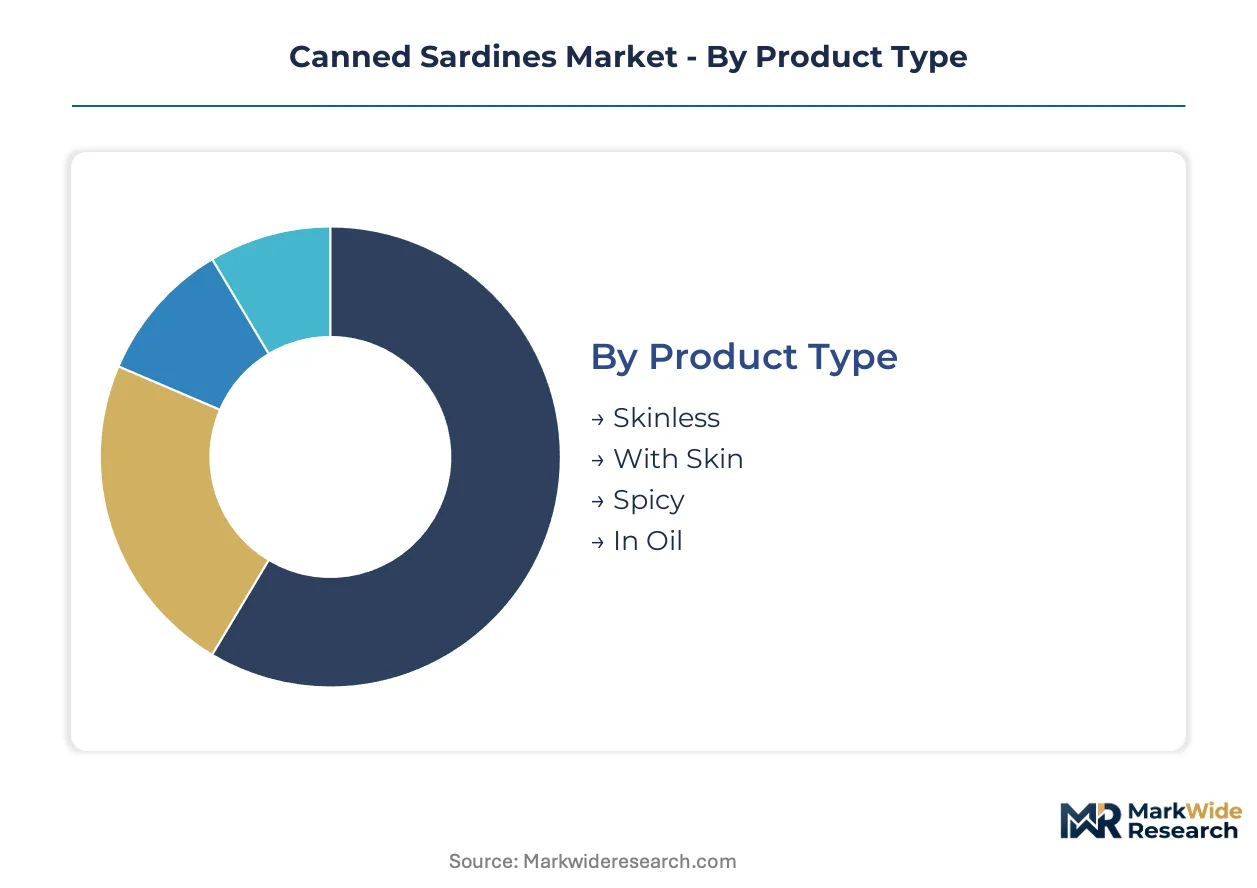
Segmentation in canned sardines reflects divergent buyer priorities across convenience, culinary tradition, and supply chain access. Product format and channel selection determine margin capture, while end-user distinctions separate pantry-stocking volume from food service procurement logic.
Product Type:
Buyers differentiate primarily by preparation time tolerance and flavor preference intensity.
- Skinless:Mechanical removal of skin and pin bones yields ready-to-eat portions requiring zero consumer preparation. North American supermarket resets prioritize these SKUs for meal-prep time compression, with pull-tab lids and single-serve geometry commanding eye-level planogram placement over commodity formats.
- Spicy:Chili-infused oil formulations target Southeast Asian convenience store channels where heat-profile intensity correlates with price multiples over standard brine packs. These variants capture premium margin pools in markets with established spicy condiment traditions.
- With Skin:Traditional whole-fish preservation maintains structural integrity preferred in Iberian and North African culinary applications where skin texture signals freshness authenticity.
- In Oil:Olive or vegetable oil packing extends shelf stability and enables direct incorporation into Mediterranean-style salads without additional fat addition.
Volume sits with Skinless; growth tilts toward Spicy.
Packaging Type:
Channel economics and storage density requirements shape format selection across retail tiers.
- Can:Tin-plated steel containers dominate ambient shelf-stable distribution with 36-month durability and established recycling infrastructure. Portuguese and Moroccan coastal canneries operate automated seaming lines optimized for cylindrical geometry at throughput scales glass cannot match.
- Pouch:Retort flexible packaging reduces warehouse cube requirements by 40% versus rigid formats, enabling direct-to-convenience-store distribution that bypasses wholesale consolidation layers in Southeast Asian retail networks.
- Glass Jar:Hermetically sealed gourmet private-label lines in transparent containers support premium positioning in continental European distribution with ambient shelf-life parity to tin formats.
- Tin:Traditional rectangular formats persist in wholesale industrial procurement for food service portion control and institutional meal planning.
Can holds the volume base; Pouch climbs the fastest on logistics efficiency gains.
Distribution Channel:
Buyer access patterns separate planned pantry stocking from impulse-driven consumption occasions.
- Supermarket:Planned purchase environments in Portugal and Spain sustain structurally embedded consumption through multi-pack promotions and private-label penetration. EFSA traceability mandates accelerate automated lot-tracking investment to secure shelf placement in these regulated channels.
- Convenience Store:Impulse-driven single-serve purchases in Southeast Asia favor spicy oil variants with immediate consumption potential and minimal preparation requirements.
- Online:Direct-to-consumer subscription models aggregate niche demand for glass jar premium lines and artisanal Moroccan imports outside traditional retail footprints.
- Wholesale:Food service and industrial procurement concentrates in pallet-scale transactions with specification-driven contracting for skinless boneless product grades.
Supermarket anchors volume stability; Convenience Store captures the steepest expansion trajectory on urbanization-driven format adoption.
End User:
Procurement scale and specification precision separate household discretion from institutional compliance requirements.
- Households:Pantry-stocking behavior in mature European markets demonstrates per capita consumption rigidity regardless of macroeconomic pressure, with Portugal and Spain maintaining dietary habit embeddedness across income tiers.
- Food Service:Portion-controlled skinless formats enable kitchen labor reduction and plate-cost predictability for restaurant operators managing protein input standardization.
- Retail:Branded and private-label SKUs compete for shelf space based on margin contribution and velocity metrics, with EFSA documentation requirements filtering supplier eligibility.
- Industrial:Ingredient-grade sardine inputs supply processed food manufacturers requiring specified particle size and oil content for secondary product formulation.
Households dominate tonnage; Food Service gains share fastest on out-of-home dining recovery and labor cost compression priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlantic coastal waters off Morocco and Portugal supply the primary raw material base for global canning operations. Processing infrastructure clusters along these shorelines where vessel-to-factory proximity minimizes post-catch degradation. Regulatory divergence between EU traceability mandates and Asian wholesale channel requirements creates geographic arbitrage opportunities for processors.
Portugal
Matosinhos and Peniche harbor districts sustain Europe's densest cannery concentration with multi-generational workforce expertise in hand-packing techniques. EFSA electronic catch documentation requirements now mandate real-time vessel monitoring for all EU-bound landings. The Algarve fishing cooperative federation aggregates artisanal boat data to maintain bloc market access for small-scale operators.
Spain
Galician household consumption patterns demonstrate per capita sardine intake rigidity across income tiers, insulating volume from macroeconomic pressure. The national food safety agency enforces histamine testing protocols that exceed baseline EU thresholds, extending lot-release timelines for domestic processors. Vigo port infrastructure handles the largest Atlantic sardine unloading volumes outside Moroccan waters.
Morocco
Agadir and Safi processing hubs dominate global canning capacity with vertically integrated operations spanning vessel fleets to automated seaming lines. EU Green Deal fisheries quota frameworks now require satellite-transmitted position data for unloading authorization at bloc ports. Coastal cooperative consolidation accelerates as artisanal operators lacking connectivity seek data-sharing arrangements to preserve EU channel access.
United States
Supermarket reset priorities favor skinless boneless SKUs with pull-tab lids and single-serve geometry over traditional whole-fish formats. FDA HACCP mandates govern domestic cannery compliance with lot traceability requirements for retail distribution. Pacific Northwest retail buyers increasingly allocate eye-level planogram placement to value-added product specifications.
Thailand
Convenience store channel expansion drives demand for spicy oil formulations with immediate consumption potential in urban centers. Cold-chain logistics networks sustain shelf-stable seafood exports across Southeast Asian retail channels with ambient distribution parity. Bangkok-based distribution hubs enable direct-to-convenience-store delivery that bypasses traditional wholesale consolidation layers.
Canned Sardines Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue premium private-label positioning and alternative packaging formats. Market structure consolidates around coastal processing hubs where vessel proximity and automated line scale create defensive moats. Three archetypes dominate: vertically integrated Atlantic operators, Asian logistics-integrated exporters, and North American brand-house specialists. Competitive moves concentrate on Marine Stewardship Council certification acquisition and retort pouch format adoption.
Among Iberian coastal operators, Frinsa Group exemplifies the Atlantic-integrated archetype with dedicated fishing partnerships anchoring raw material security. Thai Union Group represents the logistics-integrated Asian exporter model, leveraging cold-chain infrastructure for regional retail penetration. Dongwon Industries occupies the scale-driven position with in-house vessel fleets and automated canning capacity. These three entities illustrate the geographic and operational stratification defining competitive positioning.
| Leading Market Players |
|---|
| Bolton Group |
| Frinsa Group |
| Thai Union Group |
| Crown Prince |
| Ocean Brands |
| Bumble Bee Foods |
| Dongwon Industries |
| Wild Planet Foods |
| Starkist Co. |
| Others |
Supply Flow & Price Mechanics
Automated vision-sorting and laser-coding systems for EFSA traceability compliance simultaneously inflate capital expenditure requirements and consolidate processing capacity among Moroccan and Portuguese coastal operators with balance sheet depth. This technology transition compresses margins for legacy canneries while rewarding certified facilities with preferential EU channel access and faster customs clearance.
Pricing Analysis
Warranty-equivalent service bundling separates premium glass jar private-label lines from unbundled commodity tin formats in continental European distribution. Three-tier pricing structure across premium, standard, and economy levels stratifies by Marine Stewardship Council certification grade and automated lot-tracking capability. Pricing pressure stems from EFSA histamine testing laboratory capacity constraints extending lot-release timelines and inflating working capital requirements. Food service procurement demonstrates lowest price sensitivity due to portion-control labor savings, while North American supermarket private-label buyers drive hardest bargain on skinless boneless specifications.
Supply Chain Analysis
Direct-to-convenience-store distribution through Bangkok-based hubs handles Southeast Asian urban demand for spicy oil single-serve pouches, bypassing wholesale consolidation layers. Raw material supply concentrates in Morocco, Portugal, and Spain where Atlantic sardine biomass fluctuations create input cost instability. Automated seaming equipment, cold-chain logistics infrastructure, and satellite-enabled vessel monitoring systems constitute critical dependencies. Single-source geographic concentration around Agadir-Safi and Matosinhos-Peniche clusters exposes the network to climate-related fishing moratoriums and port congestion cascades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch technology is displacing traditional tin formats across Southeast Asian convenience channels, compressing warehouse cube requirements and enabling direct retail distribution that legacy rigid packaging cannot match.
For Market Incumbents: Acquire automated vision-sorting and laser-coding asset classes to secure EFSA traceability compliance and defend shelf placement against Moroccan coastal competitors. Consolidate through cooperative data-sharing arrangements with artisanal Portuguese flag fleets to preserve EU channel access. Prioritize backward integration into satellite-enabled vessel monitoring systems to meet EU Green Deal real-time position transmission mandates. For New Entrants and Emerging Players: EU Green Deal fisheries quota frameworks in Portugal and Spain open a window for glass jar gourmet private-label positioning in underpenetrated North American online subscription channels. Target Southeast Asian convenience store spicy oil variants where heat-profile intensity commands premium multiples over standard brine packs. Pursue direct-to-retailer distribution bypassing wholesale layers to capture logistics efficiency gains. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated Atlantic coastal operators with captive vessel fleets and automated canning line scale. Long-term viability hinges on EFSA compliance infrastructure and Marine Stewardship Council certification asset ownership. Monitor artisanal cooperative federation consolidation velocity in Portugal's Algarve region as inflection indicator for small-scale operator exclusion risk.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Stewardship Council Certification Acquisition | EFSA gatekeeping requirements reward certified operators with preferential EU retail shelf placement and faster customs clearance. |
| Retort Pouch Format Adoption | Southeast Asian convenience store channels reduce warehouse cube requirements by 40% versus rigid tin formats. |
| Backward Integration into Vessel Monitoring Systems | EU Green Deal mandates real-time satellite position data transmission for unloading authorization at bloc ports. |
| Glass Jar Premium Line Extension | Continental European gourmet private-label positioning captures margin expansion with ambient shelf-life parity to traditional formats. |
| Direct-to-Convenience-Store Distribution Buildout | Bangkok-based cold-chain hubs enable bypass of wholesale consolidation layers in Southeast Asian urban retail networks. |
Methodological Framework
Document review covered customs and trade flow databases, EFSA regulatory filings, and Marine Stewardship Council chain-of-custody records, complemented by interviews with Moroccan cannery operations directors, Portuguese fishing cooperative federation managers, Southeast Asian convenience store category buyers, and North American supermarket private-label procurement leads. Secondary validation drew from EU catch documentation system transmissions, FDA HACCP compliance records, and Atlantic sardine biomass assessment reports. Bottom-up volume modeling triangulated against top-down value estimates across product format, packaging type, distribution channel, and end-user segmentation dimensions.
Segment-level projections across the analysis window applied elasticity-adjusted consumption trend extrapolation calibrated to EFSA regulatory phase-in schedules and EU Green Deal quota implementation timelines. Modeled dimensions spanned preparation type, packaging format, channel access pattern, and geographic regulatory cluster. CAGRs derived from historical volume trajectory analysis adjusted for technology substitution effects and certification penetration curves. Forecast inputs incorporated automated line retrofit cost schedules, histamine testing laboratory capacity expansion plans, and retort pouch adoption rate assumptions by regional retail network.
Caveats apply where Atlantic sardine biomass volatility, EFSA enforcement intensity variation, or plant-based protein substitution acceleration could materially shift the outlook beyond modeled ranges. Forecasts rest on assumptions regarding cooperative federation consolidation velocity and satellite connectivity penetration among artisanal vessel operators. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Europe Dried Scallop Market
Seafood
Trout Market
Seafood
Shellfish Market
Seafood
Dry-Packaged Scallops Market
Seafood
Canned Anchovy Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Salmon Fish Market
Seafood
Haddock Market
Seafood
Halibut Market
Seafood
Europe Shrimp Market
Seafood
Molluscs Market
Seafood
Mussel Oil Market
Seafood
Food Clamshells Market
Seafood
Tuna Market
Seafood
Middle East Seafood Market
Seafood
Canned Seafood Market