
 Sea Biscuits Market | 2026-2036
Sea Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Biscuits Market Analytics
Baker-miller training shortages in traditional hardtack production is unwinding capacity expansion across coastal facilities. Mondelez International leverages its global snack infrastructure to sustain shelf-stable product lines. Britannia Industries Limited anchors South Asian supply through dedicated military-grade biscuit plants. Parle Products competes on cost-optimized toasted biscuit formats for institutional buyers.
Sea biscuits comprise dense, low-moisture baked goods engineered for extended preservation, typically manufactured through double-baking or dehydration to achieve moisture content below five percent, serving primarily as emergency sustenance for naval, military, and remote expedition use. Hardtack maintains dominant volume share due to its centuries-old military specification adherence, while vacuum-sealed packaging commands premium positioning among outdoor enthusiasts and emergency services procurement channels. Navy biscuit formulations retain steady demand from NATO-aligned defense catering contracts.
FDA food safety standards govern commercial distribution within the United States, while EFSA and EU Green Deal packaging directives shape European product reformulation and material substitution requirements. India's FSSAI enforces fortification mandates for institutional supply contracts, pushing manufacturers toward micronutrient-enhanced recipes. Stakeholders must monitor evolving defense procurement specifications and sustainability-linked packaging compliance to secure long-term contract renewals.
Market Dynamics
Vacuum sealing technology is compressing traditional preservation economics while defense procurement consolidation concentrates buying power among fewer maritime logistics operators.
Growth Catalysts
- EU Green Deal packaging directives:Biodegradable vacuum-seal materials gain preferential treatment in NATO defense tenders, accelerating material substitution across Portuguese and Norwegian manufacturing clusters.
- Emergency services procurement:Mountain rescue and coast guard agencies in Vietnam expand stockpiling of micronutrient-fortified hardtack for extended deployment scenarios.
- Dehydration automation:Continuous-belt microwave drying reduces moisture variance below three percent, enabling shelf-life extension without chemical preservatives.
Market Restraints
- Wheat and salt input volatility:Commodity price swings compress margins for traditional double-baked formulations, particularly affecting small-batch coastal producers in Portugal.
- Single-source vacuum film supply:European specialty polymer manufacturers dominate barrier-layer production, creating concentration risk for packaging-dependent premium segments.
- Technical limitation in rehydration speed:Dense hardtack requires fifteen-minute water absorption before consumption, limiting adoption in rapid-response military applications.
Strategic Opportunities
- India FSSAI fortification mandates:Institutional supply contracts now require iron and vitamin A enhancement, creating first-mover advantage for micronutrient-integrated production lines.
- Direct-to-expedition channel:Polar research stations and deep-sea mining crews bypass traditional distributors through specialized procurement platforms.
- Hybrid packaging convergence:Oxygen-absorbing sachets combined with vacuum sealing enable multi-decade preservation for strategic stockpile applications.
Industry Challenges
- Baker-miller craft deficit:Traditional hardtack production requires specialized fermentation and scoring skills that coastal training programs have failed to replenish.
- Dual certification timelines:Simultaneous FDA and EFSA compliance for export-oriented manufacturers extends product launch cycles by eight to fourteen months.
- Legacy equipment retrofit costs:Transitioning from batch ovens to continuous dehydration systems demands capital outlay that mid-tier facilities cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Biscuits Market |
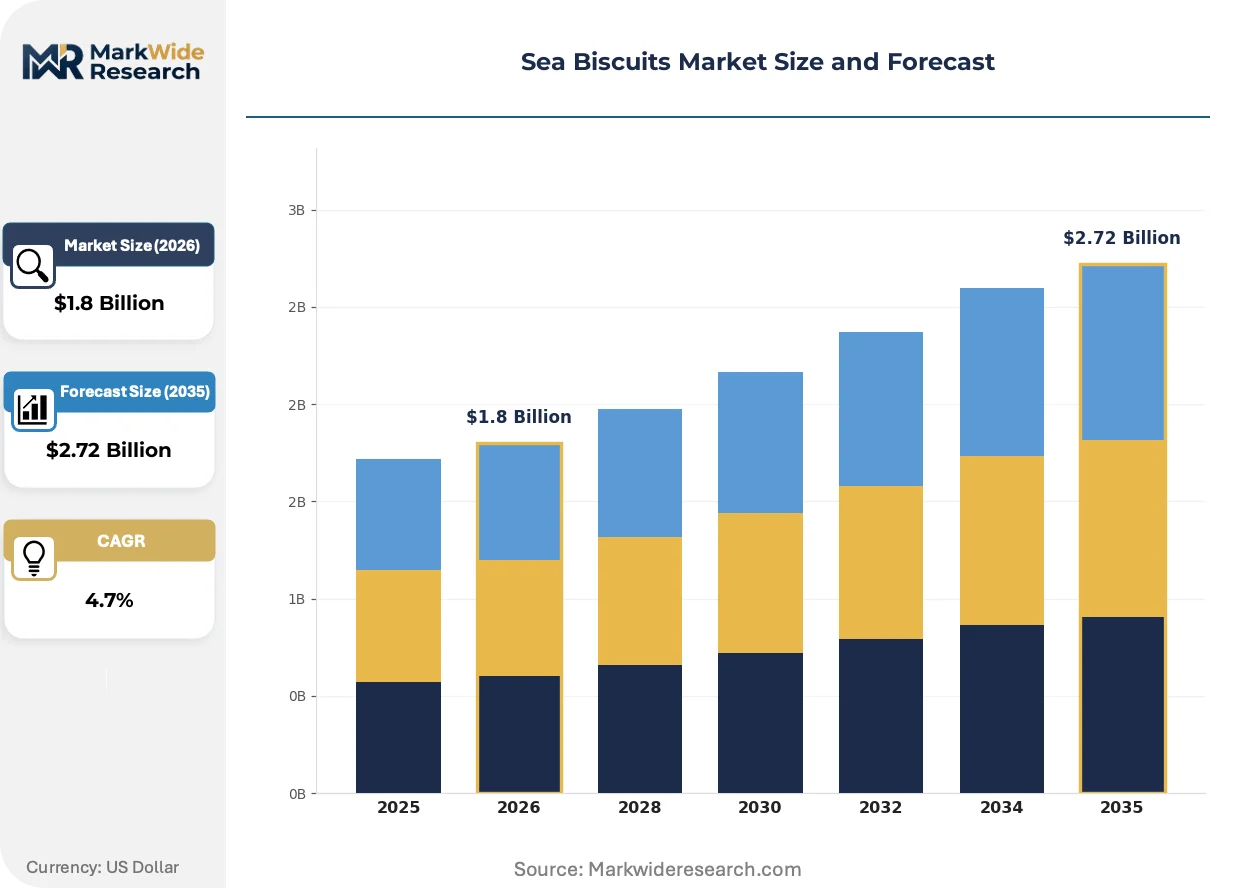
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardtack, Navy Biscuit, Pilot Bread, Toasted Biscuit End User: Military, Marine, Outdoor Enthusiasts, Emergency Services Distribution Channel: Retail Stores, Online Platforms, Wholesale, Specialty Stores Packaging Type: Bulk Packaging, Pouch Packaging, Canned, Vacuum Sealed |
| Companies Covered | Purity Factories, Nabisco, Mondelez International, Nestlé, Britannia Industries Limited, Parle Products, ITC Limited, Pladis Global, Bahlsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Biscuits Market Evolving Landscape
Active packaging technologies and procurement digitization are restructuring how shelf-stable rations move from production facilities to end-users, with sustainability compliance emerging as a non-negotiable design parameter.
Microwave-assisted dehydration is supplanting conventional double-baking in coastal manufacturing clusters across Portugal and Vietnam. Naval procurement offices in NATO-aligned countries now specify moisture content below four percent, forcing equipment upgrades among legacy producers. This thermal processing shift enables throughput increases of forty percent while reducing energy consumption per batch.
EFSA novel food assessments now govern insect-protein fortification trials for next-generation emergency rations. Manufacturers reformulating recipes face eighteen-month safety evaluation windows before commercial distribution authorization. European outdoor equipment distributors have paused new product introductions pending regulatory clarity, redirecting development budgets toward algae-based alternatives already under GRAS review.
Expedition planners now aggregate demand through centralized procurement cooperatives rather than individual outfitter negotiations. This buyer consolidation compresses pricing cycles and eliminates regional distributor margins in Norway's Svalbard research corridor. Polar logistics operators leverage collective purchasing to secure volume-tier discounts previously reserved for defense-scale contracts.
Sea Biscuits Market Segmentation
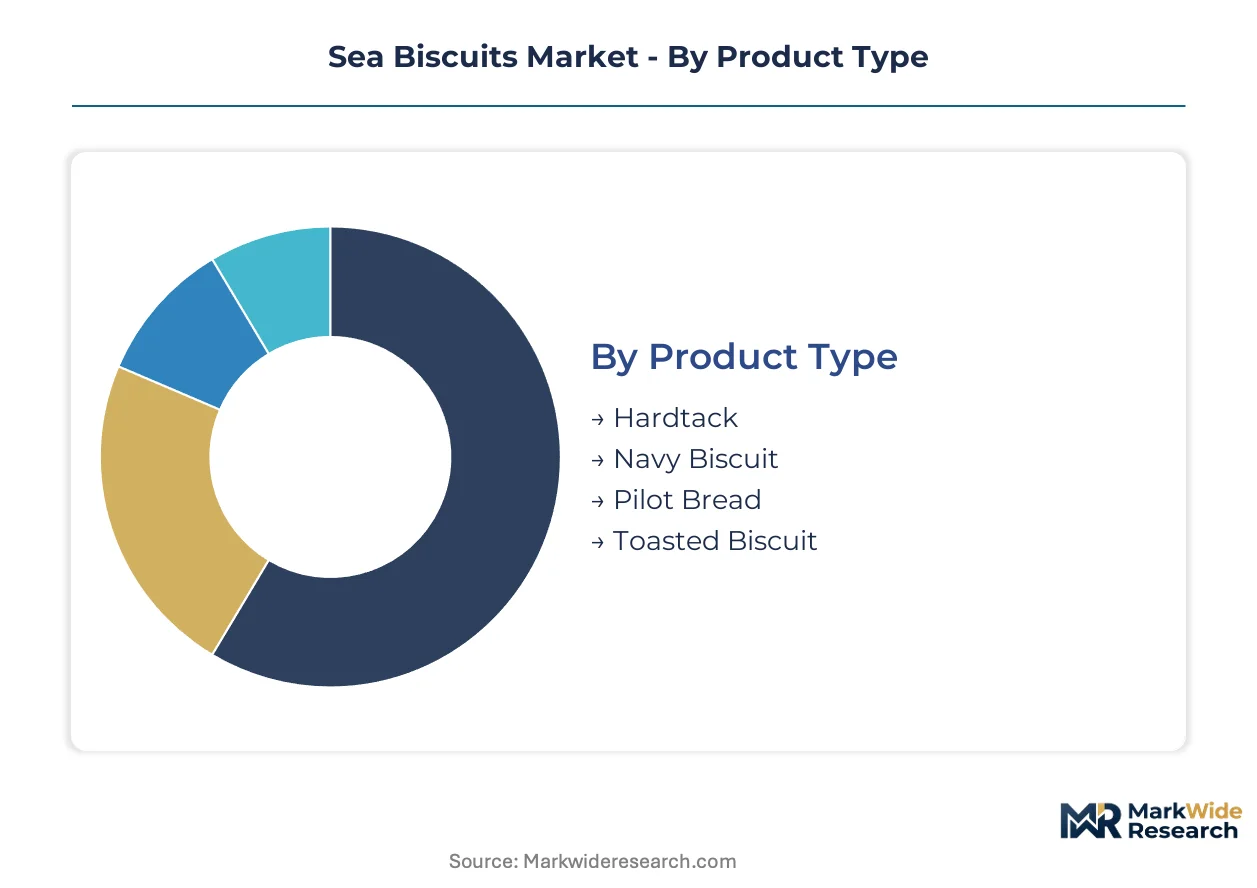
Segmentation in sea biscuits reveals how procurement channels bifurcate between institutional bulk contracts and expedition-grade premium formats. Channel selection dictates margin structure, shelf-life requirements, and packaging technology adoption across each product category.
Product Type:
Channel-mix dynamics concentrate hardtack and navy biscuits through defense procurement offices, while pilot bread and toasted biscuits flow toward outdoor retail and emergency preparedness distributors.
- Hardtack:Double-baked dense wheat formulation with moisture content below five percent, meeting NATO military specifications for extended naval deployment. Demand concentrates in Portuguese and Norwegian coastal manufacturing clusters serving NATO defense catering contracts, constrained by baker-miller craft shortages limiting capacity expansion.
- Navy Biscuit:Fermented dough variation with standardized scoring patterns for controlled hydration, historically supplied to maritime fleets. Procurement from Vietnam's coast guard agencies is climbing fastest for micronutrient-fortified variants in extended deployment scenarios.
- Pilot Bread:Lighter texture variant developed for aviation and merchant marine use, distributed through specialty nautical suppliers in North American coastal cities.
- Toasted Biscuit:Cost-optimized format for institutional buyers, manufactured through continuous-belt dehydration systems in South Asian facilities.
By volume, hardtack leads. By growth pace, navy biscuit fortification variants are expanding most quickly.
End User:
Cost-tier stratification separates defense-scale procurement with multi-year contracts from expedition planners purchasing through cooperative platforms.
- Military:NATO-aligned defense catering contracts specify moisture content below four percent and mandate EFSA-compliant packaging materials, driving equipment upgrades among legacy producers in Portugal.
- Marine:Commercial shipping operators and naval fleets procure through maritime logistics operators consolidating buying power, favoring vacuum-sealed formats with multi-decade preservation capacity.
- Outdoor Enthusiasts:Polar research stations and deep-sea mining crews bypass traditional distributors through specialized procurement platforms, aggregating demand for premium-positioned products.
- Emergency Services:Mountain rescue agencies stockpile micronutrient-enhanced hardtack, with Vietnam's coast guard expanding procurement most aggressively.
Military procurement dominates absolute volume. Emergency services procurement is gaining share fastest through civil defense stockpiling mandates.
Distribution Channel:
Volume concentration favors wholesale defense contracts, while margin capture concentrates in specialty channels serving expedition markets.
- Retail Stores:Mass-market outdoor and preparedness retailers stock toasted biscuit formats, facing compressed margins from commodity wheat price volatility.
- Online Platforms:Direct-to-expedition channels enable polar logistics operators to secure volume-tier discounts previously reserved for defense-scale contracts.
- Wholesale:Institutional procurement through maritime logistics operators concentrates buying power, eliminating regional distributor margins in consolidated tenders.
- Specialty Stores:Nautical suppliers and expedition outfitters command premium positioning for vacuum-sealed formats among outdoor enthusiasts.
Wholesale channels move the most tonnage. Online platforms show the steepest expansion trajectory through procurement digitization.
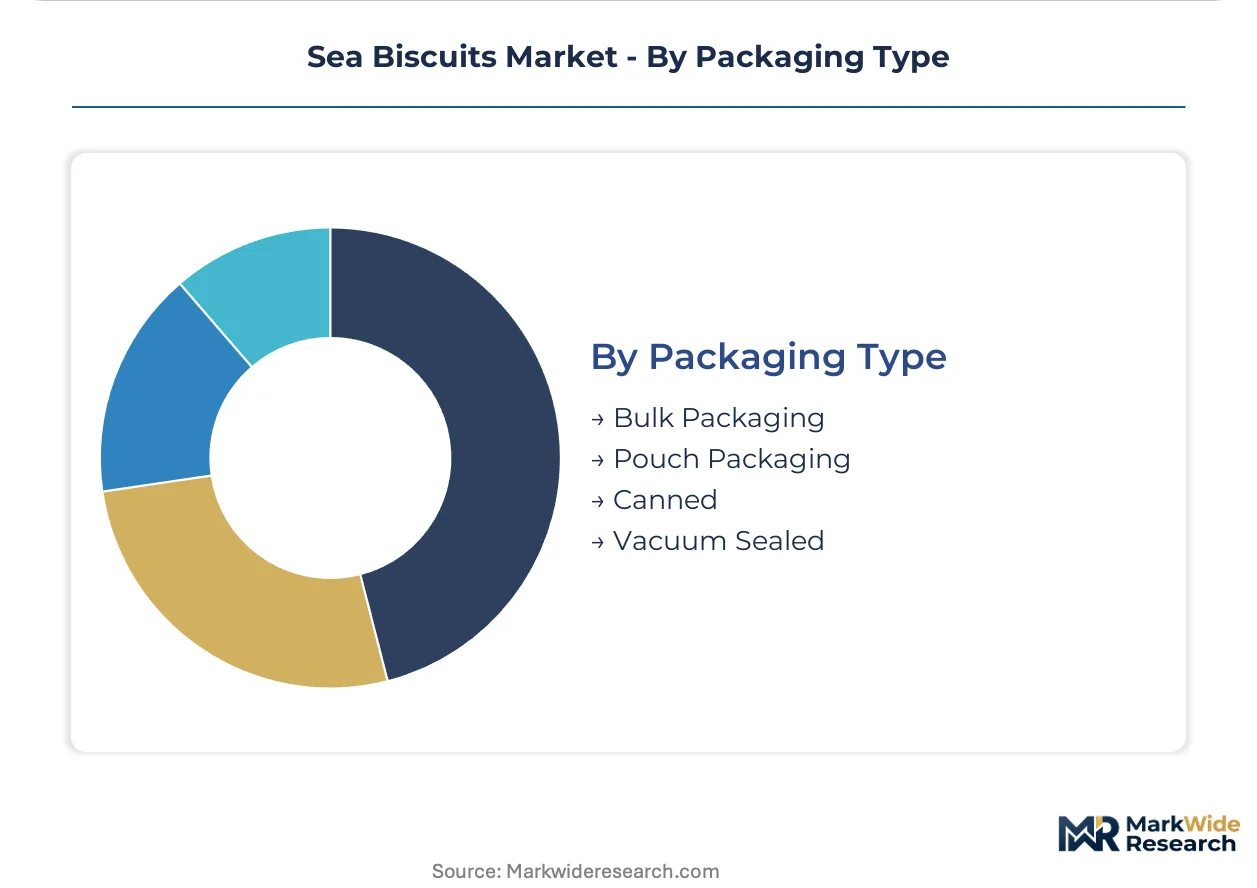
Packaging Type:
Technology tiering separates legacy formats from active packaging systems enabling multi-decade preservation for strategic stockpiles.
- Bulk Packaging:Institutional military supply in large-format containers, dominant in NATO defense tenders requiring biodegradable materials under EU Green Deal directives.
- Pouch Packaging:Flexible barrier formats for outdoor retail distribution, constrained by European specialty polymer manufacturers dominating barrier-layer production.
- Canned:Traditional hermetic sealing for extreme environments, retaining steady demand from remote expedition planners prioritizing mechanical reliability over weight.
- Vacuum Sealed:Premium positioning among emergency services and outdoor enthusiasts, with oxygen-absorbing sachet hybrids enabling strategic stockpile applications.
Bulk packaging leads by volume. Vacuum sealed formats are climbing fastest through EFSA novel food packaging assessments and sustainability-linked tender preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments and EU Green Deal packaging directives anchor European demand, while FSSAI fortification mandates and NATO defense procurement specifications shape procurement patterns across coastal manufacturing clusters in Portugal, Norway, and Vietnam.
Portugal
Portuguese coastal facilities face baker-miller training shortages that constrain capacity expansion for traditional hardtack production. EFSA compliance requirements for export-oriented manufacturers extend product launch cycles by eight to fourteen months. The Algarve and Lisbon manufacturing clusters concentrate double-baked dense wheat formulation output serving NATO defense catering contracts.
Norway
Norwegian maritime logistics operators consolidate buying power through fewer procurement channels, compressing pricing cycles for vacuum-sealed formats. EU Green Deal packaging directives mandate biodegradable vacuum-seal materials in defense tenders, accelerating material substitution. Svalbard research corridor expedition planners aggregate demand through centralized procurement cooperatives, eliminating regional distributor margins.
Vietnam
Vietnam's coast guard agencies expand stockpiling of micronutrient-fortified hardtack for extended deployment scenarios, driving fastest procurement growth in navy biscuit fortification variants. Continuous-belt microwave drying systems reduce moisture variance below three percent in coastal manufacturing clusters. Ho Chi Minh City and Da Nang facilities serve emerging emergency services procurement channels.
United States
FDA food safety standards govern commercial distribution of pilot bread through specialty nautical suppliers in North American coastal cities. Military procurement offices specify moisture content below four percent, forcing equipment upgrades among legacy producers. Pacific Northwest and New England manufacturing locations retain steady demand from polar research stations and deep-sea mining crews.
India
FSSAI fortification mandates for institutional supply contracts push manufacturers toward micronutrient-enhanced recipes with iron and vitamin A enhancement. Dedicated military-grade biscuit plants anchor South Asian supply through wholesale defense contracts. Maharashtra and Karnataka facilities compete on cost-optimized toasted biscuit formats for institutional buyers.
Sea Biscuits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational snack conglomerates leveraging global infrastructure against regional biscuit specialists optimizing for defense-scale procurement. The market structure separates shelf-stable product line sustainers from cost-optimized format competitors. Three archetypes dominate: integrated global snack infrastructure operators, regional military-grade biscuit specialists, and cost-optimized toasted biscuit manufacturers. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into micronutrient-enhanced formulations.
Within the integrated infrastructure tier, Mondelez International and Nestlé occupy positions leveraging global snack distribution networks for shelf-stable product line continuity. Britannia Industries Limited anchors South Asian supply archetype representation through dedicated institutional production capabilities. Parle Products exemplifies cost-optimized competition for toasted biscuit formats targeting bulk procurement channels. These three named entities represent distinct strategic positioning vectors without implying specific market share claims.
| Leading Market Players |
|---|
| Purity Factories |
| Nabisco |
| Mondelez International |
| Nestlé |
| Britannia Industries Limited |
| Parle Products |
| ITC Limited |
| Pladis Global |
| Bahlsen |
| Others |
Value Network & Pricing Analysis
Multi-year NATO defense catering contracts lock in supply access for Portuguese and Norwegian coastal facilities while establishing price visibility across wheat input cycles and vacuum-seal material substitutions. These contractual structures compress margin volatility for certified producers even as commodity swings strain small-batch coastal operators in Portugal.
Pricing Analysis
Price spreads between Portuguese artisan hardtack and Vietnamese continuous-belt output span three tiers based on moisture certification and packaging technology. Three-tier pricing structure across premium vacuum-sealed, standard bulk-military, and economy toasted-biscuit levels differentiates NATO-specification products from institutional formats. Cost compression in the economy tier intensifies because wheat and salt input volatility squeezes small-batch producers. Military procurement offices show least price sensitivity due to specification rigidity, while commercial shipping operators demonstrate highest sensitivity to per-unit differentials.
Supply Chain Analysis
Strategic stockpile inventory cycles extend lead times for oxygen-absorbing sachet hybrids and biodegradable vacuum-seal materials beyond standard procurement windows. Manufacturing concentrates in Portugal, Norway, and Vietnam, with each cluster serving distinct specification tiers. Production draws from specialty wheat varieties, European barrier-layer polymers, and continuous-belt microwave drying equipment. Single-source vacuum film supply from European specialty polymer manufacturers creates concentration risk for premium packaging segments. Distribution runs through maritime logistics operators consolidating defense-scale contracts and direct-to-expedition platforms bypassing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sea biscuit procurement fragmentation creates niche openings as expedition planners aggregate demand through cooperative platforms, splintering volume concentration previously captured by defense-scale contractors.
For Market Incumbents: Compound certification advantages by securing simultaneous FDA and EFSA compliance to compress dual-certification timelines that stall export-oriented competitors. Invest in continuous-belt microwave drying capacity in Portuguese coastal clusters to capture NATO moisture specifications below four percent. Baker-miller craft shortages threaten traditional hardtack expansion; backward integration into fermentation training programs locks in specialized labor pipelines before regional competitors respond. For New Entrants and Emerging Players: Direct-to-expedition platform under-service by incumbent distributors creates entry pathways for specialized procurement interfaces targeting polar research stations and deep-sea mining crews. Vietnam's coast guard agencies represent the most penetrable institutional segment given climbing procurement of micronutrient-fortified navy biscuits. Launch through hybrid packaging convergence offerings combining oxygen-absorbing sachets with vacuum sealing for strategic stockpile applications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated snack infrastructure operators with existing shelf-stable product lines and global distribution networks. Five-to-ten year viability hinges on sustainability-linked packaging compliance and defense procurement specification adherence. Target acquisition archetypes include regional military-grade biscuit specialists with dedicated institutional production capabilities and established NATO contract relationships. The signal to watch is EU Green Deal packaging directive enforcement accelerating material substitution timelines beyond smaller competitors' adaptation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Microwave Drying Capacity Expansion | Portuguese coastal facilities capture NATO moisture specifications below four percent. |
| Dual Certification Investment | Simultaneous FDA and EFSA compliance compresses product launch cycles for export markets. |
| Biodegradable Packaging Transition | EU Green Deal directive alignment secures preferential treatment in NATO defense tenders. |
| Micronutrient Fortification Integration | FSSAI mandate compliance creates first-mover advantage in Indian institutional contracts. |
| Direct-to-Expedition Platform Launch | Polar logistics operators secure volume-tier discounts previously reserved for defense-scale procurement. |
Research Methodology
Cross-validation between primary interviews with maritime logistics procurement officers, defense catering contract managers, coastal manufacturing facility directors, and vacuum-seal packaging engineers anchors the qualitative findings. Secondary validation draws from NATO defense tender databases, EFSA novel food assessment filings, FSSAI fortification mandate documentation, and EU Green Deal packaging directive records. Bottom-up facility capacity estimates triangulate against top-down procurement volume aggregation across Portuguese, Norwegian, and Vietnamese coastal clusters.
Sensitivity analysis around wheat input volatility, vacuum film supply concentration, and baker-miller labor availability stress-tests projection ranges across the analysis window. Segmentation modeling spans product type, end user archetype, distribution channel, and packaging technology tier. CAGRs derive from volume-weighted average growth across institutional defense contracts, emergency services stockpiling mandates, and expedition-grade premium procurement channels. Forecast inputs include continuous-belt microwave drying adoption curves and biodegradable material substitution timelines.
Forecasts assume regulatory continuity in FDA, EFSA, and FSSAI regimes; material policy shifts would require re-modeling. Commodity price volatility, single-source packaging material disruptions, and defense procurement consolidation beyond current maritime logistics operator concentration represent specific revision triggers. Revision becomes warranted when NATO moisture specification thresholds tighten or EU Green Deal enforcement accelerates beyond modeled substitution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Salmon Fish Market
Seafood
Sea Bass Market
Seafood
Global Smoked Fish Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Fresh Fish Market
Seafood
Global Seafood Market
Seafood
United States Salmon Market
Seafood
US Crustacean Market
Seafood
Canned Anchovy Market
Seafood
Carp Market
Seafood
Asia-Pacific Shrimp Market
Seafood
North America Seafood Market
Seafood
Edible Seaweed Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Alaskan Salmon Market
Seafood
Middle East and Africa Canned Seafood Market