
 Cod Fish Market | 2026-2036
Cod Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Cod Fish Market Analysis
North Atlantic whitefish producers is pivoting toward value-added fillet and loin products as raw-material volatility pressures commodity margins. Norsk Fisk leverages its integrated trawler-to-retail chain to secure consistent supply for European retail clients. Royal Greenland anchors its competitive position through dominance of inshore Greenlandic cod quotas. Lerøy Seafood Group differentiates via specialized fresh-fillet operations serving Scandinavian restaurant networks.
Cod comprises Gadus morhua and related Gadidae species, a lean whitefish containing approximately 17% protein and less than 1% fat by weight, harvested through bottom trawling, longlining, or hook-and-line methods for human consumption across fresh, frozen, and preserved formats. Frozen cod maintains the largest volume position due to extended shelf stability and intercontinental shipping feasibility, though smoked cod commands premium positioning in Mediterranean retail channels. Vacuum-sealed packaging is displacing ice-packed formats in direct-to-restaurant distribution as buyers prioritize yield retention and reduced cold-chain footprint.
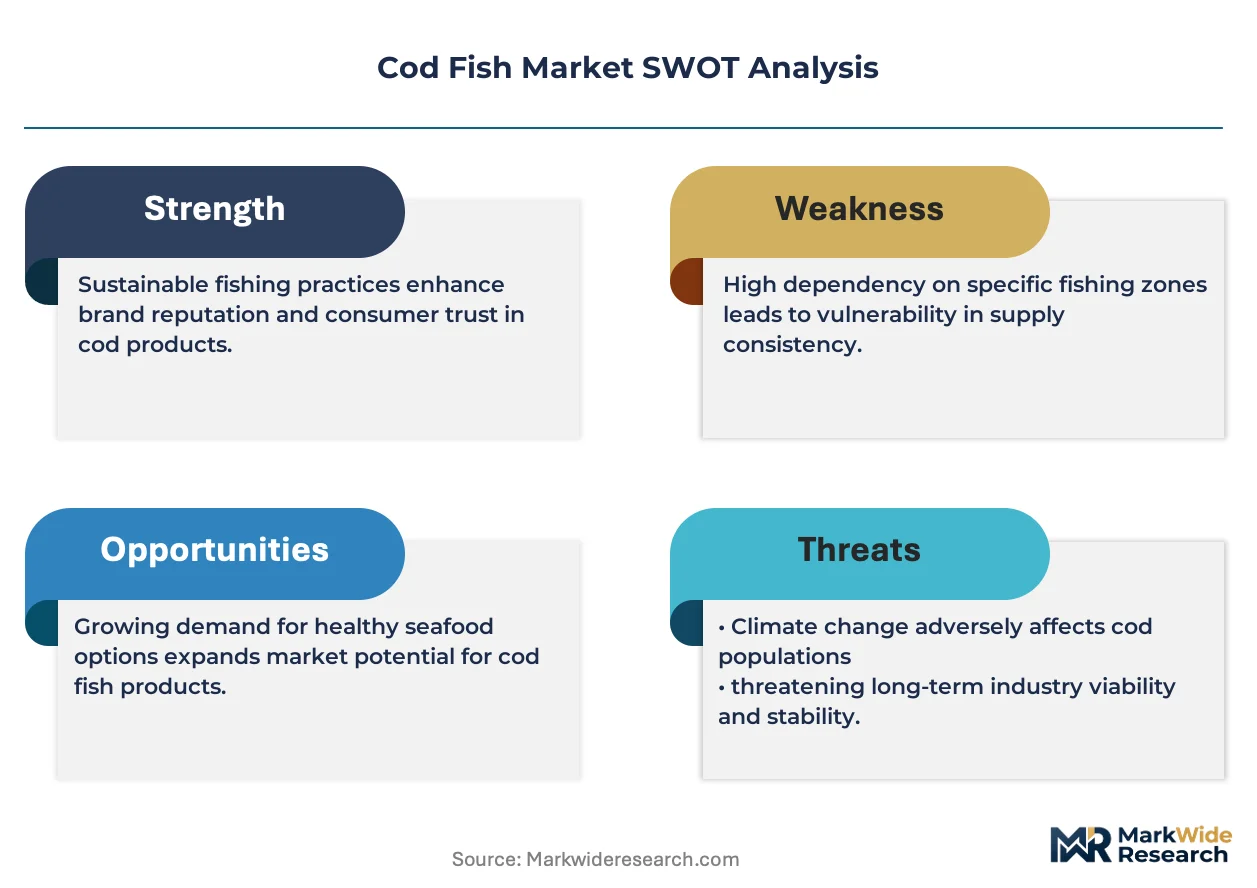
Norway's Directorate of Fisheries enforces individual transferable quota systems that constrain total allowable catch, while EU REACH and EFSA residue-monitoring protocols shape import-access conditions for non-European suppliers. The Norwegian Food Safety Authority audits chain-of-custody documentation, creating compliance barriers for unintegrated foreign entrants. Stakeholders must monitor quota-bargaining outcomes between coastal states and assess whether land-based recirculating aquaculture systems can supplement wild-catch supply without triggering new regulatory categories.
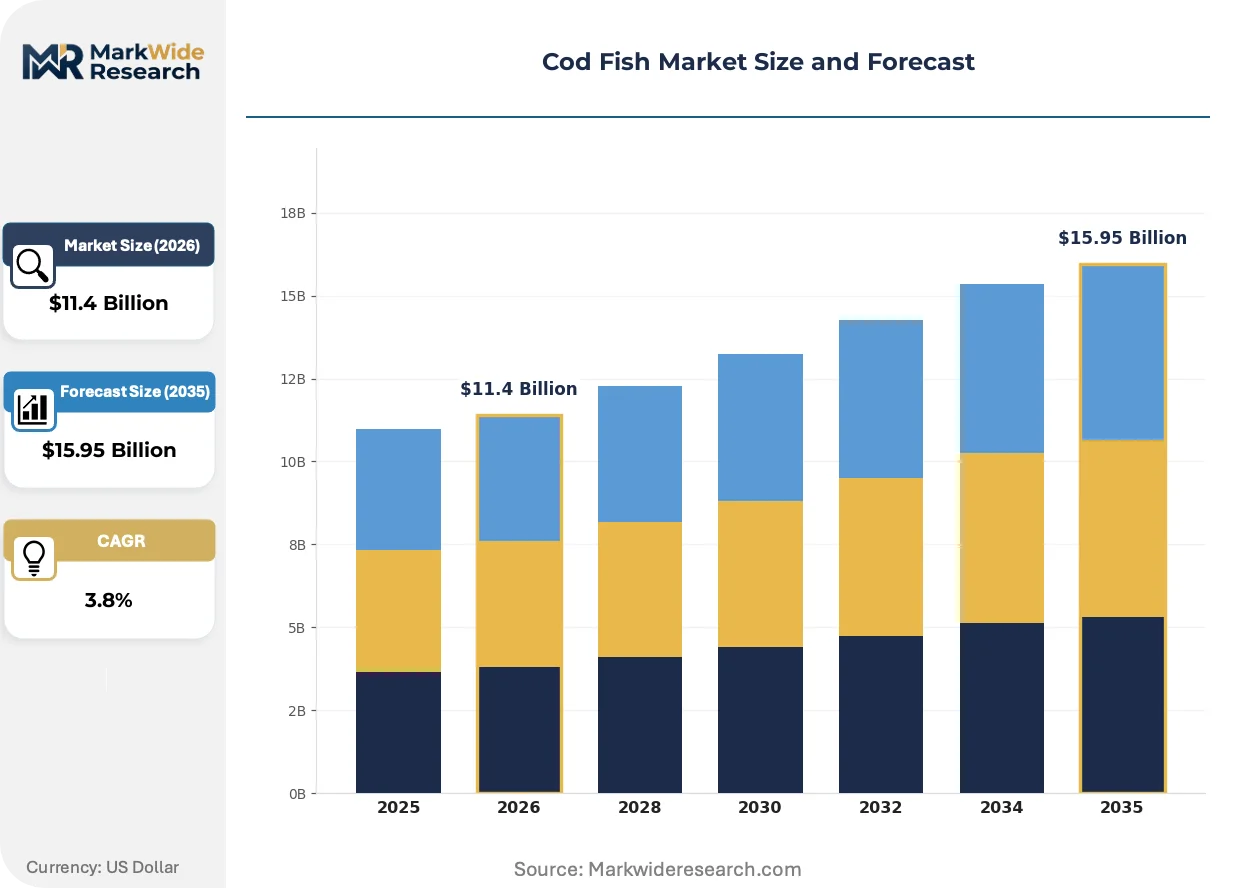
Market Dynamics
Individual transferable quota systems enforced by Norway's Directorate of Fisheries are constraining total allowable catch, forcing processors to compete for limited raw material through vertical integration and long-term supply contracts rather than spot-market purchasing.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Retail chains across Germany, France, and Spain now require Marine Stewardship Council certification for shelf placement, pulling certified cod volumes through dedicated procurement channels.
- Ready-meal processor demand:Northern European food manufacturers are expanding cod input for premium frozen fish portions and surimi-based products.
- Bergen-Ålesund infrastructure cluster:Concentrated aquaculture and wild-catch processing capacity in western Norway enables same-day fresh fillet distribution to continental European buyers.
Market Restraints
- Input cost volatility from fuel and labor:Bottom trawling operations face diesel price swings and crew shortages that compress vessel operating margins.
- Supply concentration in Barents Sea quotas:Norwegian and Russian coastal state agreements control access to the primary Atlantic cod biomass, creating bilateral negotiation risk.
- Regulatory friction from EU REACH residue protocols:Non-European suppliers face extended testing timelines and documentation burdens that delay market entry.
Strategic Opportunities
- Land-based recirculating aquaculture systems:Closed-containment facilities in Norway and Iceland could supplement wild-catch supply without triggering new quota categories.
- Direct-to-restaurant distribution channels:Vacuum-sealed packaging formats are displacing traditional ice-packed shipments, reducing cold-chain footprint and improving yield retention for Scandinavian restaurant networks.
- Mediterranean premium smoked cod positioning:Spanish and Italian retail channels command price premiums for traditional smoking-process products.
Industry Challenges
- Chain-of-custody documentation complexity:Norwegian Food Safety Authority audits require vessel-to-shelf traceability systems that smaller unintegrated foreign entrants struggle to implement.
- Quota bargaining outcome uncertainty:Coastal state negotiations between Norway, Russia, and Iceland create planning volatility for multi-year supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cod Fish Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $15.95 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Cod, Frozen Cod, Smoked Cod, Dried Cod End User: Retailers, Restaurants, Food Processors, Domestic Consumers Distribution Channel: Wholesale, Direct Sales, Online Marketplaces, Fishery Co-ops Packaging Type: Vacuum Sealed, Canned, Ice Packed, Bulk Packaging |
| Companies Covered | Ocean Quality, Norsk Fisk, Marine Harvest, Royal Greenland, Lerøy Seafood Group, Aker BioMarine, Bakkafrost, Ode, Gadus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cod Fish Market Emerging Trajectories
Digital catch documentation and automated processing systems are compressing supply chain timelines while regulatory traceability mandates reshape competitive requirements across the value chain.
Machine-vision grading systems installed at processing facilities are automating fillet quality assessment and weight sorting that previously required manual labor. Norwegian exporters deploying this technology report throughput increases and reduced giveaway in portion-cutting operations. The capital investment is automating margin recovery for mid-scale processors competing against integrated trawler-to-retail chains.
REACH and EFSA residue-monitoring protocols are tightening import-access conditions for non-European cod suppliers entering EU markets. Extended laboratory testing timelines and maximum residue limit documentation now precede first commercial shipments. Russian and Icelandic exporters are responding by pre-certifying catch batches through EU-recognized third-party laboratories before vessel departure.
Restaurant procurement patterns are consolidating toward fewer, larger fresh-fillet suppliers capable of daily delivery with full traceability documentation. Independent fishmongers and smaller wholesalers are losing share to specialized logistics operators offering integrated cold-chain and digital documentation services. This consolidation is most visible in Copenhagen, Stockholm, and Oslo where group purchasing organizations dominate hospitality sector sourcing.
Cod Fish Market Segmentation
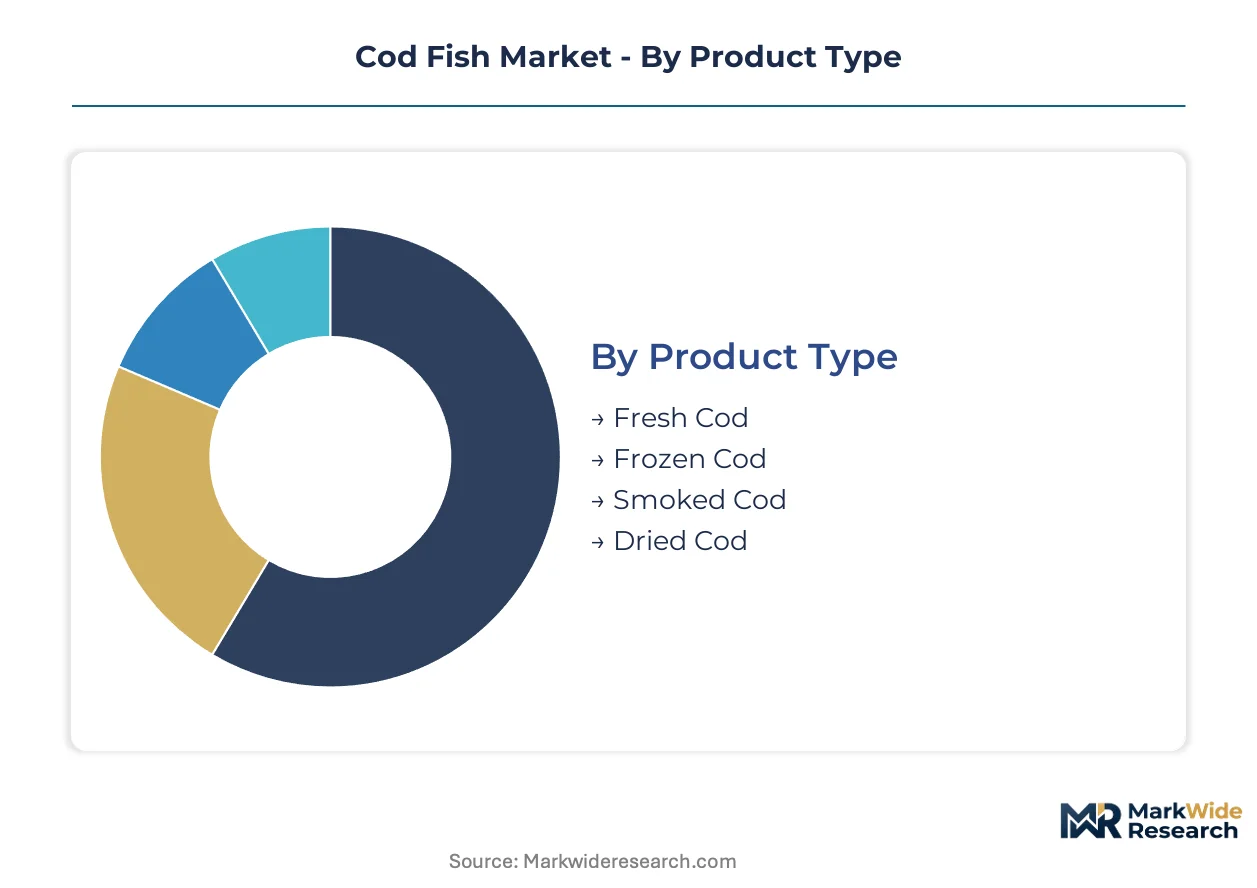
Cod product flows split sharply between commodity formats serving mass retail and specialized presentations commanding hospitality premiums. Processor investment patterns and cold-chain infrastructure quality determine which segments absorb capital and capture margin expansion.
Product Type:
Upgrade cycles in cod processing track shifting buyer tolerance for yield loss against shelf-life requirements, with format selection increasingly tied to distribution distance and end-use preparation method.
- Fresh Cod:Unfrozen fillets and loins deliver maximum texture retention for same-day or next-day preparation. Scandinavian restaurant networks in Copenhagen, Stockholm, and Oslo prioritize this format for premium menu positioning despite compressed delivery windows.
- Frozen Cod:Blast-frozen at sea or shore plants enables intercontinental shipment with 12-18 month stability. This format dominates volume flows to German, French, and Spanish retail chains where inventory flexibility outweighs freshness premiums.
- Smoked Cod:Traditional cold-smoking over hardwood generates distinctive flavor profiles for Mediterranean specialty retail. Spanish and Italian buyers accept significant price premiums for certified origin smoking processes.
- Dried Cod:Salt-cured and air-dried preservation creates shelf-stable protein for African and Caribbean re-export markets. Norwegian and Icelandic processors maintain dedicated drying facilities for this heritage format.
Frozen cod sits at the top of the volume ranking, with vacuum-sealed fresh fillets climbing the fastest as restaurant procurement consolidates around specialized logistics operators.
End User:
Cost tier stratification separates high-frequency, low-margin retail consumption from intermittent, high-margin hospitality purchasing that demands full traceability documentation.
- Retailers:Supermarket chains across Germany, France, and Spain require Marine Stewardship Council certification for shelf placement, pulling certified volumes through dedicated procurement channels with strict residue-testing protocols.
- Restaurants:Group purchasing organizations in Scandinavian capitals dominate hospitality sourcing, consolidating formerly fragmented independent fishmonger supply. Daily delivery requirements with digital catch documentation favor specialized fresh-fillet operators.
- Food Processors:Northern European manufacturers expand cod input for ready-meal portions and surimi-based products. Bergen and Ålesund infrastructure clusters enable same-day raw material access for these high-volume buyers.
- Domestic Consumers:Direct purchasing through fishery co-ops persists in coastal Norwegian communities where vessel-to-table relationships remain culturally embedded.
Retailers command the largest volume absorption, with restaurant networks expanding most quickly as procurement professionalization displaces traditional wholesaler relationships.
Distribution Channel:
Supply concentration in western Norway shapes channel viability, with proximity to processing infrastructure determining which intermediaries can meet documentation and timing requirements.
- Wholesale:Traditional aggregated distribution remains dominant for frozen cod moving to continental European retail, though margins compress as buyers consolidate toward fewer, larger suppliers.
- Direct Sales:Integrated trawler-to-retail chains bypass intermediaries for fresh fillet delivery to Scandinavian hospitality networks. Norsk Fisk and Lerøy Seafood Group leverage this channel for consistency premiums.
- Online Marketplaces:Digital platforms emerge for domestic consumer segments seeking traceable origin verification, particularly in Norwegian urban centers.
- Fishery Co-ops:Collective marketing organizations aggregate small-vessel catch for standardized quality presentation, preserving access for non-integrated coastal operators.
Wholesale retains volume leadership, with direct sales gaining share fastest as vertical integration rewards documentation compliance and cold-chain control.
Packaging Type:
Margin structure across packaging formats reflects material costs against yield retention performance, with regulatory pressure on plastic waste reshaping investment priorities.
- Vacuum Sealed:Modified atmosphere packaging extends fresh cod shelf life while reducing cold-chain footprint. Scandinavian restaurant networks prioritize this format for yield retention and reduced ice-melt waste.
- Canned:Thermal processing enables ambient distribution for value-added presentations, though cod's lean protein profile limits traditional canning economics compared to oilier species.
- Ice Packed:Traditional flake-ice preservation persists for same-day fresh distribution where packaging cost minimization outweighs logistics efficiency.
- Bulk Packaging:Frozen blocks and interleaved fillets serve food processor input requirements where downstream portion control occurs at manufacturing facilities.
Vacuum sealed holds the steepest expansion trajectory, with bulk packaging maintaining foundational volume for processor supply contracts.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping processing location decisions as EU REACH residue protocols and Norwegian traceability mandates create divergent compliance cost structures across the North Atlantic basin. Producers migrate toward jurisdictions where digital catch documentation and quota administration reduce operational friction.
Norway
Marine Stewardship Council certification requirements from German and French retail chains drive certified cod volumes through dedicated procurement channels. The Norwegian Food Safety Authority audits chain-of-custody documentation from vessel to shelf, creating compliance barriers for unintegrated foreign entrants. Bergen and Ålesund infrastructure clusters concentrate aquaculture and wild-catch processing capacity, enabling same-day fresh fillet distribution to continental European buyers.
Russia
Barents Sea quota allocations negotiated through coastal state agreements control access to primary Atlantic cod biomass, creating bilateral planning volatility for multi-year supply contracts. The Federal Agency for Fisheries administers catch documentation systems that must align with EU import-access conditions. Murmansk processing facilities serve as consolidation points for raw material destined for European markets.
Iceland
Land-based recirculating aquaculture systems in coastal zones supplement wild-catch supply without triggering new quota categories under current regulatory frameworks. The Icelandic Food and Veterinary Authority enforces residue-monitoring protocols that satisfy EFSA import requirements. Reykjanesbær and Akureyri host specialized fresh-fillet operations targeting Scandinavian restaurant networks.
United Kingdom
Post-Brexit customs documentation requirements extend testing timelines for cod imports from non-European suppliers, delaying market entry. The Food Standards Agency maintains residue-monitoring standards equivalent to EU REACH protocols. Grimsby and Peterhead retain historical processing infrastructure though volume flows shift toward direct Norwegian supply relationships.
Spain
Mediterranean retail channels command price premiums for traditional cold-smoking processes, anchoring demand for certified origin products. Spanish Agency for Food Safety and Nutrition enforces maximum residue limits that align with EFSA standards. Vigo and A Coruña processing facilities specialize in value-added presentations for domestic and Italian distribution.
Cod Fish Market Vendor Landscape
Norwegian producers anchor the integrated trawler-to-retail tier; Greenlandic and Icelandic specialists hold quota-dependent positions with limited downstream integration. Market structure concentrates around vertically integrated chains controlling vessel operations, shore processing, and distribution logistics. Three archetypes dominate: integrated trawler-to-retail operators, quota-holding specialist processors, and logistics-focused fresh-fillet distributors. Competitive moves center on backward integration into vessel fleets and long-term supply contract negotiations with retail chains.
Within the integrated tier, Norsk Fisk and Lerøy Seafood Group exemplify archetypes combining vessel ownership with retail distribution capabilities. Royal Greenland occupies a distinct position anchored to inshore Greenlandic quota allocations. These three entities represent the competitive spectrum from full vertical control through captive supply to quota-constrained specialization.
| Leading Market Players |
|---|
| Ocean Quality |
| Norsk Fisk |
| Marine Harvest |
| Royal Greenland |
| Lerøy Seafood Group |
| Aker BioMarine |
| Bakkafrost |
| Ode |
| Gadus Group |
| Others |
Supply Flow & Price Mechanics
Integrated trawler-to-retail chains anchor supply positioning and pricing power through captive vessel fleets and direct distribution control. Norsk Fisk and Lerøy Seafood Group leverage this structure to bypass wholesale margin layers and command consistency premiums from Scandinavian hospitality networks.
Pricing Analysis
Retailer markup layers dominate final price formation, with Marine Stewardship Council certification tiers separating premium fillet positioning from commodity frozen blocks. Three-tier pricing structure across certified premium, standard grade, and unbranded economy levels reflects quality grade and volume scale differentiation. Pricing pressure stems from diesel cost volatility compressing trawler operating margins. Food processors exhibit highest price sensitivity due to thin ready-meal manufacturing margins, while Mediterranean smoked cod buyers accept significant premiums.
Supply Chain Analysis
Norwegian domestic-content mandates through the Directorate of Fisheries' individual transferable quota system reshape sourcing toward vessel-flagged domestic operators. Raw material flows concentrate in Norway, Russia, and Iceland around Barents Sea biomass access. Processing depends on fuel inputs, labor crews, and ice-class logistics capacity. Single-source vulnerability runs through coastal state quota negotiations between Norway and Russia. Distribution runs through Bergen-Ålesund infrastructure clusters for fresh fillet output and Murmansk consolidation points for frozen commodity flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier fresh fillet positioning and automation-driven yield recovery, with machine-vision grading systems compressing processing giveaway.
For Market Incumbents: Lock in long-term supply contracts with retail chains before coastal state quota renegotiations create planning volatility. Deepen backward integration into specialized logistics operators serving Copenhagen, Stockholm, and Oslo hospitality networks to defend against procurement consolidation. Invest in digital catch documentation systems ahead of Norwegian Food Safety Authority audit expansions. For New Entrants and Emerging Players: Begin with land-based recirculating aquaculture systems in Iceland or coastal Norway to bypass quota constraints and establish regulatory-compliant supply. Target Mediterranean smoked cod channels where traditional process certification commands price premiums unavailable in commodity frozen segments. Pursue direct-to-restaurant distribution partnerships with group purchasing organizations seeking traceable origin verification. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fresh-fillet processors because restaurant procurement consolidation favors specialized logistics operators with daily delivery capability and full documentation compliance. Five-to-ten year viability hinges on quota bargaining stability between coastal states and land-based aquaculture regulatory categorization outcomes. Monitor Norwegian-Russian bilateral negotiation signals as the primary inflection indicator for supply contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vessel Fleets | Captive supply secures raw material access against quota-constrained spot market volatility. |
| Machine-Vision Grading Installation | Automated quality assessment reduces labor dependency and portion-cutting giveaway. |
| Marine Stewardship Council Certification | EU Green Deal mandates pull certified volumes through dedicated German and French retail channels. |
| Land-Based Recirculating Aquaculture Buildout | Closed-containment facilities supplement wild-catch without triggering new quota categories. |
| Direct-to-Restaurant Distribution Expansion | Vacuum-sealed formats displace ice-packed shipments for Scandinavian hospitality networks. |
Methodological Framework
Bottom-up food processor and restaurant procurement modeling reconciled against top-down vessel catch and quota tracking forms the analytical core. Primary interviews with trawler fleet operators, shore plant managers, retail category buyers, and hospitality procurement directors combined with secondary validation from Norwegian Directorate of Fisheries catch statistics, EU EFSA residue-monitoring protocols, and customs trade documentation. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map raw material flows from Barents Sea catch areas through processing formats to end-use segments across the analysis window. Segmentation dimensions include product type, end user archetype, distribution channel, and packaging format. CAGRs derive from quota trajectory modeling, aquaculture capacity buildout assumptions, and retail certification penetration curves. Forecast inputs incorporate diesel price sensitivity for trawler operations and EU REACH testing timeline impacts on non-European supplier access.
Several conditions sit outside the modeled scope, including abrupt coastal state quota reallocation, land-based aquaculture regulatory reclassification, and trade policy shifts affecting Russian market access. Forecasts reflect documented assumptions regarding bilateral negotiation stability and certification adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Nutrition Market
Seafood
Middle East Seafood Market
Seafood
Smoked Salmon Market
Seafood
Saudi Arabia Seafood Market
Seafood
Crayfish Market
Seafood
Mussel Oil Market
Seafood
Edible Seaweed Market
Seafood
Latin America Salmon Market
Seafood
Organic Salmon Market
Seafood
Asian Sea Bass Market
Seafood
Food Clamshells Market
Seafood
Fish Powder Market
Seafood
Molluscs Market
Seafood
Salmon Fish Market
Seafood
Toothfish Market
Seafood
Fish Protein Hydrolysate Market