
 Global Ferrous Sulfate Market | 2026-2036
Global Ferrous Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ferrous Sulfate Market Foresight
Capital-intensity divergence between integrated titanium dioxide producers and standalone chemical processors is bifurcating competitive dynamics across the value chain. Rech Chemicals leverages captive sulfuric acid networks to sustain cost-advantaged heptahydrate output for agricultural distributors. KRONOS Worldwide anchors its ferrous sulfate position through TiO2 pigment co-product streams, competing on volume scale rather than formulation specialization. Kemira differentiates via controlled-release granulation technology for municipal water treatment contracts in Northern Europe.
Ferrous sulfate denotes an iron(II) salt compound, typically crystallizing as FeSO₄·7H₂O with 20% elemental iron content, manufactured through steel pickling liquor neutralization or direct reaction of iron with sulfuric acid; its primary commercial purpose centers on coagulation, nutrient supplementation, and oxidation-reduction catalysis across industrial processes. Heptahydrate formulations dominate agricultural applications where solubility governs bioavailability, while monohydrate grades command premium positioning in cement additive specifications requiring controlled moisture release. Water treatment applications represent the fastest-expanding demand pool as phosphorus precipitation mandates tighten across OECD jurisdictions, with granular product forms capturing margin concentration through reduced handling costs and dust mitigation.
EPA effluent limitation guidelines and REACH substance registration requirements shape product purity thresholds and market access conditions for ferrous sulfate suppliers serving regulated industries. China's MEE discharge standards and India's Central Pollution Control Board directives are extending compliance burdens to emerging-market producers, compressing informal supply channels. Stakeholders must monitor evolving heavy-metal contaminant limits and circular-economy certification schemes to anticipate which production routes and geographic sourcing positions will sustain competitive viability.
Market Dynamics
Steel pickling byproduct recovery networks are consolidating feedstock access for ferrous sulfate manufacturers, concentrating supply leverage among integrated titanium dioxide producers who control sulfuric acid logistics and neutralization capacity.
Growth Catalysts
- Phosphorus precipitation mandates:EPA effluent limitation guidelines compel municipal water utilities to upgrade chemical dosing infrastructure, expanding ferrous sulfate procurement for nutrient removal.
- China's circular-economy enforcement:MEE discharge standards accelerate steel mill byproduct valorization, channeling spent pickling liquor into agricultural-grade heptahydrate production.
- REACH substance registration:ECHA compliance requirements in European water treatment sectors favor registered suppliers with documented contaminant thresholds, advantaging formal producers over informal channels.
Market Restraints
- Sulfuric acid price volatility:Input cost swings from sulfur combustion and smelter off-gas recovery compress margins for standalone chemical processors lacking captive acid supply.
- Hebei and Shandong supply concentration:Over half of agricultural-grade ferrous sulfate originates from these Chinese provinces, exposing buyers to logistics disruptions and regional environmental enforcement variability.
- Ferric chloride substitution:Alternative coagulants capture share in high-rate clarification systems where rapid floc formation outweighs ferrous sulfate's cost advantage.
Strategic Opportunities
- Brazilian agricultural expansion:Soybean and sugarcane growers in Mato Grosso and São Paulo states present untapped demand for iron micronutrient supplementation in acidic soils.
- Controlled-release granulation:Kemira's polymer-coated formulations for Northern European municipal contracts demonstrate premium positioning through reduced dust exposure and automated dosing compatibility.
- EU Green Deal circular-economy certification:Steel mill byproduct recovery routes qualify for carbon intensity reductions, creating procurement preference among sustainability-mandated water utilities.
Industry Challenges
- Heavy-metal analytical capability gaps:Municipal procurement departments lack in-house ICP-MS testing capacity to verify arsenic and lead thresholds, delaying supplier qualification timelines.
- Legacy dosing system incompatibility:Existing ferric-based infrastructure at water treatment plants requires retrofitting for ferrous sulfate's lower pH and oxygen sensitivity, extending pilot-to-contract cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ferrous Sulfate Market |
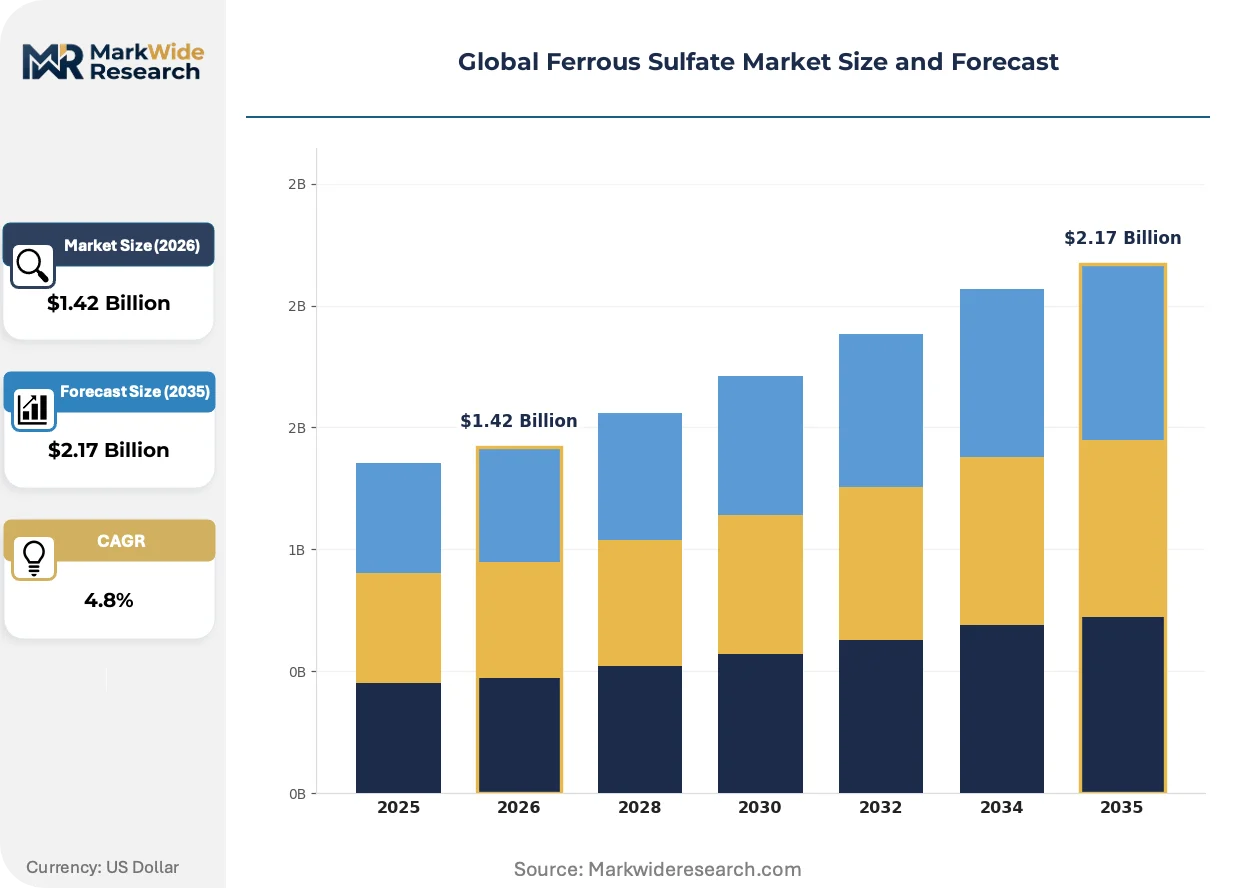
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Heptahydrate, Anhydrous, Granular, Powder Application: Water Treatment, Animal Feed, Cement Additive, Soil Amendment, Textile Processing End User Industry: Waste Management, Agriculture, Construction, Livestock Farming, Manufacturing Packaging Type: Bag, Drum, Jumbo Bag, Bulk, Box |
| Companies Covered | Rech Chemicals, KRONOS Worldwide, Venator Materials, Lomon Billions Group, Coogee, Crown Technology, Kemira, Pencco, Chemland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ferrous Sulfate Market Shifts & Advancements
Product form innovation and regulatory chemistry are reshaping how ferrous sulfate moves through industrial procurement channels, with granularity and contaminant documentation becoming primary differentiation vectors.
Encapsulated granule technology is miniaturizing particle size distribution while maintaining flowability, enabling pneumatic conveying systems at automated municipal water plants. German and Dutch utilities are adopting these formulations to reduce manual handling and respiratory exposure compliance costs. The technology is compressing price premiums for standard heptahydrate crystals in contract bidding.
REACH Annex XVII restrictions on heavy-metal content in fertilizer-grade materials are tightening analytical documentation requirements for EU-bound shipments. ECHA enforcement has disqualified several Turkish and Indian exporters from agricultural tenders due to inconsistent certificate of analysis standards. Northern European distributors now require third-party accredited testing as a condition of supply agreements.
Consolidated procurement by multinational water treatment service providers is displacing fragmented municipal tendering, concentrating volume commitments with tier-one chemical distributors. Veolia and Suez have implemented pan-European framework contracts for phosphorus removal chemicals, bypassing regional brokers. This pattern is most visible in France and the United Kingdom where asset ownership has shifted to private operators under concession arrangements.
Global Ferrous Sulfate Market Segmentation
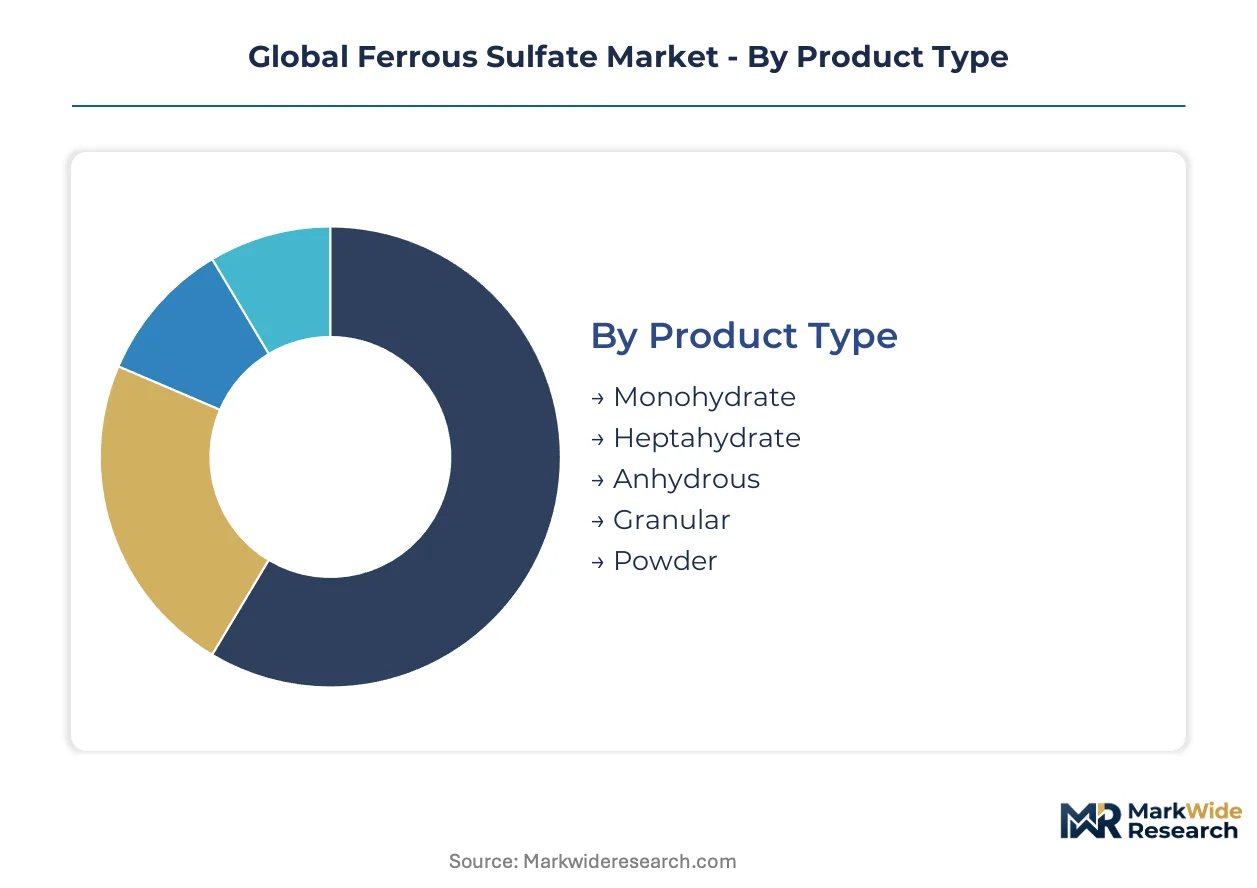
Product form and purity specifications dictate margin capture in ferrous sulfate markets, with water treatment utilities paying premiums for contaminant documentation while agricultural buyers prioritize solubility economics. Application-driven segmentation reveals divergent procurement patterns across municipal infrastructure and farming inputs.
Product Type:
Premium margin pools concentrate in controlled-release granules and low-moisture monohydrate grades serving automated dosing systems and cement specifications.
- Monohydrate:Crystalline FeSO₄·H₂O with 30% elemental iron content commands specification-grade positioning in cement additive formulations where moisture control prevents premature hydration. Construction material producers in Germany and Japan specify monohydrate for sulfate-resistant concrete applications, with procurement tied to EN 197-1 cement standard compliance.
- Heptahydrate:The standard FeSO₄·7H₂O crystalline form with 20% iron dominates agricultural distribution due to rapid dissolution in acidic soils. Brazilian soybean growers in Mato Grosso and São Paulo states drive volume procurement for iron chlorosis correction, with seasonal demand peaking during pre-planting nutrient application windows.
- Anhydrous:Dehydrated salt with maximum iron density serves specialized chemical synthesis and battery precursor manufacturing where water content interferes with reaction stoichiometry.
- Granular:Agglomerated particles with polymer coating options reduce dust exposure and enable pneumatic conveying at automated municipal water plants.
- Powder:Fine-ground material offers cost-minimized entry for textile processing and legacy agricultural blending equipment lacking granule-handling capability.
The dominant share belongs to Heptahydrate, while Granular is closing the gap fastest.
Application:
Water treatment contracts concentrate procurement volume and documentation requirements, while soil amendment applications spread demand across fragmented agricultural distribution networks.
- Water Treatment:Phosphorus precipitation in municipal effluent systems consumes high-purity grades with certified arsenic and lead thresholds below EPA Method 200.8 limits. Utilities in the United Kingdom and Netherlands specify granular forms for automated ferric/ferrous switching stations, with REACH registration documentation mandatory for framework contract eligibility.
- Animal Feed:Iron fortification in poultry and swine rations requires feed-grade certification under EU 1831/2003 additive regulations, with bioavailability testing distinguishing sulfate from oxide and chelate alternatives.
- Cement Additive:Sulfate source for ettringite formation in expansive cements and chromium(VI) reduction in finished cement, with monohydrate preferred for moisture-sensitive grinding aids.
- Soil Amendment:Corrective application for calcareous and alkaline soils where iron availability limits crop productivity, particularly in Mediterranean olive groves and Californian vineyard regions.
- Textile Processing:Mordant and reducing agent in dye fixation and indigo vat reduction, with powder forms dominating South Asian garment manufacturing clusters.
Water Treatment commands the largest procurement volumes, though Soil Amendment is expanding most quickly in Brazilian and Australian agricultural markets.
End User Industry:
Waste management utilities consolidate purchasing power through multinational service contracts, while livestock farming remains fragmented across regional feed compounders.
- Waste Management:Municipal and industrial effluent treatment operators specify ferrous sulfate for odor control and heavy metals precipitation, with Veolia and Suez implementing pan-European chemical framework agreements that bypass regional brokers.
- Agriculture:Row-crop producers and specialty growers procure through cooperative distributors, with Brazilian and Chinese markets representing concentrated demand pools for heptahydrate bulk shipments.
- Construction:Cement manufacturers integrate ferrous sulfate into grinding aid formulations and chromium reduction protocols, with specification adherence to national cement standards determining supplier qualification.
- Livestock Farming:Integrated poultry and swine operations specify feed-grade material through vertical supply arrangements with premix manufacturers, with EU 1831/2003 compliance mandatory for European market access.
- Manufacturing:Textile dyehouses, ink producers, and chemical synthesis operations consume technical-grade material with variable purity tolerances depending on downstream process sensitivity.
Agriculture retains the dominant consumption position, while Waste Management is gaining share fastest through phosphorus removal mandate expansion.
Packaging Type:
Handling automation and logistics economics drive packaging selection, with bulk and jumbo formats capturing margin in high-volume contracts and small-unit packaging preserving access to fragmented agricultural endpoints.
- Bag:Standard 25-50 kg woven polypropylene units dominate agricultural distribution through farm supply retailers, with moisture-resistant liners critical for heptahydrate stability in humid climates.
- Drum:Steel and fiber containers serve laboratory, pharmaceutical, and specialty chemical applications requiring sealed storage and precise dosing control.
- Jumbo Bag:One-tonne flexible intermediate bulk containers enable pneumatic discharge at automated water treatment plants and large-scale feed mills, reducing manual handling labor and spillage losses.
- Bulk:Tanker and hopper truck delivery minimizes unit packaging costs for integrated cement plants and municipal chemical storage facilities with dedicated unloading infrastructure.
- Box:Corrugated containers with inner liners serve retail agricultural channels and small-scale textile processors requiring palletized storage and fork-lift mobility.
Bag packaging holds the largest volume share, though Jumbo Bag is climbing the fastest as water treatment automation spreads across OECD utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ferrous sulfate primarily as a steel-pickling byproduct for agricultural and water treatment applications, while Germany and the United States prioritize high-purity grades for municipal phosphorus removal with stringent contaminant documentation.
China
Hebei and Shandong provinces generate over half of global agricultural-grade heptahydrate output from integrated steel mill operations. MEE discharge standards enforce spent pickling liquor neutralization, channeling byproduct streams into fertilizer-grade production. The Yangtze River Delta water utilities are upgrading chemical dosing infrastructure to meet tightening phosphorus limits.
Germany
Cement manufacturers in North Rhine-Westphalia specify monohydrate grades for sulfate-resistant concrete under EN 197-1 standards. ECHA REACH registration requirements disqualify non-compliant suppliers from municipal water treatment tenders. The Ruhr industrial corridor hosts advanced granulation facilities serving Dutch and Belgian export markets.
United States
EPA effluent limitation guidelines drive phosphorus precipitation upgrades across Great Lakes municipal utilities. Midwestern water treatment operators specify granular forms for automated ferric-ferrous switching stations. The Ohio River Valley steel industry supplies byproduct feedstock to regional chemical processors.
Brazil
Soybean growers in Mato Grosso and São Paulo states drive seasonal demand for iron chlorosis correction in acidic soils. ANVISA feed-grade certification opens poultry and swine fortification markets for imported heptahydrate. The Santos port complex handles bulk agricultural shipments during pre-planting application windows.
Netherlands
Randstad water utilities specify polymer-coated granules for pneumatic conveying systems at automated treatment plants. EU Green Deal circular-economy procurement preferences favor steel byproduct recovery routes with documented carbon intensity reductions. Rotterdam chemical distributors consolidate pan-European framework contracts for phosphorus removal chemicals.
Global Ferrous Sulfate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with titanium dioxide producers leveraging captive sulfuric acid networks against standalone chemical processors dependent on merchant acid supply. The market structure bifurcates between volume-scale co-product operators and formulation-focused technology licensors. Three archetypes dominate: integrated pigment producers with pickling liquor access, regional agricultural chemical distributors with blending capabilities, and controlled-release technology specialists serving automated municipal systems. Capacity expansion and granulation technology licensing represent the primary competitive moves, with sustainability certification emerging as a procurement differentiator in European water treatment markets.
Within the integrated producer tier, KRONOS Worldwide and Venator Materials exemplify pigment-co-product positioning, while Kemira occupies the technology-specialist vector with polymer-coated formulations. Rech Chemicals represents the regional distributor archetype with sulfuric acid logistics integration. These three anchors illustrate how competitive positioning stratifies across feedstock access, formulation specialization, and geographic market focus.
| Leading Market Players |
|---|
| Rech Chemicals |
| KRONOS Worldwide |
| Venator Materials |
| Lomon Billions Group |
| Coogee |
| Crown Technology |
| Kemira |
| Pencco |
| Chemland Group |
| Others |
Supply & Pricing Matrix
Captive sulfuric acid networks at integrated titanium dioxide plants compress unit economics for ferrous sulfate producers, concentrating margin advantage among pigment-co-product operators while standalone processors face persistent feedstock cost volatility. This scale asymmetry stratifies pricing power across the value chain, with volume-scale incumbents dictating floor prices in agricultural heptahydrate tenders while specialty granulation commands premiums in municipal automation contracts.
Pricing Analysis
After-sales service bundling around automated dosing system maintenance and certificate-of-analysis documentation drives lifetime value capture in municipal water treatment contracts. Three-tier pricing structure across premium granules, standard heptahydrate crystals, and economy-grade powder separates contamination-certified utilities from cost-sensitive agricultural blenders. Pricing pressure stems from ferric chloride substitution in high-rate clarification systems where rapid floc formation outweighs ferrous sulfate's cost position. Agricultural distributors in Brazil and China exhibit highest price sensitivity, while Northern European utilities prioritize documented purity over unit cost.
Supply Chain Analysis
China and India anchor global ferrous sulfate supply through steel pickling byproduct recovery and direct acid neutralization routes, with Hebei and Shandong provinces generating dominant agricultural-grade volumes. Merchant sulfuric acid from smelter off-gas and sulfur combustion feeds standalone chemical processors, creating input cost exposure absent at integrated pigment producers. Single-source vulnerability concentrates in Chinese provincial supply clusters where regional environmental enforcement variability disrupts logistics. Distribution runs through multinational water treatment service providers consolidating pan-European framework contracts alongside fragmented agricultural cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrous sulfate incumbents face substitution defense imperatives as ferric chloride and aluminum-based coagulants capture share in automated clarification systems, requiring strategic repositioning around phosphorus removal efficacy and circular-economy certification.
For Market Incumbents: Shield agricultural-grade market share by deepening backward integration into steel mill byproduct offtake agreements in Hebei and Shandong, while accelerating REACH-registered granulation capacity for Northern European municipal automation tenders. Certification investment in EU Green Deal circular-economy documentation creates procurement preference against informal supply channels.
For New Entrants and Emerging Players: Automated dosing system compatibility gaps in legacy ferric-based water treatment infrastructure present white-space entry points, particularly for polymer-coated granule formulations reducing retrofit complexity. Brazilian soybean and sugarcane regions offer penetrable agricultural demand for iron chlorosis correction, with ANVISA feed-grade certification unlocking poultry and swine fortification channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controlled-release technology specialists serving automated municipal systems with multi-year framework contracts. Long-term viability favors acquisition targets with documented steel byproduct recovery routes and ECHA-registered contaminant thresholds. Monitor EPA effluent guideline enforcement intensity as inflection indicator for phosphorus removal chemical procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Pickling Byproduct Recovery | Captive feedstock access neutralizes sulfuric acid price volatility for Hebei and Shandong producers. |
| Controlled-Release Granulation Technology Licensing | Kemira's polymer-coated formulations demonstrate premium positioning in Dutch and German municipal automation contracts. |
| REACH Registration and ECHA Compliance Investment | Documented contaminant thresholds under EU 1831/2003 and water treatment frameworks disqualify informal competitors. |
| Long-term Supply Agreement with Multinational Water Utilities | Veolia and Suez pan-European framework contracts bypass regional brokers and concentrate volume commitments. |
| EU Green Deal Circular-Economy Certification Program | Carbon intensity reduction documentation creates procurement preference among sustainability-mandated Northern European utilities. |
Research Methodology
Initial hypotheses were tested against primary input from water treatment plant engineers, municipal procurement officers, agricultural cooperative distributors, and titanium dioxide plant managers, and refined through secondary validation against customs trade data, SEC 10-K filings from pigment producers, ECHA registration databases, and MEE discharge standard enforcement records. Bottom-up volume estimates from grade-specific consumption patterns were triangulated with top-down value projections across product form and application segments.
Variance decomposition across the projection horizon isolates drivers including phosphorus mandate enforcement intensity, steel production cycles affecting byproduct availability, and sulfuric acid input cost trajectories. Segmentation dimensions modeled encompass crystalline form tier, end-use industry, packaging automation level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution dynamics between ferrous and ferric coagulants.
Forecasts assume regulatory continuity in EPA effluent guidelines, REACH Annex XVII restrictions, and China's MEE discharge standards; material policy shifts would require re-modeling. Supply concentration risk in Hebei and Shandong provinces, ferric chloride substitution acceleration, and heavy-metal analytical capability gaps at municipal procurement departments constitute specific revision triggers. Recalibration cycles align with material shifts in phosphorus removal mandate enforcement and circular-economy procurement preference adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Magnesium Chloride Market