
 Granular Urea Market | 2026-2036
Granular Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Granular Urea Market Outlook
Direct sales to large-scale agricultural cooperatives is rewriting procurement patterns across the granular urea value chain. CF Industries Holdings, Inc. leverages its Gulf Coast ammonia integration to dominate North American supply corridors. Yara International ASA anchors European demand through controlled-release formulations and carbon footprint tracking. Nutrien Ltd. extends its retail network density to control last-mile distribution in the North American prairie provinces.
Granular urea consists of solid nitrogen fertilizer prills or granules typically containing 46% nitrogen by weight, produced via the Bosch-Haber synthesis of ammonia with carbon dioxide followed by granulation or prilling. Standard granular formulations command the largest volume share across emerging markets where price sensitivity governs procurement, while coated granular and controlled-release variants capture premium margin pools in specialty crop segments where application efficiency and environmental compliance carry tangible economic value. Agricultural cooperatives remain the dominant distribution channel for bulk volumes, though online retail platforms are gaining traction among smaller horticulture operators seeking transparent pricing and flexible lot sizes.
The EPA regulates ammonia and nitrous oxide emissions from US urea production facilities under the Clean Air Act, while the EU Green Deal's Farm to Fork strategy pressures nitrogen input intensity across member states. India's Fertilizer Ministry administers the urea subsidy regime through the Department of Fertilizers, directly shaping farmer affordability and import parity calculations. Stakeholders must monitor how carbon border adjustment mechanisms and evolving farm subsidy structures in major consuming nations reshape competitive cost positions between domestic production and seaborne imports.
Market Dynamics
Carbon border adjustment mechanisms and farm subsidy recalibration in major consuming nations are redrawing the cost competitiveness map between domestic production and seaborne imports. Producers now face dual pressure: decarbonizing ammonia synthesis while defending price positions against subsidized imports from regions with weaker environmental enforcement.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates demand for nitrogen-based alternatives in precision cooling applications, indirectly boosting technical-grade urea consumption for industrial processes.
- Indo-Gangetic Plain intensity:Rice-wheat double-cropping systems sustain bulk offtake volumes where subsidized pricing locks in farmer affordability regardless of international price spikes.
- Controlled-release coating technology:Polymer and sulfur-coated variants capture premium margins in specialty horticulture segments where application efficiency and runoff compliance carry measurable economic value.
Market Restraints
- Natural gas cost volatility:Ammonia synthesis consumes 70-80% of production costs, exposing margins to Henry Hub and TTF price swings that compress returns during energy spikes.
- Supply concentration in Gulf producers:Qatar, Saudi Arabia, and the UAE control disproportionate export capacity, creating single-source vulnerability for Atlantic Basin buyers during geopolitical disruptions.
- EU carbon border adjustment mechanism:Impending CBAM charges on embedded emissions threaten to erode cost advantages of non-EU producers supplying European agricultural markets.
Strategic Opportunities
- Brazilian Cerrado expansion:Soybean frontier cultivation creates underpenetrated demand for bulk urea applications where logistics infrastructure gaps currently limit supplier access.
- Online retail platforms:Direct-to-farmer channels bypass cooperative intermediaries for smaller horticulture operators seeking transparent spot pricing and sub-ton lot flexibility.
- EU Green Deal Farm to Fork:Nitrogen input reduction targets incentivize controlled-release formulations that align environmental compliance with yield optimization.
Industry Challenges
- Process engineer scarcity:Ammonia plant optimization and carbon capture retrofitting require specialized talent pools that regional labor markets fail to replenish at replacement rates.
- Legacy distribution integration:Cooperative procurement systems resist platform-based disintermediation, forcing digital entrants to absorb customer acquisition costs without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granular Urea Market |
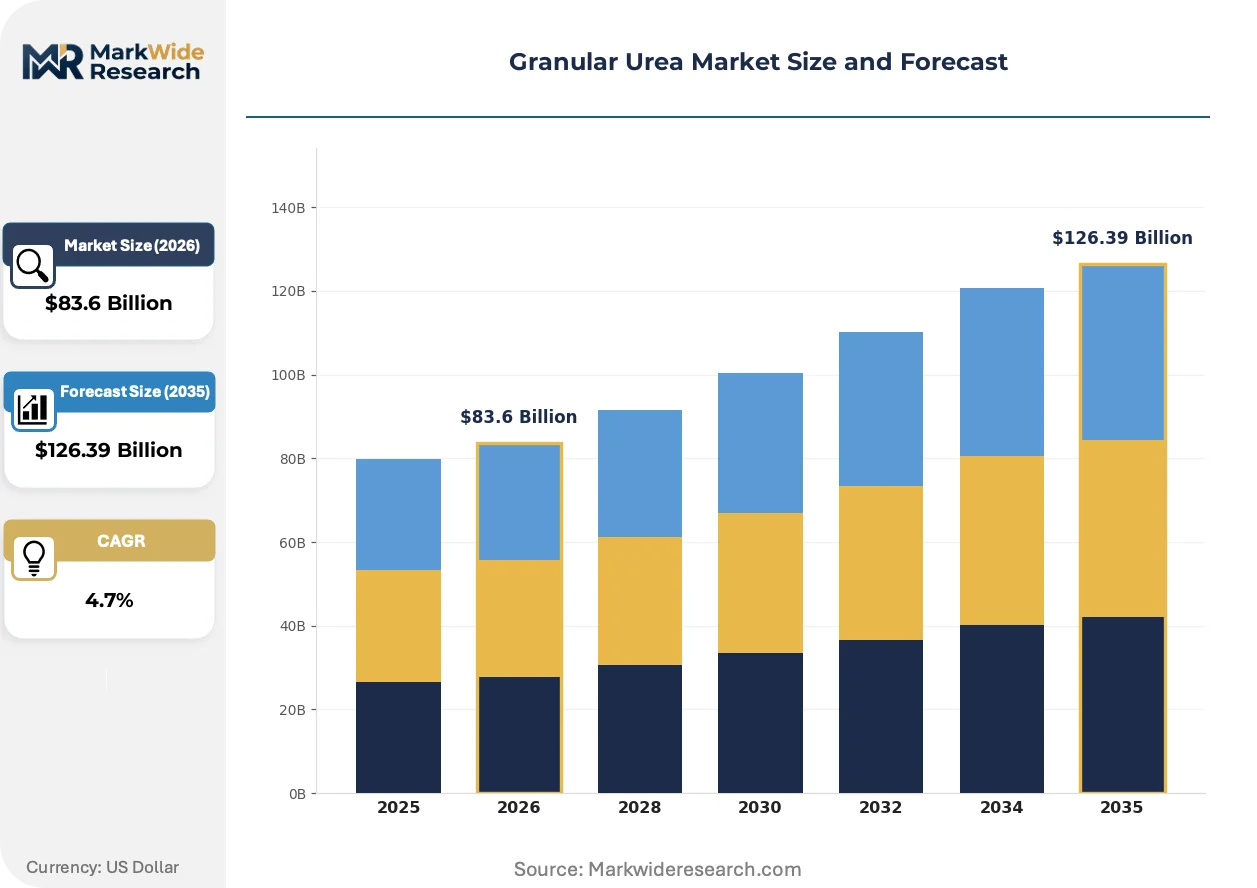
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $126.39 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Granular, Coated Granular, Controlled-Release, Stabilized Urea Application: Agriculture, Horticulture, Forestry, Turf Management Distribution Channel: Online Retail, Agricultural Cooperatives, Specialty Stores, Direct Sales Market Player Type: Fertilizer Manufacturers, Wholesalers, Distributors, Regional Suppliers |
| Companies Covered | CF Industries Holdings, Inc., Yara International ASA, Nutrien Ltd., SABIC, OCI N.V., EuroChem Group, Koch Fertilizer LLC, PT Pupuk Indonesia, Qatar Fertiliser Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granular Urea Market Strategic Shifts
Production technology and regulatory compliance frameworks are converging to redefine product differentiation beyond commodity nitrogen content. Stakeholders now compete on carbon intensity metrics, application precision, and supply chain traceability rather than price alone.
Controlled-release coating technology is hybridizing conventional prill formulations with polymer barriers and sulfur matrices that meter nitrogen availability across crop growth cycles. Specialty vegetable and fruit producers in California's Central Valley adopt these variants at accelerating rates despite 40-60% price premiums. The technology is hybridizing procurement criteria, forcing commodity suppliers to document environmental performance alongside traditional assay specifications.
The EU F-Gas Regulation and impending carbon border adjustment mechanisms are tightening emission accounting requirements for imported fertilizers. Producers must now certify ammonia synthesis carbon intensity to maintain European market access, favoring facilities with carbon capture retrofits or renewable hydrogen feedstock pilots. Atlantic Basin suppliers with Gulf Coast gas integration face particular exposure as CBAM phase-in approaches.
Direct platform procurement is displacing cooperative intermediaries among smaller-scale horticulture operators seeking price transparency and flexible lot sizes. Specialty crop growers in Florida and the Pacific Northwest bypass traditional distribution channels through agricultural e-commerce portals that aggregate demand for containerized shipments. This behavioral shift concentrates in regions where cooperative density remains thin and logistics costs favor direct import arrangements over domestic supply chains.
Granular Urea Market Segmentation
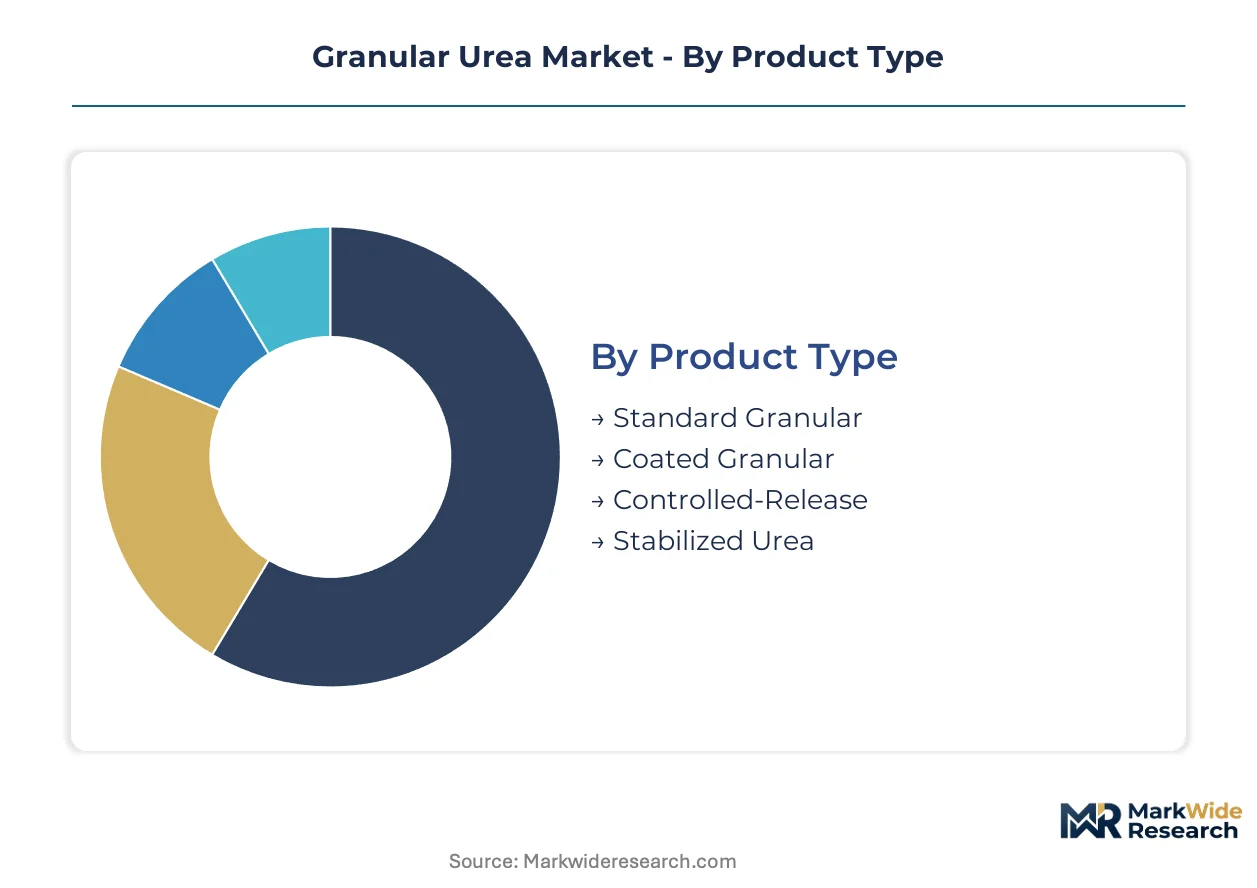
Granular urea segmentation reflects divergent paths between commodity nitrogen bulk and precision agriculture premiumization. Product formulation, application specificity, and channel configuration each reshape margin architecture across the value chain.
Product Type:
Mature commodity formats anchor volume economics while emerging coating technologies capture environmental compliance premiums.
- Standard Granular:Conventional prilled formulations containing 46% nitrogen by weight dominate procurement across price-sensitive grain belts. Demand concentrates in the Indo-Gangetic Plain where India's Department of Fertilizers subsidy regime locks in farmer affordability regardless of international price volatility.
- Controlled-Release:Polymer-coated variants meter nitrogen availability across crop growth cycles, reducing leaching and volatilization losses. Specialty vegetable producers in California's Central Valley adopt these formulations at accelerating rates where runoff compliance carries measurable regulatory and insurance cost consequences.
- Coated Granular:Sulfur-based coatings offer intermediate release characteristics between commodity prills and precision polymers. Brazilian soybean operators in the Cerrado frontier increasingly specify these grades where logistics infrastructure gaps limit frequent application access.
- Stabilized Urea:Urease and nitrification inhibitors delay nitrogen conversion, extending soil residence time. North American corn belt cooperatives specify stabilized formulations where split-application labor costs exceed inhibitor premiums.
Standard Granular retains volume leadership; Controlled-Release holds the steepest expansion curve.
Application:
Cost tier stratification separates bulk commodity offtake from precision-input specialty markets.
- Agriculture:Broadacre grain and oilseed cultivation consumes the majority of global granular urea tonnage. Rice-wheat double-cropping systems across Punjab and Haryana sustain bulk demand where subsidized procurement insulates farmers from price spikes.
- Horticulture:High-value fruit and vegetable production commands premium formulations with documented application efficiency. Florida specialty crop growers bypass cooperative channels through direct platform procurement seeking sub-ton lot flexibility.
- Turf Management:Golf course and sports field maintenance requires consistent color response with minimal burn risk. Sulfur-coated variants dominate this segment where aesthetic performance tolerates moderate nitrogen cost premiums.
- Forestry:Plantation timber and reforestation programs apply bulk urea for establishment-phase nitrogen supplementation. Scandinavian forest cooperatives specify standard granular delivered to remote sites where coating premiums exceed stand value differentials.
Agriculture commands absolute tonnage; Horticulture generates the highest margin per kilogram applied.
Distribution Channel:
Customer type fragmentation is forcing channel diversification between legacy cooperative systems and platform-based disintermediation.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregate demand across thousands of farm operations. Prairie province cooperatives in Canada maintain last-mile distribution density that platform entrants cannot economically replicate.
- Direct Sales:Large-scale farming operations and integrated agribusinesses negotiate volume contracts bypassing intermediary markups. Gulf Coast ammonia-integrated producers leverage this channel to defend margin positions against subsidized import competition.
- Online Retail:Agricultural e-commerce portals aggregate fragmented horticulture demand for containerized spot purchases. Pacific Northwest specialty growers utilize these platforms where cooperative density remains thin and import logistics favor direct arrangements.
- Specialty Stores:Garden center and farm supply retailers serve hobbyist and small-scale professional operators. These outlets stock coated and stabilized variants in bagged formats unsuited to bulk cooperative procurement.
Agricultural Cooperatives retain volume leadership; Online Retail holds the steepest expansion curve.
Market Player Type:
Supply concentration among integrated ammonia producers shapes competitive dynamics across downstream tiers.
- Fertilizer Manufacturers:Ammonia-urea integrated producers control primary cost positions through Gulf Coast gas access or Middle Eastern feedstock advantage. These operators increasingly certify carbon intensity metrics to maintain European market access under impending CBAM requirements.
- Wholesalers:Regional volume aggregators manage inventory positions across multiple source origins. Atlantic Basin wholesalers face particular margin compression when Henry Hub spikes coincide with subsidized import availability.
- Distributors:Logistics specialists coordinate bulk handling, storage, and last-mile delivery to farm gate. Brazilian distributors are expanding Cerrado coverage where infrastructure gaps currently limit manufacturer direct access.
- Regional Suppliers:Localized blenders and formulators customize product specifications for niche agronomic conditions. These operators capture value through application advisory services that commodity manufacturers cannot scale.
Fertilizer Manufacturers retain volume leadership; Regional Suppliers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Gulf Coast ammonia-integrated producers and Indo-Gangetic subsidized buyers defines regional competitive dynamics. India's Department of Fertilizers locks in farmer affordability through import parity calculations that insulate domestic demand from international volatility. European carbon border adjustments now threaten to erode Middle Eastern producers' cost advantages in Atlantic Basin markets.
United States
Precision agriculture adoption across Iowa and Illinois corn belts expands controlled-release formulation demand. The EPA regulates ammonia and nitrous oxide emissions under the Clean Air Act, pressuring Gulf Coast facilities to certify carbon intensity metrics. CF Industries leverages its Donaldsonville-Baton Rouge corridor integration to dominate North American supply corridors with pipeline-connected distribution.
India
Rice-wheat double-cropping intensity across Punjab and Haryana sustains the world's largest subsidized urea offtake. The Department of Fertilizers administers the urea subsidy regime through neem-coating mandates and import parity pricing that shields farmers from international spikes. Paradip and Kandla ports handle bulk arrivals from Middle Eastern producers under long-term offtake agreements.
Brazil
Soybean frontier expansion across Mato Grosso and Goiás in the Cerrado biome creates underpenetrated bulk demand where logistics infrastructure gaps limit supplier access. ANVISA and the Ministry of Agriculture regulate fertilizer quality standards while import dependency exceeds domestic production capacity. Santos and Paranaguá terminals serve as primary discharge points for seaborne urea from Qatar and Saudi Arabia.
Germany
The EU F-Gas Regulation and impending carbon border adjustment mechanism reshape procurement criteria for nitrogen inputs across Bavarian and North Rhine-Westphalia farming cooperatives. Yara International anchors European demand through carbon footprint tracking and controlled-release formulations that align with Farm to Fork nitrogen reduction targets. The BASF Ludwigshafen cluster drives coating technology innovation for precision agriculture applications.
China
Domestic production capacity consolidation under environmental enforcement pressures from the Ministry of Ecology and Environment reduces export availability. Shandong and Inner Mongolia production bases face dual carbon and energy intensity mandates that favor facilities with coal-gasification retrofits. The country's national fertilizer regulator oversees quality standards while provincial governments manage reserve stockpiling programs.
Granular Urea Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ammonia synthesis and coating technology. Market structure consolidates around ammonia-urea integrated producers with captive natural gas access, while regional blenders and formulators fragment the downstream advisory layer. Three archetypes dominate: Gulf Coast gas-integrated majors, Middle Eastern export-focused national champions, and European precision-formulation specialists. Competitive moves concentrate on carbon capture retrofitting and direct-to-farmer platform development to bypass cooperative intermediaries.
Among North American ammonia-integrated producers, CF Industries Holdings, Inc. and Nutrien Ltd. occupy positions that exemplify Gulf Coast feedstock advantage and prairie distribution density respectively. Yara International ASA represents the European precision-formulation archetype with carbon-tracking capabilities. Middle Eastern export capacity concentrates around Qatar Fertiliser Company and SABIC as national champions with disproportionate Atlantic Basin supply influence.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| Yara International ASA |
| Nutrien Ltd. |
| SABIC |
| OCI N.V. |
| EuroChem Group |
| Koch Fertilizer LLC |
| PT Pupuk Indonesia |
| Qatar Fertiliser Company |
| Others |
Value Chain & Pricing Dynamics
Qatar, Saudi Arabia, and the UAE control disproportionate export capacity for granular urea, anchoring margin pools with Gulf Coast ammonia-integrated producers who defend positions through pipeline-connected distribution networks. This upstream concentration allows Middle Eastern national champions to dictate spot pricing volatility while subsidized import regimes in India and Brazil absorb cost fluctuations through government-backed procurement mechanisms.
Pricing Analysis
The customization-premium spread between standard granular and controlled-release formulations runs 40-60% above commodity baselines, with polymer-coated variants commanding peak margins in California's Central Valley specialty crop segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by nitrogen efficiency certification and application precision, with coating technology and carbon intensity documentation driving differentiation. Cost compression in standard granular is intensifying because Middle Eastern producers expand export capacity into Atlantic Basin markets. Agricultural cooperatives in the Indo-Gangetic Plain exhibit lowest price sensitivity due to India's Department of Fertilizers subsidy regime, while Pacific Northwest horticulture operators demonstrate highest sensitivity as they bypass cooperative channels for spot platform procurement.
Supply Chain Analysis
Export-control regimes limiting ammonia synthesis technology transfer have concentrated production know-how among established Gulf Coast and Middle Eastern operators, reinforcing barriers for new capacity entrants. Geographic supply concentrates in Qatar, Saudi Arabia, and the United Arab Emirates for seaborne exports, with the United States and Russia anchoring Atlantic Basin supply. Raw material dependencies center on natural gas feedstock for ammonia synthesis, sulfur for coating matrices, and polymer resins for controlled-release barriers. Single-source vulnerability threatens Atlantic Basin buyers during geopolitical disruptions or Strait of Hormuz chokepoint events. Distribution runs through agricultural cooperative networks for bulk volumes, with platform-based direct procurement gaining share among smaller horticulture operators seeking containerized spot flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granular urea sits in early-cycle expansion as precision agriculture adoption accelerates controlled-release formulation penetration beyond commodity grain belts into specialty crop segments. Brazilian Cerrado soybean frontier cultivation and Southeast Asian rice intensification programs extend addressable demand beyond traditional Indo-Gangetic strongholds.
For Market Incumbents: Insulate margin positions through carbon capture retrofitting at Gulf Coast ammonia-integrated facilities before EU carbon border adjustment mechanisms phase in full charges on embedded emissions. Deepen backward integration into pipeline-connected storage and distribution infrastructure to defend against platform-based disintermediation threatening cooperative channel control. Prioritize certification investment for carbon intensity metrics to maintain European market access as Farm to Fork nitrogen reduction targets reshape procurement criteria.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian Cerrado logistics infrastructure where current gaps limit manufacturer direct access to soybean frontier cultivation demand. Target Pacific Northwest and Florida specialty horticulture segments through agricultural e-commerce portals offering sub-ton lot flexibility and transparent spot pricing that cooperative density cannot match. Pursue coating technology licensing agreements with European precision-formulation specialists to bypass capital-intensive ammonia synthesis barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward regional blenders and formulators with application advisory capabilities that commodity manufacturers cannot scale, capturing value downstream from ammonia-urea integration. Long-term viability across the projection horizon favors operators with documented carbon intensity certification and controlled-release formulation pipelines aligned with environmental compliance premiums. Watch for inflection signals in EU carbon border adjustment implementation timelines that would shift competitive cost positions between domestic production and seaborne imports.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofitting | Enables Gulf Coast producers to certify emissions intensity for EU market access under impending CBAM requirements. |
| Backward Integration into Distribution | Secures last-mile control through pipeline-connected storage networks that platform entrants cannot economically replicate. |
| Controlled-Release Formulation Expansion | Captures premium margins in California Central Valley specialty crops where runoff compliance carries insurance cost consequences. |
| Direct Platform Procurement Development | Bypasses cooperative intermediaries for Pacific Northwest horticulture operators seeking transparent spot pricing flexibility. |
| Brazilian Logistics Infrastructure Partnership | Opens Cerrado soybean frontier access where current gaps limit supplier penetration into accelerating bulk demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fertilizer procurement managers at agricultural cooperatives, ammonia plant operations directors, coating technology R&D leads, and logistics specialists managing bulk terminal operations. Secondary validation drew from customs and trade data, Department of Fertilizers subsidy administration records, SEC filings from listed ammonia-urea integrated producers, and EU emissions trading scheme disclosures. Bottom-up volume modeling across application segments and top-down macroeconomic anchoring were triangulated to constrain estimate variance.
Calibration against historical price volatility episodes and subsidy regime shifts informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product formulation tier, crop application type, distribution channel configuration, and regional regulatory cluster. CAGRs were derived from slope-constrained growth curves fitted to adoption S-cycles for precision agriculture technologies and penetration limits for controlled-release formulations. Industry-specific inputs incorporated natural gas feedstock cost scenarios and carbon border adjustment phase-in schedules.
Stress conditions across Henry Hub and TTF price spikes, EU CBAM implementation acceleration, and Indo-Gangetic subsidy regime recalibration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory enforcement intensity. Material shifts in Gulf producer export capacity expansion timelines or Farm to Fork nitrogen reduction target acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
4-Diisopropylbenzene Market