
 Global Isobutanol Market | 2026-2036
Global Isobutanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isobutanol Market Foresight
A capital-intensity divergence between integrated petrochemical majors and emerging bio-based specialists is unwinding competitive stability in isobutanol supply. BASF SE leverages its Ludwigshafen Verbund complex to sustain captive propylene-to-oxo-alcohol economics. Gevo Inc. anchors its position through bio-based production pathways targeting low-carbon fuel additive offtake. Eastman Chemical Company differentiates via specialty grade purity control for pharmaceutical and cosmetics solvent applications.
Isobutanol is a four-carbon branched alcohol with a boiling point of 108°C and solubility parameter of 11.2 MPa½, manufactured primarily through propylene hydroformylation via the oxo process or through fermentation of carbohydrate feedstocks; it functions as a latent solvent, blending component, and chemical intermediate across coatings and fuels. Purity grade material dominates value capture in pharmaceutical and electronics solvent applications where moisture and aldehyde specifications tighten. Bio-based production technology represents the fastest-expanding segment as fuel additive mandates in multiple jurisdictions pull renewable alcohol volumes into road fuel pools. Industrial grade supply remains mature, with margin pools compressing amid Asian capacity additions.
EPA fuel additive registration requirements under 40 CFR Part 79 govern US market access for isobutanol blending components, while REACH and the EU Green Deal carbon border adjustments shape European import competitiveness. China's NMPA and GB standards regulate pharmaceutical-grade material, with SAMR enforcing industrial chemical quality certifications. Stakeholders must monitor biofuel policy implementation timelines and oxo-alcohol feedstock cost spreads to calibrate capacity and technology commitments.
Market Dynamics
The oxo-process feedstock cost spread between propylene and natural gas liquids is compressing margins for merchant isobutanol producers while integrated petrochemical complexes capture captive value through backward integration into propylene supply.
Growth Catalysts
- EPA 40 CFR Part 79 fuel additive registration:US regulatory pathway for isobutanol blending into gasoline pools creates formal offtake channels for renewable alcohol producers seeking road fuel market access.
- Coatings sector solvent demand:Architectural and industrial coatings manufacturers specify isobutanol for lacquer thinners and amino resin synthesis due to its latent solvent properties and evaporation profile control.
- China oxo-alcohol capacity expansion:Domestic propylene hydroformylation investments in Ningbo and Shanghai chemical parks reduce import dependency and reshape Asia-Pacific supply availability.
Market Restraints
- Propylene price volatility:Naphtha-cracker and propane dehydrogenation feedstock costs transmit directly to oxo-alcohol production economics, squeezing variable margins during olefin upcycles.
- REACH authorization timelines:ECHA substance evaluation procedures for industrial chemical imports extend market entry lead times for non-EU producers by 18-36 months.
- Ethanol blending competition:First-generation biofuel infrastructure and policy support in Brazil and the US displace isobutanol volumes in renewable fuel additive applications.
Strategic Opportunities
- India specialty chemicals manufacturing:CDSCO pharmaceutical-grade certification requirements and expanding domestic API production create demand for high-purity solvent grades in Hyderabad and Mumbai clusters.
- EU Green Deal carbon border adjustment:CBAM implementation on imported chemicals incentivizes bio-based production pathways with verified lifecycle carbon intensity advantages.
- Fermentation-catalyst convergence:Engineered yeast strain development combined with continuous processing technology reduces bio-based isobutanol production capital intensity versus batch systems.
Industry Challenges
- Pharmaceutical-grade certification complexity:Multi-jurisdictional GMP audits and aldehyde specification testing extend product qualification cycles for solvent suppliers targeting injectable drug applications.
- Specialized bioprocess engineering talent:Scarcity of fermentation scale-up expertise limits deployment velocity for cellulosic isobutanol projects beyond pilot demonstration phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isobutanol Market |
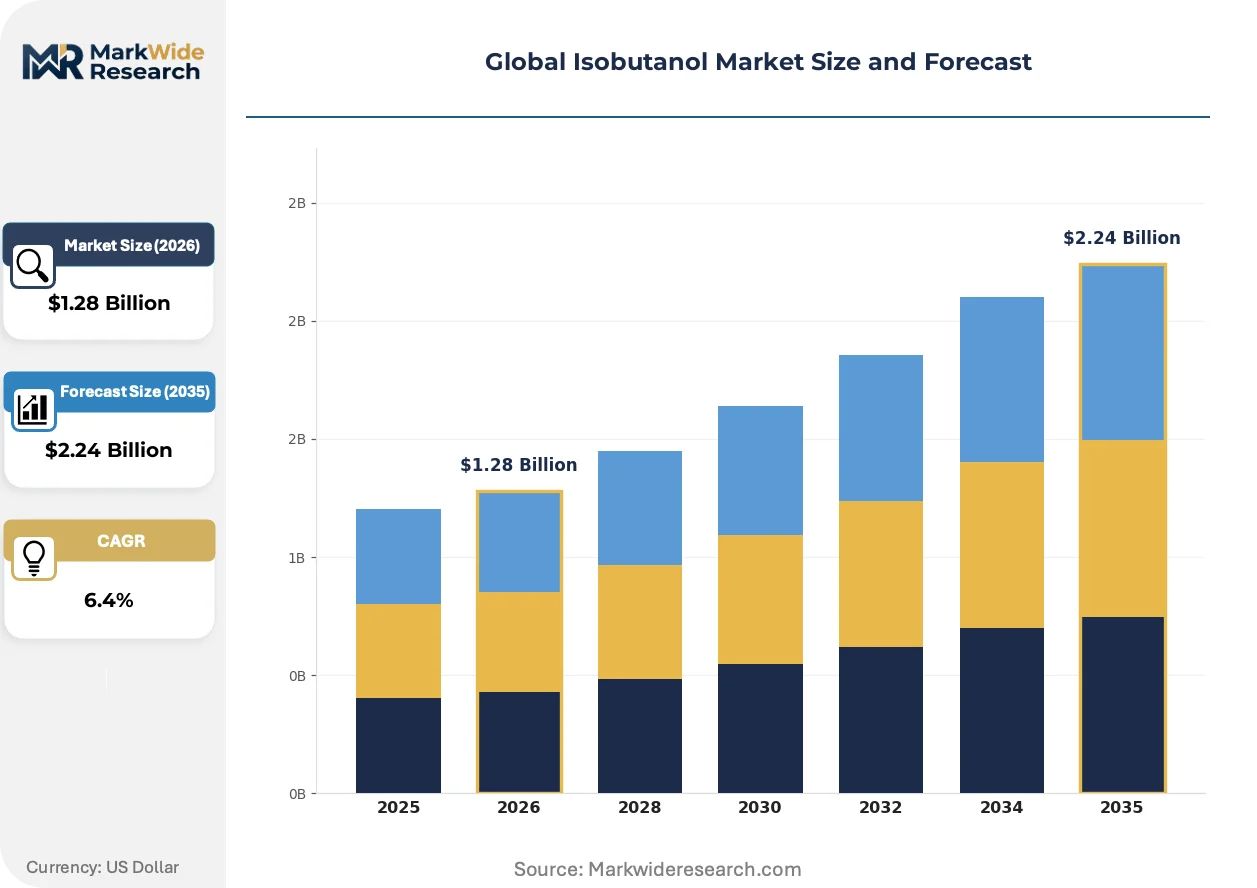
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity Grade, Formulated Grade, Industrial Grade, Fuel Grade, Specialty Grade Technology: Fermentation, Chemical Synthesis, Catalytic Hydrogenation, Oxo Process, Bio-based Production Application: Solvents, Fuel Additives, Plasticizers, Pharmaceuticals, Cosmetics End Use Industry: Paints & Coatings, Adhesives & Sealants, Personal Care, Chemical Manufacturing, Agriculture |
| Companies Covered | BASF SE, Eastman Chemical Company, Mitsubishi Chemical Group Corporation, Dow Inc., Gevo Inc., INEOS Group, ExxonMobil Corporation, LYONDELLBASELL Industries, SIBUR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isobutanol Market Shifts & Advancements
Production technology selection is fragmenting the supplier base into distinct competitive camps with irreconcilable cost structures, forcing buyers to navigate divergent carbon accounting and supply security profiles.
Advanced fermentation platforms utilizing engineered clostridium strains and gasification-syngas routes are bifurcating the bio-based isobutanol landscape. Aviation fuel offtakers including sustainable aviation fuel blenders are contracting dedicated volumes at premium pricing to secure low-carbon intensity feedstock. This technology divergence is compressing capital access for first-generation corn-starch fermentation projects while rewarding integrated biorefinery configurations with offtake visibility.
REACH authorization combined with EU Green Deal carbon border adjustments is tightening import competitiveness for non-EU oxo-alcohol producers. ECHA substance evaluation and SVHC candidate listing procedures now require extensive chemical safety dossiers for industrial-grade material. European coatings and fuel additive formulators are responding by qualifying regional bio-based suppliers with certified mass-balance chain of custody.
Long-term contracting structures are displacing spot market procurement for pharmaceutical and electronics solvent grades. Specialty chemical distributors in Germany and Japan are consolidating volume commitments through three-year supply agreements with fixed purity specifications and audit rights. This shift is most visible in semiconductor solvent applications where moisture content below 100 ppm commands dedicated tankage and handling protocols.
Global Isobutanol Market Segmentation
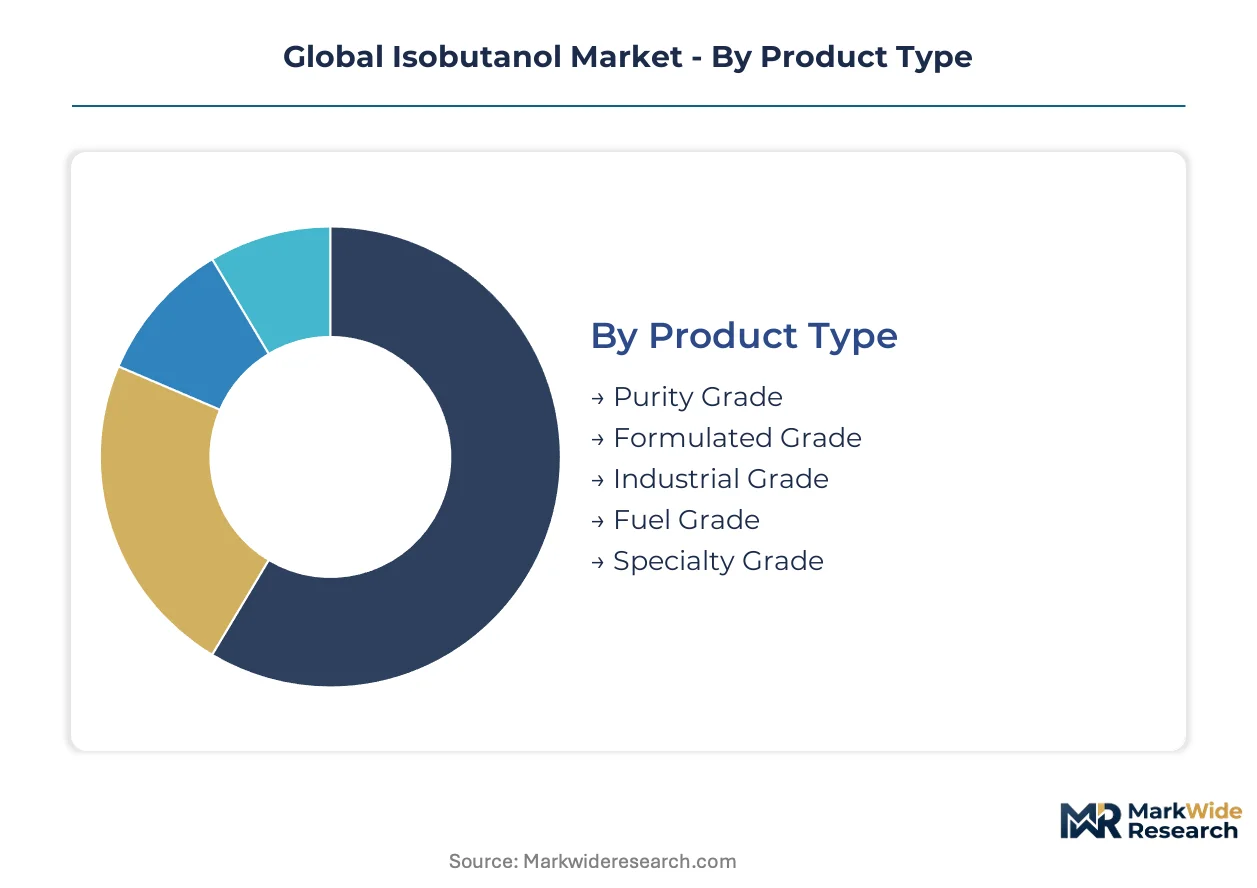
Isobutanol market segmentation reveals divergent margin pools across purity specifications and production pathways. Technology selection and end-use certification requirements create distinct competitive arenas with irreconcilable cost structures.
Product Type:
Fuel Grade and Industrial Grade face acute substitution pressure from ethanol and n-propanol in cost-sensitive blending applications, while Purity Grade commands defensive positioning through specification lock-in.
- Purity Grade:Material meeting aldehyde specifications below 50 ppm and moisture content under 100 ppm serves semiconductor cleaning and injectable drug solvent applications. Pharmaceutical manufacturers in Germany and Japan specify this grade under GMP protocols with dedicated tankage requirements.
- Fuel Grade:Denatured alcohol meeting EPA 40 CFR Part 79 registration requirements for gasoline blending pools. Renewable fuel producers in the US Midwest and Brazilian ethanol corridors compete for road fuel additive offtake against incumbent ethanol infrastructure.
- Formulated Grade:Pre-blended solvent mixtures for coatings manufacturers seeking evaporation profile control without in-house formulation capability.
- Industrial Grade:Standard oxo-process output for lacquer thinners and amino resin synthesis with compressing margins amid Asian capacity additions.
- Specialty Grade:Cosmetic-grade material meeting EU Regulation (EC) No 1223/2009 purity requirements for fragrance carrier applications.
Industrial Grade anchors the volume base while Purity Grade gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive petrochemical routes from fermentation platforms with divergent feedstock exposure and carbon intensity profiles.
- Oxo Process:Propylene hydroformylation via rhodium or cobalt catalyst systems dominates merchant supply. BASF's Ludwigshafen Verbund complex and Chinese state-owned refineries in Ningbo operate at scale with captive propylene integration.
- Bio-based Production:Engineered yeast and clostridium fermentation of corn starch or cellulosic feedstocks. Gevo Inc. and emerging biorefinery developers target sustainable aviation fuel offtake with certified mass-balance chain of custody.
- Fermentation:First-generation batch systems using conventional yeast strains with higher capital intensity than continuous processing alternatives.
- Chemical Synthesis:Guerbet condensation routes for niche specialty applications with limited scale economics.
- Catalytic Hydrogenation:Isobutyraldehyde reduction pathways integrated with oxo-alcohol complexes.
Oxo Process retains the installed capacity base while Bio-based Production expands most quickly on policy pull.
Application:
Customer type concentration varies sharply: coatings formulators prioritize latent solvent properties while fuel blenders optimize for octane enhancement and renewable identification number eligibility.
- Solvents:Lacquer thinners and amino resin synthesis in architectural and industrial coatings. Evaporation profile control drives specification in automotive OEM clearcoat applications.
- Fuel Additives:Gasoline blending for octane enhancement and renewable volume compliance. EPA registration and state-level low-carbon fuel standards govern market access.
- Plasticizers:Intermediate for dibutyl and dioctyl phthalate alternatives in flexible PVC compounding.
- Pharmaceuticals:Extraction solvent and tablet coating carrier under FDA and EMA GMP oversight.
- Cosmetics:Fragrance diluent and nail polish solvent subject to EU Cosmetics Regulation and China's NMPA filing requirements.
Solvent applications anchor the volume base while Fuel Additives climb the fastest on biofuel mandate expansion.
End Use Industry:
Supply concentration maps directly to regional manufacturing clusters: coatings demand concentrates in China's Yangtze River Delta while pharmaceutical offtake centers on European and Indian API production zones.
- Paints & Coatings:Architectural and industrial formulators in Germany, Japan, and China's Shanghai chemical parks specify isobutanol for amino resin synthesis and viscosity control.
- Chemical Manufacturing:Oxo-alcohol derivatives and plasticizer intermediate production with backward integration into propylene supply at major petrochemical complexes.
- Adhesives & Sealants:Solvent-borne pressure-sensitive adhesive formulations for tape and label applications.
- Personal Care:Fragrance and cosmetic solvent demand subject to REACH authorization and EU Green Deal carbon border adjustment exposure.
- Agriculture:Pesticide formulation solvent and adjuvant carrier under EPA and PMRA registration requirements.
Chemical Manufacturing anchors the volume base while Personal Care gains share fastest on premium-grade certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Chinese oxo-alcohol producers and European specialty-grade suppliers is widening regional arbitrage windows. German pharmaceutical-grade certification commands premiums that Ningbo industrial-grade output cannot capture. This divergence shapes capacity deployment decisions across producer geographies.
United States
EPA 40 CFR Part 79 fuel additive registration drives renewable isobutanol offtake into Midwest gasoline blending pools. State-level low-carbon fuel standards in California and Oregon pull bio-based volumes away from merchant chemical markets. Houston-Gulf Coast petrochemical complexes maintain backward integration into propylene supply through shale-derived feedstock advantages.
Germany
Ludwigshafen chemical park concentration sustains captive oxo-alcohol economics through Verbund integration. REACH authorization timelines under ECHA substance evaluation extend import lead times for non-EU producers by 18-36 months. Bavarian coatings formulators qualify regional bio-based suppliers with certified mass-balance chain of custody to manage carbon border adjustment exposure.
China
Ningbo and Shanghai chemical parks expand domestic propylene hydroformylation capacity to reduce import dependency. SAMR industrial chemical quality certifications govern merchant-grade material circulation. Yangtze River Delta coatings manufacturers specify local isobutanol for amino resin synthesis in architectural applications.
India
CDSCO pharmaceutical-grade certification requirements expand demand for high-purity solvent grades in Hyderabad and Mumbai API clusters. Domestic oxo-alcohol investments lag specialty chemical consumption growth. Gujarat chemical manufacturing zones attract import volumes for industrial-grade lacquer thinner applications.
Japan
METI energy policy frameworks govern renewable fuel additive eligibility for domestic refinery blending. Osaka-Kobe industrial corridor maintains semiconductor solvent specifications with moisture content below 100 ppm. Pharmaceutical manufacturers in Kanto specify GMP-grade material under PMDA oversight for injectable drug applications.
Global Isobutanol Market Competitive Landscape
Concentration sits with integrated petrochemical majors controlling captive propylene feedstock and fermentation-based specialists targeting low-carbon fuel additive offtake. The supplier base bifurcates into oxo-process incumbents with backward integration advantages and bio-based entrants with carbon intensity certification. Three archetypes dominate: multinational chemical conglomerates, renewable fuel technology developers, and regional oxo-alcohol merchant producers. Competitive moves center on capacity expansion in Chinese chemical parks and strategic partnerships with sustainable aviation fuel blenders.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify divergent strategic positioning. BASF anchors European supply through Ludwigshafen Verbund economics. Eastman occupies a specialty-grade niche via purity control protocols. Among bio-based developers, Gevo Inc. represents the fermentation-platform archetype targeting renewable fuel additive markets with certified lifecycle carbon accounting.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Mitsubishi Chemical Group Corporation |
| Dow Inc. |
| Gevo Inc. |
| INEOS Group |
| ExxonMobil Corporation |
| LYONDELLBASELL Industries |
| SIBUR |
| Others |
Supply & Pricing Matrix
Ethanol blending competition in renewable fuel pools simultaneously redraws supply geography toward Brazilian and US Midwest ethanol corridors while compressing isobutanol pricing premiums in fuel additive applications. This substitution dynamic forces oxo-process producers toward pharmaceutical and electronics solvent grades where certification barriers defend margin structures.
Pricing Analysis
The customization-premium spread separates GMP-certified pharmaceutical grades from standard industrial material by a factor reflecting multi-jurisdictional audit costs and dedicated tankage requirements. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with purity grade commanding defensive positioning through aldehyde specification lock-in below 50 ppm. Cost compression in fuel grade supply is intensifying because Asian oxo-alcohol capacity additions expand merchant availability. Coatings formulators exhibit highest price sensitivity due to solvent substitution elasticity, while semiconductor manufacturers show least sensitivity given moisture content thresholds below 100 ppm.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical and electronics solvent procurement, with German and Japanese buyers consolidating three-year supply agreements to secure dedicated handling protocols. Geographic supply concentration centers on Germany's Ludwigshafen Verbund complex, China's Ningbo and Shanghai chemical parks, and US Gulf Coast propylene-integrated facilities. Raw material dependencies draw from propylene hydroformylation feedstocks, corn starch fermentation inputs, and rhodium or cobalt catalyst systems. Single-source vulnerability in specialty grade purification creates exposure for semiconductor solvent applications. Distribution runs through specialty chemical distributors with certified mass-balance chain of custody capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
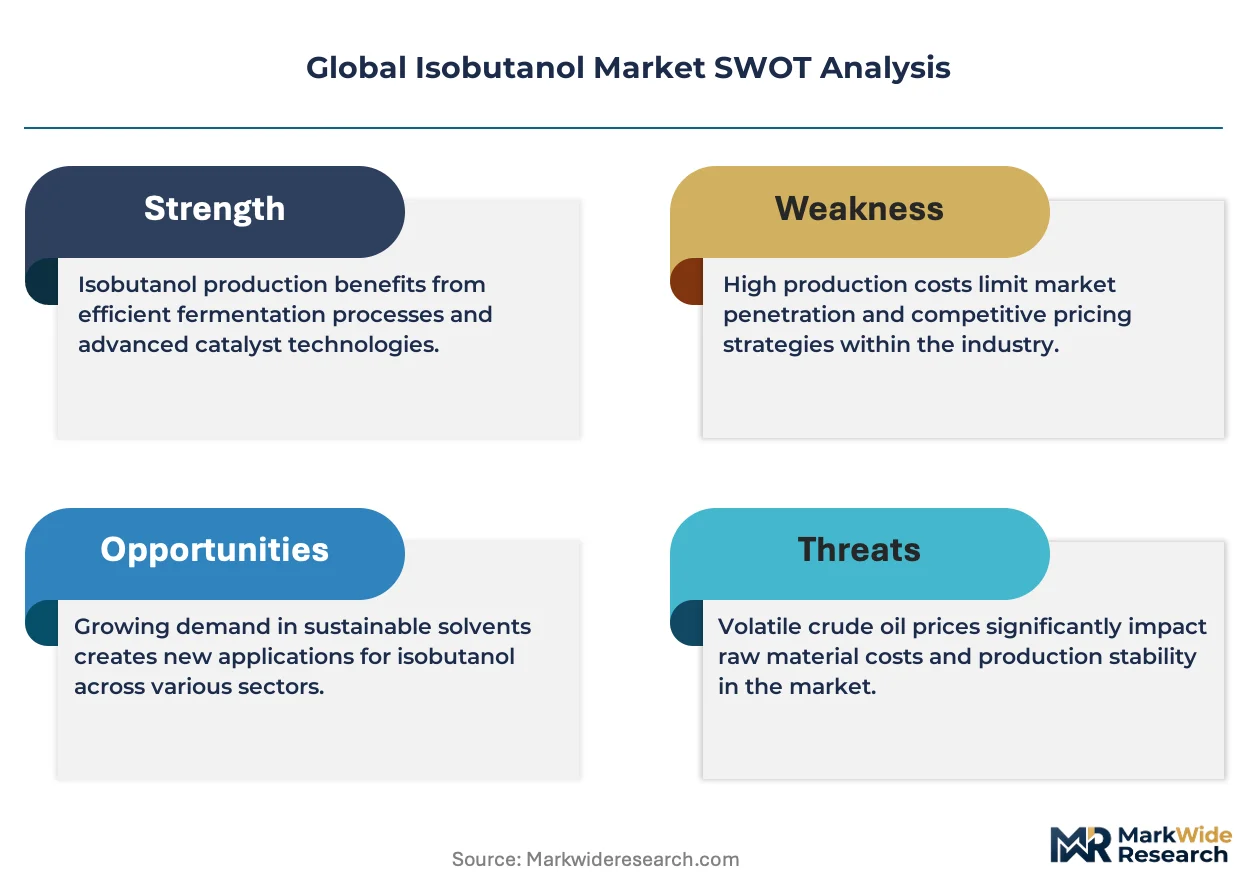
This market functions as a defensive-moat story where REACH authorization timelines and ECHA substance evaluation procedures create regulatory entrenchment extending market entry lead times by 18-36 months for non-EU producers.
For Market Incumbents: Fortify backward integration into propylene supply at Ludwigshafen and Ningbo complexes to defend against bio-based fermentation entrants targeting sustainable aviation fuel offtake. Expand GMP certification investment for pharmaceutical-grade material to deepen specification lock-in against Asian industrial-grade imports. For New Entrants and Emerging Players: Lead with CDSCO pharmaceutical-grade certification in Hyderabad and Mumbai API clusters where domestic oxo-alcohol investment lags specialty chemical consumption growth. Target sustainable aviation fuel blender partnerships as the most penetrable offtake channel, leveraging certified lifecycle carbon accounting as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed bio-based fermentation platforms holding offtake visibility with renewable fuel blenders but requiring capital for continuous processing scale-up. Long-term viability hinges on carbon border adjustment mechanics favoring verified low-carbon intensity pathways. Monitor EU Green Deal CBAM implementation stringency as the inflection indicator warranting re-evaluation of oxo-process versus fermentation platform exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | BASF's Ludwigshafen Verbund complex captures captive oxo-alcohol economics against merchant margin compression. |
| Continuous Processing Technology Deployment | Engineered yeast strain fermentation reduces bio-based isobutanol capital intensity versus batch alternatives. |
| Long-term Supply Agreement Structuring | German specialty distributors consolidate three-year commitments with fixed purity specifications and audit rights. |
| Pharmaceutical-Grade Certification Investment | CDSCO and PMDA GMP protocols create specification lock-in for injectable drug solvent applications. |
| Sustainable Aviation Fuel Offtake Partnership | Renewable fuel blenders contract dedicated volumes at premium pricing for low-carbon intensity feedstock security. |
Research Methodology
Cross-validation between plant manager interviews at oxo-alcohol complexes and customs trade data anchors the qualitative findings in this study. Primary engagement with procurement leads at coatings OEMs, fermentation scale-up engineers, and specialty chemical distribution channel partners combines with secondary validation through SEC 10-K filings, Cefic capacity reports, and ECHA substance evaluation databases. Bottom-up and top-down triangulation reconciles production capacity assessments with end-use consumption estimates.
Sensitivity analysis around propylene feedstock cost spreads and biofuel mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, production technology pathway, end-use industry concentration, and regional regulatory cluster. CAGRs derive from installed capacity expansion schedules cross-referenced with offtake visibility in sustainable aviation fuel and pharmaceutical solvent applications.
Forecasts assume regulatory continuity in EPA fuel additive registration, REACH authorization procedures, and EU Green Deal carbon border adjustment mechanics; material policy shifts would require re-modeling. Revision becomes warranted when bio-based production cost parity thresholds cross commercial viability boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market