
 Phosphorus Market | 2026-2036
Phosphorus Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorus Market Outlook
Electrochemical phosphorus recovery from sewage sludge and food waste streams is fragmenting traditional reliance on phosphate rock mining as the sole production pathway. ICL Group Ltd. leverages integrated downstream capabilities across flame retardants and food-grade phosphates to sustain margin capture beyond commodity fertilizers. PhosAgro anchors its position through captive access to high-grade Kola Peninsula apatite reserves, while The Mosaic Company competes via North American phosphate processing scale and sulfuric acid integration.
Phosphorus is a multivalent nonmetal element, atomic number 15, existing primarily as white phosphorus, red phosphorus, or phosphate minerals in nature; industrial production centers on wet-process phosphoric acid via sulfuric acid digestion of phosphate rock, yielding orthophosphoric acid for downstream derivative synthesis. Its primary commercial purpose spans fertilizer nutrient delivery, detergent builder chemistry, and specialized industrial applications requiring thermal or chemical stability. Phosphate rock supply dominates raw material value capture, though phosphoric acid purification for food-grade and electronic-grade specifications commands premium pricing pools. DAP remains the workhorse fertilizer formulation in bulk agriculture, while industrial chemicals applications in lithium iron phosphate cathode precursors represent the fastest-growing demand vector within the end-user landscape.
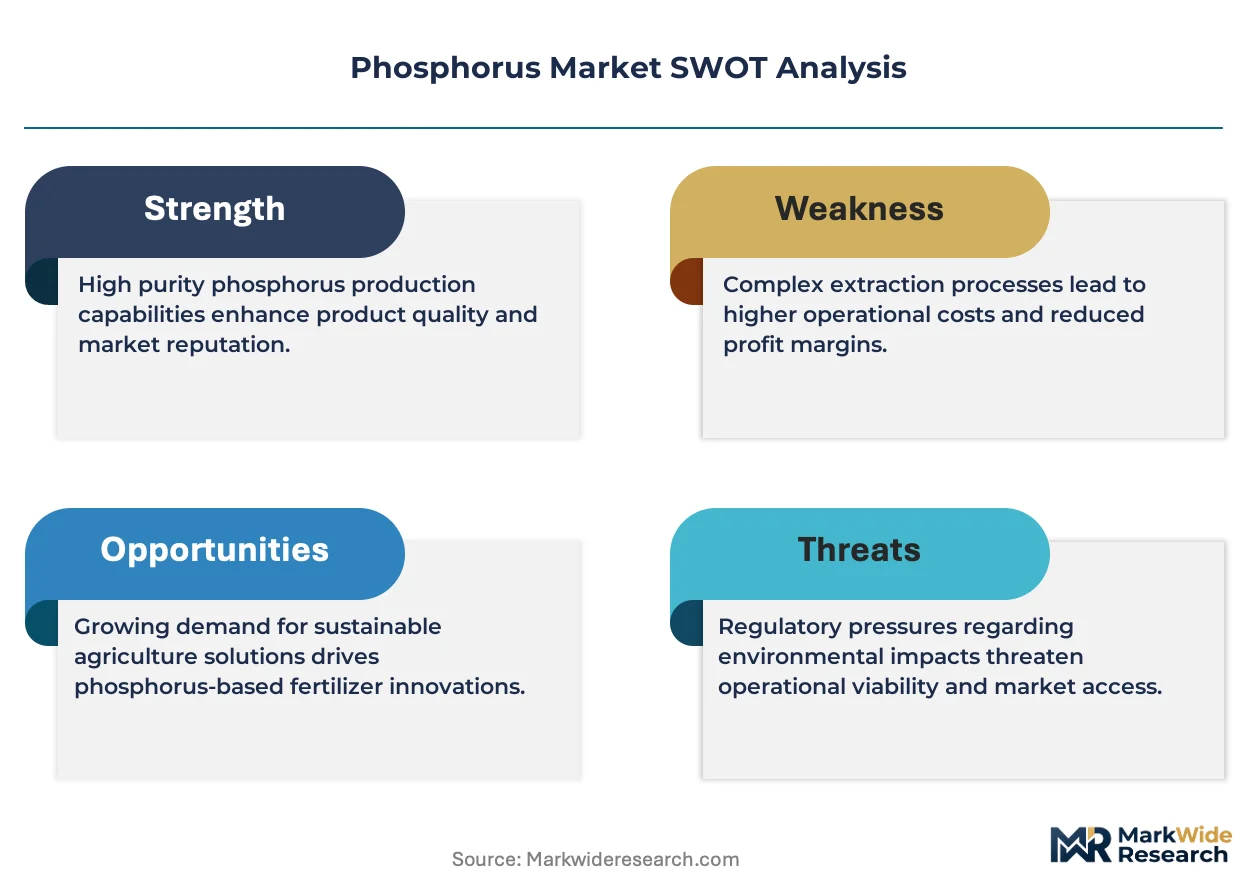
EPA effluent guidelines under the Clean Water Act constrain phosphorus discharge limits from manufacturing facilities, compelling capital deployment toward closed-loop acid recovery systems. REACH registration requirements and EU Green Deal circular economy mandates are accelerating substitution trials for recycled phosphate feedstocks across European chemical manufacturers. China's MEE environmental inspections and dual carbon goals are forcing capacity rationalization in Yunnan and Guizhou production belts. Stakeholders must monitor regulatory divergence between EU circular material quotas and North American mining-permit timelines when allocating long-term offtake commitments.
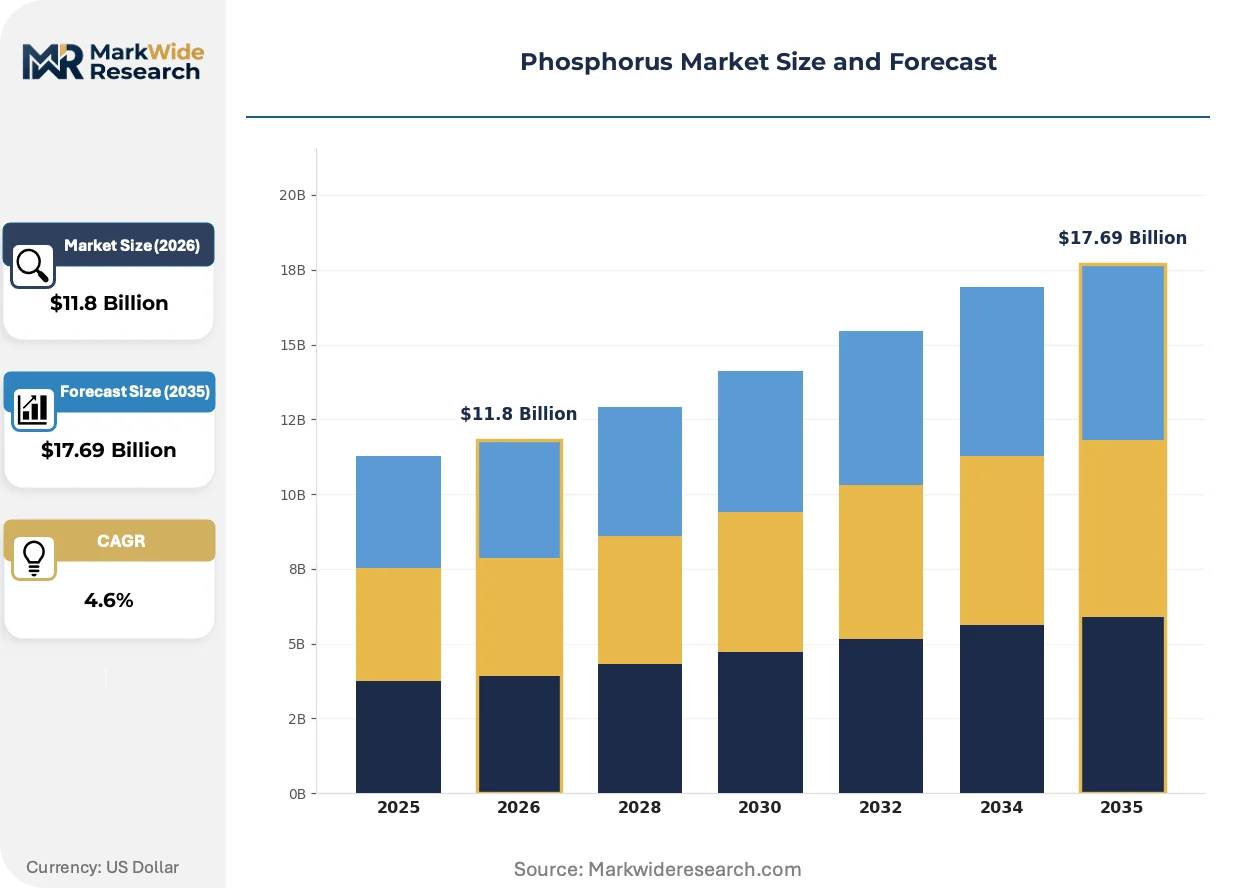
Market Dynamics
Electrochemical phosphorus recovery technologies are fragmenting the century-old phosphate rock mining monopoly, forcing incumbents to reconfigure asset bases around circular feedstock integration and urban mining infrastructure.
Growth Catalysts
- Lithium iron phosphate cathode chemistry:Battery manufacturers in China and Europe are expanding LFP precursor offtake as automakers prioritize cost-stable cathode formulations over nickel-cobalt alternatives.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons is accelerating demand for phosphorus-based flame retardants in HVAC and electronics cooling systems.
- Soil nutrient replenishment in Brazil:Agricultural intensification across the Cerrado and Matopiba regions is driving sustained phosphate fertilizer application rates above historical baselines.
Market Restraints
- Phosphate rock supply concentration:Over 70% of exportable reserves sit with state-linked producers in Morocco and Western Sahara, creating geopolitical offtake vulnerability for import-dependent consumers.
- Sulfuric acid cost volatility:Wet-process phosphoric acid production remains tethered to sulfur pricing swings tied to oil refining and copper smelting output.
- Cadmium and uranium contamination thresholds:EU REACH and EFSA tightening of heavy metal limits in food-grade phosphates is rendering marginal sedimentary deposits uneconomical to process.
Strategic Opportunities
- Urban mining infrastructure in Germany:The EU Green Deal circular economy action plan is funding sewage sludge ash processing pilots to extract secondary phosphate for detergent and animal feed applications.
- India PLI scheme for advanced chemistry cell manufacturing:Domestic LFP cathode production incentives are creating captive demand for battery-grade phosphoric acid purification capacity.
- Precision agriculture integration:Variable-rate phosphorus application systems combined with soil microbiome diagnostics are opening premium service revenue pools beyond commodity fertilizer sales.
Industry Challenges
- Food-grade phosphoric acid certification timelines:FDA and EFSA concurrent approval pathways for new purification facilities extend capital deployment cycles by 18-24 months.
- Electrochemical recovery process engineering talent:The scarcity of specialists integrating membrane electrolysis with struvite precipitation is constraining scale-up of municipal phosphorus recovery plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorus Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Rock, Phosphoric Acid, DAP, TSP Application: Agriculture, Animal Feed, Food Processing, Industrial Chemicals Form: Granular, Powdered, Liquid, Ammonium Phosphate End User: Fertilizers, Chemical Manufacturers, Food Industry, Pharmaceuticals |
| Companies Covered | Thermphos International, Hubei Xingfa Chemicals Group Co. Ltd., ICL Group Ltd., The Mosaic Company, OCP Group, Yunnan Yuntianhua Co. Ltd., PhosAgro, EuroChem, Jiangsu Chengxing Phosph-Chemicals Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorus Market Strategic Shifts
Process intensification and feedstock diversification are converging to compress traditional boundaries between mining, chemical processing, and waste management in phosphorus value creation.
Struvite crystallization reactors deployed at wastewater treatment facilities are rendering obsolete the assumption that phosphate rock must serve as the sole commercial phosphorus source. Municipal utilities in the Netherlands and Germany are installing magnesium-dosing precipitation systems at scale. The technology is rendering obsolete long-term supply contracts tied to Moroccan export quotas.
China's MEE environmental inspections and dual carbon goals are forcing capacity rationalization in Yunnan and Guizhou production belts. Smaller thermal acid producers lacking flue-gas desulfurization infrastructure face mandatory closure timelines. Battery-grade phosphoric acid manufacturers with integrated purification trains are consolidating market access as marginal players exit.
OEM procurement teams at lithium battery producers are unbundling cathode precursor specifications from legacy fertilizer-grade phosphate contracts. Direct negotiations with purified phosphoric acid specialists are displacing trader-mediated spot purchases in volume commitments. This pattern is most visible in South Korean and Japanese cathode material supply chains.
Phosphorus Market Segmentation
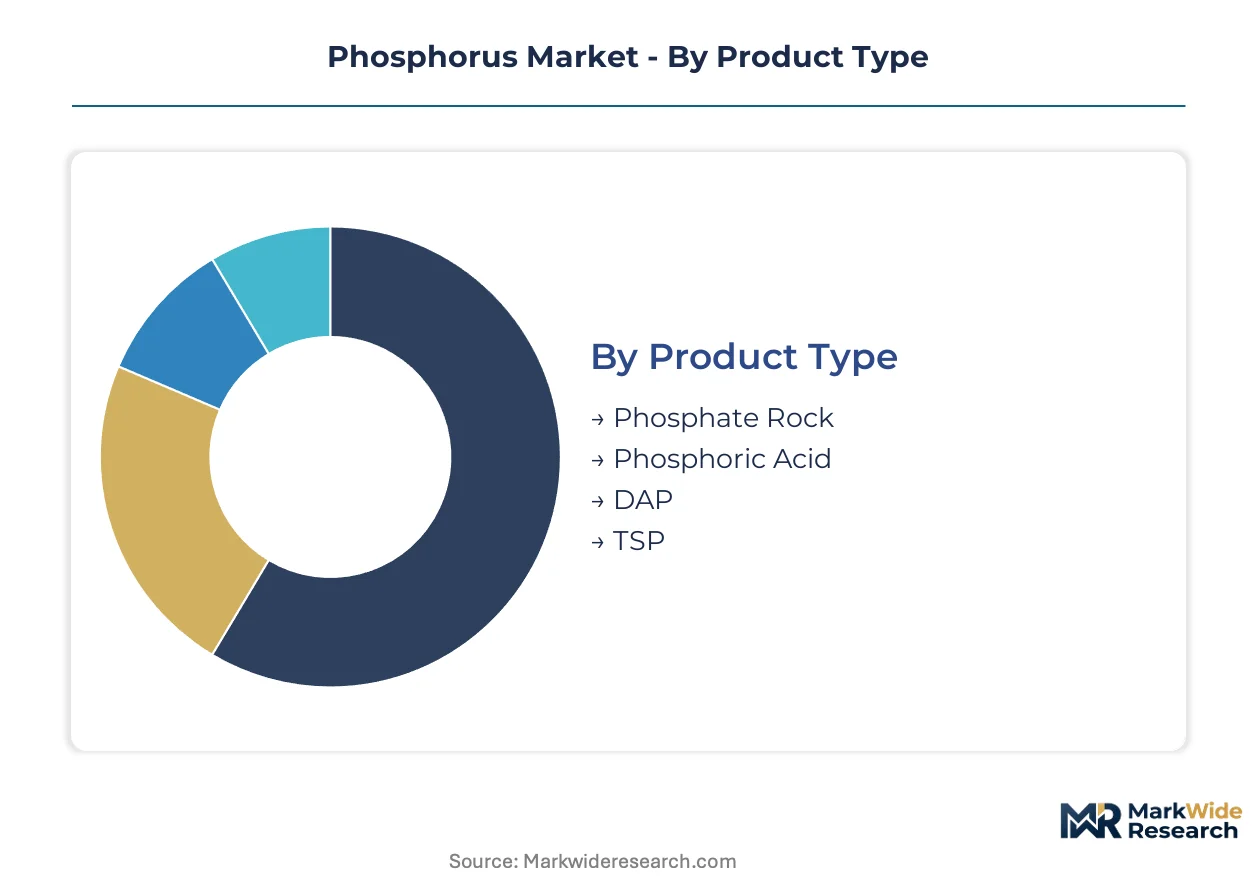
Phosphorus market segmentation reveals divergent margin profiles across upstream mining, midstream acid purification, and downstream specialty derivatives. Each category channels distinct regulatory exposure and customer concentration patterns that reshape competitive positioning.
Product Type:
Use-case spectrum spans bulk commodity extraction through high-purity electronic-grade synthesis, with margin capture concentrating at purification stages.
- Phosphate Rock:Sedimentary and igneous apatite concentrates serve as the foundational feedstock for wet-process acid production. Moroccan state-linked producers control the bulk of exportable reserves, creating geopolitical leverage over import-dependent consumers in India and Brazil.
- Phosphoric Acid:Wet-process orthophosphoric acid dominates fertilizer manufacturing, while thermal acid and purified grades command premiums in food additive and lithium battery cathode precursor applications. Battery manufacturers in China and South Korea are expanding direct offtake negotiations with purified acid specialists.
- DAP:Diammonium phosphate remains the workhorse formulation for bulk agricultural nutrient delivery across the American Midwest and Brazilian Cerrado.
- TSP:Triple superphosphate offers higher phosphorus concentration for specialized soil amendment in precision agriculture systems.
Established volume favors phosphate rock; emerging adoption favors phosphoric acid purification grades.
Application:
Customer concentration varies sharply across cost tiers, from price-sensitive commodity agriculture to specification-driven pharmaceutical synthesis.
- Agriculture:Soil nutrient replenishment drives the bulk of phosphorus consumption, with variable-rate application systems expanding in Brazil's Matopiba region. Fertilizer producers face sulfuric acid cost volatility tied to oil refining and copper smelting output.
- Animal Feed:Defluorinated phosphate supplements meet livestock nutrition requirements under FDA and EFSA contamination thresholds. EU REACH cadmium limits are rendering marginal sedimentary deposits uneconomical for feed-grade processing.
- Food Processing:Food-grade phosphoric acid serves as an acidulant and leavening agent in beverage and bakery applications.
- Industrial Chemicals:Lithium iron phosphate cathode precursors are climbing the fastest within this category as automakers prioritize cost-stable battery chemistry.
Volume leadership sits with agriculture; margin expansion concentrates in industrial chemicals.
Form:
Physical state determines logistics economics and application equipment compatibility across end-use environments.
- Granular:Dense, free-flowing particles optimize bulk handling and mechanical spreading equipment in mechanized farming operations.
- Powdered:Fine particulate grades enable rapid dissolution for liquid fertilizer blending and industrial chemical synthesis.
- Liquid:Solution and suspension formulations support fertigation systems and precision agriculture integration in water-scarce regions.
- Ammonium Phosphate:MAP and DAP solids combine nitrogen and phosphorus in single-application products for emerging market smallholders.
Granular form dominates commodity volumes; liquid form gains share in precision agriculture adoption.
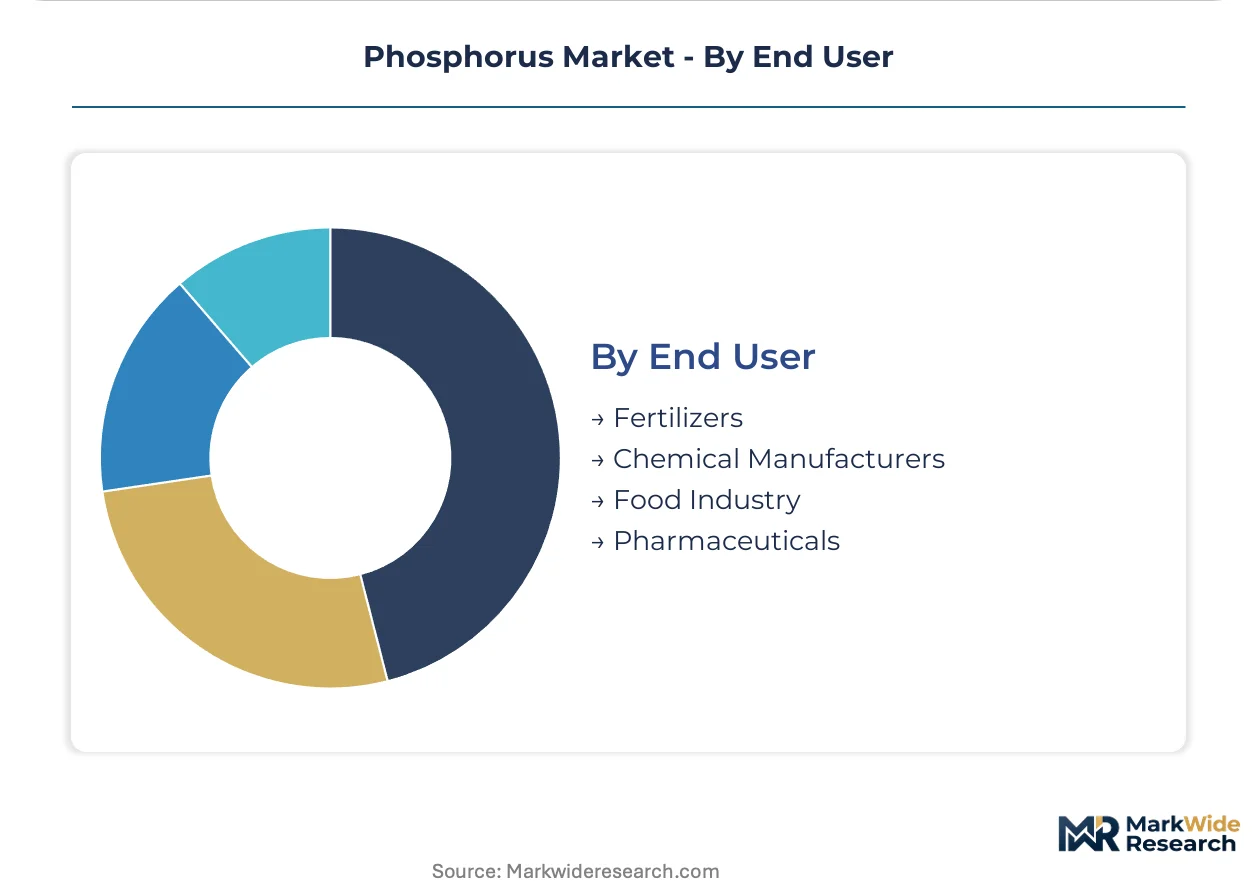
End User:
Procurement sophistication diverges between specification-driven pharmaceutical buyers and price-sensitive fertilizer distributors.
- Fertilizers:Blenders and distributors aggregate phosphate rock, acid, and finished products for agricultural retail channels. Brazilian and Indian offtake is intensifying as soil nutrient depletion accelerates.
- Chemical Manufacturers:Industrial synthesizers of flame retardants, water treatment chemicals, and battery materials require consistent acid purity grades.
- Food Industry:Beverage and processed food manufacturers source food-grade phosphoric acid under FDA and EFSA concurrent approval pathways.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient producers demand ultra-high purity phosphorus compounds with extended certification timelines.
Fertilizers anchor volume demand; pharmaceuticals command premium pricing pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate fertilizer blenders in Brazil and India dominate procurement volumes, while battery-grade acid buyers in China and South Korea reshape contract structures. Regulatory divergence between EU circular economy mandates and North American mining-permit timelines complicates long-term offtake planning.
China
Lithium iron phosphate cathode manufacturers in Jiangsu and Hunan provinces are expanding purified phosphoric acid offtake for electric vehicle battery supply chains. MEE environmental inspections and dual carbon goals are forcing capacity rationalization in Yunnan and Guizhou production belts. Battery-grade phosphoric acid specialists with integrated purification trains are consolidating market access as marginal thermal acid producers face mandatory closure.
Morocco
OCP Group's integrated phosphate mining and downstream expansion anchors global supply chain restructuring for DAP and MAP fertilizer exports. State-linked control over exportable phosphate rock reserves creates geopolitical leverage over import-dependent consumers. Jorf Lasfar industrial complex hosts expanding phosphoric acid purification capacity serving European food-grade and industrial chemical buyers.
United States
The Mosaic Company competes via North American phosphate processing scale and sulfuric acid integration across Florida and Louisiana operations. EPA effluent guidelines under the Clean Water Act constrain phosphorus discharge limits from manufacturing facilities. Midwest fertilizer distributors aggregate phosphate rock, acid, and finished products for agricultural retail channels serving corn and soybean producers.
India
Fertilizer producers are expanding phosphate offtake as soil nutrient replenishment intensifies across the Indo-Gangetic Plain and Deccan Plateau. The PLI scheme for advanced chemistry cell manufacturing is creating captive demand for battery-grade phosphoric acid purification capacity. Gujarat and Maharashtra industrial corridors host emerging purification facilities targeting domestic LFP cathode production.
Germany
The EU Green Deal circular economy action plan is funding sewage sludge ash processing pilots in the Ruhr region to extract secondary phosphate for detergent and animal feed applications. REACH registration requirements and EFSA tightening of heavy metal limits are accelerating substitution trials for recycled phosphate feedstocks. Municipal utilities in the Netherlands and Germany are installing magnesium-dosing struvite precipitation systems at wastewater treatment facilities.
Phosphorus Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. State-linked Moroccan producers dominate upstream phosphate rock export volumes, while integrated chemical conglomerates capture midstream acid purification margins. Three archetypes define competitive positioning: mining-captive state enterprises, diversified fertilizer-chemical hybrids, and purified-acid specialists serving battery and food-grade segments. Dominant competitive moves include backward integration into sulfuric acid production and strategic partnerships with lithium battery cathode manufacturers.
Among diversified chemical conglomerates, ICL Group Ltd. and The Mosaic Company occupy positions spanning flame retardants, food-grade phosphates, and fertilizer manufacturing. State-linked mining enterprises exemplified by OCP Group and PhosAgro anchor upstream supply security through captive access to high-grade phosphate reserves. Chinese chemical manufacturers including Hubei Xingfa Chemicals Group Co. Ltd. and Yunnan Yuntianhua Co. Ltd. represent the scale-driven domestic production tier serving both fertilizer and emerging battery material demand.
| Leading Market Players |
|---|
| Thermphos International |
| Hubei Xingfa Chemicals Group Co. Ltd. |
| ICL Group Ltd. |
| The Mosaic Company |
| OCP Group |
| Yunnan Yuntianhua Co. Ltd. |
| PhosAgro |
| EuroChem |
| Jiangsu Chengxing Phosph-Chemicals Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Jorf Lasfar-to-Rotterdam bulk freight corridors transmit Moroccan phosphate rock pricing power directly into European fertilizer blenders' cost bases, amplifying margin compression when sulfuric acid indices spike and forcing downstream differentiation toward food-grade and battery-grade purification premiums.
Pricing Analysis
Long-term offtake contracts with sulfur and ammonia indexation dominate phosphate fertilizer transactions, with DAP and MAP pricing tethered to commodity benchmarks rather than value-based structures. Price differentiation separates battery-grade phosphoric acid from fertilizer-grade material based on purification intensity and heavy metal certification under REACH and FDA tiers. Pricing pressure stems from sulfuric acid cost volatility tied to oil refining output swings. Brazilian agricultural cooperatives exhibit highest price sensitivity, while South Korean cathode manufacturers accept premiums for specification consistency.
Supply Chain Analysis
Contract manufacturing concentration in Moroccan state-linked facilities and Chinese purification plants controls upstream phosphate rock processing and midstream acid refining capacity. Supply draws from sedimentary deposits in Morocco and igneous apatite in Russia's Kola Peninsula, with sulfuric acid feedstock sourced from oil refining and copper smelting operations. Single-source vulnerability concentrates in Moroccan export quotas controlled by OCP Group. Distribution runs through trader-mediated spot markets for fertilizer-grade material, shifting toward direct OEM negotiations for battery-grade specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate value capture operates as a regulatory-entrenchment moat, where REACH cadmium thresholds and FDA food-grade certification timelines create structural barriers that extend capital deployment cycles and protect incumbent purification specialists from rapid commoditization.
For Market Incumbents: Harden captive reserve positions through backward integration into sulfuric acid production and accelerated certification investment for battery-grade phosphoric acid under concurrent FDA-EFSA pathways. Electrochemical phosphorus recovery startups threaten long-term rock mining economics; incumbents must pre-empt urban mining scale-up through pilot partnerships with German and Dutch municipal utilities.
For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing offers underpenetrated battery-grade acid purification demand with domestic LFP cathode production incentives creating captive offtake. Target Gujarat and Maharashtra industrial corridors with modular purification trains designed for rapid EFSA compliance, bypassing established trader networks through direct cathode manufacturer negotiations.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown timelines reshape the acquisition landscape toward phosphorus-based flame retardant specialists with HVAC and electronics cooling system certifications. Five-to-ten year viability favors purified-acid specialists over commodity fertilizer exposure. Watch for MEE environmental inspection enforcement patterns in Yunnan and Guizhou as capacity rationalization inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive sulfur supply insulates wet-process phosphoric acid margins from oil refining volatility. |
| Battery-Grade Purification Capacity Expansion | LFP cathode precursor demand in Jiangsu and Hunan provinces commands premium pricing pools. |
| Urban Mining Infrastructure Partnership | Ruhr region sewage sludge ash pilots extract secondary phosphate under EU Green Deal funding. |
| REACH-Compliant Reserve Acquisition | High-grade igneous apatite deposits bypass tightening EU cadmium contamination thresholds. |
| Direct OEM Cathode Supply Negotiations | South Korean and Japanese battery producers displace trader-mediated spot purchases. |
Study Parameters
Initial hypotheses were tested against primary input from phosphate plant managers, fertilizer procurement leads at Brazilian agricultural cooperatives, distribution channel partners in Indian state fertilizer networks, and battery cathode material R&D directors, then refined through customs trade data, OCP Group and Mosaic Company SEC filings, ECHA REACH registration databases, and MEE environmental inspection disclosures, with bottom-up capacity modeling triangulated against top-down demand aggregation across end-use segments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product grade tier, end-use industry spanning agriculture through lithium battery manufacturing, packaging format from bulk granular to electronic-grade liquid, and regional production hub concentration. CAGRs were derived from intensity-of-use coefficients applied to downstream sector growth projections, incorporating sulfuric acid price elasticity and LFP cathode chemistry adoption curves as phosphorus-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed purification specialists or accelerated EU circular economy mandate enforcement would shift outcomes beyond modeled ranges. Quarterly review of MEE inspection closure timelines, OCP Group export quota adjustments, and South Korean cathode producer direct contracting announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Sodium Bromate Market