
 Oxo Chemicals Market | 2026-2036
Oxo Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Oxo Chemicals Market Outlook
A capital-intensity divergence between integrated petrochemical giants and specialized oxo alcohol producers is redrawing competitive boundaries in this sector. BASF SE leverages its Ludwigshafen Verbund structure to sustain captive syngas and olefin supplies that insulate margin structures from feedstock volatility. Sasol anchors its position through Fischer-Tropsch integration into detergent-range alcohols, while OXEA GmbH specializes in C4-chemistry precision that larger commodity players rarely match.
Oxo chemicals comprise aldehydes and alcohols produced via hydroformylation of olefins with syngas, typically operating at 50-150 bar and 50-150°C with cobalt or rhodium catalysts, serving primarily as precursors for plasticizers, solvents, and surfactant intermediates. The butanol segment dominates volume flows given its entrenched role in acrylic esters and glycol ether production, though plasticizer-grade 2-ethylhexanol commands superior margin pools amid phthalate-transition dynamics. Hydrogenation technology leads process licensing activity as producers retrofit carbonylation trains to handle mixed C3-C4 feedslates and tighten carbon efficiency.
EPA New Source Performance Standards and REACH Annex XVII restrictions on nonylphenol ethoxylates are redirecting formulation R&D toward lower-toxicity oxo derivatives in coatings and cleaning applications. OSHA Process Safety Management requirements and EU Seveso III thresholds further constrain greenfield capacity siting, advantaging incumbents with permitted assets. Stakeholders must monitor feedstock-switching economics between shale-derived ethylene and refinery-based propylene streams to anticipate regional cost-curve shifts.
Market Dynamics
Feedstock-switching economics between shale-derived ethylene and refinery-based propylene streams are restructuring regional cost curves, forcing producers to recalibrate carbonylation train configurations and catalyst selection to maintain margin capture across volatile olefin spreads.
Growth Catalysts
- Plasticizer-grade 2-ethylhexanol demand:Coatings and adhesive formulators in China and India are absorbing expanding volumes as phthalate-transition dynamics accelerate specification shifts toward higher-purity oxo derivatives.
- REACH Annex XVII compliance:European formulators redirecting R&D spend toward lower-toxicity oxo derivatives creates specification premiums for producers with certified purity thresholds.
- Hydrogenation technology retrofits:Cobalt-to-rhodium catalyst conversions are tightening carbon efficiency and enabling mixed C3-C4 feedslate flexibility that insulates operations from single-olefin price spikes.
Market Restraints
- Syngas feedstock volatility:Natural gas price swings directly transmit to hydroformylation economics, compressing margin structures for non-integrated producers lacking captive synthesis gas supply.
- Seveso III siting constraints:EU threshold requirements for high-pressure carbonylation assets block greenfield capacity expansion in industrial clusters near population centers.
- Bio-based plasticizer substitution:Epoxidized soybean oil and citrate esters are capturing formulation share in flexible PVC applications, pressuring volume growth for traditional phthalate alternatives.
Strategic Opportunities
- India coatings sector expansion:Architectural and automotive refinish formulators are scaling butanol and propylene oxide derivative procurement as domestic manufacturing capacity ramps.
- EPA New Source Performance Standards:Tighter emissions mandates for solvent applications create first-mover advantages for producers with pre-certified low-VOC oxo alcohol product lines.
- Digital formulation platforms:AI-driven blend optimization tools are compressing customer technical service cycles and enabling remote specification matching that reduces sample shipment costs.
Industry Challenges
- Carbonylation catalyst supply security:Rhodium market concentration and geopolitical refining disruptions expose producers to procurement delays that can idle high-pressure trains for weeks.
- OSHA Process Safety Management audits:Compliance documentation for hydroformylation operations requires specialized process safety engineering talent that commands premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxo Chemicals Market |
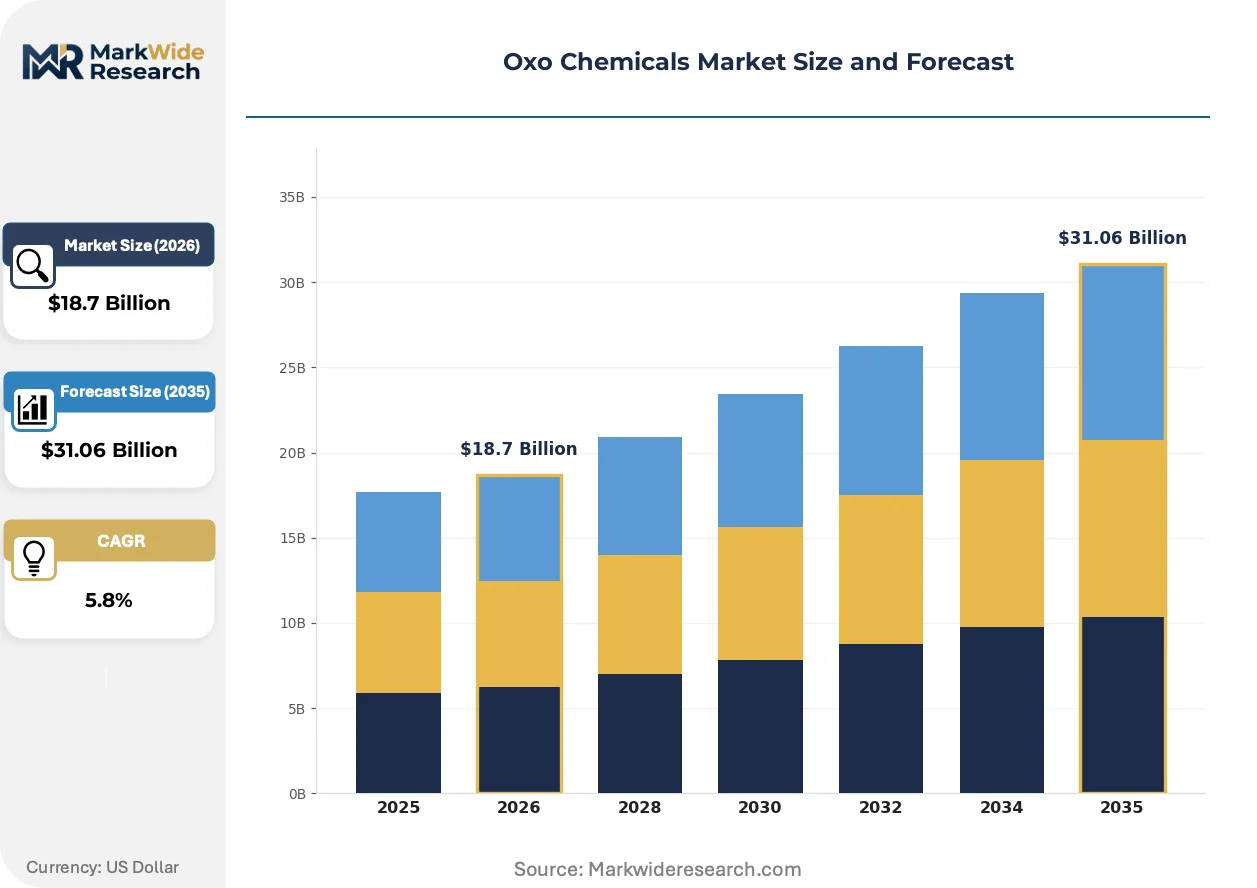
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
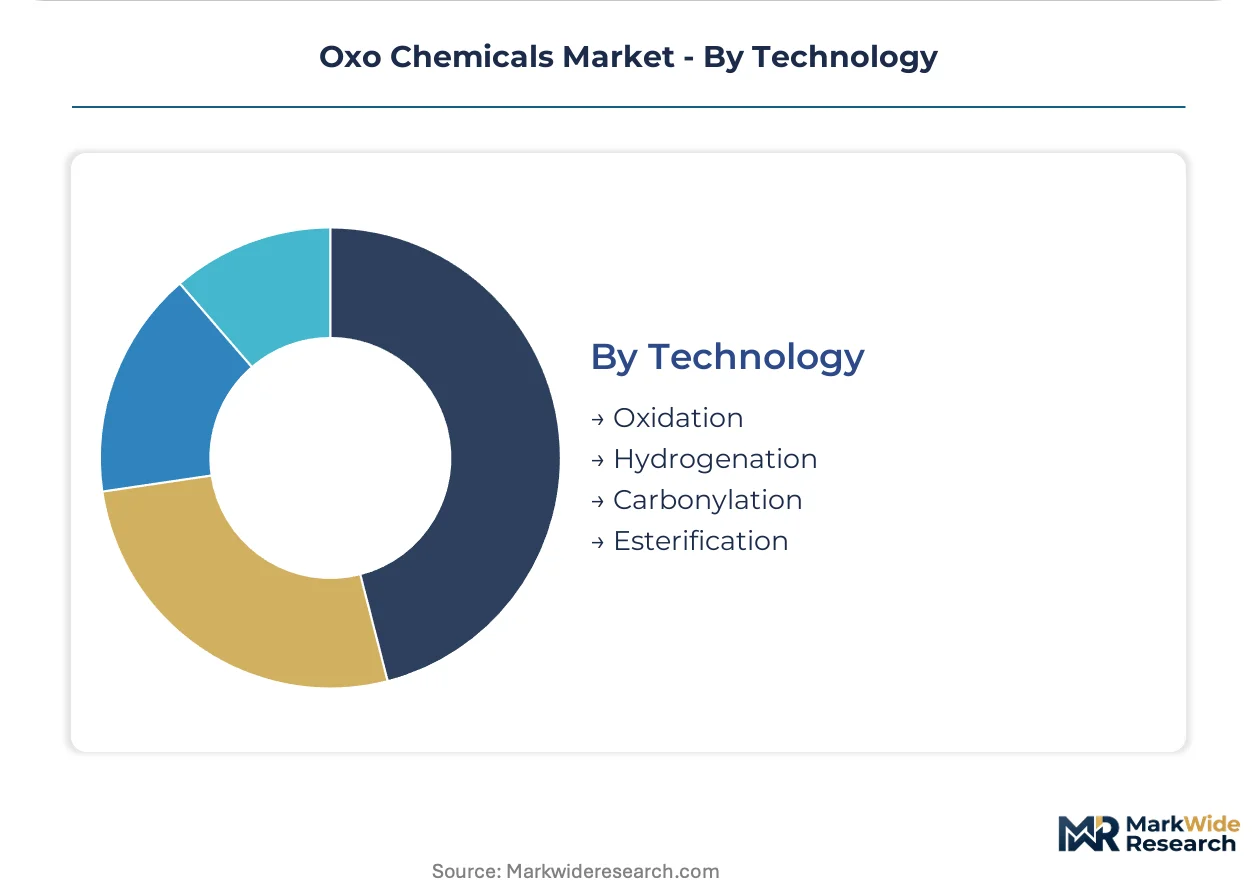
| Segmentation | Product Type: Propylene Oxide, Butanol, Nonylphenol, Butyric Acid End Use Industry: Plastics, Coatings, Adhesives, Lubricants Application: Solvents, Plasticizers, Intermediates, Additives Technology: Oxidation, Hydrogenation, Carbonylation, Esterification |
| Companies Covered | Eastman Chemical Company, LG Chem, BASF SE, Perstorp, OXEA GmbH, Dow Inc., Evonik Industries, Sasol, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxo Chemicals Market Strategic Shifts
Process intensification and regulatory specification tightening are converging to reward producers with integrated syngas capabilities and advanced catalyst management systems, while digital tools compress technical service delivery timelines.
Membrane-based syngas purification is displacing conventional cryogenic separation in new hydroformylation installations, cutting energy intensity by approximately one-third. Asian producers in South Korea and China are adopting this technology fastest, drawn by dual carbon goals compliance and operating cost reduction. The shift is compressing competitive differentiation around carbon footprint credentials rather than scale alone.
REACH restrictions on nonylphenol ethoxylates are forcing surfactant manufacturers toward C12-C14 oxo alcohol feedstocks that meet biodegradability thresholds. European formulators face reformulation timelines that compress supplier qualification windows to under eighteen months. Detergent-range alcohol producers with pre-certified product lines are capturing specification premiums that offset higher raw material costs.
Long-term offtake agreements are replacing spot-market procurement for plasticizer-grade alcohols as converters seek supply security amid olefin volatility. Major coatings manufacturers in Germany and the United States are locking in three-to-five-year contracts with fixed-price escalators. This behavior shift is concentrating volume with integrated producers who can underwrite capital commitments against guaranteed revenue streams.
Oxo Chemicals Market Segmentation
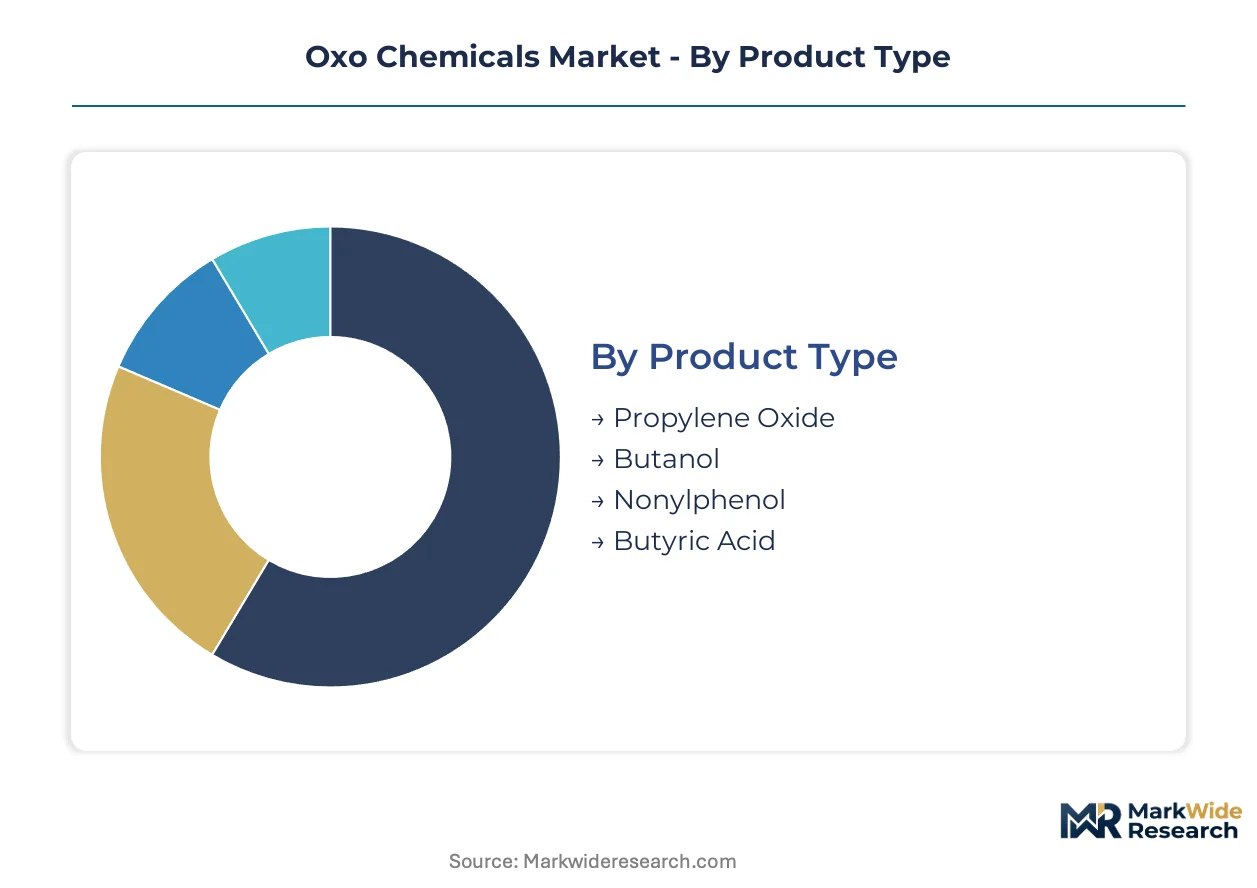
Oxo chemical value pools fragment across four distinct dimensions. Product chemistry determines feedstock exposure and margin volatility. End-use concentration in Asia-Pacific coatings and European plastics compliance regimes shapes regional demand asymmetries.
Product Type:
Domestic consumption in China and India absorbs expanding butanol volumes, while propylene oxide derivatives flow disproportionately into export markets serving European coatings formulators.
- Butanol:Four-carbon primary alcohol produced via propylene hydroformylation and subsequent hydrogenation. Indian coatings manufacturers are scaling procurement as architectural and automotive refinish capacity ramps, though phthalate-transition dynamics in Europe are compressing plasticizer-grade specifications.
- Propylene Oxide:Epoxide intermediate manufactured through chlorohydrin or direct oxidation routes. German and US coatings formulators are locking in long-term offtake agreements to secure supply amid olefin volatility, creating volume concentration with integrated producers.
- Nonylphenol:C9-alkylphenol feedstock for ethoxylate surfactant production facing REACH Annex XVII biodegradability constraints.
- Butyric Acid:Short-chain carboxylic acid serving flavor, fragrance, and animal nutrition applications with limited oxo-process overlap.
Butanol commands the established base. The steepest expansion runs through propylene oxide derivatives.
End Use Industry:
Cost-tier stratification separates specification-critical applications from commodity volume plays.
- Plastics:Flexible PVC compounding and plasticizer integration. REACH compliance deadlines are forcing European converters toward certified low-toxicity 2-ethylhexanol grades that command specification premiums.
- Coatings:Architectural, automotive, and industrial finishes. Chinese and Indian formulators are absorbing expanding butanol and propylene oxide derivative volumes as domestic manufacturing capacity scales.
- Adhesives:Pressure-sensitive and structural bonding formulations requiring solvent-grade alcohol purity.
- Lubricants:Synthetic base stock and additive intermediate applications with stringent viscosity index requirements.
Plastics maintains volume leadership. Coatings is gaining share fastest on Asia-Pacific capacity expansion.
Application:
Customer-type bifurcation separates process solvent buyers from formulation-integrated consumers.
- Plasticizers:Phthalate and non-phthalate alternatives for flexible PVC. Bio-based substitution via epoxidized soybean oil is pressuring volume growth in consumer-facing applications.
- Solvents:Coating and cleaning formulation carriers. EPA New Source Performance Standards are redirecting procurement toward pre-certified low-VOC oxo alcohol lines.
- Intermediates:Acrylic ester and glycol ether precursors for downstream chemical synthesis.
- Additives:Lubricant and fuel performance enhancement compounds.
Solvents anchor current procurement volumes. Plasticizers face the steepest specification disruption from regulatory transition dynamics.
Technology:
Process maturity curves separate legacy asset bases from retrofit-intensive modernization programs.
- Carbonylation:Hydroformylation of olefins with syngas at 50-150 bar pressure. Cobalt-to-rhodium catalyst conversions are tightening carbon efficiency and enabling mixed C3-C4 feedslate flexibility.
- Hydrogenation:Aldehyde reduction to alcohol products. This technology leads process licensing activity as producers retrofit trains to handle variable feed compositions.
- Oxidation:Direct olefin epoxidation or alcohol oxidation routes with higher energy intensity profiles.
- Esterification:Acid-alcohol condensation for plasticizer and solvent ester production, typically downstream of oxo alcohol units.
Carbonylation underpins installed capacity. Hydrogenation retrofits represent the steepest expansion trajectory in technology licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese coatings formulators consume butanol and propylene oxide derivatives at scale for architectural and automotive refinish applications, whereas European demand tilts toward certified low-toxicity 2-ethylhexanol grades for REACH-compliant plasticizer formulations.
China
Domestic architectural coatings manufacturers in Jiangsu and Zhejiang provinces are scaling butanol procurement as construction activity sustains. MEE enforcement of dual carbon goals is accelerating membrane-based syngas purification retrofits. The Yangtze River Delta cluster around Nanjing hosts expanding hydrogenation technology licensing activity for mixed C3-C4 feedslate flexibility.
United States
Gulf Coast refiners are recalibrating carbonylation trains to exploit shale-derived ethylene economics versus refinery propylene. EPA New Source Performance Standards for solvent applications are redirecting procurement toward pre-certified low-VOC oxo alcohol lines. The Houston Ship Channel concentration of integrated petrochemical assets sustains captive syngas supply advantages.
Germany
Ludwigshafen and Marl industrial complexes anchor European detergent-range alcohol production with Fischer-Tropsch integration. REACH Annex XVII restrictions on nonylphenol ethoxylates are compressing supplier qualification windows to under eighteen months. BASF SE's Verbund structure insulates margin structures from natural gas price volatility through captive olefin supplies.
India
Maharashtra and Gujarat coatings manufacturers are absorbing expanding butanol volumes as domestic automotive refinish capacity ramps. BIS certification requirements for solvent-grade purity are tightening specification thresholds. The Dahej PCPIR chemical cluster in Gujarat is attracting hydrogenation technology retrofits for plasticizer-grade alcohol production.
South Korea
Ulsan-based petrochemical complexes are adopting membrane-based syngas purification fastest among Asian producers. MFDS oversight of chemical manufacturing safety is elevating documentation burdens for hydroformylation operations. Yeosu National Industrial Complex concentration of carbonylation assets enables mixed feedslate optimization against volatile olefin spreads.
Oxo Chemicals Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on C4-chemistry precision and certification-grade purity. The upper tier commands margin insulation through captive syngas and olefin supplies, while specialists capture specification premiums in REACH-compliant and low-VOC product lines. Two archetypes dominate: diversified petrochemical conglomerates with Verbund or Fischer-Tropsch integration, and focused oxo alcohol producers with hydrogenation technology licensing depth. Competitive moves concentrate on cobalt-to-rhodium catalyst conversions and long-term offtake agreements with coatings manufacturers.
Among German-integrated conglomerates, BASF SE and Evonik Industries occupy positions that exemplify the Verbund-integrated archetype, while OXEA GmbH represents the specialized C4-chemistry precision tier that larger commodity players rarely match. These three anchors illustrate how capital-intensity divergence redraws competitive boundaries between scale-driven upstream control and specification-critical downstream formulation support.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| LG Chem |
| BASF SE |
| Perstorp |
| OXEA GmbH |
| Dow Inc. |
| Evonik Industries |
| Sasol |
| ExxonMobil Chemical |
| Others |
Value Chain & Pricing Dynamics
Cobalt-to-rhodium catalyst conversions are redrawing procurement economics as producers retrofit carbonylation trains, simultaneously compressing supply geography toward technology licensors in Germany and South Korea while elevating pricing premiums for certified low-carbon efficiency grades.
Pricing Analysis
Long-term offtake agreements dominate volume flows as coatings manufacturers in Germany and the United States lock in three-to-five-year contracts with fixed-price escalators. Price differentiation separates REACH-certified low-toxicity grades from standard solvent-tier products, with specification premiums widening amid compressed supplier qualification windows. Pricing pressure stems from bio-based plasticizer substitution via epoxidized soybean oil in flexible PVC applications. Spot-market buyers in commodity plasticizer segments exhibit highest price sensitivity, while integrated producers with captive syngas supply capture margin insulation.
Supply Chain Analysis
Strategic stockpiling of rhodium catalyst precursors characterizes risk management as producers buffer against procurement delays from concentrated refining sources. Supply concentrates in China, Germany, and the United States, with the Yangtze River Delta and Gulf Coast clusters anchoring hydrogenation technology deployment. Raw material dependencies center on natural gas for syngas generation, olefin feedstocks from shale or refinery streams, and cobalt or rhodium catalyst metals. Single-source vulnerability in rhodium supply exposes high-pressure trains to weeks-long idling. Distribution runs through long-term direct contracts with coatings formulators and plastics compounders rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory specification fragmentation across REACH, EPA, and BIS jurisdictions is multiplying addressable niches for certified-grade producers. Demand-side bifurcation between commodity volume and premium purity tiers rewards focused positioning.
For Market Incumbents: Shield margin structures through captive syngas supply investments in permitted industrial clusters near the Houston Ship Channel or Ludwigshafen. Accelerate cobalt-to-rhodium conversions to tighten carbon efficiency credentials before competitor retrofits saturate certification windows. Long-term offtake anchoring with automotive refinish formulators in India provides volume underwriting against bio-based substitution pressure in European plasticizer segments.
For New Entrants and Emerging Players: REACH Annex XVII fast-track certification for C12-C14 detergent-range alcohols opens specification-premium capture in surfactant reformulation timelines compressed under eighteen months. Target Indian coatings sector expansion in Maharashtra and Gujarat, where BIS purity requirements are tightening faster than domestic supply response. Go-to-market leverage rests on digital formulation platforms that compress technical service cycles for architectural coatings manufacturers scaling procurement.
For Investors and Strategic Acquirers: The market sits at a technology-retrofit phase that favors hydrogenation technology licensors with mixed C3-C4 feedslate flexibility. Long-term viability over the next decade hinges on carbon efficiency credentials rather than scale alone. Acquisition focus should center on specialized C4-chemistry producers with pre-certified low-VOC product lines. Watch membrane-based syngas purification adoption rates in South Korea and China as inflection signals for competitive differentiation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Syngas | BASF's Ludwigshafen Verbund structure insulates margins from natural gas volatility through in-house synthesis gas production. |
| Hydrogenation Technology Retrofit | Cobalt-to-rhodium conversions enable mixed C3-C4 feedslate flexibility that protects operations against single-olefin price spikes. |
| REACH Certification Fast-Track | Pre-certified low-toxicity grades capture specification premiums as European formulators face compressed eighteen-month qualification windows. |
| Long-Term Supply Agreement | German coatings manufacturers are locking in three-to-five-year contracts with fixed-price escalators to secure supply amid olefin volatility. |
| Digital Formulation Platform Deployment | AI-driven blend optimization tools reduce sample shipment costs for coatings manufacturers scaling butanol procurement in India. |
Study Parameters
A standing panel of plant managers at hydroformylation facilities, procurement leads at downstream coatings OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration throughout the study. Primary interviews with these stakeholders were cross-validated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and national chemical safety regulator disclosures. Bottom-up volume modeling across product chemistry tiers was triangulated with top-down demand aggregation from end-use industry consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product chemistry type, end-use industry concentration, application function, and regional production hub configuration. CAGRs were derived from fitted growth curves anchored to base-year market sizing and projected demand trajectories. Industry-specific forecast inputs incorporated olefin feedstock switching economics and regulatory compliance timeline acceleration.
Decision-makers should treat outputs as directional under assumptions of sustained coatings sector expansion in China and India and stable rhodium catalyst supply channels; material deviation would warrant model refresh. Forecasts reflect these base assumptions regarding shale-derived ethylene competitiveness and REACH enforcement intensity. Revision becomes warranted when bio-based plasticizer substitution rates or membrane-based syngas purification adoption thresholds cross materiality levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Asia-Pacific Synthetic Camphor Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
1,3-Dioxolane Market