
 Bulk Molding Compounds Market | 2026-2036
Bulk Molding Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Molding Compounds Market Outlook
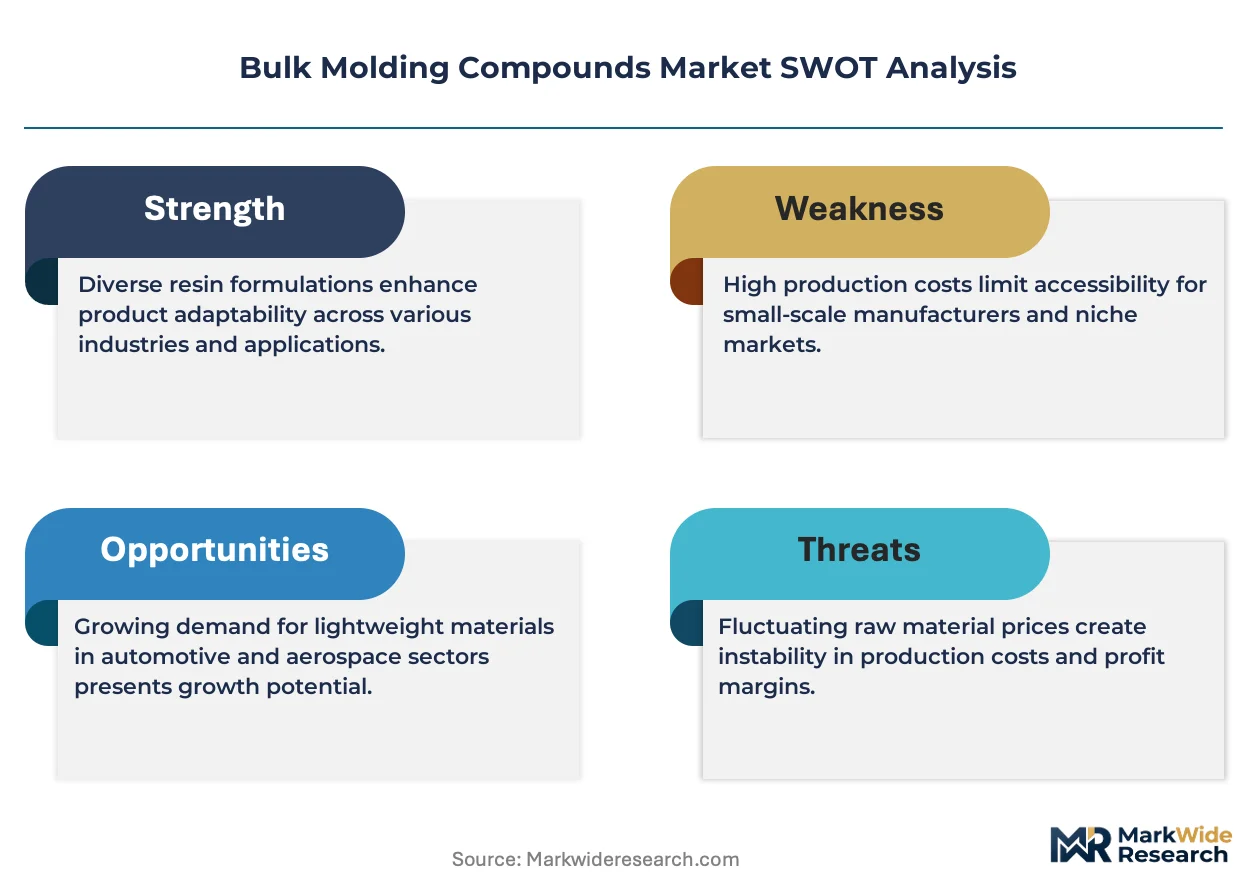
Glass fiber-reinforced polyester is repositioning bulk molding compounds as a cost-competitive alternative to die-cast aluminum in automotive under-hood applications. IDI Composites International leverages its North American manufacturing footprint to supply heat-resistant grades directly to Detroit-based automakers. Toray Advanced Composites sustains technology leadership through continuous fiber-reinforced formulations that extend performance boundaries for structural components. Polynt Group anchors European supply with integrated resin production that controls raw material quality and cost positions.
Bulk molding compounds are fiber-reinforced thermoset molding materials formulated from unsaturated polyester, vinyl ester, or epoxy resins blended with mineral fillers and glass fibers typically at 15-25% loading by weight, designed for injection or compression molding into complex shapes with high strength-to-weight ratios and Class A surface finishes. Thermosetting compounds dominate volume consumption due to their dimensional stability under thermal cycling and chemical exposure in automotive powertrain environments. Electrical insulation applications within the electrical and electronics end user industry represent the fastest-expanding demand pool as OEMs specify flame-retardant BMC for EV battery housings and charging infrastructure components where UL 94 V-0 ratings are mandatory.
EPA regulations under the Toxic Substances Control Act restrict certain styrene emissions during BMC compounding, compelling processors to invest in closed-loop manufacturing systems. REACH registration requirements in Europe govern the chemical composition of phenolic and epoxy resin precursors, directly affecting import eligibility and formulation costs for non-EU suppliers. China's GB standards for automotive materials, administered by SAMR, mandate specific flammability and smoke-density thresholds that shape product development priorities for domestic and export-oriented compounders. Stakeholders must monitor evolving EV platform architectures and regional carbon-border adjustment mechanisms to align capacity investments with the next generation of thermoset material specifications.
Market Dynamics
Automotive electrification is compressing design cycles for under-hood components, forcing compounders to synchronize formulation development with platform launches rather than traditional model-year refresh schedules. Tier-one suppliers now specify thermoset grades 18-24 months ahead of production ramp.
Growth Catalysts
- Metal substitution mandates:OEMs in Germany and China specify glass fiber-reinforced BMC for engine covers and battery trays to achieve 15-20% mass reduction versus die-cast aluminum.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbons is accelerating adoption of thermoset composites in HVAC housings and thermal management systems.
- EV charging infrastructure buildout:UL 94 V-0 rated compounds are capturing sockets, enclosures, and connector bodies across North American and European utility deployments.
Market Restraints
- Styrene price volatility:Unsaturated polyester resin feedstock costs swing with benzene and ethylene spot markets, compressing compounding margins unpredictably.
- Tooling capex intensity:Compression and injection molds for BMC require hardened steel cavities with 250,000+ shot durability, deterring mid-volume program entry.
- Thermoplastic substitution:Long-fiber reinforced polypropylene from compounders in Germany challenges BMC in non-structural automotive panels where heat resistance thresholds are lower.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced chemistry cell manufacturing are creating parallel demand for flame-retardant electrical housings in domestic EV supply chains.
- Wind energy nacelle components:Vinyl ester BMC grades are penetrating pitch control housings and transformer enclosures as turbine OEMs seek corrosion-resistant alternatives to painted steel.
- Closed-loop recycling:Pyrolysis and solvolysis routes for thermoset composite recovery are opening circular material claims for sustainability-scored procurement tenders in the Netherlands and California.
Industry Challenges
- Formulation chemist scarcity:Expertise in unsaturated polyester and vinyl ester cure kinetics is concentrating at retiring technical staff levels without adequate university pipeline replacement.
- REACH compliance latency:Registration dossier preparation for novel phenolic resin precursors extends 18-36 months, delaying European market entry for Asian compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Molding Compounds Market |
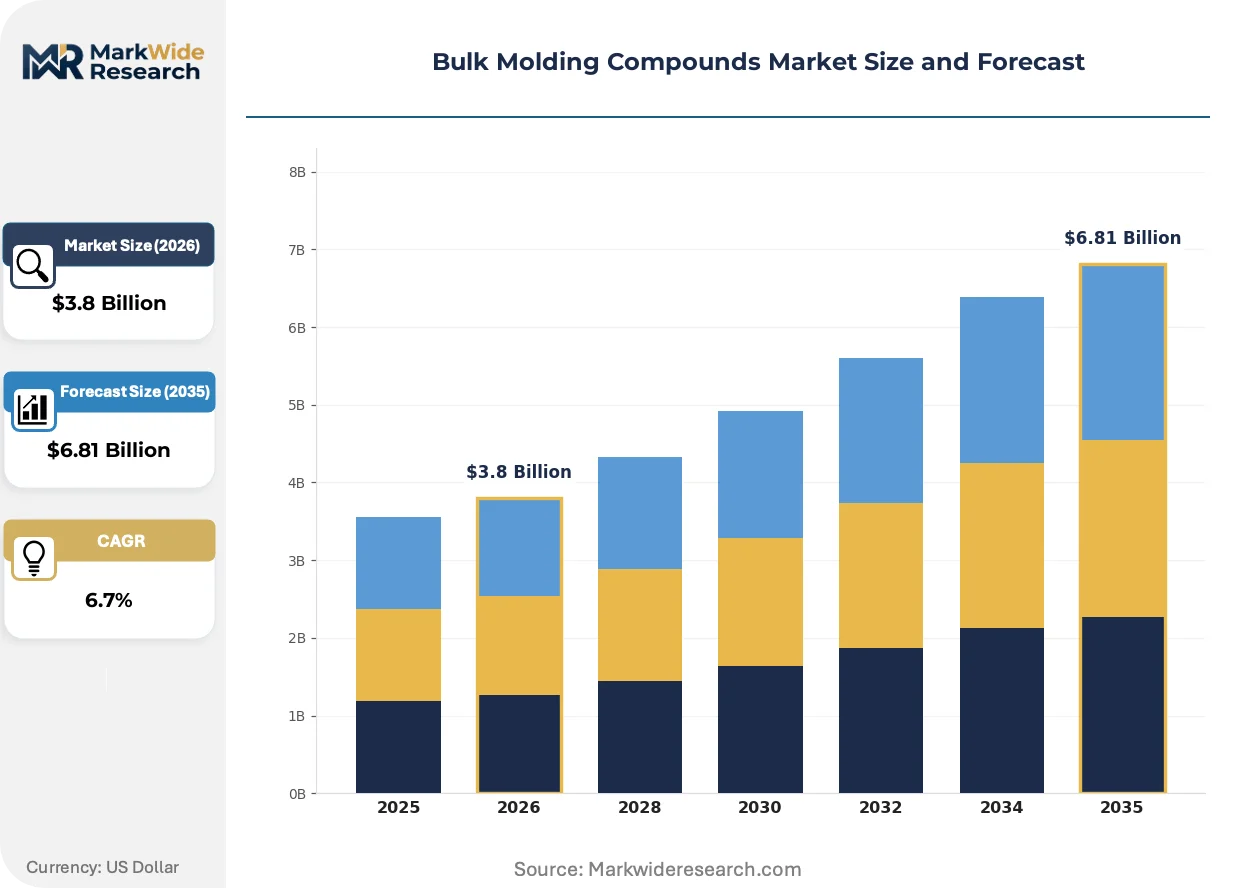
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Compounds, Unsaturated Polyester, Epoxy Resin, Phenolic Resin End User Industry: Automotive, Electrical & Electronics, Consumer Goods, Aerospace Application: Electrical Insulation, Structural Components, Thermal Management, Surface Finishing Distribution Channel: Direct Sales, Distributors, Online Sales, Third-party Retailers |
| Companies Covered | IDI Composites International, Toray Advanced Composites, Polynt Group, Core Molding Technologies, Menzolit, Mar-Bal, LyondellBasell, Huayuan Advanced Materials, Lorenz Kunststofftechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Molding Compounds Market Strategic Shifts
Material informatics and automated compounding controls are collapsing development timelines from 24 months to under 12 months. This acceleration is redrawing competitive boundaries between established resin houses and specialized compounders.
Hybrid fiber architectures combining chopped glass with recycled carbon fiber are modularizing BMC property sets. Tier-one automotive suppliers in Stuttgart and Detroit are qualifying these grades for structural brackets where load paths are complex. The approach is compressing the traditional trade-off between cost and mechanical performance that has segmented thermoset markets.
REACH authorization requirements for diisocyanates are tightening handling protocols across European compounding facilities. Processors must implement mandatory worker training and exposure monitoring by ECHA deadlines. Small and mid-scale compounders in Italy and Poland are consolidating tolling relationships to share compliance infrastructure costs.
Specification-driven procurement is replacing spot purchasing for automotive BMC programs. OEMs in Michigan and Bavaria now lock resin formulations 36 months ahead of SOP through single-source agreements with penalty clauses for specification drift. This behavioral shift is concentrating volume at compounders with captive resin production and certified laboratory networks.
Bulk Molding Compounds Market Segmentation
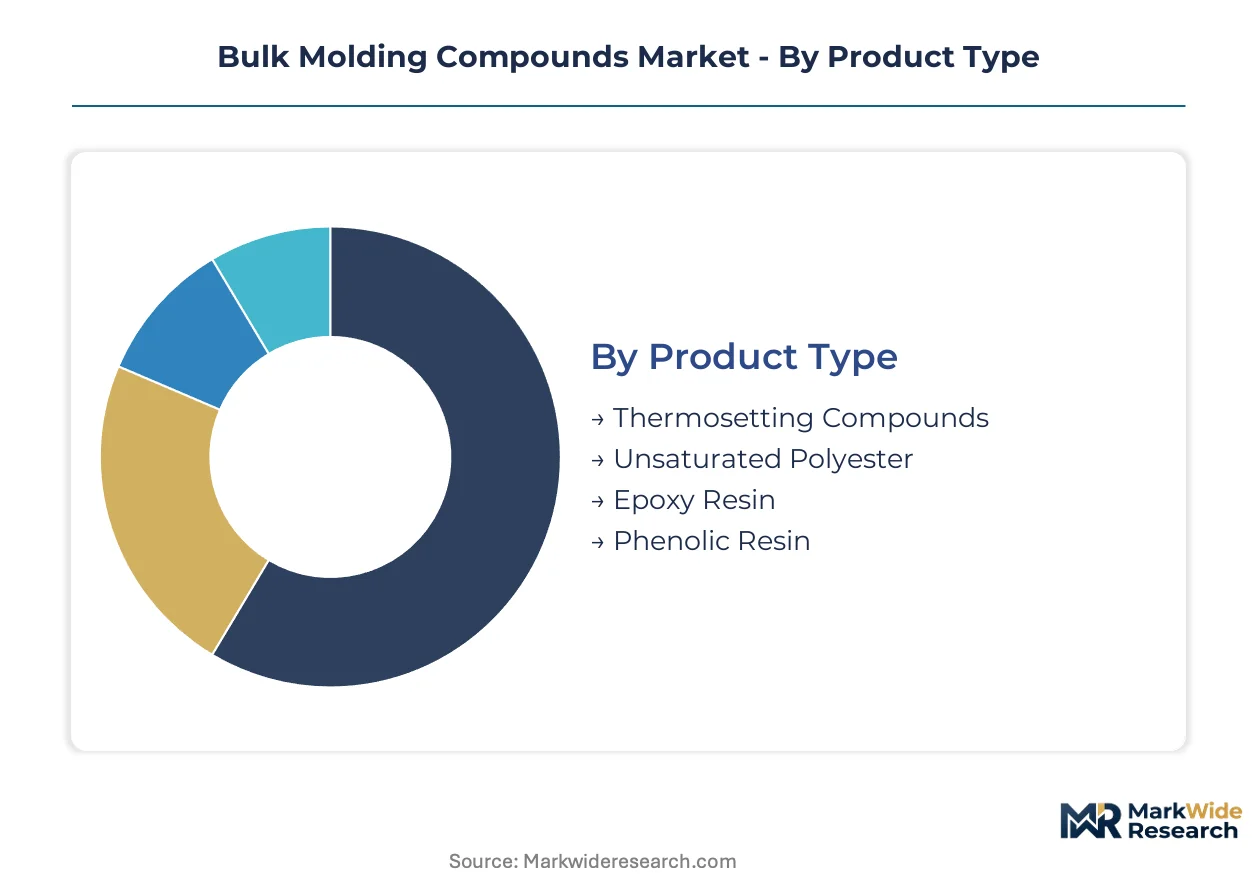
Segmentation reveals how material specifications, end-use requirements, and channel economics partition the bulk molding compounds landscape. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Supply concentration clusters around resin systems with captive precursor production and established automotive qualification pathways.
- Thermosetting Compounds:These cross-linked formulations deliver dimensional stability under thermal cycling and chemical exposure. Automotive powertrain applications in Germany and the United States absorb the majority of volume, driven by metal substitution mandates for under-hood components. OEMs specify these grades 18-24 months ahead of production ramp.
- Unsaturated Polyester:The dominant chemistry relies on styrene monomer blended with mineral fillers and chopped glass fiber at 15-25% loading. Price volatility in benzene and ethylene feedstocks compresses compounding margins unpredictably, forcing processors toward long-term supply agreements.
- Epoxy Resin:Higher-performance systems command premium positioning in electrical insulation and structural applications requiring elevated temperature resistance.
- Phenolic Resin:Flame-retardant grades serve EV battery housings and charging infrastructure where UL 94 V-0 ratings are mandatory.
Thermosetting compounds absorb the bulk of installed capacity; phenolic resin formulations are expanding most quickly.
End User Industry:
Cost tier segmentation separates specification-intensive automotive programs from price-sensitive consumer goods applications.
- Automotive:Under-hood components, electrical housings, and battery trays dominate consumption as OEMs pursue 15-20% mass reduction versus die-cast aluminum. Detroit-based and Stuttgart-based manufacturers lock formulations 36 months ahead of SOP through single-source agreements.
- Electrical & Electronics:EV charging infrastructure buildout across North American and European utility deployments drives sockets, enclosures, and connector bodies. UL 94 V-0 rated compounds are capturing this demand pool fastest.
- Consumer Goods:Appliance housings and kitchenware applications prioritize surface finish and color stability over mechanical performance.
- Aerospace:Niche specifications for interior components and secondary structures require extensive qualification cycles that limit supplier participation.
Automotive absorbs the bulk of installed capacity; electrical & electronics is climbing the fastest.
Application:
Volume concentration tracks toward functional requirements that BMC uniquely satisfies versus competing thermoplastics and metals.
- Electrical Insulation:Flame-retardant grades for EV battery housings, charging infrastructure, and transformer enclosures represent the steepest expansion trajectory. UL 94 V-0 ratings are mandatory across North American and European deployments.
- Structural Components:Hybrid fiber architectures combining chopped glass with recycled carbon fiber are modularizing property sets for complex load paths. Tier-one suppliers in Stuttgart and Detroit are qualifying these grades for brackets.
- Thermal Management:HVAC housings and powertrain heat shields leverage dimensional stability under cyclic temperature exposure.
- Surface Finishing:Class A finishes for visible automotive and consumer goods panels require specialized mold design and processing controls.
Electrical insulation absorbs the bulk of installed capacity; structural components are gaining share fastest.
Distribution Channel:
Customer type segmentation distinguishes integrated OEM supply chains from fragmented aftermarket and MRO procurement.
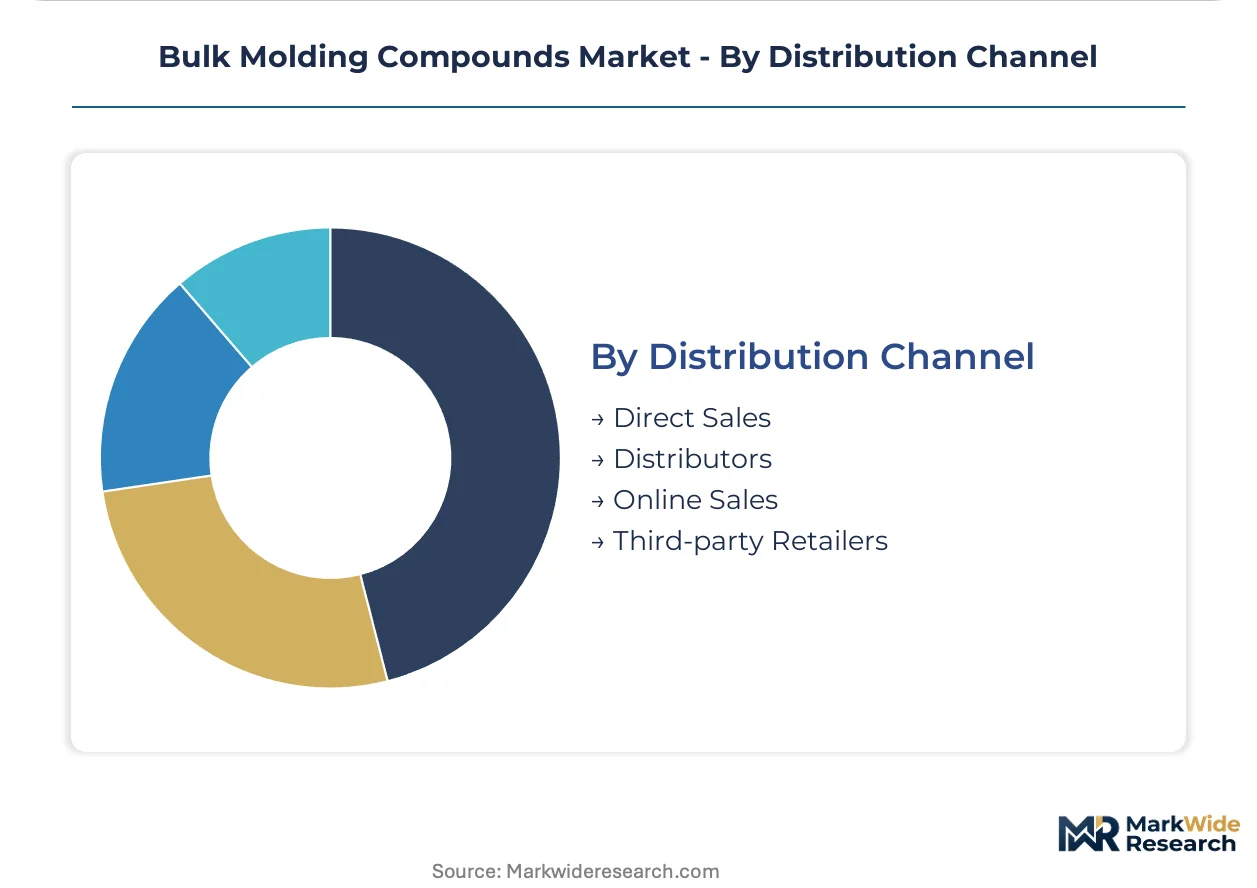
- Direct Sales:Tier-one automotive suppliers and electrical OEMs negotiate single-source agreements with penalty clauses for specification drift. Compounders with captive resin production and certified laboratory networks concentrate volume here.
- Distributors:Regional stocking locations support just-in-time supply to mid-volume processors without qualification overhead for direct relationships.
- Online Sales:Emerging channel for standard grades and technical documentation serving R&D procurement and small-batch production.
- Third-party Retailers:Limited penetration given the technical specification requirements and formulation customization typical of BMC procurement.
Direct sales absorb the bulk of installed capacity; online sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for advanced chemistry cell manufacturing is concentrating investment in flame-retardant electrical housings for domestic EV supply chains.
Germany
Automotive OEMs in Stuttgart and Munich specify glass fiber-reinforced BMC for engine covers and battery trays to achieve mass reduction targets. REACH registration requirements govern chemical composition of phenolic and epoxy resin precursors, extending dossier preparation timelines. Industrial clusters in Baden-Württemberg host compounding facilities that supply tier-one suppliers through just-in-time agreements.
China
Domestic compounding capacity supports EV battery housing and charging infrastructure component production for both local and export markets. GB standards administered by SAMR mandate specific flammability and smoke-density thresholds for automotive materials. Yangtze River Delta manufacturing hubs concentrate formulation development aligned with next-generation thermoset specifications.
United States
Detroit-based automakers lock BMC formulations 36 months ahead of production start through single-source agreements with penalty clauses. EPA regulations under the Toxic Substances Control Act restrict styrene emissions during compounding, compelling investment in closed-loop manufacturing systems. Michigan industrial corridors concentrate direct supply relationships with heat-resistant grade specialists.
India
PLI scheme incentives for advanced chemistry cell manufacturing generate parallel demand for flame-retardant electrical housings in domestic EV supply chains. BIS certification requirements shape product development priorities for compounders targeting automotive qualification. Maharashtra and Gujarat industrial zones concentrate emerging compounding capacity to serve localized tier-one supplier networks.
Netherlands
Sustainability-scored procurement tenders prioritize circular material claims from pyrolysis and solvolysis recovery routes for thermoset composites. ECHA authorization requirements for diisocyanates tighten handling protocols across compounding facilities with mandatory worker training deadlines. Rotterdam-area chemical clusters concentrate tolling relationships that share compliance infrastructure costs among mid-scale processors.
Bulk Molding Compounds Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with specification-intensive automotive programs concentrating volume at integrated resin houses while electrical applications support more fragmented supplier participation. The vendor base organizes around three strategic archetypes: captive resin producers controlling raw material quality and cost positions, specialized compounders with certified laboratory networks, and tolling operators sharing compliance infrastructure. Consolidation pressure is accelerating among mid-scale European compounders facing REACH compliance latency, while Asian manufacturers pursue qualification pathways for North American and European automotive programs.
Among North American integrated manufacturers, IDI Composites International occupies a position exemplifying the captive production archetype with direct supply relationships to Detroit-based OEMs. Toray Advanced Composites represents the technology leadership tier through continuous fiber-reinforced formulations. Polynt Group anchors European supply structures with backward integration into resin production that controls formulation cost positions across automotive and electrical segments.
| Leading Market Players |
|---|
| IDI Composites International |
| Toray Advanced Composites |
| Polynt Group |
| Core Molding Technologies |
| Menzolit |
| Mar-Bal |
| LyondellBasell |
| Huayuan Advanced Materials |
| Lorenz Kunststofftechnik |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive suppliers in Detroit and Stuttgart lock formulations through single-source agreements that compress pricing power toward compounders with captive resin production. This buyer concentration forces a contract-based long-term offtake model where specification drift penalties and 36-month lead-time commitments dominate spot-market alternatives.
Pricing Analysis
Short lead-time premiums attach to heat-resistant grades for platform launches where OEMs synchronize compounding with 18-24 month production ramps. Three-tier pricing structure across automotive-qualified, electrical-grade, and standard industrial levels separates UL 94 V-0 certified compounds from uncertified alternatives. Cost compression in unsaturated polyester feedstocks runs through benzene and ethylene spot volatility, squeezing mid-scale compounders without backward integration. Consumer goods applications show highest price sensitivity where surface finish requirements yield to polypropylene substitution.
Supply Chain Analysis
Dual-sourcing requirements from Detroit-based automakers and European tier-one suppliers mandate multi-supplier qualification for critical under-hood components. Manufacturing concentrates in Germany, China, and the United States where domestic compounding supports just-in-time delivery. Feedstock dependencies on styrene monomer, glass fiber rovings, and phenolic resin precursors tether margins to petrochemical and minerals markets. Single-source vulnerability in specialized cure kinetics expertise compounds formulation chemist scarcity. Distribution runs through direct sales relationships with certified laboratory networks rather than fragmented distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance latency and formulation chemist scarcity are forcing consolidation among mid-scale European compounders without captive infrastructure. Weaker players face exit pressure as qualification timelines extend and specification-driven procurement concentrates volume.
For Market Incumbents: Deploy backward integration into phenolic and vinyl ester resin precursors to secure formulation cost positions against Asian import competition. Capture tier-one automotive programs through certified laboratory networks that accelerate 18-24 month qualification cycles. Lock single-source agreements with 36-month lead times before emerging compounders achieve UL 94 V-0 certification for EV battery housings. For New Entrants and Emerging Players: Launch via tolling partnerships with established European compounders facing REACH compliance infrastructure costs. Target India's PLI-driven advanced chemistry cell supply chain where flame-retardant electrical housing demand outpaces domestic qualification capacity. Penetrate wind energy nacelle components through vinyl ester BMC grades for pitch control housings where corrosion resistance specifications remain under-supplied. For Investors and Strategic Acquirers: The window for entry favors mid-scale European compounders with REACH dossier preparation underway and established automotive qualification pathways. Long-term viability hinges on captive resin production and certified laboratory networks that concentrate tier-one procurement. Watch for pyrolysis and solvolysis recovery route commercialization in the Netherlands and California as circular material claims reshape sustainability-scored procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursors | Captive phenolic and vinyl ester production secures formulation cost positions against feedstock volatility. |
| Certified Laboratory Network Expansion | UL 94 V-0 and REACH dossier capabilities accelerate tier-one automotive and electrical qualification timelines. |
| Long-term Supply Agreement Lock-in | Single-source contracts with 36-month lead times concentrate volume before emerging competitors achieve certification. |
| Closed-loop Manufacturing Investment | EPA-compliant styrene emission controls maintain access to Detroit-based automaker procurement programs. |
| Circular Material Recovery Partnership | Pyrolysis and solvolysis routes open sustainability-scored tenders in Dutch and California procurement. |
Study Parameters
Trade databases, chemical industry association filings, and automotive production records formed the secondary backbone for volume and value estimation. Primary interviews with BMC plant managers, procurement leads at Detroit and Stuttgart tier-one suppliers, distribution channel partners, and technical R&D directors at resin houses validated formulation trends and qualification timelines. Bottom-up segment modeling across resin chemistry, end-use industry, and application combined with top-down macroeconomic triangulation to anchor projections.
Historical trendline analysis of automotive metal substitution rates and electrical infrastructure buildout patterns established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include resin system tier, end-use industry vertical, functional application, and regional production hub clustering. CAGRs derived from fitted trend extrapolation adjusted for regulatory phase-in schedules and platform launch cadences specific to EV battery housing and charging infrastructure deployment.
REACH authorization delays, styrene feedstock price spikes, and thermoplastic substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts embed assumptions around regulatory compliance timelines and OEM platform standardization trajectories. Deviation in EU F-Gas Regulation phase-down speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Ground Calcium Carbonate Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market