
 Bleached Softwood Kraft Pulp Market | 2026-2036
Bleached Softwood Kraft Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Bleached Softwood Kraft Pulp Market Outlook
Scandinavian mill complexes is broadening the availability of elemental chlorine-free grades for European tissue manufacturers. Suzano leverages its integrated eucalyptus and softwood platform to secure long-term supply contracts with Asian converters. Metsä Fibre anchors its competitive position through bioproduct mill architecture that captures side-stream value from kraft pulping. UPM-Kymmene competes on delivery reliability to Central European printing houses through rail-linked logistics networks.
Bleached softwood kraft pulp is a chemically processed virgin fiber derived from coniferous species, cooked under alkaline conditions and bleached to brightness levels exceeding 88% ISO for premium paper grades. Its long, intact cellulose fibers deliver tensile strength and runnability critical to high-speed tissue and specialty packaging machines. Chemical pulp commands the dominant value share among product types due to its superior purity and strength relative to mechanical or recycled alternatives. Tissue paper represents the fastest-expanding application channel as consumer hygiene standards rise in emerging economies. The packaging end-use industry captures expanding margin pools as brand owners substitute plastic with fiber-based barriers.
The EU Deforestation Regulation requires geolocation traceability for all pulp entering European conversion facilities, reshaping supplier certification requirements. China's SAMR enforces GB standards on imported bleached pulp brightness and residual chemical limits at port of entry, filtering non-compliant shipments. EPA effluent guidelines in the United States constrain kraft mill bleaching sequences, pushing capital investment toward oxygen delignification and chlorine dioxide substitution. Stakeholders must monitor regulatory divergence across these three jurisdictions when qualifying supply sources and planning capacity additions.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing bleached softwood kraft pulp suppliers to rebuild certification infrastructure around geolocation verification, compressing procurement timelines for European tissue converters and packaging houses.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation documentation for all fiber entering European conversion facilities creates certified supply premiums for compliant Scandinavian and Baltic producers.
- Tissue and hygiene demand:Southeast Asian consumer markets are absorbing record volumes of long-fiber virgin pulp for premium toilet tissue and facial tissue production.
- Plastic substitution mandates:Brand-owner commitments to fiber-based food-contact packaging are pulling high-strength bleached softwood kraft into barrier-coated paperboard applications.
Market Restraints
- Energy cost volatility:Nordic and Baltic mills face structurally higher electricity and natural gas input costs versus South American integrated pulp-paper-power complexes.
- Supply concentration:Brazilian eucalyptus-softwood integrated platforms control disproportionate share of seaborne trade, creating single-source vulnerability for Asian converters.
- Mechanical pulp substitution:Thermomechanical and chemithermomechanical grades with improved strength profiles are capturing volume in lower-brightness packaging segments.
Strategic Opportunities
- Indonesian tissue expansion:Domestic hygiene paper capacity builds are outpacing local hardwood pulp supply, opening import windows for bleached softwood kraft with superior tensile properties.
- Bioproduct mill architecture:Side-stream valorization from lignin, tall oil, and turpentine extraction is converging with carbon-negative fuel substitution to improve mill economics.
- China GB standard compliance:Stricter port-of-entry testing for residual chemical limits and brightness specifications is filtering out marginal suppliers, creating share gains for certified Nordic and North American producers.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous compliance with EU Deforestation Regulation geolocation rules, FSC/PEFC chain-of-custody, and China SAMR GB testing protocols stretches quality assurance teams.
- Oxygen delignification capex cycles:EPA effluent guideline compliance in the United States requires capital-intensive brownstock washing and extended delignification sequences, extending payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleached Softwood Kraft Pulp Market |
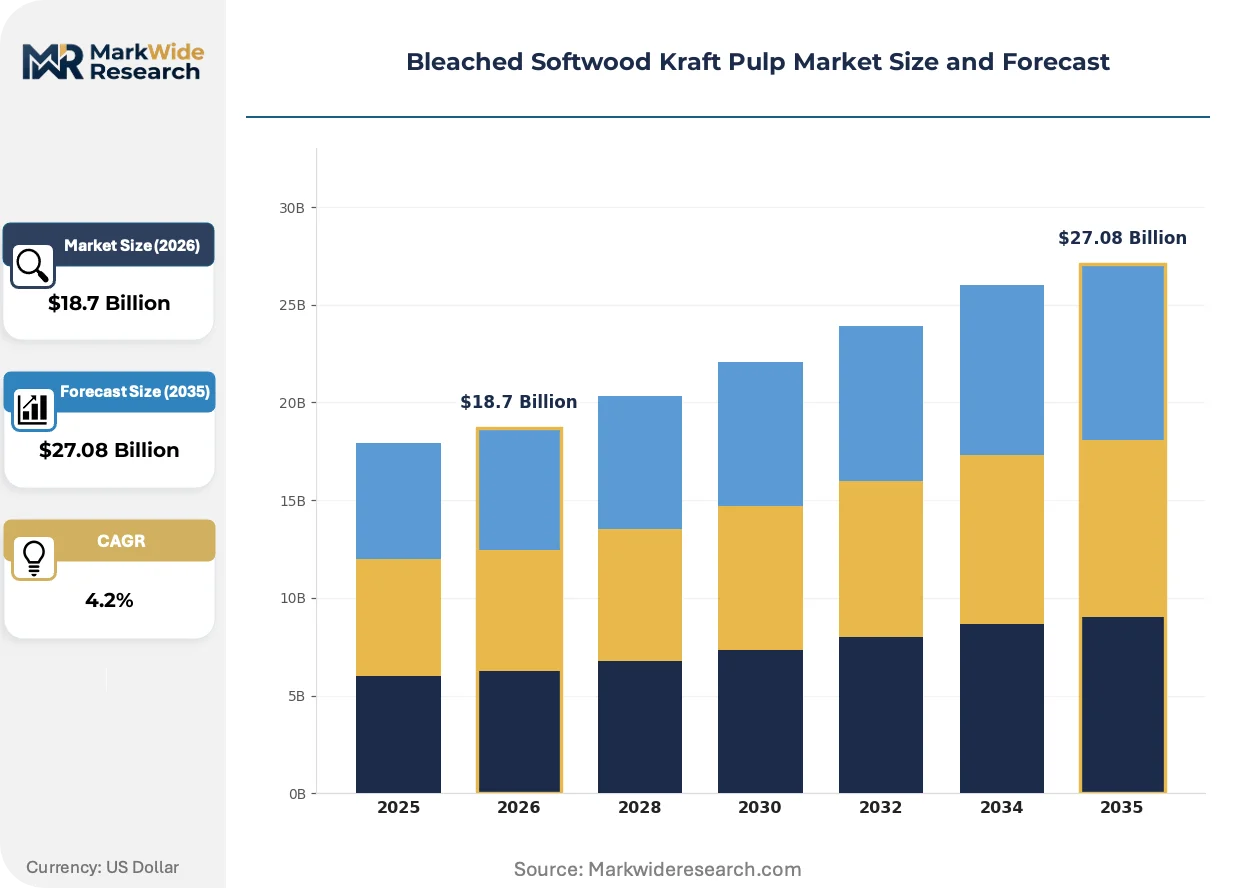
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Pulp, Mechanical Pulp, Semi-Chemical Pulp, Recycled Pulp Application: Printing Paper, Writing Paper, Packaging Material, Tissue Paper End Use Industry: Publishing, Packaging, Healthcare, Consumer Goods Form: Sheet, Roll, Bulk, Liquid |
| Companies Covered | Suzano, Arauco, Canfor Pulp, UPM-Kymmene, Metsä Fibre, West Fraser Timber, Mercer International, CMPC Celulosa, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleached Softwood Kraft Pulp Market Strategic Shifts
Elemental chlorine-free bleaching sequences are advancing alongside bioproduct extraction technologies, compressing the environmental footprint of virgin fiber production while opening parallel revenue streams from kraft pulping side-streams.
Extended oxygen delignification coupled with chlorine dioxide substitution is converging with closed-loop water recycling systems to reduce adsorbable organic halogen formation in bleached softwood kraft production. Nordic mill operators are deploying these integrated sequences to meet EU Industrial Emissions Directive limits. The structural consequence is a bifurcation between capital-upgraded European facilities and legacy North American mills facing accelerated environmental compliance timelines.
REACH chemical registration requirements for pulp mill effluent constituents are tightening discharge limits for chlorinated organics across EU member state permitting regimes. Industrial consequence includes mandatory best available technique upgrades for mills serving German and French tissue converters. Packaging end-users in the Benelux region are responding by specifying elemental chlorine-free grades with third-party verified environmental product declarations.
Long-term offtake contracting is displacing spot market purchasing among major Asian tissue and hygiene producers seeking supply security amid shipping volatility. Direct mill-to-converter agreements are replacing trader-mediated procurement for large Indonesian and Vietnamese tissue houses. This behavioral shift is most visible in Southeast Asian markets where integrated pulp-paper groups are capturing volume through captive supply arrangements.
Bleached Softwood Kraft Pulp Market Segmentation
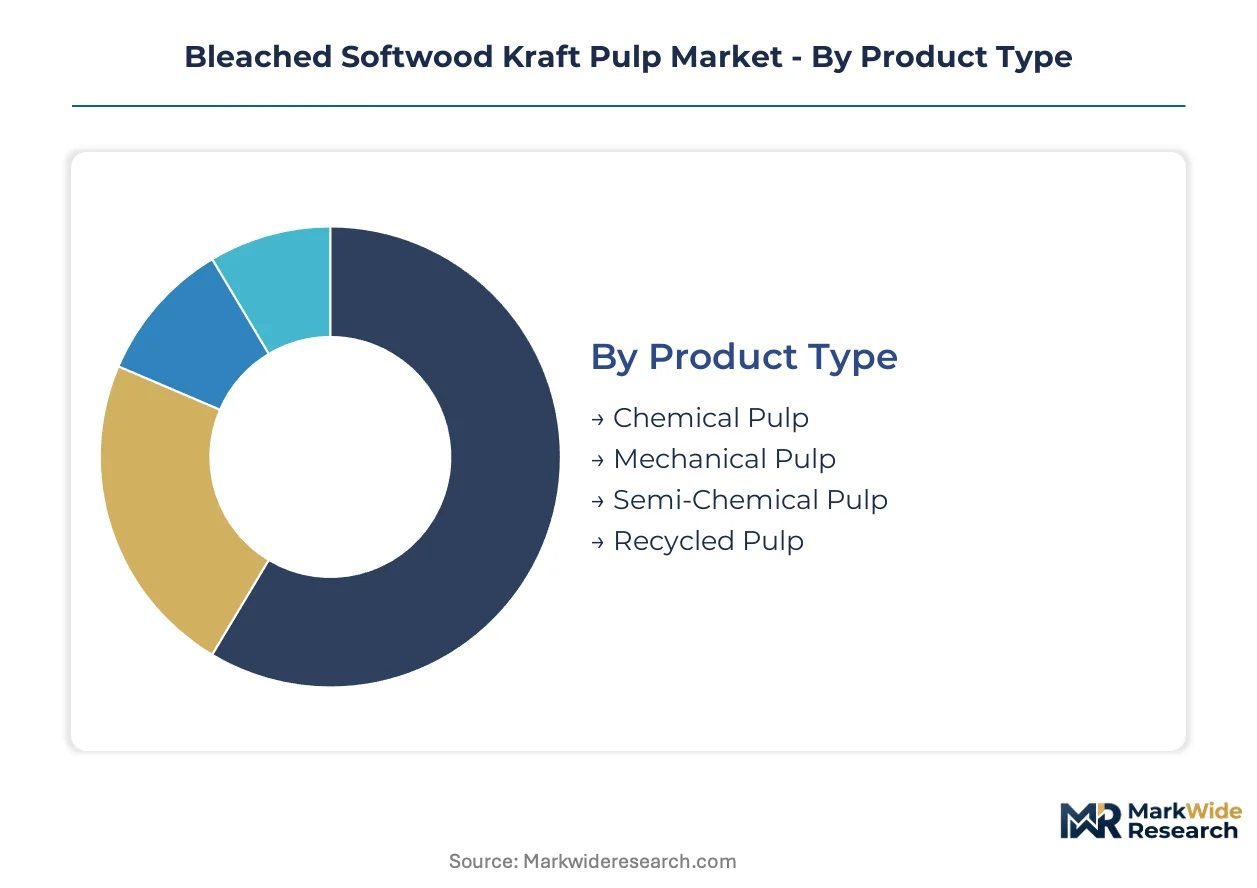
Segmentation in bleached softwood kraft pulp reveals how fiber specifications, delivery formats, and end-use requirements fragment procurement strategies. Buyers select grades based on machine runnability, brightness thresholds, and regulatory compliance needs rather than commodity pricing alone.
Product Type:
Supply concentration in chemical pulp production has created tiered availability across fiber processing technologies, with capital intensity and environmental compliance costs determining regional production footprints.
- Chemical Pulp:Alkaline cooking dissolves lignin to liberate long cellulose fibers with tensile strength exceeding 60 Nm/g. European tissue manufacturers and Asian packaging converters prioritize these grades for high-speed machine reliability under EU Deforestation Regulation traceability mandates.
- Mechanical Pulp:Groundwood and thermomechanical processes retain lignin for yield efficiency but sacrifice brightness stability. Newsprint producers in Nordic markets accept yellowing tendencies to reduce fiber costs for short-lifecycle publications.
- Semi-Chemical Pulp:Neutral sulfite semichemical cooking delivers intermediate strength for corrugating medium applications.
- Recycled Pulp:Deinked recovered fiber faces brightness ceilings that exclude premium hygiene applications.
Today's leader: Chemical Pulp. Tomorrow's challenger: Semi-Chemical Pulp.
Application:
Cost tier differentiation across paper grades determines pulp specification intensity, with premium applications absorbing virgin long-fiber premiums and commodity segments tolerating shorter fiber or recycled blends.
- Tissue Paper:Premium toilet and facial tissue production requires softwood kraft for bulk and wet strength. Indonesian and Vietnamese converters are expanding capacity faster than regional hardwood pulp supply, pulling Scandinavian exports into Southeast Asian ports.
- Packaging Material:Barrier-coated paperboard for food contact demands high-strength virgin fiber to replace plastic laminates. Brand-owner plastic substitution commitments in Benelux and German markets are accelerating specification of elemental chlorine-free grades with verified environmental product declarations.
- Printing Paper:Coated woodfree grades face demand compression from digital substitution in European publishing.
- Writing Paper:Copy and office paper segments prioritize brightness consistency over fiber length.
Volume concentrates in Packaging Material. Margin expansion concentrates in Tissue Paper.
End Use Industry:
Customer type segmentation separates specification-intensive buyers with technical service requirements from price-sensitive commodity purchasers.
- Packaging:Food-contact and industrial corrugated applications dominate tonnage offtake. Direct mill-to-converter contracting is displacing trader mediation for large Asian integrated groups seeking supply security.
- Consumer Goods:Hygiene product manufacturers specify brightness and softness thresholds that filter marginal suppliers. China's SAMR port-of-entry testing for residual chemical limits reinforces preference for certified Nordic producers.
- Publishing:Magazine and catalog segments face structural demand decline from digital media substitution.
- Healthcare:Medical-grade tissue and sterilization wrap applications require bioburden documentation.
Procurement sophistication peaks in Consumer Goods. Volume scale peaks in Packaging.
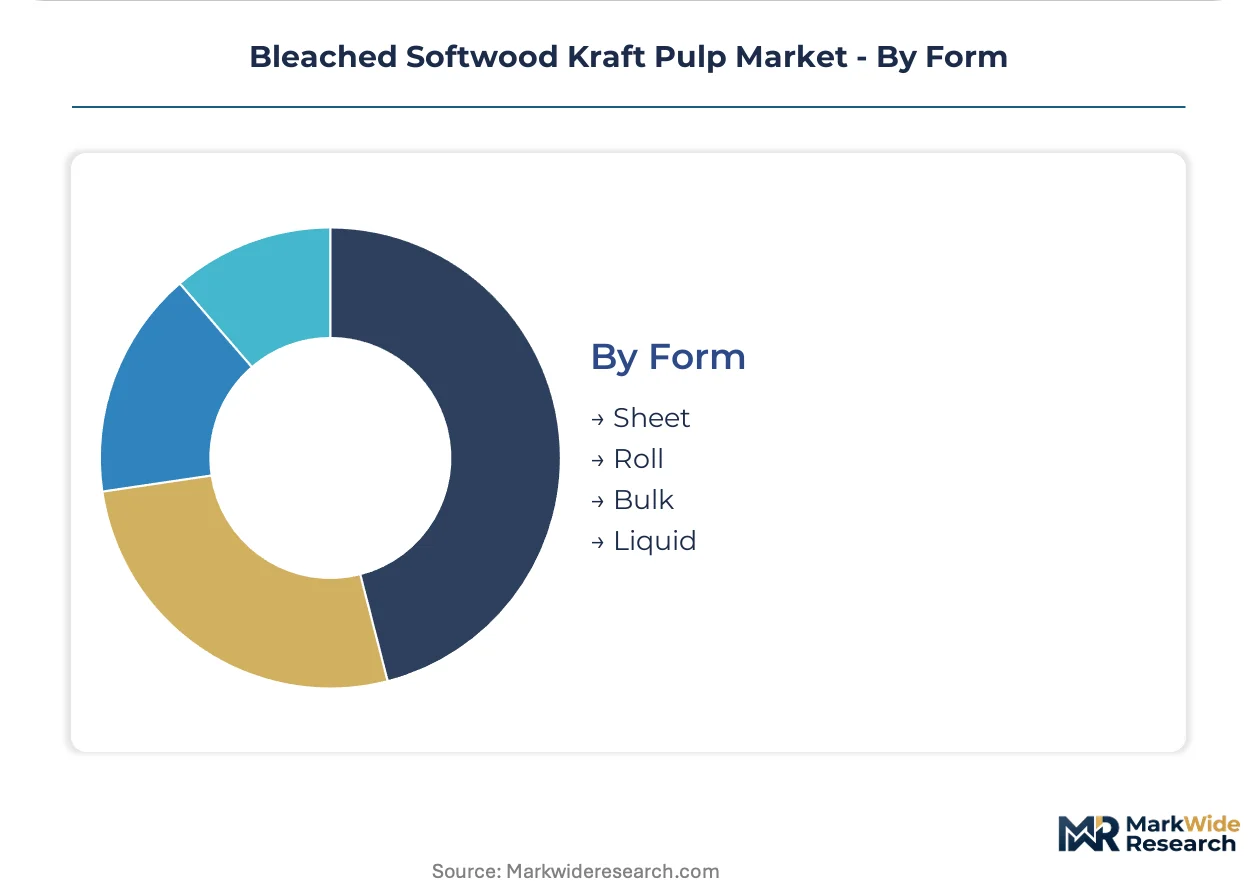
Form:
Logistics configuration and handling infrastructure at conversion facilities determine format preferences, with capital investment in unwinding and slitting equipment locking in procurement patterns.
- Roll:Continuous web delivery minimizes slitting waste for high-speed tissue and printing machines. Rail-linked logistics networks from Finnish mill complexes serve Central European converters with scheduled reliability.
- Sheet:Cut-size formats suit smaller packaging converters and specialty paper producers without roll-handling capability.
- Bulk:Loose fiber shipments serve integrated pulp-paper complexes with captive pulping capacity.
- Liquid:Slurry delivery eliminates drying energy for adjacent wet-laid nonwoven producers.
Operational standardization favors Roll. Niche flexibility favors Sheet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between jurisdictions with divergent environmental compliance costs is redirecting bleached softwood kraft pulp trade flows. Scandinavian producers leverage EU Deforestation Regulation readiness to capture certified supply premiums, while South American integrated platforms exploit lower energy and labor inputs to dominate seaborne volume.
United States
Pacific Northwest tissue converters and Southeast packaging houses drive demand for high-brightness virgin fiber. EPA effluent guidelines constrain kraft mill bleaching sequences, pushing capital investment toward oxygen delignification at Georgia and Alabama facilities. The Gulf Coast cluster around Mobile anchors expanding specialty paperboard capacity serving food-contact barrier applications.
China
GB standards enforced by SAMR at port of entry filter imported pulp for residual chemical limits and brightness specifications. Yangtze River Delta tissue manufacturers absorb record softwood kraft volumes as domestic hardwood pulp supply lags hygiene paper capacity expansion. Shandong Province converters increasingly specify elemental chlorine-free grades for premium facial tissue export.
Indonesia
Domestic hygiene paper capacity builds outpace local hardwood pulp supply, opening import windows for bleached softwood kraft with superior tensile properties. Jakarta and Surabaya-based tissue houses execute direct mill-to-converter agreements with Nordic suppliers, displacing trader-mediated procurement. The government prioritizes pulp self-sufficiency through plantation development in Kalimantan and Sumatra.
Germany
Benelux-oriented packaging converters specify elemental chlorine-free grades with third-party verified environmental product declarations under REACH-influenced permitting. North Rhine-Westphalia and Bavaria tissue manufacturers absorb Scandinavian rail-delivered rolls for high-speed machine reliability. The country's national packaging regulator enforces strict fiber traceability ahead of full EU Deforestation Regulation implementation.
Brazil
Eucalyptus-softwood integrated platforms control disproportionate seaborne trade share, creating single-source vulnerability for Asian converters. São Paulo state complexes leverage captive pulp-paper-power economics to undercut Nordic energy costs. The national environmental regulator monitors bleaching sequence compliance as export volumes to China and Southeast Asia accelerate.
Bleached Softwood Kraft Pulp Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bioproduct diversification and carbon-negative positioning. The market structure consolidates around integrated pulp-paper-power complexes with captive fiber supply and merchant market specialists dependent on spot pricing exposure. Three archetypes dominate: South American scale platforms with plantation-to-port control, Nordic bioproduct mills extracting side-stream value from lignin and tall oil, and North American lumber-linked producers with residual chip supply. Competitive moves concentrate on long-term offtake contracting displacement of spot purchasing and extended oxygen delignification capex cycles for EPA compliance.
Within the integrated platform tier, Suzano anchors Brazilian supply security through its eucalyptus-softwood combination, while Arauco represents Chilean scale concentration serving Pacific Basin converters. Among Nordic specialists, Metsä Fibre and UPM-Kymmene occupy positions defined by rail-linked logistics networks and bioproduct mill architecture. These named entities exemplify how geographic endowment and regulatory positioning stratify competitive capability rather than product differentiation alone.
| Leading Market Players |
|---|
| Suzano |
| Arauco |
| Canfor Pulp |
| UPM-Kymmene |
| Metsä Fibre |
| West Fraser Timber |
| Mercer International |
| CMPC Celulosa |
| International Paper |
| Others |
Value Chain & Pricing Dynamics
EU Deforestation Regulation traceability mandates gate both qualified supply and premium-tier pricing access, compressing procurement timelines for European tissue converters while Scandinavian producers capture certified supply premiums through geolocation-verified fiber documentation.
Pricing Analysis
Distributor margin layers compress as direct mill-to-converter contracting displaces trader-mediated procurement for large Indonesian and Vietnamese tissue houses. Pricing stratifies across elemental chlorine-free certified grades, FSC/PEFC chain-of-custody tiers, and standard brightness specifications, with certification premiums widening as China's SAMR enforces stricter GB standards at port of entry. Price erosion runs through lower-brightness mechanical pulp substitutes capturing volume in commodity packaging segments. Asian integrated pulp-paper groups exhibit lowest price sensitivity through captive supply arrangements, while independent European converters face acute cost compression from energy-linked logistics premiums.
Supply Chain Analysis
Direct-to-mill channels handle hyperscale tissue and hygiene demand from Southeast Asian converters seeking supply security amid shipping volatility. Production gravity centers on Brazil, Finland, and Sweden, with Nordic rail-linked logistics networks serving Central European packaging houses and São Paulo state complexes dominating Pacific Basin seaborne trade. Raw material dependencies include coniferous plantation fiber, chlorine dioxide for bleaching sequences, and tall oil for bioproduct side-stream extraction. Single-source vulnerability concentrates around Brazilian eucalyptus-softwood integrated platforms controlling disproportionate export share to Asian markets. Distribution runs through long-term offtake contracts with scheduled rail and bulk vessel delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bleached softwood kraft pulp functions as a stable compounder anchored by irreversible plastic substitution mandates in food-contact packaging that lock in structural demand for high-strength virgin fiber.
For Market Incumbents: Deepen bioproduct mill architecture investments to capture lignin and tall oil side-stream value, insulating margin pressure from Nordic energy cost volatility. Prioritize oxygen delignification capex cycles at U.S. Gulf Coast facilities to secure EPA effluent guideline compliance ahead of accelerated environmental timelines. Extend rail-linked logistics networks into Central European printing corridors to defend delivery reliability positioning against South American seaborne alternatives. For New Entrants and Emerging Players: The price-point gap between elemental chlorine-free certified premiums and standard brightness grades creates entry space for mid-tier regional suppliers. Target Indonesian tissue expansion where domestic hygiene paper capacity outpaces local hardwood pulp supply, opening import windows for bleached softwood kraft with superior tensile properties. Pursue direct mill-to-converter agreements with Jakarta and Surabaya-based tissue houses to bypass established trader networks. For Investors and Strategic Acquirers: Valuations sit cheapest among North American lumber-linked producers with residual chip supply and legacy mill assets facing EPA compliance capex cycles. Five-to-ten year viability hinges on successful brownstock washing and extended delignification upgrades converting environmental liability into certified supply positioning. Watch for inflection where Chinese GB standard enforcement filters marginal suppliers and concentrates share gains among certified Nordic and North American producers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct mill-to-converter contracting secures volume commitment from Indonesian tissue houses. |
| Backward Integration | Captive plantation development in Kalimantan reduces import dependency for domestic pulp supply. |
| Green Manufacturing Transition | Extended oxygen delignification sequences reduce adsorbable organic halogen formation at Nordic mills. |
| Capacity Expansion | Specialty paperboard builds along U.S. Gulf Coast serve food-contact barrier applications. |
| Joint Venture | Bioproduct extraction partnerships monetize lignin and tall oil side-streams from kraft pulping. |
Study Parameters
Coverage spans Nordic, South American, Southeast Asian, and North American production clusters, with primary inputs from each. The analysis combines interviews with mill operations directors, procurement leads at European tissue converters, Asian packaging house supply chain managers, and technical R&D directors at specialty paperboard producers with secondary validation from customs trade data, SEC pulp segment filings, FAO forest product statistics, and EPA effluent guideline documentation. Bottom-up capacity modeling triangulates against top-down demand aggregation across tissue, packaging, and printing end-uses.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across chemical-mechanical-recycled pulp grades, tissue-packaging-printing applications, and roll-sheet-bulk-liquid delivery formats, with additional dimensioning by EU Deforestation Regulation compliance tier. CAGRs derive from production capacity build schedules, import absorption rates at Chinese and Indonesian ports, and substitution elasticity estimates for plastic barrier applications. Industry-specific inputs include plantation fiber supply curves and bleaching sequence capital cost trajectories.
Caveats apply where regulatory enforcement intensity, energy cost volatility, or shipping route disruptions could materially shift the outlook. Forecasts reflect documented assumptions about Chinese GB standard adherence, EU Deforestation Regulation implementation timelines, and Nordic mill bioproduct extraction yields. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Reprographic Paper Market
Paper Products
Paper Coating Materials Market
Paper Products
Paper Based Laminates Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Veneer Sheets Market
Paper Products
North America Specialty Paper Market
Paper Products
Insulation Paper Market
Paper Products
Sawn Wood Market
Paper Products
Global Thin Papers Market
Paper Products
Duplex Paper and Board Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Africa Tissue Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Recovered Paper Market