
 Potassium Fluoborate Market | 2026-2036
Potassium Fluoborate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Fluoborate Market Outlook
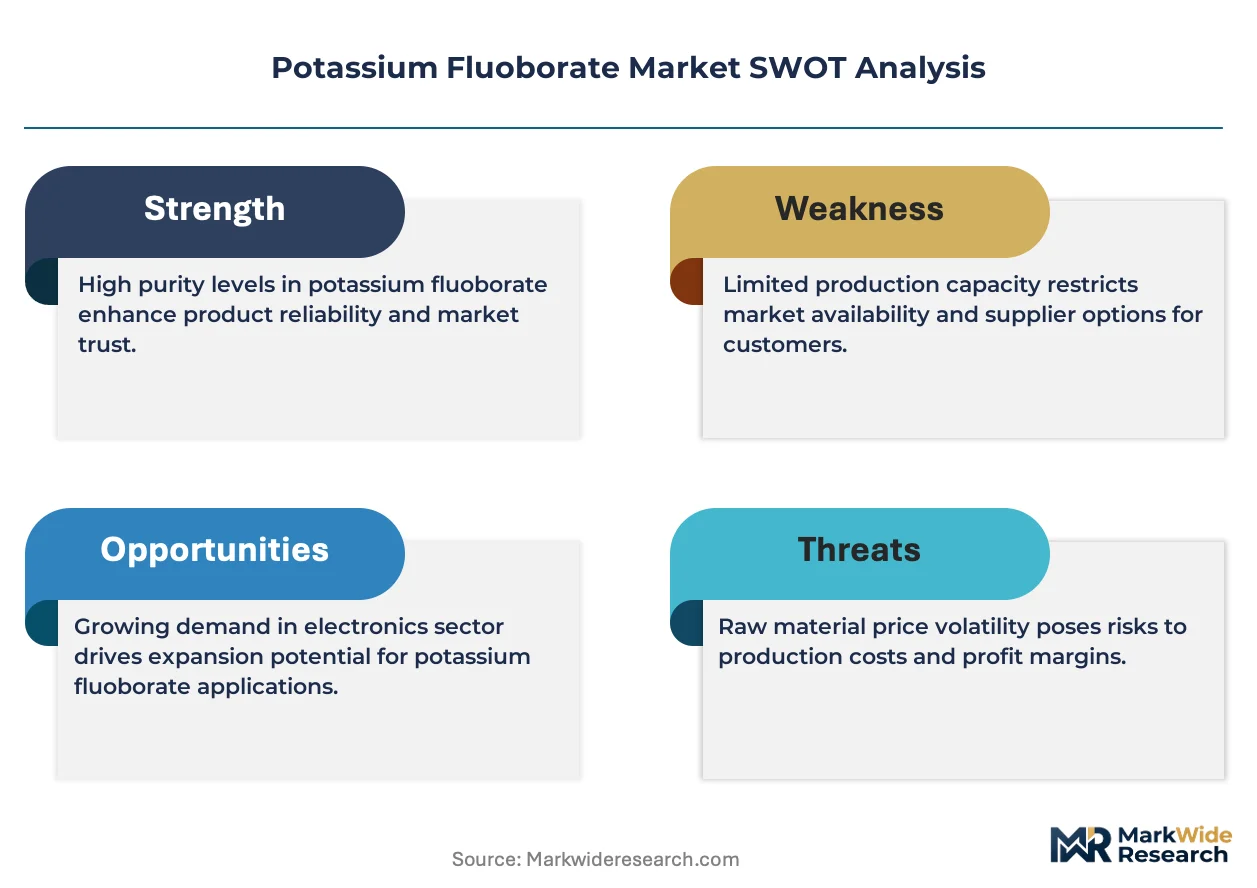
Multi-source procurement for fluoroborate salts is pivoting toward captive in-house production among large aluminum smelters seeking supply security. Solvay S.A. leverages its integrated fluorine chemistry platform to control raw material flows from mine to refined salt. AMG Aluminum anchors its position through backward integration into bauxite processing and on-site flux generation. Stella Chemifa Corporation competes on pharmaceutical-grade purification standards that command premium positioning in laboratory markets.
Potassium fluoborate (KBF4) is a white crystalline inorganic salt synthesized via reaction of hydrofluoric acid with boric acid and potassium carbonate, typically assaying 98-99% purity with controlled particle size distribution for fluxing applications. The compound functions primarily as an active flux in aluminum and magnesium alloy refining, lowering oxide surface tension and improving melt cleanliness. Industrial grade material dominates volume flows into metal surface treatment and glass manufacturing, where cost sensitivity outweighs purity premiums. Reagent grade applications in electronics and laboratories sustain higher margins despite smaller offtake volumes, driven by semiconductor wafer cleaning protocols and analytical chemistry standards.
EPA hazardous waste classifications in the United States and REACH chemical registration requirements in Europe constrain production facility siting and waste discharge permits, elevating compliance costs for non-integrated producers. China's MEE enforces fluorine emission caps that favor producers with closed-loop acid recovery systems. India's BIS certification mandates for industrial chemicals add testing burdens for import-dependent metal treatment shops. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and chemical safety dossiers reshape competitive access to key demand clusters.
Market Dynamics
Automotive lightweighting mandates are compressing aluminum smelter procurement cycles, forcing flux suppliers to co-locate with melt shops or risk volume displacement by captive in-house production.
Growth Catalysts
- Automotive CAFE Standards:US EPA fuel efficiency targets are accelerating aluminum substitution in vehicle bodies, expanding flux consumption per ton of recycled alloy.
- MEE Fluorine Emission Caps:China's Ministry of Ecology and Environment standards are consolidating production toward closed-loop acid recovery systems, advantaging compliant suppliers with secured permits.
- Electroplating Cluster Expansion:East China's fluorochemical corridor is scaling surface treatment capacity for export glass manufacturing, anchoring regional KBF4 offtake.
Market Restraints
- Hydrofluoric Acid Price Volatility:Feedstock cost swings from phosphate fertilizer co-production constraints compress margins for non-integrated salt processors.
- East China Supply Concentration:Over 60% of global capacity sits within 200 kilometers of Shanghai, creating single-point vulnerability to port congestion or regional power rationing.
- REACH Registration Burden:ECHA chemical safety dossier requirements for KBF4 importers are elevating compliance costs above €100,000 per substance, filtering small traders from EU market access.
Strategic Opportunities
- India BIS Certification Gap:Domestic metal treatment shops dependent on imports face testing backlogs, creating first-mover advantage for local synthesis investments meeting Bureau of Indian Standards mandates.
- Semiconductor Wafer Cleaning:Reagent-grade KBF4 adoption in advanced node fabrication is outpacing industrial-grade growth rates as chipmakers tighten particle contamination protocols.
- EU F-Gas Regulation Phase-Down:Fluorinated gas restrictions are redirecting fluorine feedstock availability toward inorganic salt production, easing raw material access for compliant producers.
Industry Challenges
- Pharmaceutical-Grade Purification Talent Scarcity:Laboratory salt production requires analytical chemists trained in ICP-MS trace metal detection, a skill set concentrated in Japanese and German technical institutes.
- Legacy ERP Integration Friction:Smelters adopting just-in-time flux delivery systems face data interoperability failures with 1990s-era aluminum melt shop control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Fluoborate Market |
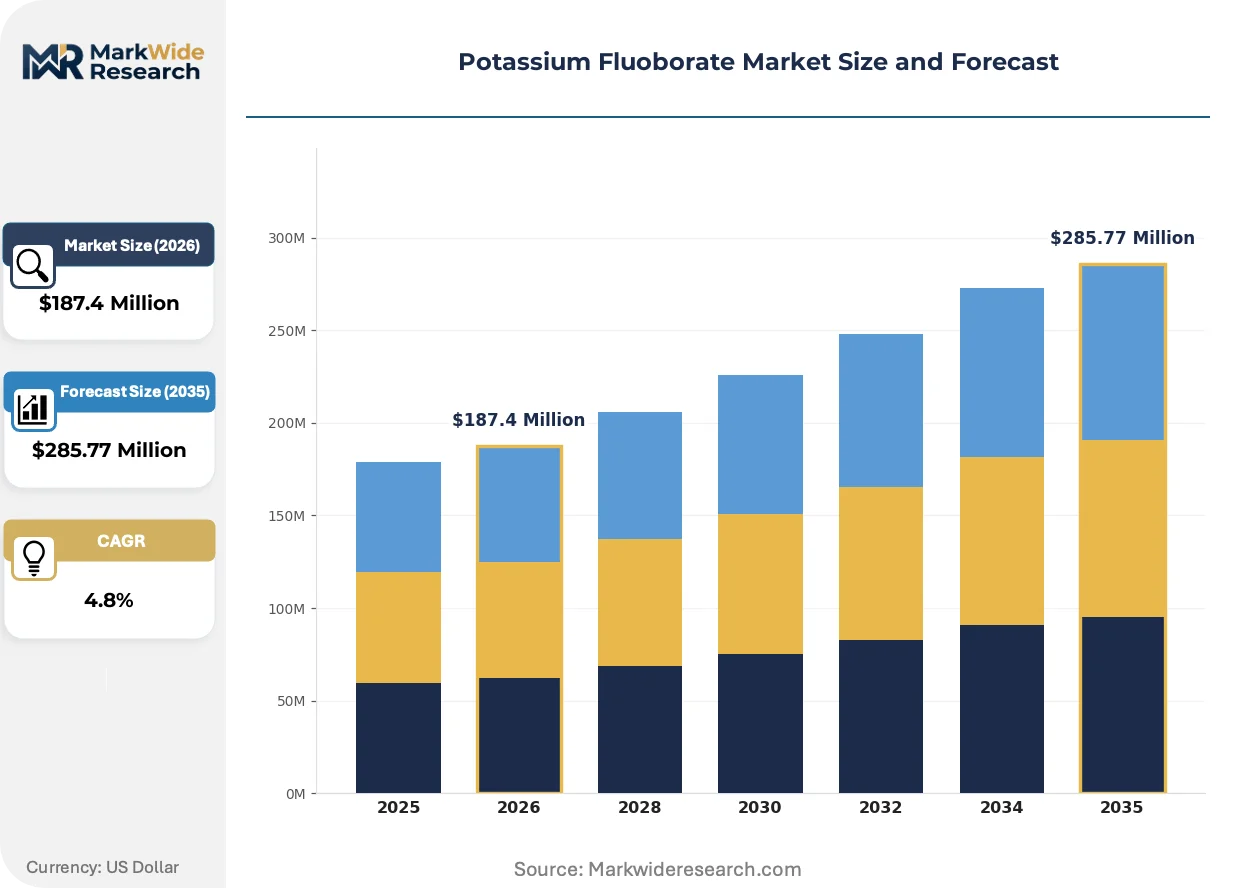
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Technical Grade Application: Glass Manufacturing, Electroplating, Cleaning Agents, Metal Surface Treatment End User: Manufacturing, Pharmaceuticals, Laboratories, Electronics Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Solvay S.A., American Elements, Morita Chemical Industries, AMG Aluminum, Stella Chemifa Corporation, Hunan Merits New Materials Co. Ltd., Harshil Industries, Derivados Del Flúor (DDF), Foshan Nanhai Fluoride Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Fluoborate Market Strategic Shifts
Fluorine chemistry platforms are converging with closed-loop manufacturing systems, compressing waste discharge while enabling higher-purity salt outputs for electronics applications.
Membrane electrolysis for fluoroborate regeneration is electrifying flux recovery economics in aluminum remelting operations. Secondary smelters in Germany and Japan are retrofitting membrane cells to capture spent flux components, cutting virgin KBF4 purchases by half. This technology is electrifying competitive positioning among mid-scale recyclers previously locked out of premium automotive alloy contracts.
REACH Annex XIV authorization requirements for boron compounds are tightening substance volume tracking across EU electroplating supply chains. Metal finishers must now document KBF4 mass balance from import through waste treatment, elevating digital traceability system investments. The laboratory reagent segment faces the steepest compliance cost escalation as analytical-grade purity demands intersect with expanded safety data sheet obligations.
Long-term offtake agreements are displacing spot market purchasing among aluminum casthouses serving electric vehicle platforms. Tier-1 suppliers in Michigan and Bavaria are locking three-year flux supply contracts with fixed-price escalators, transferring inventory risk upstream. This behavior is most pronounced in battery enclosure casting programs where alloy consistency specifications leave minimal tolerance for supplier switching.
Potassium Fluoborate Market Segmentation
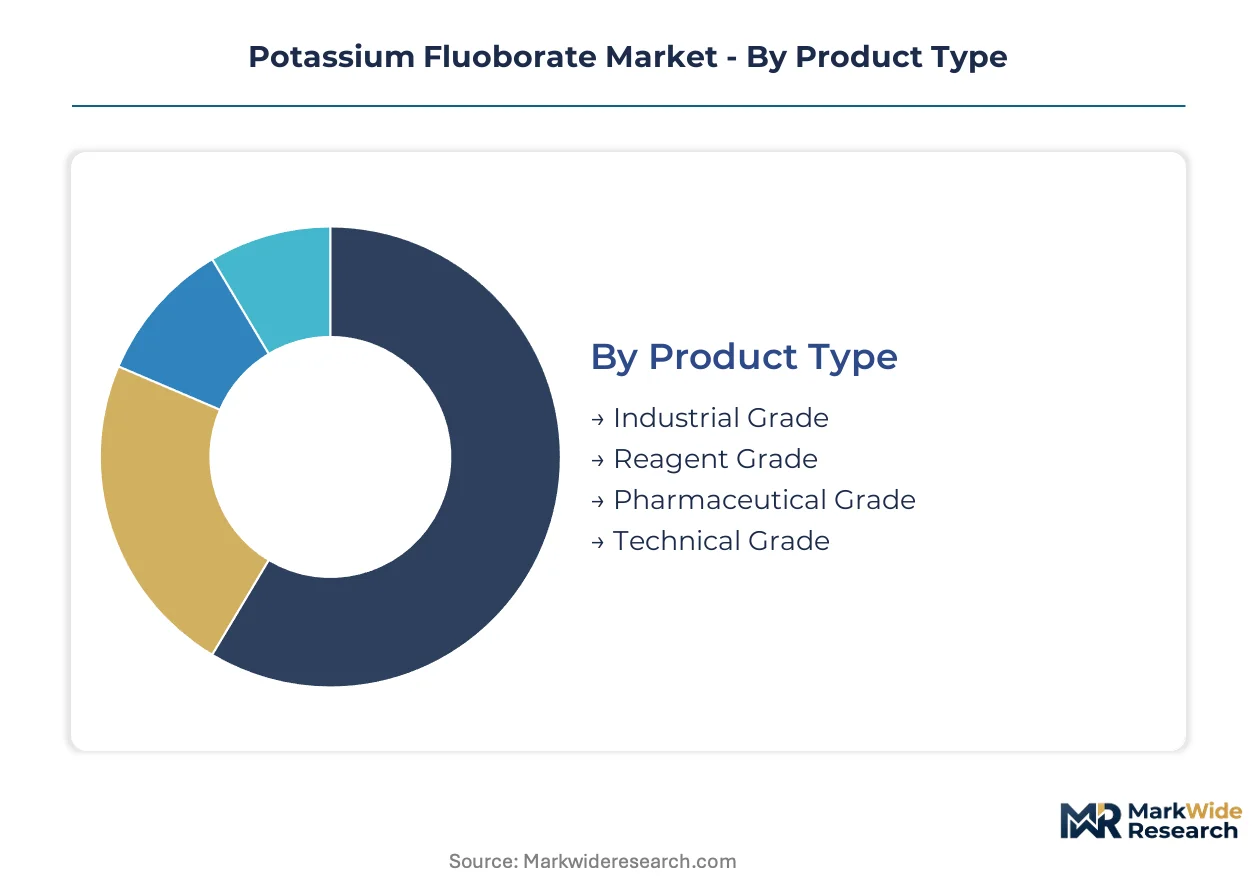
Potassium fluoborate specifications diverge sharply across end-use requirements, with purity thresholds determining access to premium electronics and pharmaceutical channels versus commodity metal treatment markets. Grade differentiation locks in margin stratification that rewards purification capability investments.
Product Type:
Purity thresholds and particle size distribution separate commodity flux applications from contamination-sensitive electronics and laboratory end-uses.
- Industrial Grade:Material assays 98-99% KBF4 with controlled granulometry optimized for aluminum melt shop fluxing. Demand concentrates in East China's fluorochemical corridor serving automotive lightweighting programs, where smelters prioritize cost stability over trace metal specifications. MEE emission caps favor producers with closed-loop acid recovery systems.
- Reagent Grade:Sub-ppm trace metal specifications enable semiconductor wafer cleaning protocols and analytical chemistry standards. Adoption is climbing fastest in advanced node fabrication facilities in Taiwan and South Korea as chipmakers tighten particle contamination thresholds. Premium positioning sustains margins three to five times industrial grade levels.
- Pharmaceutical Grade:Meets USP/EP monograph requirements for boron compound purity in drug synthesis and diagnostic reagents.
- Technical Grade:Intermediate specification serving specialty glass manufacturers and non-critical electroplating baths.
Industrial grade leads on scale; reagent grade leads on momentum.
Application:
Process chemistry requirements dictate grade selection, with molten metal applications tolerating higher impurity loads than surface deposition processes.
- Metal Surface Treatment:Aluminum and magnesium alloy refining consumes the largest volume share, with KBF4 functioning as an active flux to lower oxide surface tension and improve melt cleanliness. Automotive CAFE standards in the United States are accelerating aluminum substitution in vehicle bodies, expanding flux consumption per ton of recycled alloy.
- Glass Manufacturing:Opacifying agent in borosilicate and specialty glass production for laboratory equipment and lighting. East China's export-oriented glass clusters anchor regional offtake, with fluoroborate demand tracking photovoltaic and pharmaceutical packaging growth.
- Electroplating:Brightening agent in nickel and tin plating baths for electronics connectors and decorative finishes.
- Cleaning Agents:Precision cleaning formulations for semiconductor equipment and optical components.
Metal surface treatment dominates volume; glass manufacturing offers steadiest replacement demand.
End User:
Procurement sophistication varies dramatically, from spot-market commodity purchasing to multi-year supply agreements with fixed-price escalators.
- Manufacturing:Aluminum casthouses and secondary smelters drive bulk purchasing, with tier-1 automotive suppliers in Michigan and Bavaria locking three-year flux contracts. Inventory risk transfer upstream is most pronounced in battery enclosure casting programs where alloy consistency specifications permit minimal supplier switching.
- Electronics:Semiconductor fabs and PCB manufacturers demand reagent-grade material with full batch traceability. REACH Annex XIV authorization requirements for boron compounds are tightening substance volume tracking across EU electroplating supply chains.
- Pharmaceuticals:API synthesis and diagnostic reagent production require pharmaceutical-grade certification.
- Laboratories:Analytical chemistry and research applications sustain premium pricing despite smaller offtake volumes.
Manufacturing commands absolute volume; electronics is expanding most quickly.
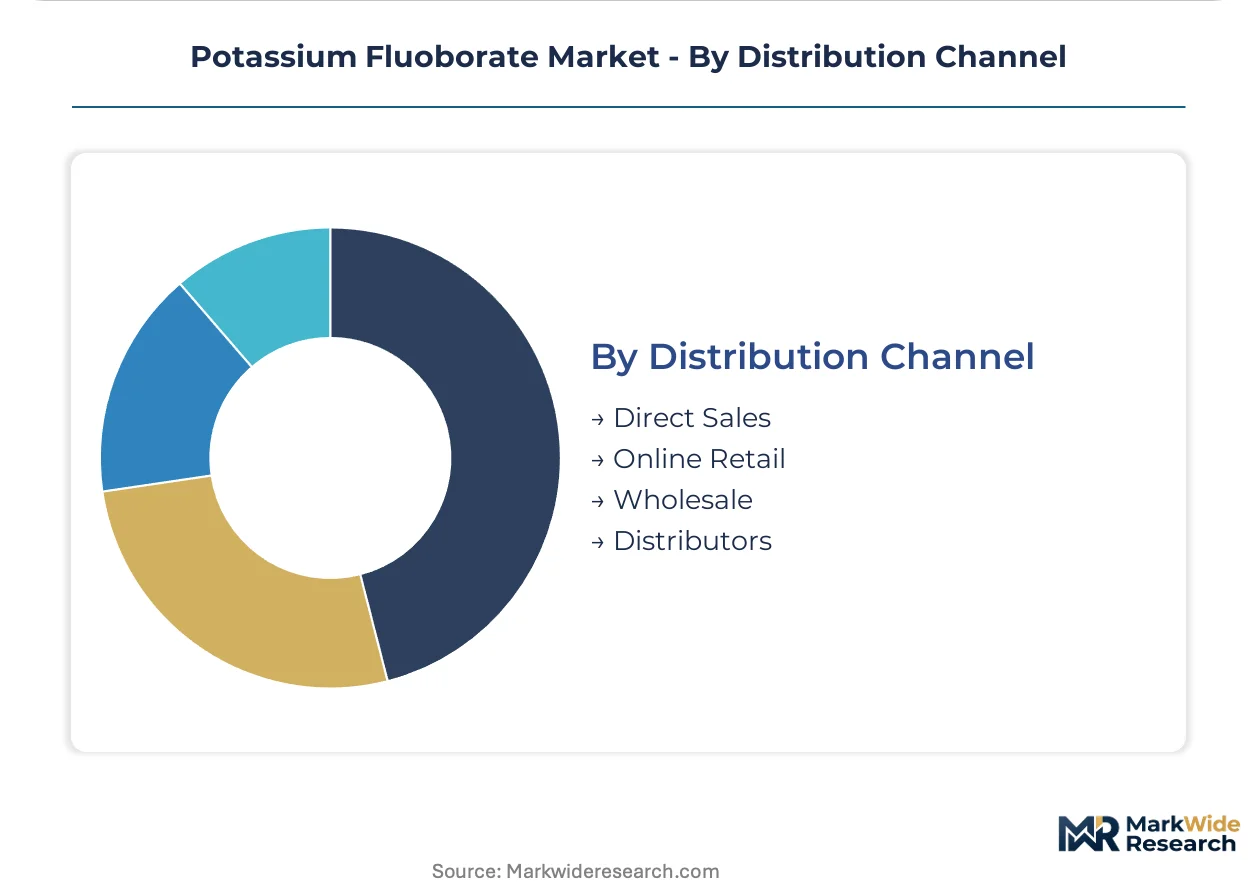
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with large consumers bypassing intermediaries to secure supply security.
- Direct Sales:Large aluminum smelters and semiconductor fabs negotiate directly with integrated fluorine chemistry producers. Solvay S.A. and AMG Aluminum leverage captive production platforms to serve automotive casthouses under long-term offtake structures.
- Distributors:Regional chemical distributors serve mid-scale metal treatment shops and electroplating operations requiring technical support and smaller lot sizes.
- Wholesale:Bulk material aggregation for industrial grade flux applications in secondary aluminum markets.
- Online Retail:Laboratory-scale packaging for research institutions and small-batch pharmaceutical synthesis.
Direct sales anchors volume concentration; distributors retain relevance in fragmented metal finishing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's fluorochemical corridor concentrates the heaviest production capacity and demand density for potassium fluoborate, with Shanghai's port infrastructure enabling export flows to glass manufacturers and aluminum casthouses worldwide.
China
Automotive lightweighting programs and photovoltaic glass expansion drive industrial-grade consumption. MEE fluorine emission caps under dual carbon goals consolidate production toward closed-loop acid recovery systems. Zhejiang and Jiangsu provinces host integrated fluoroborate clusters serving both domestic electroplating and export-oriented specialty glass manufacturers.
United States
EPA CAFE standards accelerate aluminum substitution in electric vehicle platforms, expanding flux demand per ton of recycled alloy. EPA hazardous waste classifications constrain production facility siting and elevate compliance costs for non-integrated processors. Michigan-based automotive casthouses lock long-term supply agreements with fixed-price escalators for battery enclosure casting programs.
Germany
Secondary aluminum smelters retrofit membrane electrolysis cells for spent flux regeneration, cutting virgin material purchases. REACH Annex XIV authorization requirements for boron compounds tighten substance volume tracking across electroplating supply chains. Bavarian tier-1 suppliers negotiate three-year flux contracts transferring inventory risk upstream from OEMs.
Japan
Semiconductor wafer cleaning protocols in advanced node fabrication drive reagent-grade adoption faster than industrial-grade growth. METI industrial policy supports fluorine chemistry platform consolidation. Stella Chemifa Corporation anchors pharmaceutical-grade purification standards commanding premium positioning in laboratory markets.
India
Import-dependent metal treatment shops face BIS certification backlogs for industrial chemicals, creating bottlenecks for domestic aluminum processors. CDSCO pharmaceutical regulations intersect with fluoroborate applications in diagnostic reagent production. Gujarat and Maharashtra industrial corridors attract first-mover investments in local synthesis capacity.
Potassium Fluoborate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue reagent-grade specialization and regional supply security plays. The vendor base stratifies across integrated fluorine chemistry platforms, captive aluminum smelter operations, and purification-focused laboratory suppliers. Three archetypes dominate: backward-integrated raw material controllers, downstream-captive flux generators, and premium-grade certification specialists. Competitive moves concentrate on co-location partnerships with automotive casthouses and membrane-based flux regeneration technology licensing.
Within the integrated chemistry tier, Solvay S.A. exemplifies mine-to-salt platform control, while AMG Aluminum occupies a position linking bauxite processing to on-site flux generation. Stella Chemifa Corporation anchors the pharmaceutical-grade purification segment where analytical chemistry standards command sustained margin premiums.
| Leading Market Players |
|---|
| Solvay S.A. |
| American Elements |
| Morita Chemical Industries |
| AMG Aluminum |
| Stella Chemifa Corporation |
| Hunan Merits New Materials Co. Ltd. |
| Harshil Industries |
| Derivados Del Flúor (DDF) |
| Foshan Nanhai Fluoride Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production among large aluminum smelters anchors both supply security and pricing power in the potassium fluoborate market. This integration pattern compresses procurement cycles for automotive casthouses while forcing non-integrated salt processors to compete on feedstock cost pass-through efficiency.
Pricing Analysis
Hydrofluoric acid cost pass-through dominates pricing dynamics for non-integrated producers, with phosphate fertilizer co-production constraints driving feedstock volatility. Contract-based long-term offtake structures prevail among tier-1 automotive suppliers, while spot-market purchasing persists in fragmented metal finishing segments. Price differentiation rests on certification grade and volume scale, with reagent-grade material commanding substantial premiums over industrial-grade flux. Cost compression in commodity tiers is intensifying as Chinese MEE emission caps consolidate production toward closed-loop systems, leaving import-dependent processors most exposed to margin erosion.
Supply Chain Analysis
Analytical chemists trained in ICP-MS trace metal detection concentrate in Japanese and German technical institutes, constraining pharmaceutical-grade purification capacity expansion. Manufacturing clusters in China, Germany, and Japan anchor global supply, with East China's fluorochemical corridor hosting over sixty percent of integrated capacity. Raw material flows draw from hydrofluoric acid, boric acid, and potassium carbonate sources, with fluorine feedstock availability tethered to phosphate fertilizer and aluminum smelter by-product economics. Single-source vulnerability around Shanghai's port infrastructure creates systemic exposure to regional power rationing or logistics disruption. Distribution runs through direct sales channels for large consumers and regional chemical distributors for mid-scale metal treatment operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The potassium fluoborate market functions as a stable compounder, with automotive lightweighting mandates driving steady flux consumption growth across aluminum recycling loops.
For Market Incumbents: Lock in long-term offtake agreements with electric vehicle battery enclosure casthouses before membrane electrolysis regeneration technology displaces virgin material demand. Deepen backward integration into hydrofluoric acid supply to buffer phosphate fertilizer co-production volatility. Prioritize closed-loop acid recovery system investments to secure MEE permits in China's consolidating production landscape. For New Entrants and Emerging Players: Import-dependent Indian metal treatment shops facing BIS certification backlogs represent the most penetrable buyer archetype for local synthesis investments. Target reagent-grade specialization for semiconductor wafer cleaning applications in Taiwan and South Korea, where advanced node fabrication protocols outpace incumbent supply capability. Pursue joint venture structures with East Chinese fluorochemical platforms to access established acid recovery infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH Annex XIV authorization costs exceed one hundred thousand euros per substance, filtering small traders from EU market access. Five-to-ten year viability favors integrated fluorine chemistry platforms with mine-to-salt control and captive automotive customer relationships. Watch membrane electrolysis adoption rates in German and Japanese secondary smelters as the signal for virgin KBF4 demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorine Feedstock | Mine-to-salt control insulates Solvay and AMG from phosphate fertilizer co-production volatility. |
| Membrane Electrolysis Technology Licensing | Secondary smelters in Germany cut virgin purchases by half through spent flux regeneration. |
| Long-term Supply Agreement with Automotive Casthouses | Three-year contracts with fixed-price escalators transfer inventory risk from Michigan OEMs. |
| Pharmaceutical-Grade Certification Investment | USP/EP monograph compliance unlocks diagnostic reagent premiums for Stella Chemifa. |
| Joint Venture in East China Fluorochemical Corridor | Access to Zhejiang closed-loop acid recovery systems secures MEE emission cap compliance. |
Study Parameters
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each market triangulated against secondary validation. Primary interviews incorporated fluorine chemistry plant managers, aluminum casthouse procurement leads, semiconductor fab materials engineers, electroplating technical directors, and regional chemical distribution partners. Secondary sources included customs and trade flow databases, SEC 10-K filings from integrated producers, MEE emission disclosure reports, and REACH registration dossiers. Bottom-up grade-tier demand modeling and top-down fluorochemical industry aggregation were cross-validated to establish volume and value estimates.
Rate-of-change decomposition separated volume growth from price trajectory across the projection horizon. The analytical framework modeled segmentation across industrial, reagent, pharmaceutical, and technical grades; metal surface treatment, glass manufacturing, electroplating, and cleaning agent applications; and manufacturing, electronics, pharmaceutical, and laboratory end users. Regional production hub clustering and regulatory framework divergence provided additional cross-sectional dimensions. CAGRs were derived from fitted trend extrapolation adjusted for identified inflection triggers including MEE permit issuance rates and membrane electrolysis retrofit announcements.
Underlying measurement precision varies by segment; reagent-grade and pharmaceutical-grade categories carry tighter precision than industrial-grade commodity flows given more concentrated customer bases and disclosed contract structures. Forecasts reflect assumptions about automotive aluminum substitution rates, fluorine emission cap enforcement intensity, and semiconductor fabrication node advancement. Material deviation in MEE inspection schedules, REACH authorization timelines, or membrane electrolysis cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market