
 Crowdfunding Market | 2026-2036
Crowdfunding Market Size, Share, and Industry Trends Forecast 2026-2036
Crowdfunding Market Intelligence
Recurring membership tiers and software-defined access controls are rebalancing what crowdfunding platforms sell beyond transactional campaign fees. Kickstarter PBC leverages creator subscription tools to sustain repeat project launches and reduce donor acquisition costs. GoFundMe Inc. anchors its position in medical and personal emergency fundraising, where network effects dominate. Wefunder Inc. competes aggressively on regulatory automation, streamlining SEC compliance for equity issuers.
Crowdfunding denotes the practice of raising capital from a distributed pool of contributors, typically through internet-mediated platforms that aggregate small contributions into funding targets for projects, ventures, or causes. Platforms encode trust mechanisms through escrow protocols, milestone-based disbursement, and automated background verification to reduce counterparty risk between backers and campaign operators. Reward-based platforms currently occupy the largest contribution volume, while equity-based segments are attracting institutional capital seeking early-stage exposure outside traditional venture channels. Debt-based crowdfunding, or peer-to-peer lending, is maturing fastest in regulatory environments with clear licensing frameworks for non-bank credit intermediation.
The SEC governs equity crowdfunding through Regulation Crowdfunding, capping retail investor exposure and mandating disclosure schedules that shape platform architecture. The EU AI Act and GDPR impose algorithmic transparency and data handling standards on European platforms, while the FCA in the United Kingdom maintains distinct authorization requirements for loan-based and investment-based crowdfunding. Stakeholders must monitor how divergent national approaches to investor protection and platform liability create compliance fragmentation that favors regionally specialized operators over unified global expansion.
Market Dynamics
Platform operators face mounting pressure from algorithmic transparency mandates under the EU AI Act, which forces redesigns of automated campaign verification and investor matching systems. This regulatory compression is accelerating consolidation among mid-tier platforms that lack compliance infrastructure.
Growth Catalysts
- Regulation Crowdfunding in the United States:SEC disclosure schedules provide retail investor access frameworks that reduce legal friction for equity issuers. Platform architecture now embeds these compliance protocols as competitive features.
- Medical emergency fundraising:Network effects in personal cause categories reduce donor acquisition costs through repeat engagement cycles. GoFundMe anchors this segment with specialized tooling for healthcare cost campaigns.
- Blockchain-based escrow protocols:Smart contract automation is consolidating trust mechanisms through immutable milestone disbursement. Early-stage platforms adopt these systems to differentiate from incumbent manual processes.
Market Restraints
- GDPR data localization requirements:European platforms face structural cost inflation from mandatory EU-based server infrastructure and cross-border transfer restrictions. Compliance overhead disadvantages smaller operators against scaled rivals.
- Bank partnership concentration:Payment processing depends on a narrow tier of licensed financial institutions willing to underwrite crowdfunding transaction risk. This supply concentration creates single-point vulnerabilities for platform liquidity.
- Retail investor exposure caps:SEC limits on annual investment amounts constrain equity crowdfunding ticket sizes. Issuers seeking larger capital pools must revert to traditional venture channels.
Strategic Opportunities
- Creator subscription tooling:Kickstarter PBC demonstrates recurring revenue potential through membership tiers that sustain repeat project launches. Platforms can capture lifetime value beyond single-campaign fees.
- Regulatory automation services:Wefunder Inc. models streamlined SEC compliance workflows that reduce issuer legal burden. White-labeling these systems creates B2B revenue streams for platform infrastructure providers.
- Debt-based crowdfunding in the United Kingdom:FCA authorization frameworks for peer-to-peer lending mature faster than equity equivalents. Licensed non-bank credit intermediation attracts institutional capital seeking yield outside traditional banking.
Industry Challenges
- Algorithmic audit talent scarcity:EU AI Act compliance requires specialized personnel capable of documenting automated decision systems. Platforms compete for limited technical-legal hybrid expertise against broader fintech hiring pools.
- Cross-border regulatory fragmentation:Divergent national approaches to investor protection and platform liability prevent unified global expansion. Operators must maintain separate compliance stacks for each jurisdiction.
- Legacy bank integration complexity:Real-time payment settlement demands API connections to core banking systems with decades-old infrastructure. Technical debt in partner institutions slows platform feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crowdfunding Market |
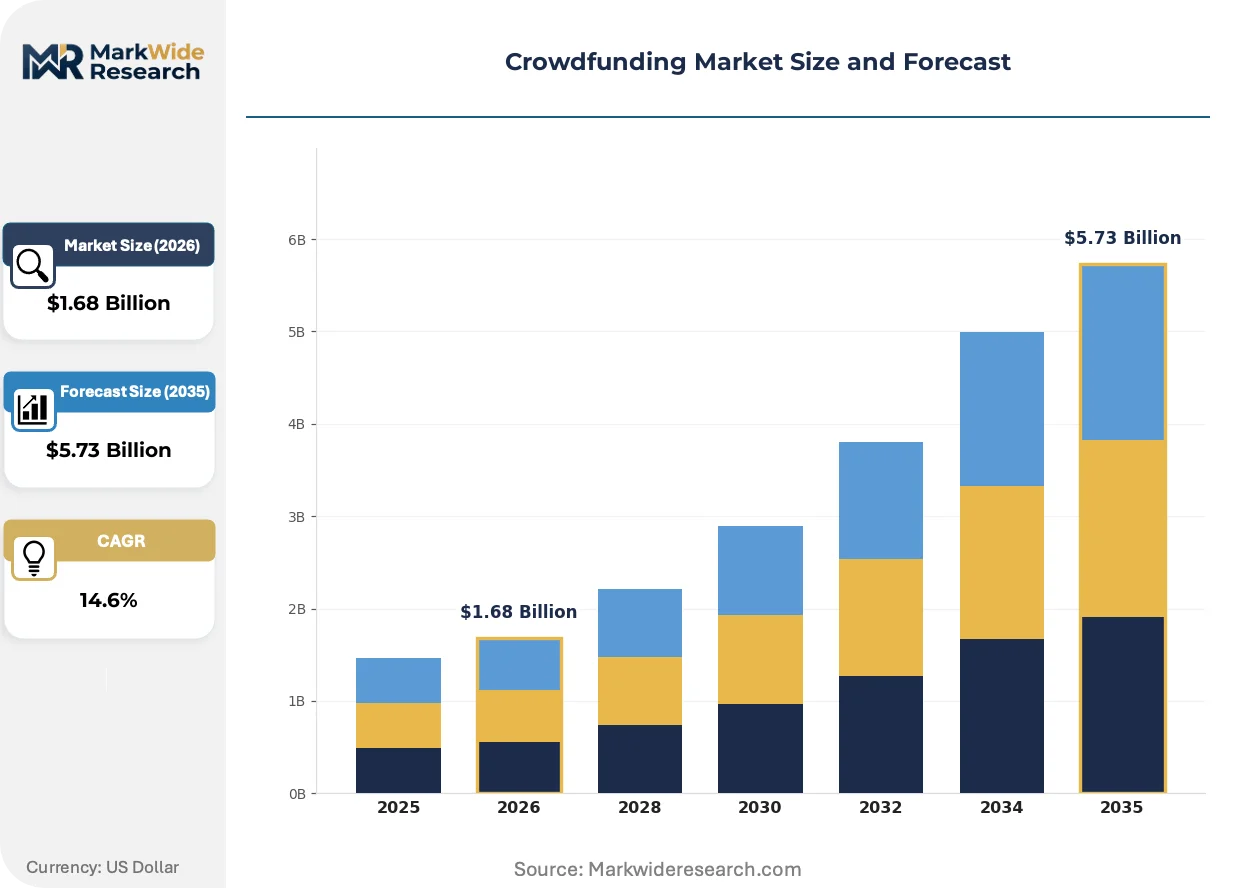
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $5.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Reward-Based, Equity-Based, Debt-Based, Donation-Based Campaign Type: Creative Projects, Startups, Social Causes, Community Initiatives Contribution Size: Small Contributions, Medium Contributions, Large Contributions, Micro-Investments User Type: Individual Investors, Institutional Investors, Nonprofits, Entrepreneurs |
| Companies Covered | Kickstarter PBC, Indiegogo Inc., GoFundMe Inc., Wefunder Inc., Crowdcube Limited, SeedInvest Technology LLC, Fundable LLC, StartEngine, Patreon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crowdfunding Market Strategic Shifts & Innovations
Automated verification systems and subscription-based creator economies are compressing traditional campaign-fee business models. Platforms now compete on retained engagement rather than transactional volume.
Blockchain-enabled escrow is consolidating trust infrastructure across reward-based and equity platforms. Early-stage operators adopt smart contract disbursement to reduce manual overhead and fraud exposure. Technology startups represent the fastest-adopting end-use segment, with venture-backed issuers demanding programmable milestone releases. This consolidation is compressing counterparty risk premiums and enabling smaller platforms to compete on security credentials.
The EU AI Act imposes algorithmic transparency obligations on automated campaign curation and investor matching systems. European operators must document training data provenance and decision logic for regulatory inspection. Equity-based segments face the heaviest compliance burden, as risk-scoring algorithms trigger classification as high-risk AI systems. Platforms are responding by hiring technical-legal hybrid staff and segregating EU-specific infrastructure from global operations.
Donor behavior is fragmenting across cause-specific verticals rather than consolidating on generalist platforms. Medical emergency fundraising commands distinct loyalty patterns from creative project backing, with limited cross-category migration. Network effects concentrate within verticals rather than across them, rewarding specialized tooling over breadth. This fragmentation is most visible in the United States, where platform switching costs vary dramatically by end-use purpose.
Crowdfunding Market Segmentation
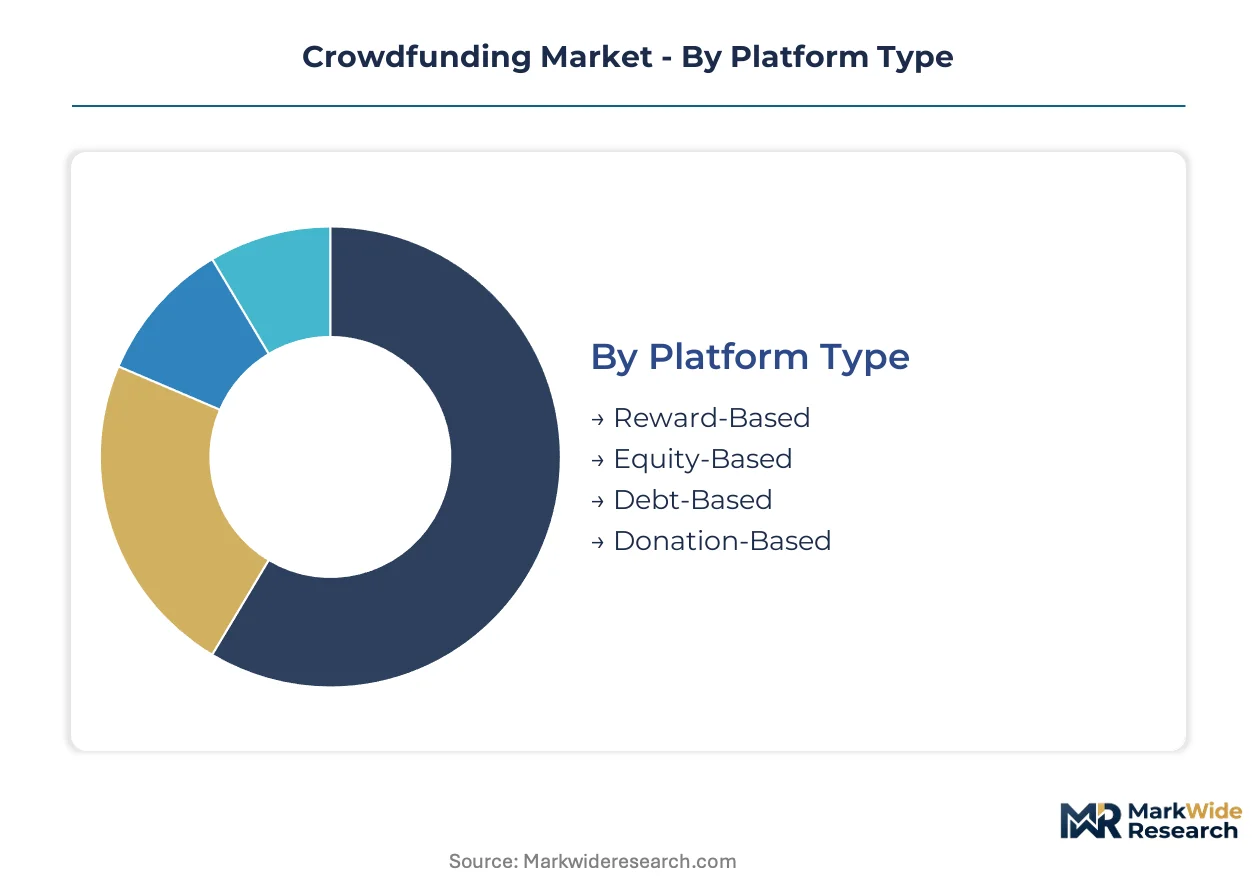
Platform architecture varies dramatically by capital structure and contributor profile. Each segmentation dimension reveals distinct compliance burdens, trust mechanisms, and revenue model constraints that shape competitive positioning.
Platform Type:
Standardization dominates reward-based infrastructure, while equity and debt platforms require bespoke regulatory modules that fragment development costs.
- Reward-Based:Platforms exchange tangible or experiential perks for contributions, with Kickstarter PBC encoding milestone disbursement protocols. Demand concentrates among creative project issuers in the United States, where repeat creator subscription tools reduce donor acquisition friction.
- Equity-Based:SEC Regulation Crowdfunding mandates disclosure schedules that embed directly into platform workflows. Technology startups in the United States anchor demand, with venture-backed issuers seeking retail capital pools outside traditional venture channels.
- Debt-Based:Peer-to-peer lending platforms intermediate credit through licensed non-bank frameworks. FCA authorization in the United Kingdom creates faster maturation than equity equivalents.
- Donation-Based:Personal cause fundraising operates through network effects rather than financial returns. GoFundMe dominates medical emergency verticals with specialized healthcare cost tooling.
Most installed capacity flows through Reward-Based platforms. Expansion is steepest in Equity-Based segments.
Campaign Type:
Volume concentration diverges sharply between recurring creative launches and one-time emergency fundraising.
- Creative Projects:Film, design, and technology hardware campaigns leverage repeat backer networks. Kickstarter PBC's membership tiers sustain creator lifetime value beyond single launches.
- Startups:Early-stage ventures access retail capital through streamlined SEC compliance. Wefunder anchors this segment with automated disclosure workflows.
- Social Causes:Environmental and advocacy campaigns depend on cause-specific donor loyalty with limited cross-category migration.
- Community Initiatives:Local development projects aggregate municipal-scale contributions through place-based network effects.
Creative Projects absorb the highest campaign frequency. Startups are climbing the fastest as regulatory automation reduces issuer friction.
Contribution Size:
Payment processing economics favor concentration at specific ticket thresholds that align with bank partnership risk appetites.
- Small Contributions:Sub-fifty-dollar donations aggregate through low-friction mobile interfaces. Social cause platforms in the United States optimize for this tier through streamlined checkout flows.
- Medium Contributions:Hundred-to-five-hundred-dollar range dominates reward-based creative backing. Kickstarter's project page design targets this behavioral segment.
- Large Contributions:Accredited investor minimums structure equity platform access. SEC exposure caps constrain annual retail participation at this threshold.
- Micro-Investments:Fractional equity stakes below traditional brokerage minimums attract first-time retail investors. Wefunder's automated compliance enables this segment.
Medium Contributions process the highest transaction velocity. Micro-Investments are gaining share fastest as fractional ownership infrastructure matures.
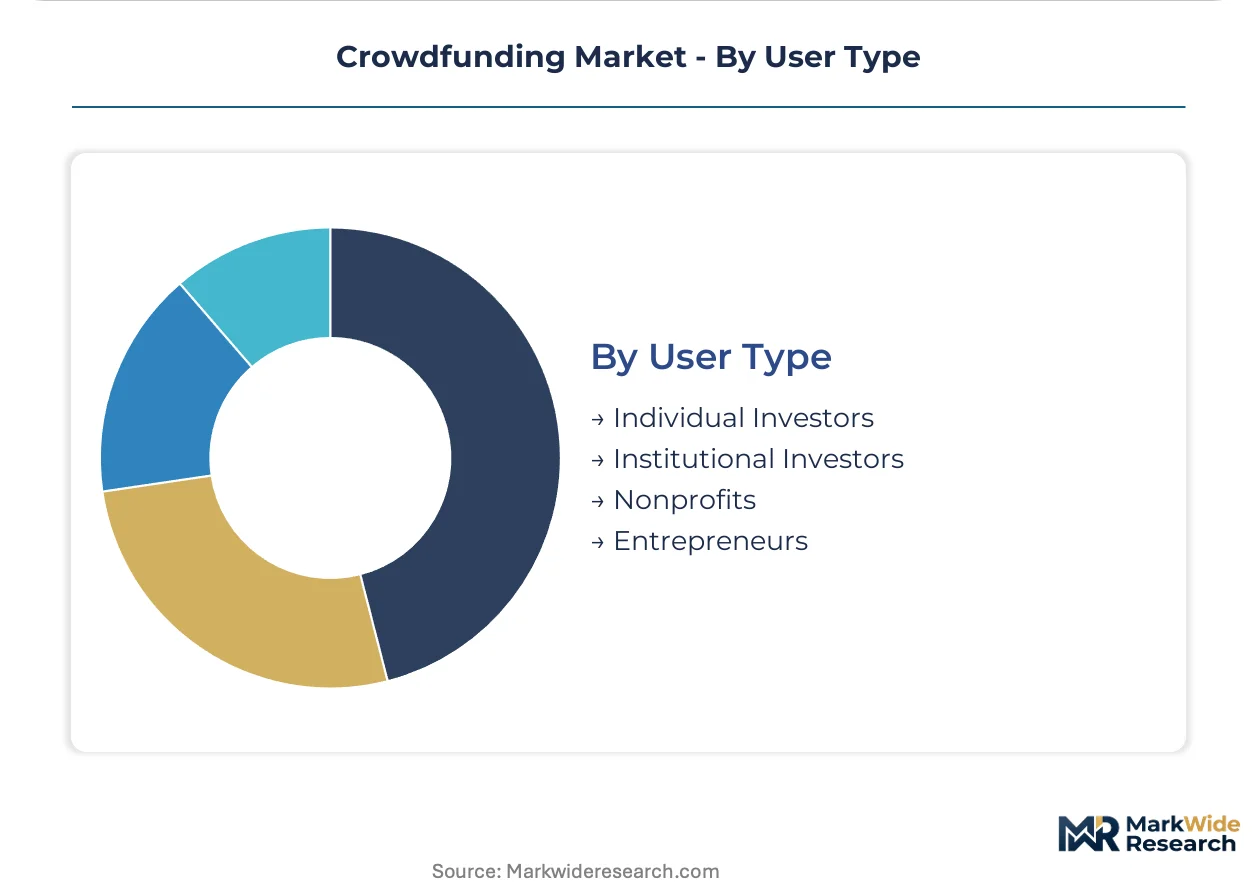
User Type:
Institutional capital deployment demands audit trails and custody solutions absent from retail-oriented platform stacks.
- Individual Investors:Retail participants access equity crowdfunding through SEC-mandated disclosure portals. Contribution caps limit annual exposure per investor.
- Institutional Investors:Venture funds and family offices seek early-stage exposure outside traditional venture channels. Equity platforms court this segment with enhanced due diligence tooling.
- Nonprofits:Tax-exempt entities leverage donation-based platforms for mission-aligned fundraising. GoFundMe's nonprofit verification protocols reduce fraud exposure.
- Entrepreneurs:Issuers select platforms based on regulatory automation and backer network quality. Technology startups demonstrate the fastest platform adoption rates.
Individual Investors represent the largest user base by count. Institutional Investors show the steepest expansion trajectory as platforms develop custody-grade infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands equity crowdfunding volume through SEC regulatory clarity, while European platforms absorb heavier compliance costs from algorithmic transparency mandates. This divergence shapes where capital formation concentrates and where operational margins compress.
United States
Technology startups in Silicon Valley and Austin drive platform adoption for early-stage capital access. SEC Regulation Crowdfunding caps retail investor exposure while mandating disclosure schedules that embed directly into platform workflows. New York and Boston clusters anchor equity issuance volume, with venture-backed issuers seeking retail capital pools outside traditional venture channels.
United Kingdom
Peer-to-peer lending platforms mature faster than equity equivalents under FCA authorization frameworks. London's fintech corridor concentrates licensed non-bank credit intermediation activity. Manchester and Edinburgh sub-regions develop specialized tooling for debt-based campaign verification, attracting institutional capital seeking yield outside traditional banking.
Germany
Creative project issuers in Berlin and Hamburg leverage reward-based platforms for film and design campaigns. BaFin oversight creates distinct compliance requirements for investment-based crowdfunding that fragment platform development costs. Munich's technology cluster experiments with blockchain-enabled escrow protocols for milestone disbursement automation.
France
Social cause fundraising concentrates in Paris and Lyon through donation-based verticals. AMF regulations govern equity participation with retail exposure frameworks that diverge from SEC approaches. Toulouse and Bordeaux develop specialized tooling for community initiative campaigns, leveraging place-based network effects for municipal-scale contributions.
Canada
Startups in Toronto and Vancouver access retail capital through provincial securities regulator harmonization. CSA National Instrument 45-110 creates startup crowdfunding exemptions that reduce issuer friction. Montreal's creative economy sustains reward-based platform activity for independent game development and documentary film production.
Crowdfunding Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with platform operators fragmenting by capital structure rather than consolidating horizontally. The vendor base separates into reward-based incumbents, equity compliance specialists, and donation-based network effect players. Three archetypes dominate: recurring membership platforms, regulatory automation providers, and vertical-specific community fundraisers. Competitive moves concentrate on compliance infrastructure acquisition and creator subscription tooling deployment.
Within the regulatory automation tier, Wefunder Inc. and SeedInvest Technology LLC exemplify platforms that streamline SEC disclosure workflows for equity issuers. Kickstarter PBC anchors the reward-based segment through creator subscription tools that sustain repeat project launches. GoFundMe Inc. occupies a distinct position in medical emergency fundraising, where specialized healthcare cost tooling generates donor retention advantages. These three operators represent how divergent capital structures produce non-overlapping competitive spheres.
| Leading Market Players |
|---|
| Kickstarter PBC |
| Indiegogo Inc. |
| GoFundMe Inc. |
| Wefunder Inc. |
| Crowdcube Limited |
| SeedInvest Technology LLC |
| Fundable LLC |
| StartEngine |
| Patreon |
| Others |
Cost & Logistics Intelligence
Technology startup issuers in the United States concentrate demand for equity crowdfunding platforms, anchoring a SaaS-tiered pricing model where subscription access tiers and per-transaction campaign fees coexist. This buyer concentration enables platform operators to extract premium pricing from high-velocity issuers while compressing margins for smaller, episodic campaign operators.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for platform service delivery. Three-tier pricing structure across premium, standard, and economy levels segments issuers by campaign complexity and compliance automation needs. Price differentiation hinges on SEC disclosure workflow depth and integrated escrow protocol sophistication. Pricing pressure stems from algorithmic transparency mandates under the EU AI Act that force redundant infrastructure investment. Small episodic campaign operators exhibit highest price sensitivity, while venture-backed technology startups accept premium tiers for regulatory automation speed.
Supply Chain Analysis
EU data localization requirements under GDPR are reshaping sourcing patterns for server infrastructure and payment processing partnerships. Platform operations draw from United States, Ireland, and Germany for compliant hosting capacity. Critical dependencies include licensed banking partnerships for payment settlement, identity verification APIs, and smart contract audit services. Single-source vulnerability concentrates in the narrow tier of financial institutions willing to underwrite crowdfunding transaction risk. Distribution runs through direct digital onboarding with minimal intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform operators can exploit geographic arbitrage between United States regulatory clarity and European compliance cost inflation, capturing margin expansion by segmenting infrastructure investments across jurisdictions with divergent AI Act implementation timelines.
For Market Incumbents: Anchor defensive positioning through vertical integration into regulatory automation tooling and creator subscription infrastructure. Acquire specialized compliance workflow providers before EU AI Act enforcement intensifies talent scarcity. Prioritize creator lifetime value capture over transactional campaign volume to reduce donor acquisition cost exposure. For New Entrants and Emerging Players: Begin with debt-based crowdfunding in United Kingdom sub-regions where FCA authorization frameworks mature faster than equity equivalents. Target Manchester and Edinburgh clusters for peer-to-peer lending specialization. Pursue white-label regulatory automation partnerships rather than building proprietary compliance stacks. For Investors and Strategic Acquirers: Fintech infrastructure consolidators represent the most active acquirer in this space, seeking platforms with embedded SEC compliance workflows and recurring revenue subscription bases. Five-to-ten year viability favors operators with segregated EU infrastructure and technical-legal hybrid staffing depth. Watch for algorithmic audit talent scarcity inflection as signal for platform margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Automation Acquisition | SEC disclosure workflow integration reduces issuer friction and captures B2B revenue streams. |
| Creator Subscription Tier Launch | Kickstarter PBC demonstrates recurring revenue potential that sustains repeat project velocity. |
| EU Infrastructure Segregation | GDPR-compliant server localization prevents cross-border transfer penalties and operational disruption. |
| Blockchain Escrow Protocol Deployment | Smart contract milestone disbursement differentiates security credentials against manual incumbent processes. |
| Debt-Based Licensing in United Kingdom | FCA authorization enables faster maturation than equity equivalents with institutional capital access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform operators, SEC compliance attorneys, venture capital allocators, and creator economy strategists alongside secondary validation through SEC filings, FCA authorization registers, EU regulatory databases, and platform transaction disclosures. Bottom-up campaign volume aggregation and top-down market sizing triangulation anchored value estimates.
Comparable historical periods anchored the projection horizon across platform type, campaign category, contribution size tier, and user archetype segmentation. CAGRs derived from regression analysis against technology startup formation rates, retail investor participation thresholds, and regulatory automation adoption curves. Forecast inputs incorporated EU AI Act implementation timelines and SEC disclosure schedule revision patterns.
Caveats apply where algorithmic transparency enforcement intensity or retail investor exposure cap adjustments could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization pace and banking partnership stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Micro VC Funds Market
Venture Capital
North America Venture Capital Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Business Incubator Market
Venture Capital
Impact Investing Market