
 Global Art Crowdfunding Market | 2026-2036
Global Art Crowdfunding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Art Crowdfunding Market Analysis
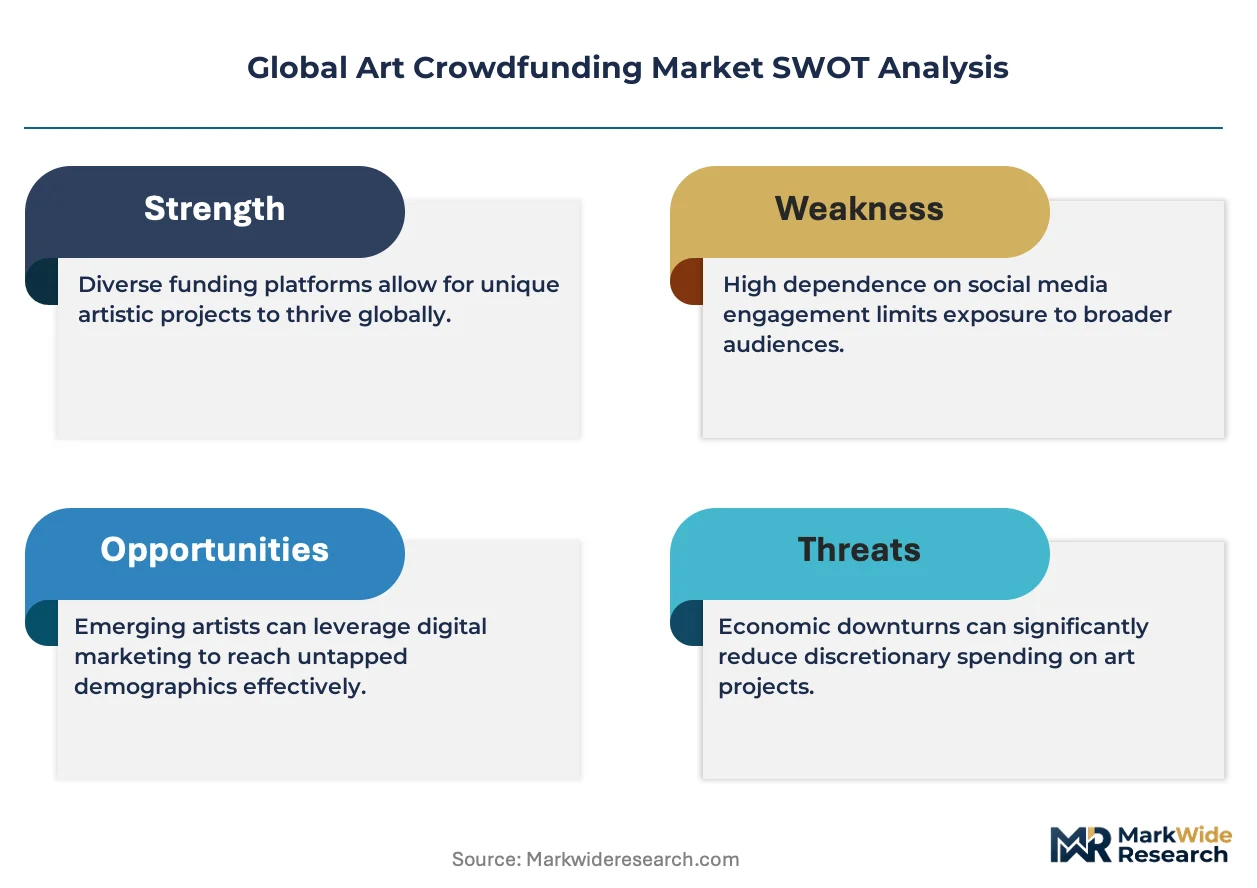
The EU AI Act is rebalancing compliance burdens for platforms hosting algorithmic curation and automated funding allocation. Kickstarter leverages its first-mover brand equity to sustain backer trust across diverse creative categories. Patreon dominates recurring revenue models for digital artists, while Nifty Gateway specializes in NFT-native crowdfunding mechanics that differentiate its value proposition from traditional reward structures.
Art crowdfunding denotes the practice of soliciting capital from dispersed individuals to finance creative works, exhibitions, or artistic ventures through internet-mediated platforms that aggregate micro-contributions into project-viable pools. Platforms typically charge commission rates between five and twelve percent of funds raised, with payment processing layered atop this fee structure. Reward-based platforms anchor current transaction volumes, while equity-based segments attract institutional attention as regulatory clarity around creative securities improves. Debt-based arrangements remain nascent but occupy a distinct niche for established artists with predictable revenue streams from prior commercial success.
The SEC in the United States governs equity crowdfunding disclosures under Regulation Crowdfunding, while the FCA in the United Kingdom enforces anti-money laundering protocols for platforms handling artist payments. GDPR compliance across Europe shapes how platforms collect and retain backer personal data, directly influencing onboarding friction and conversion rates. Stakeholders must monitor how securities regulators classify fractional art ownership tokens, as this determination will reshape platform architecture and geographic market access for cross-border campaigns.
Market Dynamics
Blockchain-based provenance verification is compressing fraud risk premiums and reshaping backer confidence thresholds across reward-based and equity-based funding models. This infrastructure shift is redistributing trust mechanisms from platform intermediaries to cryptographic verification protocols.
Growth Catalysts
- Regulation Crowdfunding:The SEC framework governing equity disclosures has clarified securities classification for fractional art ownership, expanding institutional participation in creative securities.
- Digital payment infrastructure:Upgraded settlement rails in South Korea and the United Kingdom are reducing transaction friction for micro-contributions below fifty dollars.
- NFT-native mechanics:Smart contract automation is enabling programmable royalty streams that persist through secondary market transfers, attracting digital-native creator cohorts.
Market Restraints
- GDPR compliance costs:European data retention protocols are inflating platform onboarding friction and elevating customer acquisition expenditures.
- Payment processor concentration:Dependency on a narrow set of financial intermediaries creates single-point vulnerability for campaign liquidity.
- Fraud verification latency:Manual provenance checks for physical artworks impose campaign launch delays averaging several weeks.
Strategic Opportunities
- Debt-based arrangements:Predictable revenue streams from prior commercial success enable structured lending products for established artists in the United States.
- EU AI Act alignment:Early compliance with algorithmic curation transparency requirements positions platforms for preferential regulatory treatment.
- Recurring revenue models:Subscription architectures for digital artists remain underpenetrated relative to one-time campaign structures.
Industry Challenges
- Smart contract auditing:Shortage of qualified blockchain security reviewers is delaying platform deployment timelines.
- Cross-border tax harmonization:Conflicting withholding obligations between the United States and United Kingdom complicate backer reward fulfillment.
- Creator onboarding education:Gaps in financial literacy among emerging artists elevate campaign failure rates and platform reputational risk.
Report Scope
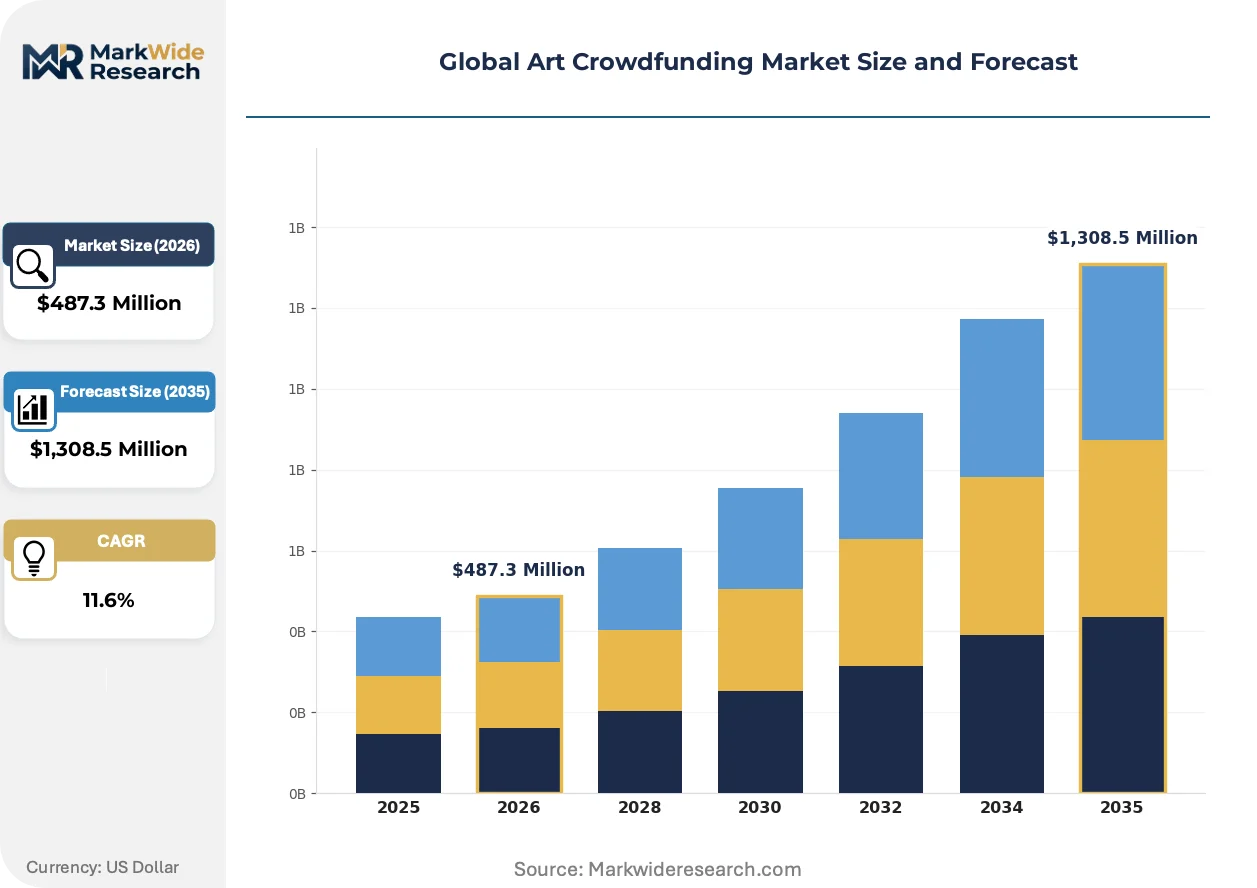
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Art Crowdfunding Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Donation-Based, Reward-Based, Equity-Based, Debt-Based Campaign Purpose: Art Projects, Creative Startups, Community Projects, Social Initiatives Funding Size: Small-Scale, Medium-Scale, Large-Scale, Mega Projects Artist Type: Emerging Artists, Established Artists, Collectives, Art Organizations |
| Companies Covered | Indiegogo, KnownOrigin, Kickstarter, Barnebys, Async Art, Patreon, Nifty Gateway, PledgeBox, Artsy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Art Crowdfunding Market Emerging Trajectories
Distributed ledger architectures are reconfiguring how value flows between creators and backers, with three distinct vectors reshaping platform economics and user behavior.
Tokenized provenance systems are decentralizing ownership verification by embedding cryptographic certificates directly into digital and physical artworks. Galleries and institutional collectors in South Korea are adopting these standards fastest, compressing due diligence cycles from weeks to minutes. This shift is decentralizing trust away from centralized appraisal authorities toward algorithmic consensus mechanisms.
The EU AI Act is mandating disclosure thresholds for algorithmic curation systems that rank or promote campaigns to prospective backers. Platforms operating across European jurisdictions must now document training data provenance and decision logic for funding allocation algorithms. Early movers in the United Kingdom are restructuring recommendation engines to satisfy these requirements ahead of enforcement deadlines.
Backer cohorts are fragmenting into micro-communities organized around aesthetic subcultures rather than geographic proximity. Discord servers and niche social channels are displacing platform-native discovery as the primary campaign amplification vector. This pattern is most visible in digital art verticals where creator-audience relationships predate platform enrollment.
Global Art Crowdfunding Market Segmentation
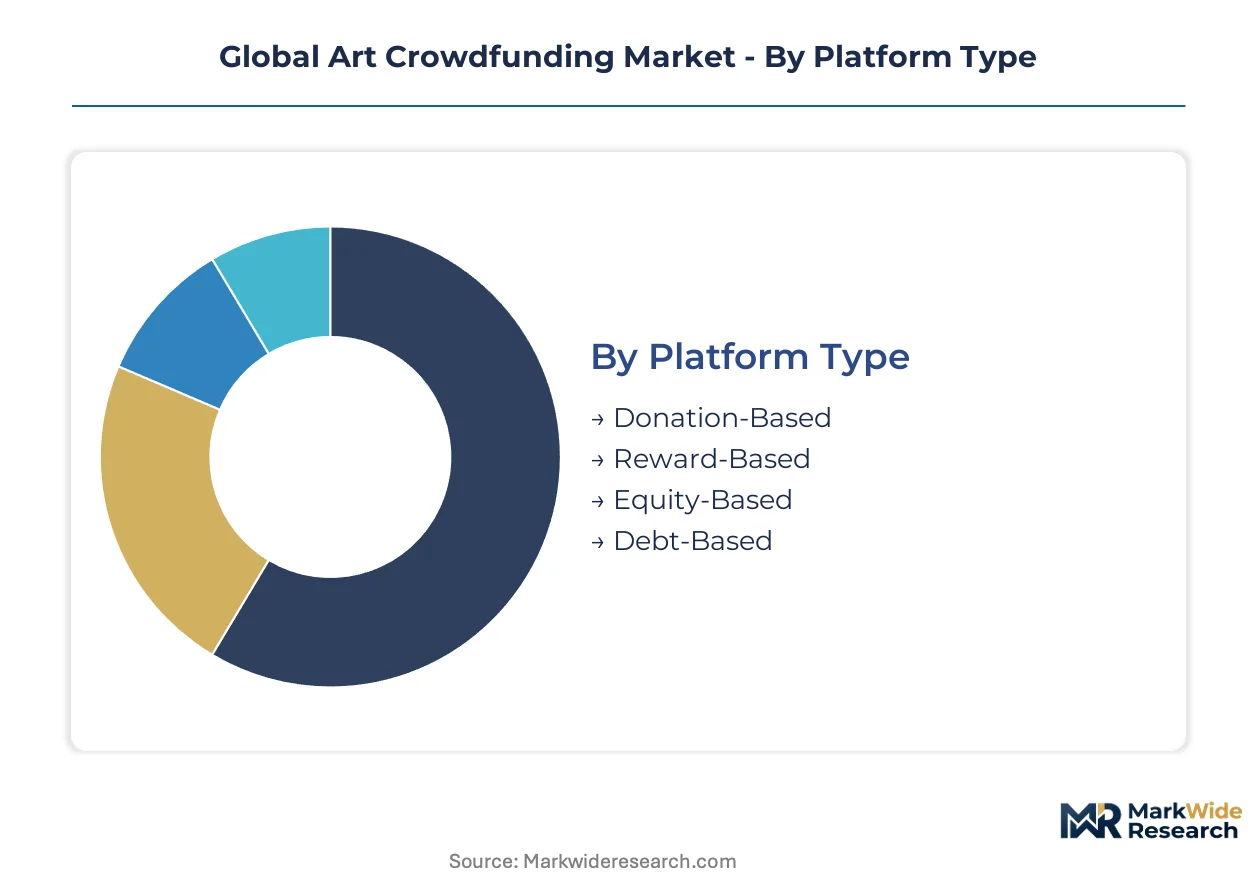
Art crowdfunding platforms serve heterogeneous creator and backer cohorts with divergent risk appetites, funding horizons, and governance expectations. Segmentation reveals how platform architecture, campaign design, and regulatory compliance requirements vary across funding mechanisms and artist maturity levels.
Platform Type:
Supply concentrates in reward-based infrastructure where commission structures and backer protections have achieved standardization across the United States, United Kingdom, and South Korea.
- Reward-Based:Dominant transaction architecture where backers receive non-financial returns including limited-edition works, exhibition access, or creator experiences. Demand clusters in digital art verticals across the United States where backer protections under consumer protection statutes have matured. Commission rates typically range between five and twelve percent.
- Equity-Based:Securities-compliant structures governed by SEC Regulation Crowdfunding in the United States and FCA disclosure protocols in the United Kingdom. Institutional participation is expanding as fractional art ownership classification clarifies across jurisdictions.
- Donation-Based:Philanthropic funding without financial or material returns, concentrated in community-anchored public art initiatives.
- Debt-Based:Structured lending products for creators with documented revenue streams, occupying a narrow niche in the United States where commercial track records enable credit underwriting.
Reward-based platforms absorb the bulk of installed capacity; equity-based mechanisms are expanding most quickly as regulatory frameworks mature.
Campaign Purpose:
Cost tier differentiation separates speculative creative ventures from revenue-generating commercial projects with predictable cash conversion timelines.
- Art Projects:Discrete creative works including exhibitions, installations, and performance pieces. Demand concentrates in South Korea where institutional collectors leverage blockchain provenance systems to compress due diligence cycles.
- Creative Startups:Business entities with scalable revenue models including design studios and production houses. The United Kingdom shows elevated backer appetite where SEIS tax incentives reduce risk-adjusted return thresholds.
- Community Projects:Place-based cultural infrastructure with localized benefit distribution, prevalent in urban regeneration corridors.
- Social Initiatives:Art interventions targeting defined social outcomes including therapeutic programs and educational access schemes.
Art projects absorb the bulk of installed capacity; creative startups are climbing the fastest as equity crowdfunding infrastructure professionalizes.
Funding Size:
Volume distribution follows a power-law concentration where micro-campaigns below ten thousand dollars generate transaction velocity but large-scale projects drive absolute platform revenue.
- Small-Scale:Campaigns typically below ten thousand dollars with minimal compliance overhead and rapid deployment timelines. The United States dominates absolute transaction count where digital payment infrastructure minimizes friction for sub-fifty-dollar contributions.
- Large-Scale:Campaigns exceeding one hundred thousand dollars requiring structured governance, milestone-based fund release, and enhanced disclosure protocols. Institutional co-investment structures are emerging in the United Kingdom where FCA oversight has standardized investor protection frameworks.
- Medium-Scale:Mid-tier campaigns with hybrid amateur-professional backer bases and moderate documentation requirements.
- Mega Projects:Multi-million-dollar initiatives with complex syndication across platforms and jurisdictions, rare but platform-defining when successful.
Small-scale campaigns absorb the bulk of installed capacity; large-scale structures are gaining share fastest as institutional capital enters creative securities markets.
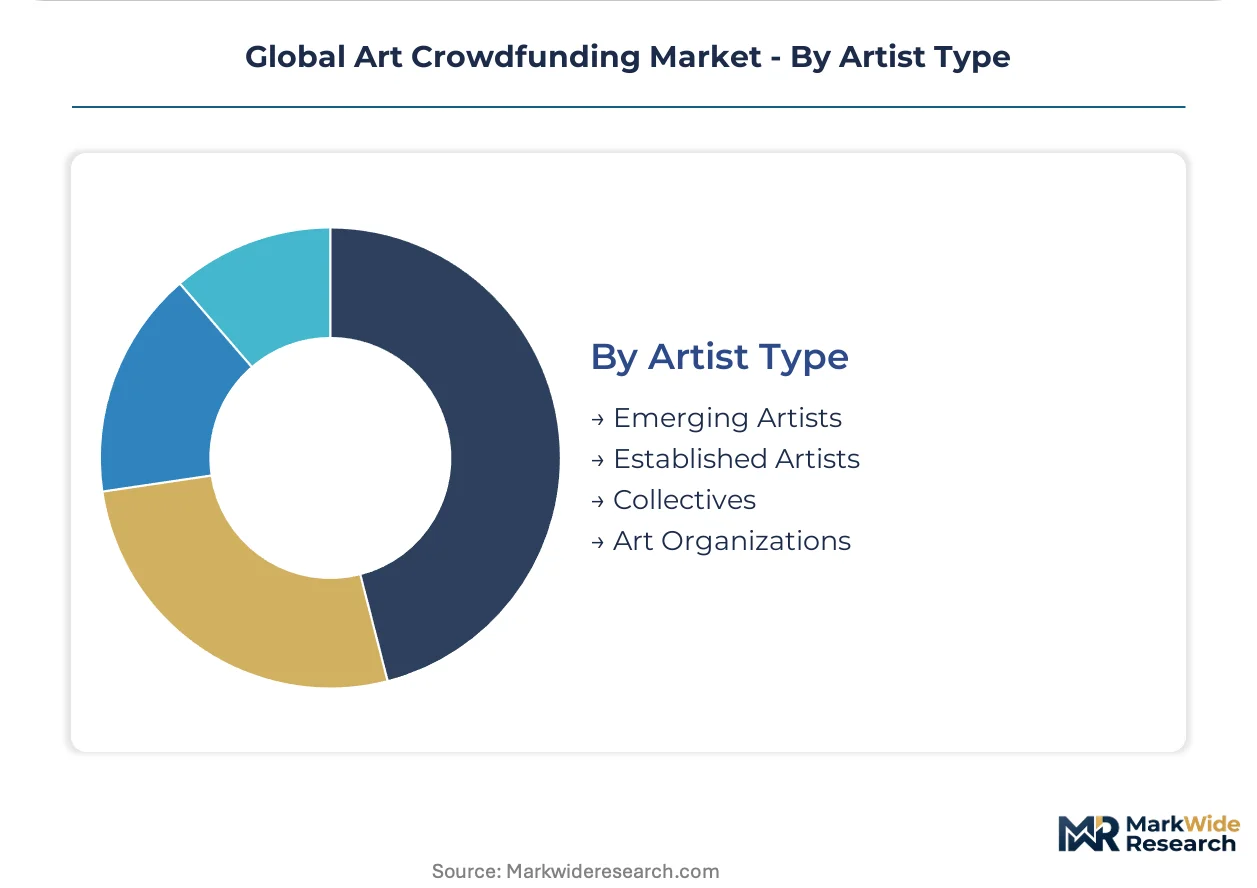
Artist Type:
Customer type segmentation separates creators with established audience relationships from those dependent on platform-native discovery algorithms.
- Emerging Artists:Creators without prior commercial track records or verified collector bases. Demand concentrates in digital-native cohorts leveraging Discord and niche social channels for pre-platform audience cultivation, particularly visible in South Korean digital art markets.
- Established Artists:Creators with documented sales histories, institutional representation, or prior crowdfunding success. The United States shows highest concentration where prior commercial success unlocks debt-based financing alternatives.
- Collectives:Multi-creator entities with distributed governance and shared revenue allocation protocols.
- Art Organizations:Non-profit and commercial entities with formal governance structures including museums, galleries, and production companies.
Emerging artists absorb the bulk of installed capacity; established artists are expanding most quickly as provenance verification infrastructure reduces backer due diligence burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backer capital concentrates in jurisdictions where creator-economy infrastructure and regulatory clarity have matured in parallel. The United States, United Kingdom, South Korea, Germany, and Australia generate the bulk of platform transaction velocity through distinct funding mechanism preferences.
United States
Reward-based platforms absorb the highest transaction volumes as SEC Regulation Crowdfunding clarifies equity disclosure requirements for fractional art ownership. The SEC framework has expanded institutional participation in creative securities. Los Angeles and New York anchor platform headquarters concentration while Miami's digital art collector base accelerates blockchain provenance adoption.
United Kingdom
FCA anti-money laundering protocols shape payment processing architecture for artist disbursements. SEIS tax incentives reduce risk-adjusted return thresholds for creative startup backers. London dominates platform operations while Manchester and Bristol clusters emerge around niche digital art curation.
South Korea
Upgraded digital payment settlement rails minimize friction for micro-contributions below fifty dollars. MFDS-equivalent cultural ministry guidelines standardize platform disclosure for art investment products. Seoul anchors institutional collector adoption of tokenized provenance systems, compressing due diligence cycles from weeks to minutes.
Germany
GDPR compliance costs elevate customer acquisition expenditures while shaping data retention protocols for backer onboarding. EU AI Act transparency requirements for algorithmic curation are restructuring recommendation engines ahead of enforcement deadlines. Berlin and Munich clusters concentrate platform technical operations and creator community management.
Australia
ASIC-equivalent securities guidance clarifies crowdfunding disclosure thresholds for equity-based art ventures. TGA-aligned consumer protection frameworks govern reward fulfillment obligations. Sydney and Melbourne generate concentrated backer demand for community-anchored public art initiatives with localized benefit distribution.
Global Art Crowdfunding Market Vendor Landscape
United States platforms anchor the reward-based and equity-based tiers; United Kingdom and South Korean specialists hold positions in NFT-native mechanics and recurring revenue models. Market structure fragments across funding mechanism specialization rather than consolidating around full-service provision. Three archetypes dominate: first-mover brand equity holders, recurring revenue infrastructure builders, and blockchain-native mechanics innovators. Geographic expansion and algorithmic curation transparency investments constitute the dominant competitive moves.
Within the first-mover tier, Kickstarter exemplifies brand-anchored trust across diverse creative categories. Patreon occupies the recurring revenue infrastructure position for digital artist subscription models. Nifty Gateway represents the blockchain-native archetype with smart contract automation for programmable royalty streams. These three entities collectively illustrate how platform differentiation fragments across reward structure innovation rather than geographic coverage alone.
| Leading Market Players |
|---|
| Indiegogo |
| KnownOrigin |
| Kickstarter |
| Barnebys |
| Async Art |
| Patreon |
| Nifty Gateway |
| PledgeBox |
| Artsy |
| Others |
Supply Flow & Price Mechanics
Backer preference for transparent fee structures and blockchain-verified provenance is forcing platforms to absorb compliance costs rather than pass them through, compressing margins and reshaping supplier relationships toward specialized verification providers.
Pricing Analysis
Volume concentration in small-scale campaigns below ten thousand dollars generates transaction velocity but thin margins, while large-scale projects above one hundred thousand dollars capture premium pricing through milestone-based governance and enhanced disclosure. Commission rates stratify across platform archetypes: reward-based operators charge five to twelve percent, equity-based platforms layer securities compliance fees atop this base, and NFT-native mechanics command premium pricing for smart contract automation. Pricing pressure stems from payment processor concentration and GDPR compliance cost inflation in European markets. Emerging artists show highest price sensitivity to platform fees, while institutional backers in the United Kingdom and South Korea prioritize provenance verification over marginal cost differences.
Supply Chain Analysis
Domestic-content mandates for data residency under GDPR and the EU AI Act are reshaping platform sourcing toward European-based cloud infrastructure and algorithmic audit providers. Technical operations concentrate in the United States, the United Kingdom, and Germany, with blockchain verification services drawing from specialized providers in South Korea and Singapore. Critical dependencies include payment processing rails, cryptographic security modules, and smart contract auditing capacity. Single-source vulnerability in qualified blockchain security reviewers delays platform deployment timelines. Distribution runs through platform-native discovery algorithms supplemented by Discord and niche social channel amplification for pre-cultivated backer communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act is erecting a compliance moat that favors platforms with early algorithmic transparency investments, raising capital requirements for new entrants and consolidating advantage among regulated incumbents.
For Market Incumbents: To counter emerging NFT-native platforms with programmable royalty mechanics, incumbents should acquire smart contract auditing capabilities or partner with established blockchain security firms, while accelerating EU AI Act alignment to secure preferential regulatory treatment ahead of enforcement deadlines. For New Entrants and Emerging Players: Launch via debt-based arrangements for established artists in the United States, where predictable revenue streams from prior commercial success enable credit underwriting with lower customer acquisition costs than saturated reward-based segments. Target emerging artists in South Korea leveraging Discord-native audience cultivation before platform enrollment. For Investors and Strategic Acquirers: The window for entry favors platforms with compliant algorithmic curation infrastructure and recurring revenue architecture for digital artists. Long-term viability hinges on regulatory adaptability across SEC, FCA, and EU AI Act jurisdictions. Monitor SEC classification determinations for fractional art ownership tokens as the critical inflection signal for equity-based segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Reduces fraud verification latency from weeks to minutes for South Korean institutional collectors. |
| EU AI Act Compliance Investment | Positions platforms for preferential treatment under algorithmic transparency mandates in Germany. |
| Debt-Based Product Launch | Captures established artist segment in the United States with documented commercial track records. |
| Recurring Revenue Architecture | Addresses underpenetrated subscription models for digital artists beyond one-time campaign structures. |
| Cross-Border Tax Harmonization | Resolves conflicting withholding obligations between the United States and United Kingdom for backer fulfillment. |
Methodological Framework
SEC filings, FCA regulatory guidance documents, and EU AI Act implementation drafts formed the secondary backbone, supplemented by customs data on cross-border art transactions and platform commission disclosures. Primary interviews with crowdfunding platform executives, blockchain security auditors, and regulatory compliance officers anchored demand-side validation. Creator-economy analysts and institutional art collectors provided supply-side perspectives. Bottom-up and top-down triangulation reconciled transaction volume estimates with regulatory filing aggregates.
Bottom-up modeling projected platform transaction flows across reward-based, equity-based, and NFT-native funding mechanisms, while top-down analysis anchored aggregate market sizing to securities regulator disclosure volumes. Segmentation dimensions included platform type, campaign purpose, funding size tier, and artist maturity level. CAGRs derived from historical transaction velocity patterns and regulatory clarity timelines. Forecast inputs incorporated payment infrastructure upgrade schedules in South Korea and the United Kingdom, plus smart contract adoption curves for provenance verification.
Regulatory reclassification of fractional art ownership, enforcement delays for EU AI Act algorithmic transparency requirements, and payment processor consolidation are the dominant revision risks to the projection envelope. Forecasts reflect assumptions regarding regulatory stability and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Micro VC Funds Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Business Incubator Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Impact Investing Market
Venture Capital
United States Venture Capital Market
Venture Capital
North America Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Angel Funds Market
Venture Capital
Crowdfunding Market